
 Expanded Polypropylene (EPP) Foam Market | 2026-2036
Expanded Polypropylene (EPP) Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Polypropylene (EPP) Foam Market Analysis
Automotive interiors is consolidating as the dominant application vertical for EPP foam as OEMs pursue weight reduction targets across electric and internal combustion platforms. BASF SE leverages its integrated polypropylene supply chain to anchor European automotive programs with consistent bead foam grades. JSP Corporation sustains technology leadership through proprietary expansion processes that yield high-energy absorption characteristics for safety-critical components. Hanwha Advanced Materials competes aggressively in Asia-Pacific markets with dedicated EPP compounding facilities serving tier-one seating suppliers.
Expanded polypropylene foam consists of closed-cell, bead-shaped particles fused into rigid yet lightweight structures with densities typically ranging from 20 to 200 grams per liter, manufactured through steam-chest molding of pre-expanded beads. Its primary commercial purpose centers on impact energy management, thermal insulation, and repetitive shock absorption across transport and protective packaging systems. Molded blocks command the largest volume share within product type segmentation due to their versatility in automotive bumper and seat core fabrication. Packaging solutions represents the fastest-growing application segment as e-commerce fulfillment networks adopt returnable protective containers to replace single-use alternatives.
EPA vehicle emission standards in the United States and REACH chemical safety protocols in Europe directly shape EPP formulation requirements by restricting additive chemistries and mandating recyclability disclosures. China's GB standards for automotive interior flammability and Japan's METI energy efficiency guidelines for transport equipment create parallel compliance layers that manufacturers must navigate simultaneously. Stakeholders should monitor evolving extended producer responsibility frameworks and bio-based polypropylene feedstock certifications as these will determine material qualification pathways and premium positioning opportunities.
Market Dynamics
Automotive lightweighting mandates and e-commerce packaging circularity requirements are compressing EPP formulation cycles while pulling bead foam specifications toward higher recycled content thresholds.
Growth Catalysts
- EPA vehicle emission standards:Corporate Average Fuel Economy targets force OEMs to substitute EPP for heavier polyurethane and metal components in bumper systems and seat structures.
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks for transport packaging accelerate returnable container adoption across fulfillment networks.
- Bead foam molding automation:Steam-chest process improvements reduce cycle times and scrap rates, enabling tier-one suppliers to scale production for electric vehicle platforms.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings compress molding compound margins and destabilize long-term supply contracts.
- REACH chemical disclosure requirements:Additive transparency mandates increase compliance documentation burdens and disqualify legacy flame retardant packages.
- Expanded polystyrene substitution:Lower-cost EPS retains share in non-automotive protective packaging despite inferior durability and recyclability profiles.
Strategic Opportunities
- Bio-based polypropylene certification:ISCC PLUS and similar mass-balance schemes open premium positioning for foam grades with verified renewable feedstock content.
- Cold chain pharmaceutical packaging:Temperature-sensitive vaccine and biologics distribution creates demand for reusable EPP insulated shippers with validated thermal performance.
- India automotive component manufacturing:PLI scheme incentives for advanced chemistry cell and EV component production attract EPP molding investments near Chennai and Pune clusters.
Industry Challenges
- Steam-chest mold engineering talent scarcity:Specialized process optimization expertise concentrates among aging workforces in Germany and Japan, constraining capacity expansion.
- Multi-standard flammability testing backlog:Simultaneous GB, FMVSS, and UL certification requirements delay automotive program qualification timelines by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Polypropylene (EPP) Foam Market |
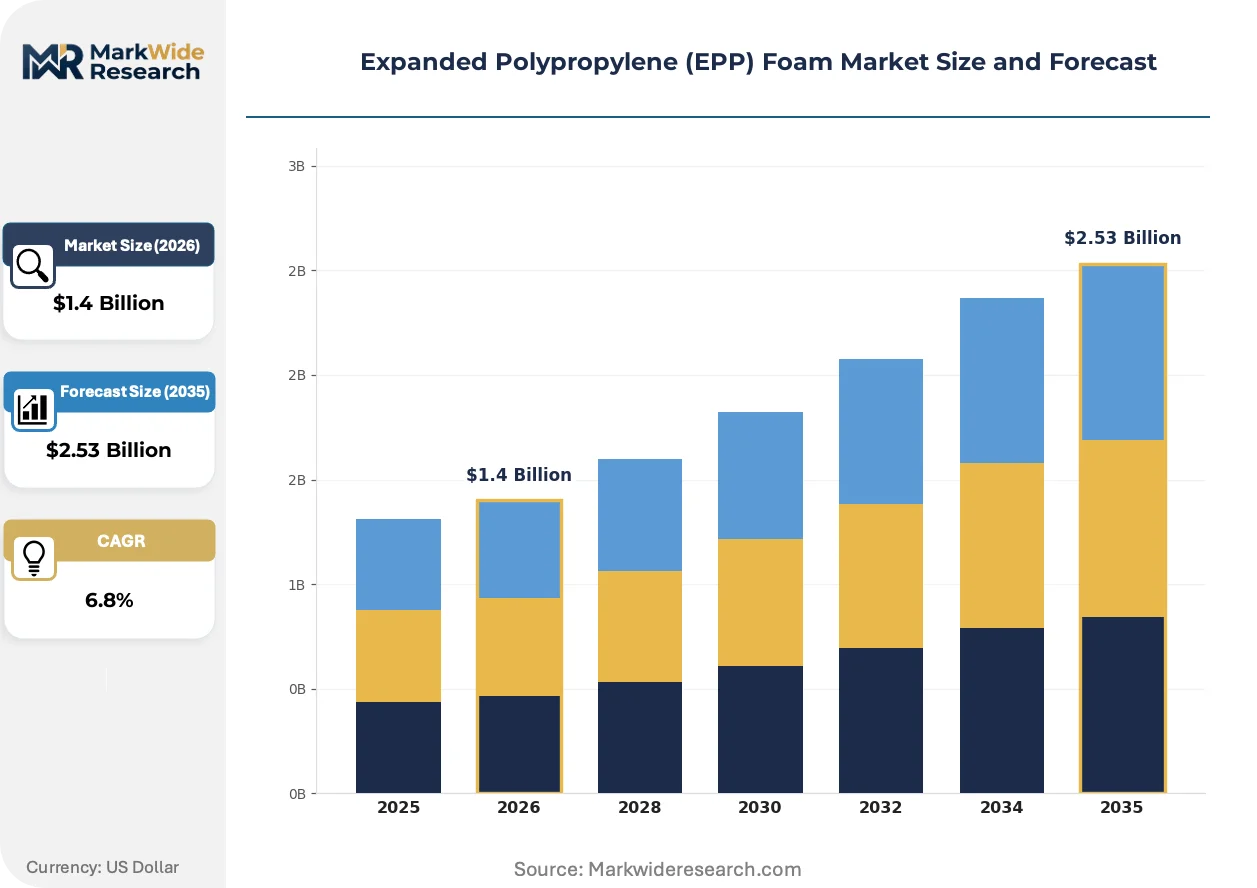
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Rolls, Blocks, Molds Application: Automobile Interiors, Packaging Solutions, Thermal Insulation, Sports Equipment End User: Aerospace, Consumer Goods, Construction, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Hanwha Advanced Materials, Sonoco Products Company, JSP Corporation, DS Smith, Wuxi Hi-Tech Environmental Material, BASF SE, Knauf Industries, Furukawa Electric, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Polypropylene (EPP) Foam Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are converging to reshape how EPP compounds are formulated, certified, and deployed across transport and protective applications.
High-expansion ratio bead technologies are absorbing impact energy more efficiently in thinner wall sections. Tier-one seating suppliers in Germany and the United States are qualifying these grades for side-impact bolster applications. The technology is absorbing market share from expanded polyethylene in safety-critical automotive components where weight minimization conflicts with crash performance targets.
REACH substance of very high concern listings are forcing reformulation of conventional flame retardant packages. ECHA restrictions on halogenated additives compounders to validate alternative chemistries through thermal runaway testing protocols. Automotive interior programs in France and Italy face the tightest compliance windows as OEMs synchronize material approvals with 2025 model year changeovers.
Returnable packaging pooling models are displacing single-use protective containers in electronics fulfillment. Amazon and regional logistics operators in the Netherlands and California are deploying tracking-enabled EPP containers through closed-loop networks. Consumer electronics assembly in Shenzhen and Guadalajara represents the highest-volume adoption nodes for these reusable systems.
Expanded Polypropylene (EPP) Foam Market Segmentation
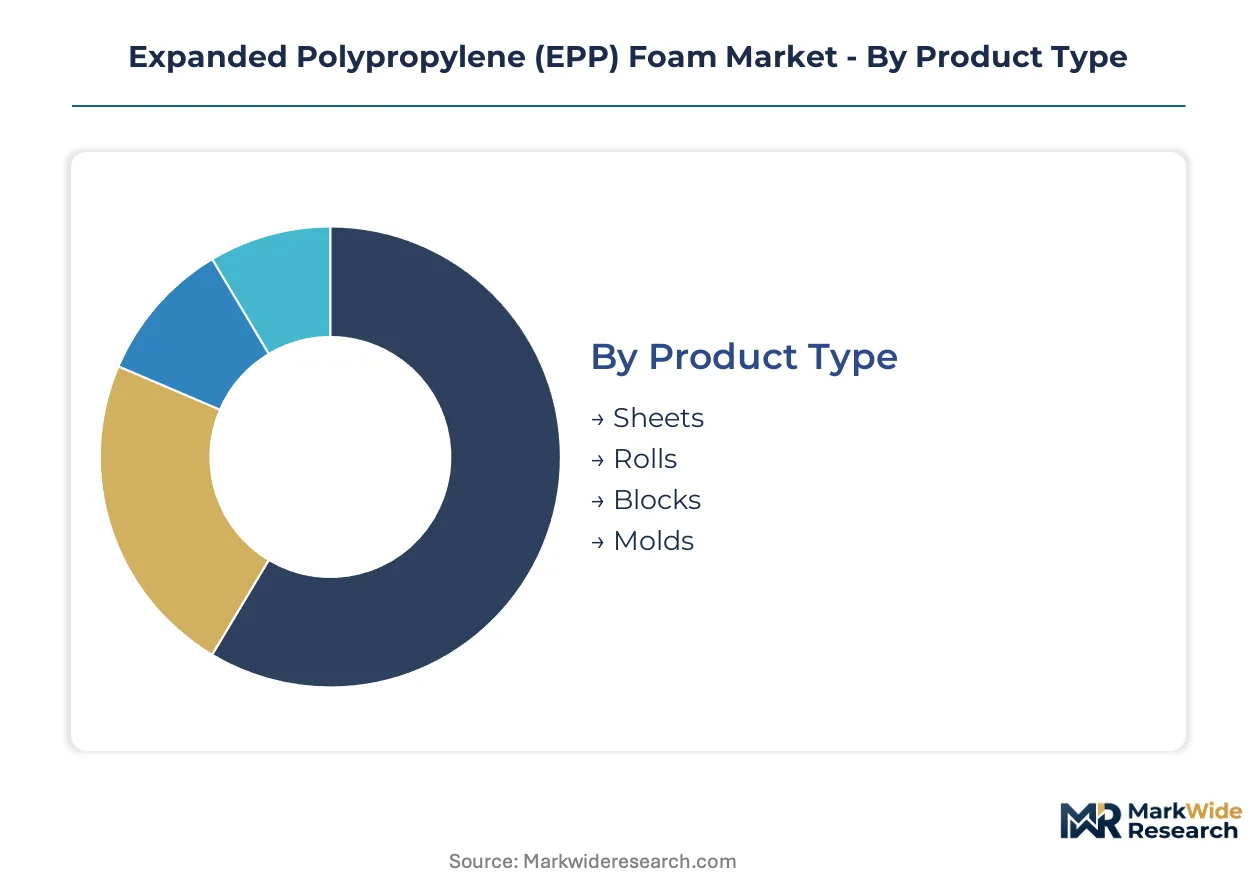
EPP foam segmentation reflects divergent capital requirements across molding technologies and end-use specifications. Understanding these structural differences clarifies where margin pools concentrate and which segments attract new processing investments.
Product Type:
Steam-chest molding infrastructure demands the heaviest upfront capital outlay, with automated bead expansion lines and precision mold tooling representing multi-million dollar commitments before first commercial production.
- Blocks:Molded block production requires high-pressure steam-chest systems with automated bead feeding and cooling cycles. Automotive bumper core programs in Germany and the United States consume the majority of block volume as OEMs qualify EPP for energy absorption modules under NHTSA and KBA safety protocols.
- Molds:Custom mold fabrication integrates CAD-designed cavity geometries with conformal cooling channels for complex automotive seating and interior components. Tier-one suppliers near Stuttgart and Detroit are expanding molded part capacity to serve electric vehicle platform launches.
- Sheets:Continuous extrusion lines produce uniform sheet stock for thermal insulation and protective interlayer applications.
- Rolls:Rolled EPP serves packaging and construction markets requiring flexible deployment formats.
Blocks absorb the bulk of installed capacity; molds are expanding most quickly.
Application:
Application segmentation tracks how formulation specifications diverge across performance requirements and regulatory exposure, with automotive programs commanding premium grades and documentation standards.
- Automobile Interiors:Seating structures, door panels, and instrument substrates utilize medium-density EPP with tailored compression set resistance. OEMs in the United States and Germany specify these grades to meet FMVSS 302 flammability and REACH substance disclosure mandates simultaneously.
- Packaging Solutions:Returnable protective containers for consumer electronics and pharmaceutical cold chain employ high-recycled-content formulations. E-commerce fulfillment networks in California and the Netherlands are deploying tracking-enabled EPP shippers through closed-loop pooling systems.
- Thermal Insulation:Building envelope and HVAC applications exploit EPP's lambda values and moisture resistance.
- Sports Equipment:Helmets and protective gear utilize high-energy-absorption bead grades.
Automobile interiors command the dominant revenue share; packaging solutions are climbing the fastest as circular economy mandates tighten.
End User:
End user concentration varies sharply by technical qualification barriers, with aerospace and electronics demanding certified traceability that consumer goods segments rarely require.
- Electronics:Smartphone, laptop, and server manufacturers specify anti-static EPP grades with controlled outgassing profiles for cleanroom assembly environments. Shenzhen and Guadalajara assembly hubs drive volume for precision-molded protective trays and returnable dunnage systems.
- Aerospace:Cabin interior components and cargo systems utilize FAA-compliant flame-retardant formulations with full batch documentation. Seating manufacturers in Seattle and Toulouse qualify EPP for seat bottom cushions and life raft containers under strict burn-through resistance protocols.
- Consumer Goods:Furniture, toys, and recreational products employ standard-density grades with basic performance certification.
- Construction:Foundation insulation and geotechnical fill applications utilize bulk block and bead formats.
Electronics consumes the largest absolute volume; aerospace is gaining share fastest through cabin retrofit programs.
Distribution Channel:
Channel structure reflects customer scale and specification complexity, with direct relationships dominating automotive programs and fragmented routes serving smaller accounts.
- Direct Sales:Long-term supply agreements connect EPP compounders directly to automotive OEMs and tier-one seating suppliers. BASF and JSP maintain dedicated account teams in Wolfsburg, Munich, and Detroit to coordinate material qualification and production scheduling.
- Distributors:Regional stock-and-serve operations hold inventory for construction, consumer goods, and smaller electronics accounts. Distributor networks in Texas and Bavaria provide technical support and just-in-time delivery for mid-volume processors lacking direct mill relationships.
- Online Retail:E-commerce platforms serve hobbyist, prototyping, and small-batch manufacturing demand.
- Specialty Stores:Niche outlets cater to sports equipment and recreational product manufacturers.
Direct sales channel captures the majority of value; distributors are expanding most quickly through regional hub investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and India's automotive corridors are concentrating EPP molding investments near OEM assembly plants. Germany's chemical parks anchor European supply through integrated polypropylene feedstock access. Mexico's border manufacturing clusters attract North American automotive foam programs seeking tariff-advantaged production.
United States
EPA vehicle emission standards and NHTSA safety protocols drive EPP substitution in bumper cores and seating structures. The Inflation Reduction Act's domestic content incentives accelerate reshoring of automotive component molding. Detroit-Windsor corridor suppliers are expanding steam-chest capacity to serve electric vehicle platform launches from Michigan assembly plants.
Germany
REACH chemical disclosure mandates and KBA crash safety certifications shape formulation requirements for automotive interior programs. The EU Green Deal's extended producer responsibility frameworks tighten recyclability documentation for transport packaging. Stuttgart and Wolfsburg industrial zones concentrate tier-one seating supplier operations serving premium OEM platforms.
China
GB standards for automotive interior flammability and MIIT new energy vehicle production quotas pull EPP demand toward electric platforms. Dual carbon goals accelerate scrutiny of polypropylene feedstock carbon intensity in Yangtze River Delta manufacturing zones. Shanghai and Guangdong molding clusters are qualifying high-recycled-content grades for domestic EV seating programs.
India
PLI scheme incentives for advanced chemistry cell and EV component production attract EPP molding investments near automotive clusters. BIS certification requirements for automotive materials create qualification barriers for imported compounds. Chennai and Pune manufacturing corridors are emerging as dedicated EPP fabrication hubs for domestic and export seating supply.
Japan
METI energy efficiency guidelines for transport equipment and JIS quality standards shape domestic EPP specification requirements. Aging steam-chest engineering expertise concentrates in Nagoya and Osaka industrial zones. Domestic compounders are prioritizing high-expansion ratio bead technologies for next-generation automotive safety components.
Expanded Polypropylene (EPP) Foam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding automotive qualification pathways while regional fabricators capture packaging volume. The vendor base organizes around three strategic archetypes: polypropylene producers with captive foam operations, independent bead foam specialists, and diversified packaging converters extending into protective formats. Capacity expansion and bio-based feedstock certification represent the dominant competitive moves as qualification windows tighten.
Among integrated chemical producers, BASF SE anchors European automotive programs through polypropylene supply chain control. JSP Corporation and Hanwha Advanced Materials exemplify the specialist archetype, with the former representing Japanese process technology leadership and the latter occupying a position in Asia-Pacific regional supply. These three entities collectively illustrate how geographic feedstock access and OEM relationship depth determine competitive positioning.
| Leading Market Players |
|---|
| Hanwha Advanced Materials |
| Sonoco Products Company |
| JSP Corporation |
| DS Smith |
| Wuxi Hi-Tech Environmental Material |
| BASF SE |
| Knauf Industries |
| Furukawa Electric |
| Kaneka Corporation |
| Others |
Supply Flow & Price Mechanics
Steam-chest mold engineering expertise concentrates in aging workforces across Germany and Japan, creating labor-cost differentials that widen pricing-tier spreads between premium automotive grades and commodity packaging formulations. REACH chemical disclosure mandates and EPA emission standards compound these spreads by layering compliance documentation burdens onto qualified suppliers.
Pricing Analysis
Short lead-time premiums command substantial markups in automotive qualification programs, while spot inventory of standard-density grades trades at discounts to contract benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from industrial packaging formulations and bulk construction beads. Price differentiation hinges on flammability certification tier and volume scale, with OEM direct contracts anchoring the premium band. Pricing pressure stems from propylene feedstock volatility compressing compounder margins. Consumer goods buyers exhibit highest price sensitivity; aerospace and electronics segments absorb premium positioning with limited elasticity.
Supply Chain Analysis
Freight costs from German and Chinese chemical parks to automotive assembly clusters represent a decisive factor in supplier selection and inventory positioning decisions. Supply concentrates in Germany, China, and the United States, with molding compound production anchored near polypropylene feedstock sources in Ludwigshafen, Shanghai, and Houston. Raw material dependencies center on propylene monomer, naphtha feedstock, and specialized flame retardant packages. Single-source vulnerability around steam-chest mold tooling fabricators in Stuttgart and Nagoya constrains capacity expansion timelines. Distribution runs through direct mill relationships for automotive tier-ones and regional stock-and-serve distributors for construction and consumer goods accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance disclosure requirements have erected a formidable cost-of-compliance barrier, creating durable moats for compounders with validated additive packages and documented recyclability pathways. New entrants lacking pre-qualified formulations face eighteen-to-twenty-four-month qualification timelines that incumbents exploit.
For Market Incumbents: Anchor automotive program relationships through backward integration into polypropylene feedstock and dedicated account teams co-located with OEM platform engineering centers. Expand steam-chest capacity in Chennai and Pune corridors to capture India PLI scheme incentives before qualification windows tighten. Defend against expanded polystyrene substitution in packaging by emphasizing returnable container total-cost-of-ownership advantages. For New Entrants and Emerging Players: EU Green Deal extended producer responsibility frameworks in the Netherlands and California open a window for tracking-enabled returnable packaging solutions with verified recycled content. Cold chain pharmaceutical distribution represents the most penetrable white-space segment, with temperature-validated EPP shippers commanding premium positioning absent incumbent saturation. Pursue ISCC PLUS bio-based certification as a go-to-market differentiator for sustainability-focused electronics assemblers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap compounders possessing captive automotive qualifications and underutilized steam-chest capacity given electric vehicle platform launch cadence acceleration. Long-term viability hinges on feedstock flexibility and geographic diversification across three-plus regional production hubs. Monitor ECHA substance of very high concern listing announcements as inflection indicators for reformulation-driven supplier switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Feedstock | BASF's captive supply chain control secures margin stability across REACH-mandated reformulation cycles. |
| ISCC PLUS Bio-Based Certification | Mass-balance verification opens premium positioning for foam grades with renewable feedstock content in European automotive programs. |
| Steam-Chest Capacity Expansion in India | Chennai and Pune corridor investments capture PLI scheme incentives for advanced chemistry cell component supply. |
| Returnable Packaging Pooling System Deployment | Amazon and regional logistics operators in the Netherlands deploy tracking-enabled containers through closed-loop networks. |
| High-Expansion Ratio Bead Technology Qualification | Tier-one seating suppliers in Germany absorb market share from expanded polyethylene in side-impact bolster applications. |
Methodological Framework
Multi-period observation of automotive lightweighting program announcements, e-commerce fulfillment network container deployment patterns, and regulatory disclosure filing timelines anchored the trend analysis, supplemented by interviews with EPP compounder technical directors, tier-one automotive seating procurement managers, steam-chest mold tooling engineers, and cold chain pharmaceutical logistics operators. Secondary validation drew from ECHA REACH substance listings, EPA vehicle emission standard dockets, SEC 10-K filings from integrated chemical producers, and customs trade data for polypropylene bead foam imports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting approaches modeled product type, application vertical, end-user industry, and geographic production cluster dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs included electric vehicle platform launch schedules, extended producer responsibility framework implementation timelines, and steam-chest process automation adoption curves.
The model assumes a particular technology adoption path for high-expansion ratio bead formulations; alternative pathways for expanded polyethylene substitution in safety-critical components would alter the outlook for EPP penetration rates. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Calendering Resins Market