
 Polyimide Resin Market | 2026-2036
Polyimide Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Resin Market Analytics
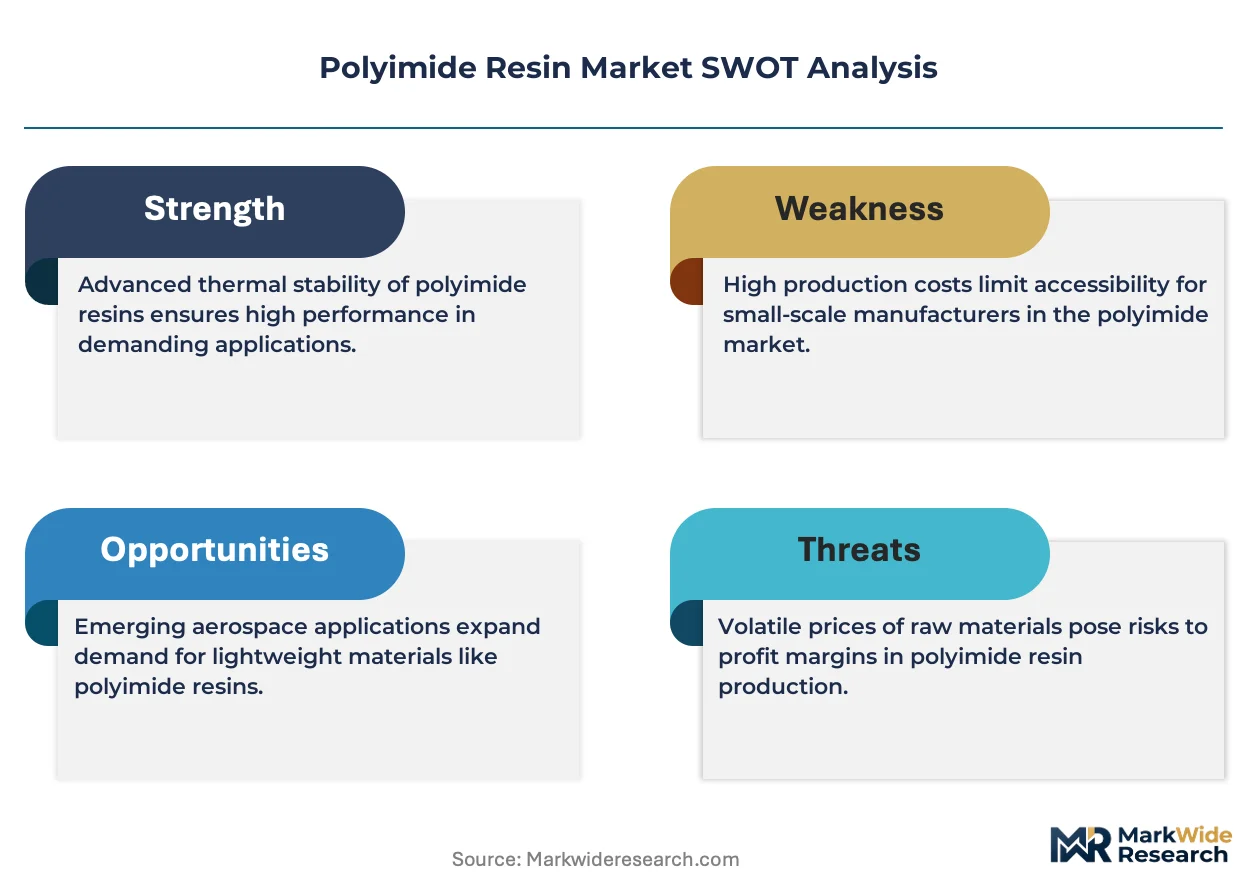
Specialized polymer synthesis expertise is collapsing across mature economies, tightening the talent pipeline for aromatic dianhydride chemistry and limiting capacity expansion at Western facilities. DuPont de Nemours anchors North American supply through captive dianhydride production and decades of Kapton brand equity in wire insulation and flexible circuits. PI Advanced Materials leverages South Korean government-backed semiconductor infrastructure to dominate ultra-thin film supply for display substrates. Kaneka Corporation sustains Japanese leadership in photosensitive polyimide formulations for wafer-level packaging applications.
Polyimide resin denotes a class of aromatic heterocyclic polymers synthesized from dianhydrides and diamines, characterized by glass transition temperatures exceeding 300°C, tensile strengths above 150 MPa, and dielectric constants ranging from 2.8 to 3.5 depending on fluorination level. These properties enable service in continuous-use environments above 200°C where conventional thermoplastics degrade, supporting applications in jet engine seals, electric motor slot liners, and flexible printed circuit boards. Thermal cure formulations occupy the largest volume share due to established supply chains in aerospace lamination and motor insulation, while photo cure grades capture expanding margin pools in semiconductor photolithography processes where patterning precision commands premium pricing. Solvent base systems retain relevance in industrial adhesive and coating applications despite environmental compliance costs associated with N-methyl-2-pyrrolidone recovery.
FDA scrutiny of extractables and leachables in medical device polymers shapes qualification protocols for implantable and diagnostic applications, while EPA reporting requirements for NMP under TSCA Section 8(a) are forcing reformulation investments toward aqueous and melt-processable alternatives. ECHA REACH restrictions on aromatic amine precursors constrain European sourcing flexibility for certain dianhydride building blocks. Buyers must evaluate supplier resilience against dual regulatory pressure from chemical hazard reclassification and carbon border adjustments affecting imported monomer feedstocks.
Market Dynamics
DuPont de Nemours maintains captive dianhydride production while PI Advanced Materials and Kaneka Corporation consolidate wafer-level packaging supply, creating a bifurcated structure between aerospace lamination incumbents and semiconductor film specialists.
Growth Catalysts
- REACH restrictions on halogenated flame retardants:European ECHA mandates redirect formulation strategies toward inherently non-flammable aromatic polymers, expanding addressable market for polyimide substitutes in wire insulation and flexible circuits.
- Wafer fabrication investments:China's domestic semiconductor passivation layer requirements concentrate demand for ultra-thin polyimide films, pulling capacity toward specialty grades with sub-10 micrometer thickness tolerances.
- Jet engine thermal protection systems:Aerospace manufacturers in the United States and Japan expand procurement of high-temperature laminates for engine seals and exhaust components, anchoring volume in thermal cure formulations.
Market Restraints
- N-methyl-2-pyrrolidone cost volatility:EPA reporting requirements under TSCA Section 8(a) force solvent recovery capital investments, compressing margins for solvent base system producers serving industrial adhesive markets.
- Aromatic amine precursor constraints:ECHA REACH restrictions on specific dianhydride building blocks limit European sourcing flexibility, creating formulation bottlenecks for photosensitive grades.
- Melt-processable polyetherimide substitution:SABIC's Ultem and similar high-performance thermoplastics encroach on cost-sensitive motor insulation applications below 180°C continuous service temperature.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic flexible display and semiconductor packaging investments create import substitution demand for specialty polyimide films currently supplied from South Korea and Japan.
- Photosensitive formulation convergence:Integration of wafer-level packaging with advanced photolithography processes opens premium margin pools in semiconductor foundries requiring sub-micron patterning resolution.
- Aqueous system regulatory tailwind:EPA and state-level air quality mandates accelerate reformulation toward water-borne polyimide precursors, rewarding first-movers with compliance cost advantages in coating applications.
Industry Challenges
- Aromatic dianhydride chemistry expertise collapse:Specialized polymer synthesis talent pipelines tighten across the United States and Western Europe, limiting qualified process engineers for condensation polymerization scale-up.
- FDA extractables and leachables qualification:Medical device polymer protocols extend certification timelines for implantable applications, delaying revenue recognition by 18-36 months for diagnostic film suppliers.
- Legacy equipment integration friction:Semiconductor fabs running 200mm and 300mm wafer lines require material qualification cycles that conflict with rapid formulation iteration demanded by advanced packaging roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Resin Market |
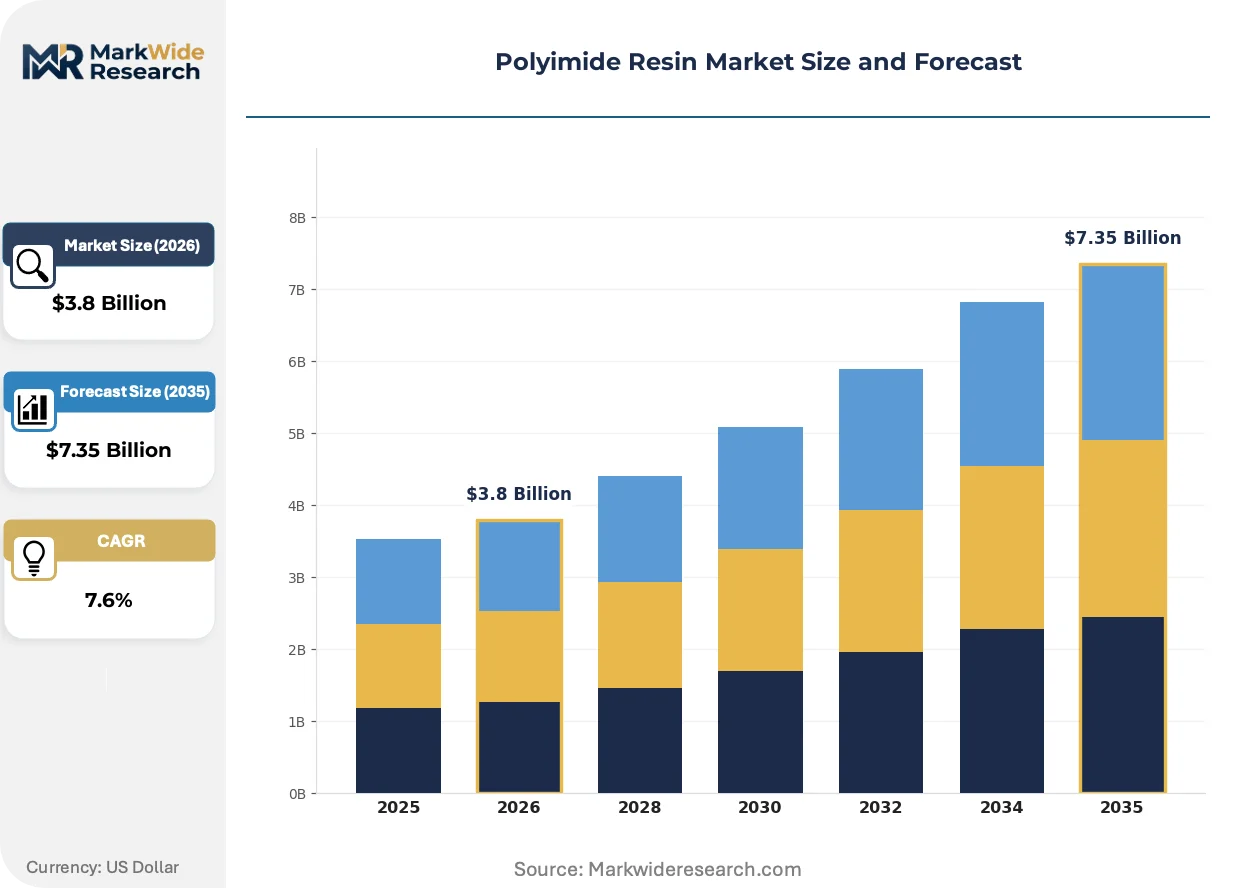
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cure, Photo Cure, Solvent Base, Prepreg Application: Aerospace, Electronics, Automotive, Industrial Grade: General Purpose, High Performance, Specialty, Flexible Technology: Liquid Process, Powder Process, Film Process, Composite Process |
| Companies Covered | DuPont de Nemours, Inc., PI Advanced Materials Co., Ltd., Kaneka Corporation, Ube Industries Ltd., Taimide Tech. Inc., SABIC, Mitsui Chemicals, Mitsubishi Gas Chemical Company, Inc., Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Resin Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are compressing traditional formulation approaches while opening specialized niches for fluorinated and aqueous alternatives in high-value semiconductor and medical segments.
Non-fluorinated transparent polyimide films are displacing conventional yellow Kapton grades in flexible display cover windows. Samsung Display and BOE Technology Group are qualifying colorless alternatives for foldable smartphone substrates, enabling optical clarity without sacrificing thermal stability. This displacement is compressing commodity film margins while expanding premium pricing tiers for optical-grade formulations.
EPA enforcement of TSCA Section 8(a) NMP reporting requirements is accelerating solvent substitution investments. Formulators serving aerospace adhesive and motor varnish markets are piloting gamma-butyrolactone and ionic liquid alternatives to avoid regulatory scrutiny. United States-based producers face the steepest compliance cost curves, pushing reformulation toward aqueous pre-imidized dispersions for industrial coating segments.
Semiconductor foundries are consolidating polyimide procurement under direct material qualification programs, bypassing traditional distributor channels. Taiwan Semiconductor Manufacturing Company and Intel Foundry Services now mandate supplier audits for dianhydride traceability and batch consistency. This channel compression is most visible in Arizona and Taichung, where new fab construction concentrates bargaining power with resin compounders capable of captive monomer synthesis.
Polyimide Resin Market Segmentation
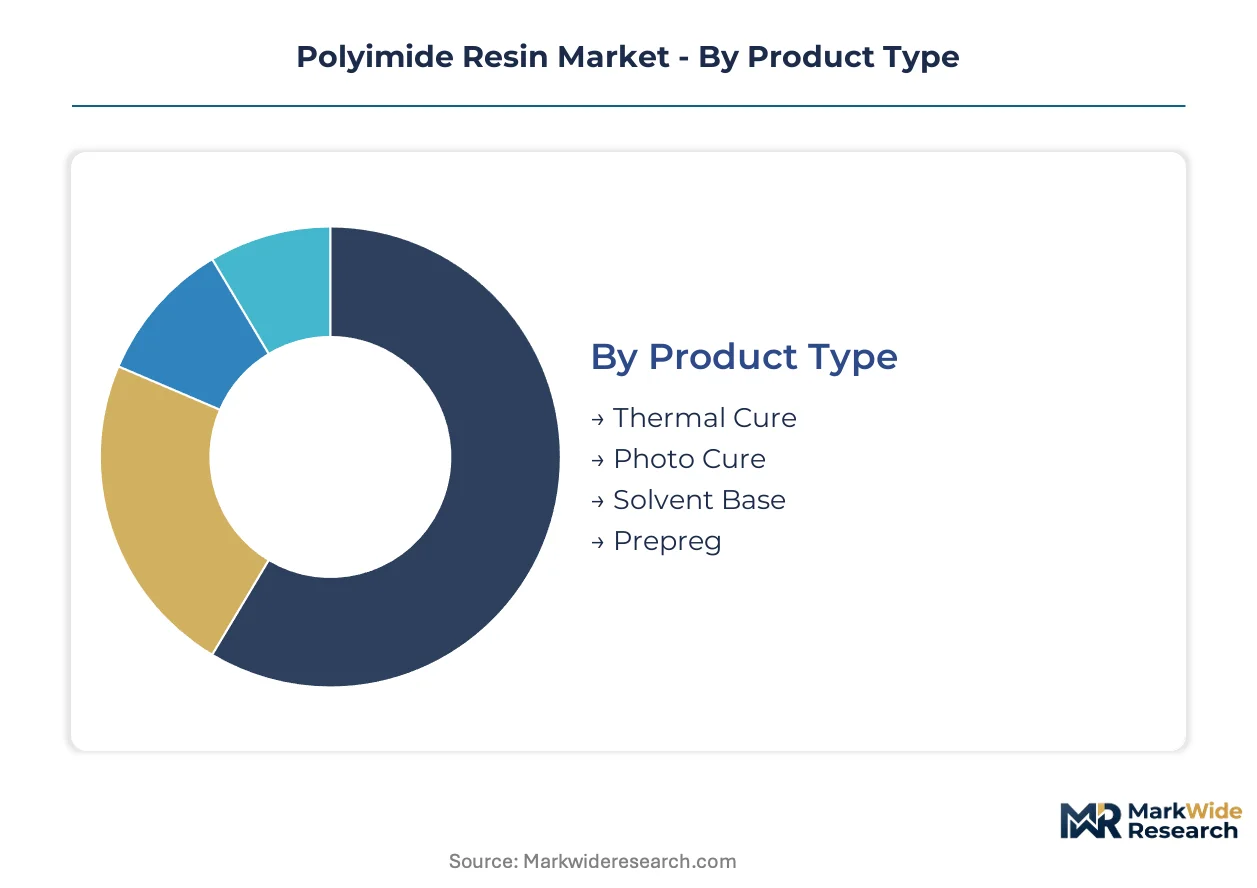
Polyimide resin formulations diverge sharply in margin capture depending on cure chemistry and end-use qualification barriers. Semiconductor and aerospace applications command premium pricing through material certification protocols that lock out commodity suppliers.
Product Type:
Thermal cure formulations anchor volume but photo cure grades capture the widest margin spreads in wafer-level packaging.
- Thermal Cure:Aromatic heterocyclic polymers requiring staged heat treatment above 300°C to achieve full imidization and mechanical properties. Jet engine seal manufacturers in the United States and Japan specify thermal cure laminates for continuous service above 200°C, with procurement expanding for exhaust component thermal protection systems.
- Photo Cure:Photosensitive formulations incorporating photoinitiator packages enabling ultraviolet or electron-beam patterning without thermal damage to underlying semiconductor structures. Taiwan Semiconductor Manufacturing Company and Intel Foundry Services in Arizona mandate direct supplier audits for dianhydride traceability, compressing distributor channels and concentrating margin with qualified compounders.
- Solvent Base:Systems dissolved in N-methyl-2-pyrrolidone for coating and adhesive applications facing EPA TSCA Section 8(a) reporting requirements.
- Prepreg:Reinforced resin matrices pre-impregnated into glass or carbon fiber for aerospace structural lamination.
Thermal cure holds installed capacity. Photo cure is rotating up the share rankings.
Application:
Electronics applications concentrate value in sub-10 micrometer film tolerances while aerospace sustains volume through engine program procurement cycles.
- Electronics:Flexible printed circuit substrates, semiconductor passivation layers, and display cover windows requiring dielectric constants between 2.8 and 3.5. China's domestic wafer fabrication investments pull capacity toward specialty ultra-thin grades, with BOE Technology Group and Samsung Display qualifying colorless alternatives for foldable smartphone substrates.
- Aerospace:High-temperature laminates for engine seals, exhaust components, and thermal protection systems where glass transition temperatures must exceed 300°C. Manufacturers in the United States and Japan are expanding procurement of thermal cure formulations for next-generation jet engine architectures.
- Automotive:Electric motor slot liners and wire insulation facing substitution pressure from SABIC's Ultem below 180°C service thresholds.
- Industrial:Adhesive and coating applications exposed to NMP solvent recovery cost volatility.
Electronics commands the steepest expansion trajectory. Aerospace maintains procurement continuity through long-term engine platform commitments.
Grade:
Specialty grades widen pricing spreads through fluorinated and optical-grade formulations that commodity producers cannot replicate.
- Specialty:Fluorinated and non-fluorinated transparent variants engineered for optical clarity without thermal stability sacrifice. These formulations enable foldable display cover window applications where conventional yellow Kapton grades fail qualification, compressing commodity film margins while establishing premium pricing tiers.
- High Performance:Tensile strengths above 150 MPa with tailored coefficient of thermal expansion for semiconductor packaging reliability.
- Flexible:Ultra-thin films below 25 micrometers for dynamic flexing applications in wearable electronics.
- General Purpose:Standard aromatic polyimides for wire insulation and motor varnish facing REACH halogenated flame retardant substitution pressure.
Specialty grade capacity concentrates with PI Advanced Materials and Kaneka Corporation. High performance is climbing the fastest in share rankings.
Technology:
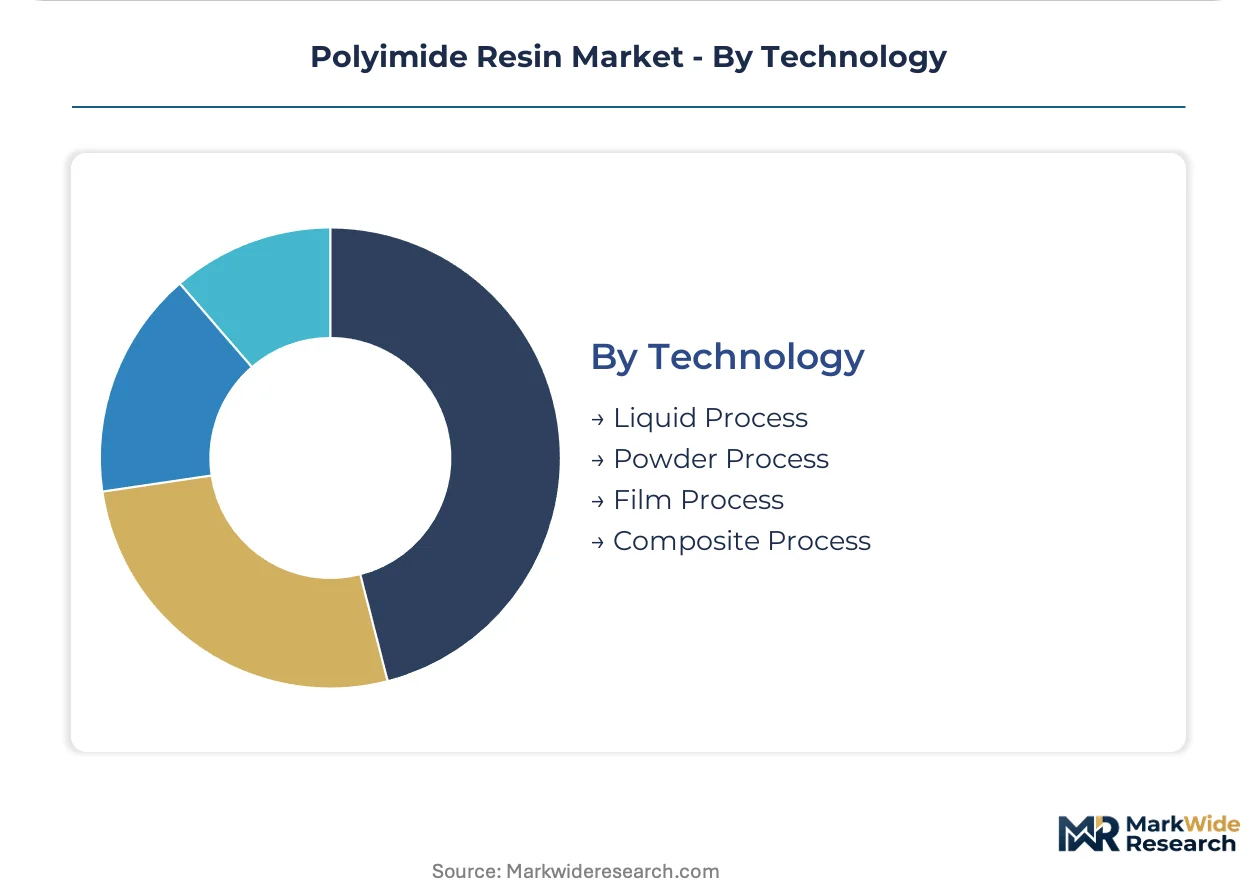
Film process technology locks in margin through thickness control precision that liquid and powder methods cannot match.
- Film Process:Continuous casting or extrusion methods producing uniform thickness polyimide films with sub-micron tolerance control. South Korean and Japanese producers dominate this technology for display substrate supply, with PI Advanced Materials leveraging government-backed semiconductor infrastructure to anchor ultra-thin film leadership.
- Liquid Process:Solution-based coating and impregnation systems for adhesive and varnish applications facing aqueous reformulation pressure from EPA air quality mandates.
- Powder Process:Solid resin forms for compression molding and sintering in industrial bearing and seal applications.
- Composite Process:Integration with carbon or glass fiber reinforcement for structural aerospace components.
Film process holds installed capacity. Liquid process is rotating up the share rankings as aqueous system investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of TSCA Section 8(a) NMP reporting requirements anchors United States regulatory pressure, while ECHA REACH restrictions on halogenated flame retardants and aromatic amine precursors reshape European formulation strategies. China's MIIT semiconductor infrastructure investments and India's PLI scheme for electronics manufacturing concentrate capacity expansion decisions across three continents.
United States
Aerospace procurement of thermal cure laminates for jet engine seals and exhaust components drives demand, with Boeing and Pratt & Whitney anchoring volume through long-term platform commitments. EPA TSCA Section 8(a) mandates force solvent recovery investments among industrial adhesive suppliers. Arizona's semiconductor corridor attracts direct material qualification programs from Taiwan Semiconductor Manufacturing Company and Intel Foundry Services.
China
Domestic wafer fabrication investments pull capacity toward ultra-thin polyimide films for semiconductor passivation layers, with BOE Technology Group qualifying colorless alternatives for foldable displays. MIIT dual carbon goals accelerate aqueous system reformulation in coating applications. Yangtze River Delta clusters in Shanghai and Suzhou concentrate specialty film production for display substrate supply.
South Korea
Samsung Display dominates flexible cover window qualification for foldable smartphones, sourcing transparent polyimide grades that displace conventional yellow Kapton. MFDS medical device polymer protocols extend certification timelines for implantable diagnostic films. Seoul Capital Area government-backed semiconductor infrastructure anchors PI Advanced Materials' ultra-thin film leadership.
Japan
Kaneka Corporation sustains photosensitive formulation expertise for wafer-level packaging applications, with METI industrial policy supporting aromatic heterocyclic polymer R&D. Jet engine thermal protection system procurement from Mitsubishi Heavy Industries and IHI anchors thermal cure volume. Chubu-Nagoya industrial corridor concentrates condensation polymerization process engineering talent.
Germany
Automotive electric motor slot liner applications face substitution pressure from SABIC's Ultem below 180°C thresholds, compressing general-purpose polyimide margins. ECHA REACH restrictions on aromatic amine precursors constrain dianhydride sourcing flexibility for European compounders. Bavaria's chemical industry clusters in Ludwigshafen and Leverkusen pilot gamma-butyrolactone solvent alternatives to NMP.
Polyimide Resin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where aerospace lamination incumbents compete on qualification heritage while semiconductor film specialists capture premium margins through thickness precision. The vendor base separates into three strategic tiers: captive dianhydride producers with decades of brand equity, government-backed Asian specialists leveraging domestic fab infrastructure, and regional compounders serving industrial adhesive markets. Dominant competitive moves include backward integration into monomer synthesis and direct material qualification programs that bypass traditional distributor channels.
Among North American incumbents, DuPont de Nemours exemplifies the captive production archetype through in-house dianhydride supply chains and established Kapton brand recognition. PI Advanced Materials and Kaneka Corporation represent the government-backed Asian specialist model, leveraging South Korean and Japanese semiconductor infrastructure respectively to anchor ultra-thin and photosensitive grade supply. These three companies occupy positions that concentrate premium-tier capacity while regional compounders compete on reformulation agility for solvent base and aqueous system segments.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| PI Advanced Materials Co., Ltd. |
| Kaneka Corporation |
| Ube Industries Ltd. |
| Taimide Tech. Inc. |
| SABIC |
| Mitsui Chemicals |
| Mitsubishi Gas Chemical Company, Inc. |
| Asahi Kasei Corporation |
| Others |
Value Network & Pricing Analysis
Captive dianhydride production at scale anchors price floors across thermal cure formulations, concentrating margin power with integrated producers in the United States and Japan while forcing compounders without upstream control toward cost-competitive aqueous alternatives. This scale asymmetry shapes a bifurcated pricing landscape where semiconductor-grade films command substantial premiums over industrial adhesive grades facing EPA compliance cost compression.
Pricing Analysis
Geographic price spreads between South Korean ultra-thin films and European solvent-base systems reflect divergent regulatory cost burdens and qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates photo cure semiconductor grades from thermal cure aerospace laminates and general-purpose wire insulation, with differentiation driven by thickness tolerance precision and captive monomer synthesis. Pricing pressure stems from SABIC's Ultem substitution in automotive applications below 180°C, compressing general-purpose margins. Industrial adhesive buyers exhibit highest price sensitivity due to NMP recovery cost pass-through, while semiconductor foundries prioritize batch consistency over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Ningbo corridor and Yokohama port complex shape raw material access for dianhydride monomers and aromatic diamine precursors. Supply concentrates in the United States, South Korea, and Japan, drawing from pyromellitic dianhydride feedstocks and oxydianiline intermediates. Single-source vulnerability pervades ultra-thin film grades below 10 micrometers, where PI Advanced Materials and Kaneka Corporation control qualified capacity. Distribution runs through direct material qualification programs at Taiwan Semiconductor Manufacturing Company and Intel Foundry Services, bypassing traditional distributor channels for semiconductor applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical lows in aerospace procurement, with jet engine platform commitments at Boeing and Pratt & Whitney anchoring volume visibility through long-term thermal cure laminate contracts.
For Market Incumbents: Shield premium positioning in photo cure grades by deepening backward integration into dianhydride synthesis and accelerating aqueous system R&D ahead of EPA enforcement timelines. Captive monomer production remains the critical lever against margin erosion from NMP cost volatility, while direct qualification programs with Arizona semiconductor fabs lock out distributor-dependent competitors. For New Entrants and Emerging Players: Lead with aqueous pre-imidized dispersions for industrial coating segments where incumbent reformulation lag creates white-space opportunity. India's PLI scheme for electronics manufacturing offers the most penetrable geography, with domestic flexible display investments seeking import substitution for South Korean film supply. Target foundry-adjacent compounders lacking captive monomer capacity for partnership-based market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among semiconductor film specialists with direct fab qualification status and multi-year supply agreements. Long-term viability favors producers with demonstrated thickness control below 10 micrometers and traceable dianhydride supply chains. Watch for Intel Foundry Services and Taiwan Semiconductor Manufacturing Company qualification announcements as inflection indicators for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Synthesis | DuPont de Nemours and Japanese incumbents secure feedstock autonomy against ECHA REACH aromatic amine constraints. |
| Aqueous System Reformulation | EPA TSCA Section 8(a) compliance cost avoidance rewards first-movers in industrial coating segments. |
| Direct Material Qualification Programs | Semiconductor foundries in Arizona and Taichung consolidate procurement power with audited compounders. |
| Optical-Grade Film Capacity Expansion | Samsung Display and BOE Technology Group qualification requirements pull investment toward colorless transparent variants. |
| India PLI Scheme Localization | Domestic electronics manufacturing incentives create import substitution demand for specialty polyimide films. |
Research Methodology
Operator-level perspectives from plant managers at condensation polymerization facilities, procurement leads at aerospace OEMs, technical R&D directors at semiconductor packaging houses, and distribution channel partners anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, and ACC industry reports. Bottom-up capacity assessments triangulated against top-down demand modeling across end-use segments.
Sensitivity analysis tested forecast robustness across the projection horizon, with segmentation modeling spanning cure chemistry type, application end-use, grade tier, and regional production hub. CAGRs derived from installed capacity expansion schedules, qualification timeline assumptions, and substitution elasticity parameters. Key inputs included jet engine platform procurement cycles, domestic wafer fabrication investment pipelines, and regulatory compliance cost curves.
Underlying assumptions cover continued EPA enforcement of TSCA Section 8(a) NMP reporting, ECHA REACH aromatic amine precursor restrictions, and MIIT semiconductor infrastructure commitments in China, with deviation risk concentrated in reformulation timeline delays and foundry qualification cycle extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Copolyesters Market