
 Asia-Pacific Reflective Tape Market | 2026-2036
Asia-Pacific Reflective Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Reflective Tape Market Insights
Market Context
Southeast Asian capacity build-out is fragmenting the Asia-Pacific reflective tape supply base as Vietnam and Indonesia add domestic lamination and coating lines. 3M leverages its regional distribution hubs to sustain premium positioning across safety and vehicle marking channels. Changzhou Hua R Sheng Reflective Material anchors volume supply for domestic Chinese road projects, while Nippon Carbide Industries competes through specialized polycarbonate formulations for Japanese automotive OEMs.
Technical Definition and Segment Structure
Asia-Pacific reflective tape comprises retroreflective sheeting and striping materials engineered with glass bead or prismatic optical elements bonded to polyester, vinyl, or polycarbonate substrates, typically manufactured through precision coating, metallization, and embossing processes to return incident light toward its source for nighttime visibility enhancement. Pressure-sensitive adhesive products dominate road safety and vehicle marking applications due to standardized procurement protocols, while apparel-grade segments gain share as Chinese and Bangladeshi textile manufacturers integrate reflective trim into workwear exports. Acrylic-based formulations command margin premiums in signage applications where UV resistance and colorfastness requirements exceed commodity vinyl specifications.
Regulatory Framework
China's SAMR enforces GB standards for retroreflective traffic control devices, while India's BIS certification mandates minimum coefficient of retroreflection for highway safety products; Japan's METI coordinates JIS standards with PMDA-adjacent automotive safety protocols. These frameworks compel manufacturers to maintain dual-certification capabilities or risk exclusion from public infrastructure tenders. Stakeholders must monitor evolving harmonization between national standards and ISO 17398 performance benchmarks to anticipate qualification barriers in cross-border supply arrangements.
Market Dynamics
China's GB standard revisions for retroreflective traffic signage are compressing qualification timelines for suppliers while simultaneously expanding the addressable market for certified high-performance materials across highway infrastructure tenders.
Growth Catalysts
- Japan's JIS-certified automotive conspicuity mandates:METI-coordinated safety protocols now require retroreflective tape on commercial vehicle fleets, creating sustained OEM demand for polycarbonate-grade formulations.
- Highway infrastructure upgrades:India's National Highways Authority and China's provincial transport bureaus are expanding procurement of high-visibility marking materials for lane delineation and signage replacement programs.
- Glass bead precision coating advances:Automated metallization lines in eastern China's manufacturing belt are improving coefficient of retroreflection consistency, reducing rejection rates in BIS and SAMR certification testing.
Market Restraints
- Petrochemical input volatility:Acrylic and polyester substrate costs fluctuate with regional naphtha pricing, compressing margins for non-integrated laminators in Vietnam and Indonesia.
- Prismatic film supply concentration:Microprismatic retroreflective sheeting production remains concentrated among Japanese and US technology holders, creating licensing bottlenecks for Southeast Asian entrants.
- UV degradation technical limits:Commodity vinyl formulations fail India's BIS colorfastness requirements within 36 months in high-altitude Himalayan conditions, forcing premature replacement cycles.
Strategic Opportunities
- Bangladeshi apparel export integration:Chinese reflective trim suppliers are embedding pressure-sensitive adhesive strips into EU-bound workwear, capturing value previously retained by European converters.
- ISO 17398 harmonization tailwinds:Cross-border qualification barriers are softening as SAMR, BIS, and METI align testing protocols, enabling single-certification regional supply strategies.
- E-mobility charging infrastructure marking:Retroreflective ground signage for EV station safety zones represents an emerging application channel with limited incumbent penetration.
Industry Challenges
- Dual-certification talent scarcity:Technical staff capable of navigating simultaneous GB and JIS documentation requirements command premium compensation, constraining mid-tier manufacturer expansion.
- Embossing equipment capex intensity:Precision microprismatic tooling requires dedicated capital commitments exceeding typical Southeast Asian lamination facility budgets.
- Automotive OEM qualification timelines:Japanese vehicle manufacturers impose 18-24 month validation cycles for new retroreflective material suppliers, freezing out recent market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Reflective Tape Market |
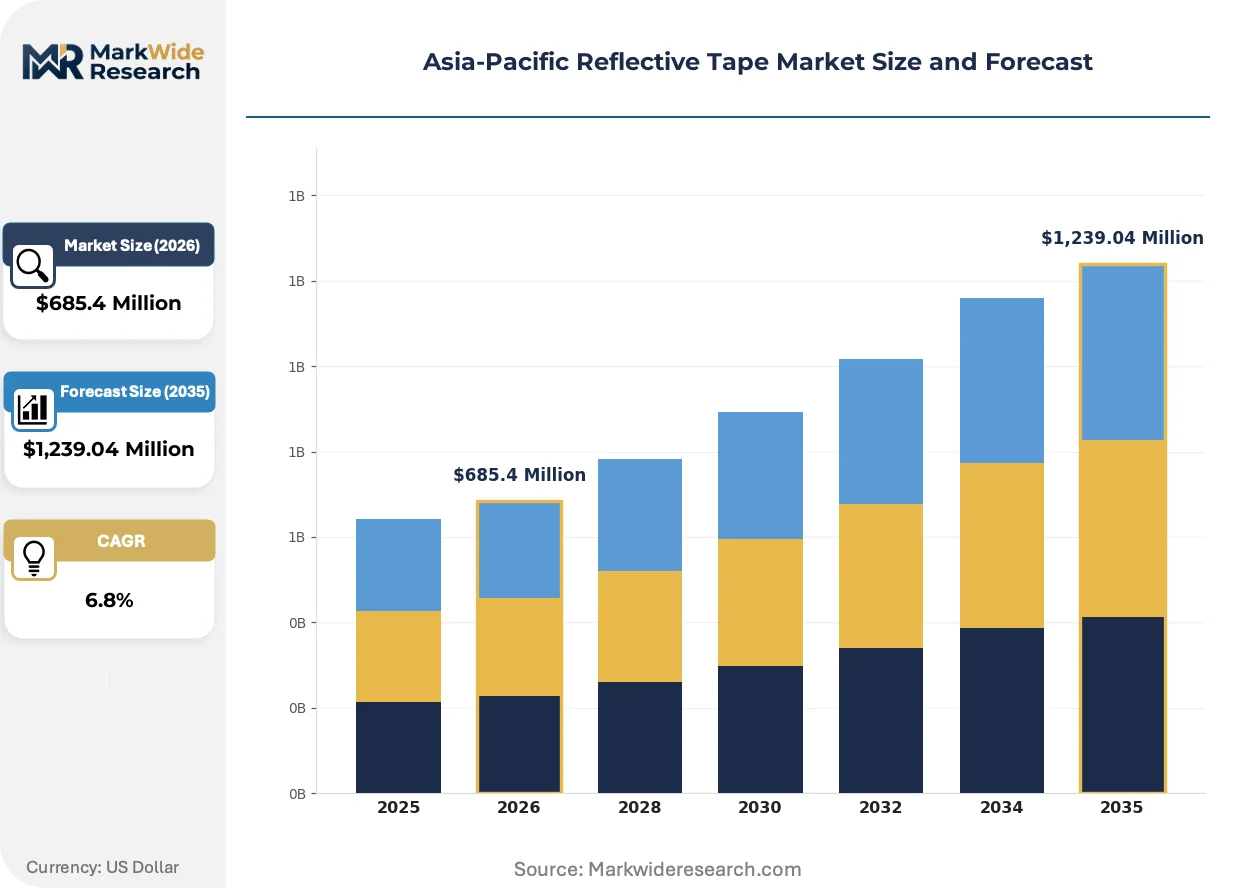
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Adhesive, Safety, Non-Adhesive Application: Road Safety, Vehicle Marking, Apparel, Signage Material: Polyester, Vinyl, Polycarbonate, Acrylic End User: Manufacturers, Construction, Transportation, Retail |
| Companies Covered | 3M, Avery Dennison Corporation, ORAFOL Europe GmbH, Nippon Carbide Industries Co., Changzhou Hua R Sheng Reflective Material Co., Ltd., Paiho Group, SKC, DM Reflective, Daoming Optics and Chemical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Reflective Tape Market Trends and Innovations
Digital specification tools and substrate material science are compressing product development cycles while expanding performance boundaries for retroreflective applications across automotive, infrastructure, and industrial safety channels.
Microprismatic retroreflective films are virtualizing the traditional glass-bead-dominated product hierarchy in Asia-Pacific signage procurement. Provincial transport authorities in China and India are specifying prismatic-grade materials for new highway contracts despite 40-60% cost premiums over bead-engineered alternatives. This specification shift is virtualizing competitive positioning, forcing legacy bead-technology manufacturers to license prismatic embossing capabilities or retreat to commodity apparel-grade segments.
China's SAMR enforcement of revised GB standards for retroreflective traffic control devices is tightening coefficient of retroreflection minimums and expanding weathering test protocols. Domestic manufacturers must now submit to accelerated UV-aging and salt-spray validation that previously applied only to export-bound production. Road safety product distributors are consolidating supplier relationships to reduce compliance documentation complexity, privileging vertically integrated producers with in-house metallization and coating capabilities.
Specification authority is migrating from procurement officers to engineering departments within Asia-Pacific infrastructure agencies. Technical committees in India's BIS and Japan's METI now draft material requirements before tender release, reducing price-only competition. This pattern is most visible in China's eastern province expressway projects, where design institutes embed retroreflective performance clauses that pre-qualify only prismatic-grade suppliers, compressing the viable vendor pool regardless of bid pricing.
Asia-Pacific Reflective Tape Market Segmentation
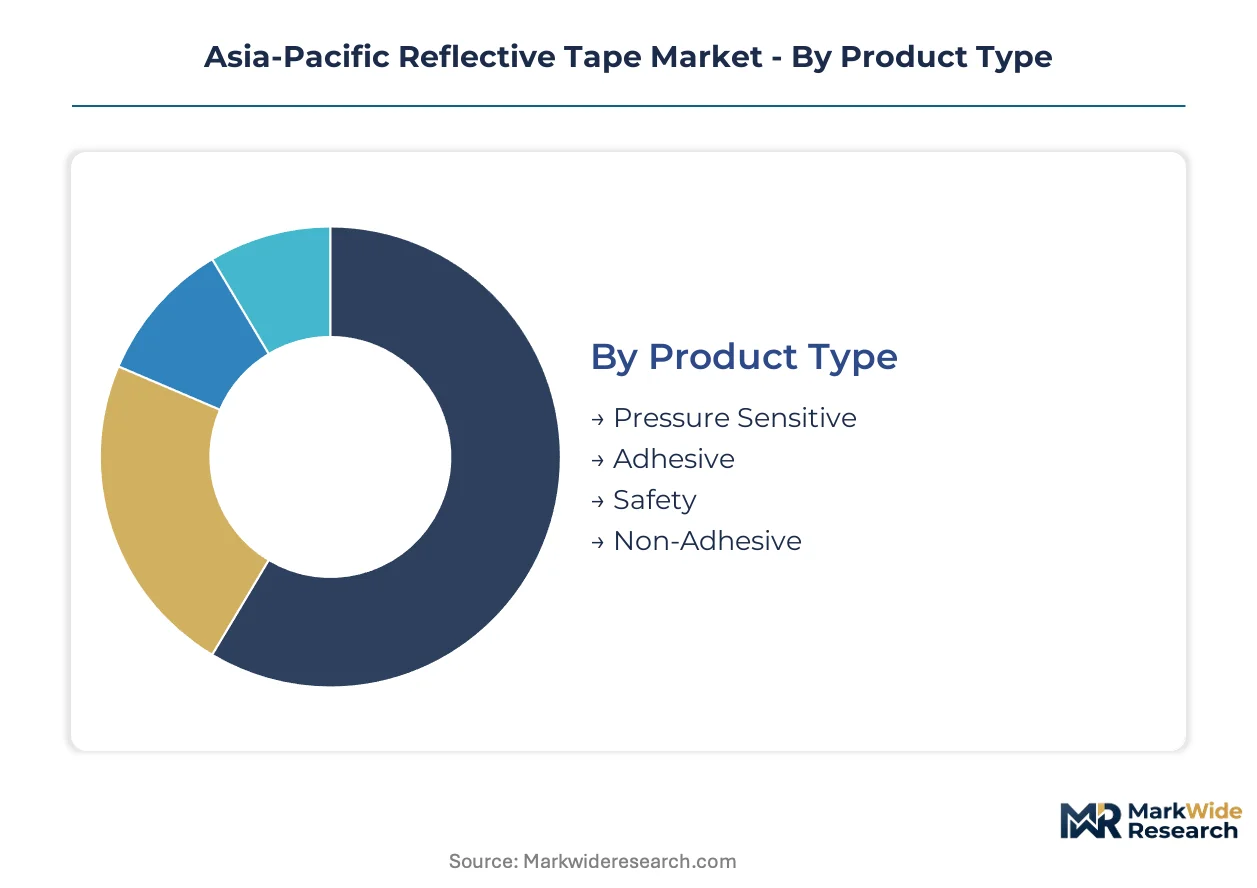
Retroreflective tape procurement in Asia-Pacific splits across adhesive technologies, safety-critical applications, substrate chemistries, and buyer categories with divergent specification authority. Each segmentation axis reveals distinct margin structures and certification barriers that shape competitive positioning.
Product Type:
Cost tiers separate commodity pressure-sensitive formats from specialized non-adhesive systems requiring mechanical fastening or heat-activation.
- Pressure Sensitive:Acrylic or rubber-based adhesive layers enable rapid field application without curing equipment. China's provincial transport bureaus specify PSA products for lane marking refresh cycles where installation speed outweighs 15-year durability requirements.
- Adhesive:Solvent-activated or heat-bonded systems deliver superior environmental resistance for permanent signage installations. Indian National Highways Authority tenders increasingly mandate adhesive-grade retroreflective sheeting for overhead gantry signs exposed to monsoon cycling and UV stress.
- Safety:High-visibility formulations engineered for emergency vehicle and personal protective equipment with enhanced conspicuity coefficients. Bangladeshi workwear exporters integrate safety-grade reflective trim into EU-bound garments.
- Non-Adhesive:Sew-on or mechanical-attachment products serving textile and temporary barrier applications where surface adhesion is impractical. Japanese automotive OEMs specify non-adhesive polycarbonate strips for interior safety markings.
Pressure sensitive commands the established base. The steepest expansion runs through safety.
Application:
End-use contexts range from infrastructure-scale procurement with multi-year validation cycles to fast-turn apparel integration with seasonal demand patterns.
- Road Safety:Lane delineation, pavement markings, and traffic control devices requiring coefficient of retroreflection certification under GB, BIS, or JIS protocols. Eastern China's manufacturing belt clusters supply road safety products for domestic highway upgrades and Southeast Asian export markets.
- Vehicle Marking:Commercial fleet conspicuity mandates under Japan's METI-coordinated safety protocols and emerging Indian commercial vehicle regulations. Polycarbonate-grade formulations dominate OEM qualification programs with 18-24 month validation timelines.
- Apparel:Reflective trim integration into industrial workwear, sportswear, and fashion applications. Chinese suppliers embed pressure-sensitive adhesive strips into Bangladeshi-manufactured garments for European retail distribution.
- Signage:Regulatory and commercial signage requiring weathering resistance and colorfastness under accelerated UV-aging test protocols. Prismatic-grade materials are displacing glass-bead alternatives in China's revised GB standard environment.
Road safety anchors procurement volume. Apparel climbs the fastest as export manufacturing shifts reflective trim integration upstream.
Material:
Substrate chemistry determines UV resistance, embossing compatibility, and cost position across climate zones from Himalayan high-altitude conditions to tropical Southeast Asian humidity.
- Polyester:PET film substrates providing dimensional stability and metallization compatibility for glass-bead and prismatic optical elements. Eastern China's polyester supply chain concentration enables integrated coating and lamination operations.
- Vinyl:PVC formulations offering cost efficiency for short-cycle applications with limited weathering exposure. Commodity vinyl fails BIS colorfastness requirements within 36 months in high-altitude Indian conditions, constraining addressable geography.
- Polycarbonate:High-performance substrates enabling microprismatic embossing with superior coefficient of retroreflection and impact resistance. Japanese automotive OEMs specify polycarbonate-grade tapes for fleet conspicuity mandates.
- Acrylic:UV-stable formulations commanding margin premiums in signage applications where colorfastness requirements exceed commodity vinyl specifications. SAMR's revised GB weathering protocols favor acrylic substrates for permanent traffic control devices.
Polyester commands the established base. Polycarbonate gains share fastest as prismatic specification authority consolidates.
End User:
Customer type determines specification authority, procurement protocol complexity, and price elasticity across integrated manufacturing and fragmented distribution channels.
- Manufacturers:Reflective material converters, textile producers, and sign fabricators purchasing bulk substrates for downstream processing. Chinese manufacturers dominate volume procurement for domestic road projects and apparel export integration.
- Construction:Infrastructure contractors executing highway, bridge, and urban development projects with milestone-based material consumption. India's National Highways Authority channels construction demand through centralized tender processes.
- Transportation:Fleet operators, rail authorities, and logistics companies implementing vehicle and facility marking programs. Japan's commercial vehicle fleet operators drive polycarbonate-grade demand under METI conspicuity mandates.
- Retail:Distributors, safety equipment suppliers, and e-commerce channels serving fragmented end-user demand for replacement and upgrade purchases. Retail channels concentrate in eastern China's manufacturing belt for proximity to production sources.
Manufacturers command the established base. Transportation climbs fastest as fleet conspicuity regulations expand across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reflective tape manufacturing clusters tightly around polyester and acrylic feedstock corridors in eastern China, while procurement demand radiates across highway infrastructure programs in India, commercial fleet mandates in Japan, and emerging apparel integration nodes in Bangladesh.
China
Provincial transport bureaus in Jiangsu and Zhejiang are refreshing lane markings and signage under revised GB standards that tighten coefficient of retroreflection minimums. SAMR's accelerated UV-aging and salt-spray validation protocols now apply to domestic production, not just export-bound material. Changzhou anchors the manufacturing belt where integrated coating and metallization operations serve both domestic highway tenders and Southeast Asian export markets.
India
The National Highways Authority is expanding procurement of high-visibility marking materials for lane delineation and gantry sign replacement across the Golden Quadrilateral network. BIS certification mandates minimum retroreflection coefficients that commodity vinyl formulations fail within 36 months in high-altitude Himalayan conditions. Gujarat and Maharashtra host the primary distribution corridors feeding infrastructure contractors executing milestone-based material consumption.
Japan
METI-coordinated JIS-certified automotive conspicuity requirements now cover commercial vehicle fleets, creating sustained OEM demand for polycarbonate-grade formulations. Automotive manufacturers impose 18-24 month validation cycles for new retroreflective material suppliers. The Kanto and Kansai industrial corridors concentrate vehicle marking demand from fleet operators and rail authorities implementing facility marking programs.
Vietnam
Domestic lamination and coating lines are adding capacity to capture regional supply previously imported from China. Petrochemical input volatility compresses margins for non-integrated operations dependent on imported acrylic and polyester substrates. Ho Chi Minh City and Hanoi industrial zones host emerging converters serving Southeast Asian road safety procurement with shorter logistics lead times than Chinese sources.
Bangladesh
Textile manufacturers are integrating reflective trim into EU-bound workwear exports, shifting value capture from European converters to upstream Asian suppliers. Chinese pressure-sensitive adhesive strip suppliers are embedding directly into garment production workflows. Dhaka and Chittagong apparel export zones represent the fastest-growing demand vector for safety-grade reflective tape outside traditional infrastructure channels.
Asia-Pacific Reflective Tape Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Asia-Pacific reflective tape market structures around three distinct competitive layers: multinational material science conglomerates with regional distribution hubs, mid-scale Asian manufacturers with vertically integrated coating capabilities, and specialized converters focused on narrow application segments. Consolidation pressure runs strongest at the mid-tier where certification documentation requirements favor producers with in-house metallization and embossing operations. Strategic moves concentrate on licensing prismatic embossing technology and embedding into upstream apparel manufacturing workflows.
Among multinational platform operators, 3M leverages regional distribution infrastructure to sustain premium positioning across safety and vehicle marking channels. Mid-scale Chinese specialists occupy the volume tier: Changzhou Hua R Sheng Reflective Material anchors domestic road project supply, while Daoming Optics and Chemical represents the integrated coating-and-metallization archetype serving both infrastructure and export apparel demand. Japanese technology holders including Nippon Carbide Industries sit within the specialized polycarbonate formulation segment where JIS certification and automotive OEM qualification timelines create defensive moats against Southeast Asian entrants.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison Corporation |
| ORAFOL Europe GmbH |
| Nippon Carbide Industries Co. |
| Changzhou Hua R Sheng Reflective Material Co., Ltd. |
| Paiho Group |
| SKC |
| DM Reflective |
| Daoming Optics and Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Vietnamese lamination facilities is compressing margins for non-integrated converters while simultaneously forcing Chinese producers toward premium polycarbonate-grade positioning. Utilization rates below break-even thresholds in Ho Chi Minh City industrial zones drive aggressive spot-market pricing for commodity pressure-sensitive tapes, whereas integrated metallization operations in Jiangsu province retain pricing power through GB-certified product lines.
Pricing Analysis
China's SAMR-enforced GB standards dictate the pricing tier structure across the Asia-Pacific reflective tape market, separating prismatic-grade polycarbonate formulations from commodity vinyl alternatives. Price differentiation hinges on certification grade under JIS and BIS protocols alongside volume scale in highway infrastructure tenders. Cost compression in Vietnamese non-integrated lamination is intensifying because petrochemical input volatility erodes converter margins. Construction contractors executing India's National Highways Authority projects exhibit highest price sensitivity, while Japanese automotive OEMs demonstrate least sensitivity due to 18-24 month qualification lock-in.
Supply Chain Analysis
Eastern China's Changzhou and Zhejiang manufacturing clusters hold dominant coating and metallization capacity for retroreflective tape production. Geographic supply concentrates in China, Japan, and emerging Vietnam facilities. Raw material dependencies draw from regional polyester film supply chains, acrylic resin producers, and imported microprismatic embossing equipment. Single-source vulnerability around Japanese-licensed prismatic technology creates licensing bottlenecks for Southeast Asian entrants. Distribution runs through provincial transport bureau tender processes for road safety products and direct OEM supply agreements for automotive marking applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in certification documentation and compliance consulting are expanding faster than hardware sales as SAMR, BIS, and METI tighten validation protocols. Recurring revenue from annual re-certification and technical file maintenance now outpaces unit volume growth for established suppliers.
For Market Incumbents: Insulate margin position through captive metallization capacity in Jiangsu province and exclusive licensing of Japanese microprismatic embossing technology. Prismatic specification shifts by China's provincial transport bureaus threaten bead-technology legacy producers. Certification investment in simultaneous GB-JIS documentation capabilities creates defensive moats against Southeast Asian entrants.
For New Entrants and Emerging Players: Bangladeshi apparel export zones offer underpenetrated safety-grade reflective trim demand with faster qualification cycles than automotive or infrastructure channels. Target EU-bound workwear integration workflows where Chinese pressure-sensitive adhesive suppliers currently embed upstream. Go-to-market angle: direct technical partnership with Dhaka-based garment manufacturers bypassing European converter intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across prismatic-grade production as precision embossing equipment requirements exceed typical mid-tier facility budgets. Long-term viability favors vertically integrated producers with in-house coating, metallization, and certification capabilities. Acquisition target archetype: Chinese manufacturers with SAMR-validated production lines and established provincial transport bureau relationships. Signal to watch: provincial tender specifications mandating prismatic-grade materials for expressway projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallization | Captive coating capacity reduces SAMR certification rejection rates and procurement documentation complexity. |
| Prismatic Technology Licensing | Japanese patent holders extract royalties while constraining Southeast Asian competitor embossing capabilities. |
| Apparel Supply Chain Embedding | Chinese adhesive strip suppliers capture value from European converters in Bangladeshi workwear export workflows. |
| Dual-Certification Capability Buildout | Simultaneous GB-JIS documentation access expands addressable tender pools across China and Japan infrastructure. |
| Regional Distribution Hub Expansion | 3M's Asia-Pacific logistics network sustains premium positioning through rapid field technical support. |
Research Methodology
A standing panel of road safety procurement officers, reflective material plant managers, automotive OEM qualification engineers, and textile supply chain directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SAMR GB standard filings, BIS certification registries, METI JIS documentation, and provincial transport bureau tender databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the Asia-Pacific region.
Scenario-bracketing framed volume and value outputs across the projection horizon, with analytical modeling segmented by adhesive technology, substrate chemistry, application channel, and end-user procurement authority. CAGRs derived from regression analysis of historical certification volumes and forward infrastructure spend commitments. Industry-specific forecast inputs included highway infrastructure tender pipelines, commercial fleet conspicuity mandate implementation timelines, and apparel export order flows from Bangladeshi manufacturing zones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Vietnamese lamination entrants or accelerated prismatic specification shifts by China's SAMR would shift outcomes. Forecasts reflect documented assumptions regarding petrochemical input cost stability and regulatory harmonization progress between national standards and ISO 17398 benchmarks. Quarterly review of provincial transport bureau tender specifications and JIS certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Global Flexible Substrates Market