
 Biphenyltetracarboxylic Dianhydride Market | 2026-2036
Biphenyltetracarboxylic Dianhydride Market Size, Share, and Industry Trends Forecast 2026-2036
Biphenyltetracarboxylic Dianhydride Market Outlook
The EU Green Deal's chemical sustainability targets is realigning procurement priorities for polyimide precursor materials across European electronics supply chains. Mitsubishi Chemical Corporation leverages its integrated aromatic chemical production to sustain cost advantages in high-purity dianhydride output. UBE Industries anchors its position through captive supply of upstream biphenyl feedstock and specialized reactor technology. Daikin Industries differentiates via fluorinated polyimide co-development programs that tighten specification tolerances for semiconductor clients.
Biphenyltetracarboxylic dianhydride (BPDA) is a tetracarboxylic acid anhydride with two phthalic anhydride units linked at the 3,3' or 4,4' positions of a biphenyl core, synthesized primarily through catalytic oxidation of dimethylbiphenyl or chlorination-carbonyl routes, and serves as the principal monomer for polyimide resins requiring thermal stability above 300°C. The solid form dominates commercial supply due to superior storage stability and precise stoichiometry control during polycondensation with aromatic diamines. Electronics applications lead value capture, driven by flexible printed circuit substrate demand and chip packaging films, while aerospace-grade composites represent the fastest-growing end-use segment as OEMs qualify BPDA-based polyimides for engine nacelle and thermal protection systems.
EPA oversight under the Toxic Substances Control Act and Japan's METI chemical substance classification system jointly shape manufacturing standards, import licensing, and emission controls for BPDA producers seeking multi-regional market access. REACH registration requirements in Europe impose full toxicological dossiers that favor established suppliers with dedicated regulatory affairs capacity. ECHA's persistent organic pollutant screening protocols and evolving GB standards under China's MEE are accelerating substitution studies for legacy dianhydride chemistries. Stakeholders must monitor polymer-grade specification divergence across regulatory jurisdictions to avoid qualification failures in qualified supplier programs.
Market Dynamics
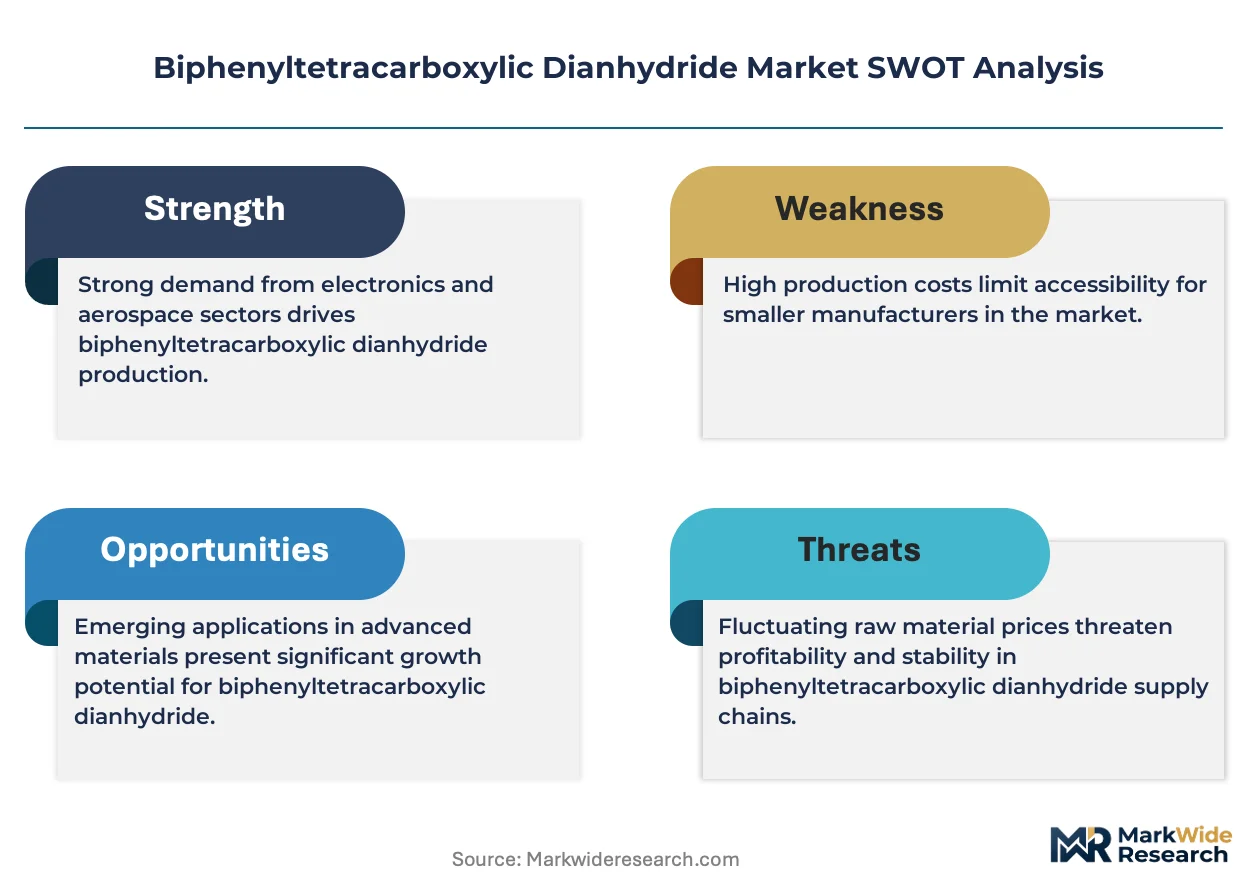
Electronics-grade polyimide qualification programs are compressing BPDA specification tolerances as semiconductor packaging architectures migrate toward finer-pitch interconnects and higher thermal loads.
Growth Catalysts
- Flexible substrate demand:Chip-scale packaging expansion in Japan and South Korea is pulling high-purity dianhydride volumes for polyimide film laminates used in advanced interposers.
- EU Green Deal chemical targets:REACH-registered BPDA grades are displacing legacy anhydride chemistries in European electronics supply chains as OEMs requalify precursor portfolios.
- Aerospace thermal protection:Engine nacelle composite programs in the United States are qualifying BPDA-based polyimides for continuous-use temperatures above 300°C, opening specification windows previously held by bismaleimide resins.
Market Restraints
- Feedstock concentration:Dimethylbiphenyl supply concentrates among Japanese aromatic chemical producers, creating price volatility transmission into dianhydride conversion economics.
- Purification capex intensity:Electronics-grade BPDA requires sub-ppm metal ion removal, forcing dedicated crystallization trains that inflate fixed cost structures for new entrants.
- Substitution pressure:Partially fluorinated dianhydrides from Daikin Industries are capturing niche semiconductor packaging segments where dielectric constant minimization outweighs thermal stability priorities.
Strategic Opportunities
- Underpenetrated India electronics:PLI scheme incentives for semiconductor packaging are creating first-mover qualification windows for BPDA suppliers willing to establish local technical service capacity.
- GB standard alignment:China's evolving MEE pollutant discharge rules are accelerating substitution studies that favor BPDA over legacy phthalic anhydride derivatives in domestic polyimide production.
- Fluorinated co-development:Convergence between BPDA backbone chemistry and perfluorinated diamine coupling agents is enabling refractive index-tuned films for optical interconnect applications.
Industry Challenges
- Regulatory dossier capacity:REACH registration maintenance and ECHA persistent organic pollutant screening require dedicated toxicology teams that mid-scale producers struggle to resource.
- Polymer-grade specification divergence:JIS, GB, and ASTM test method differences across Japan, China, and the United States force parallel qualification campaigns that extend customer approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biphenyltetracarboxylic Dianhydride Market |
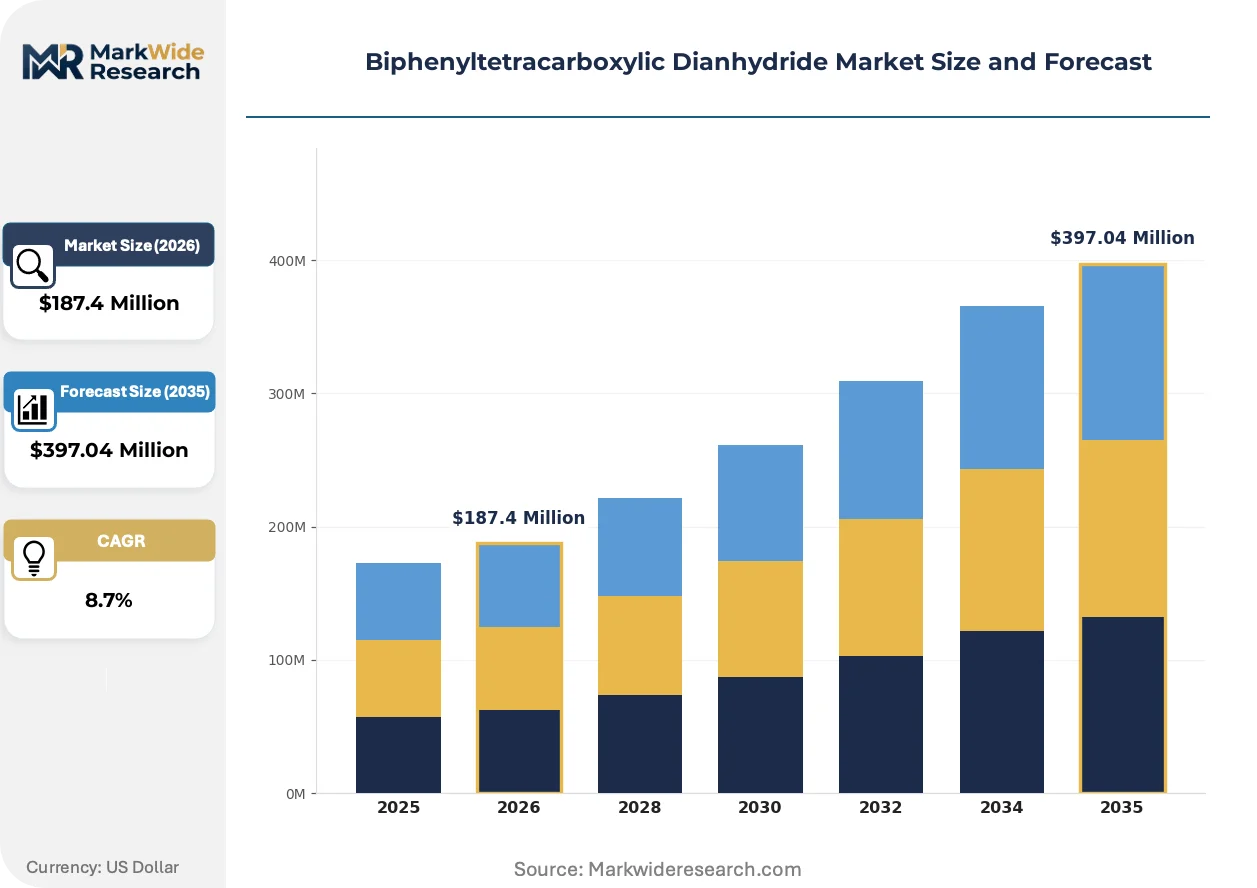
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Powder, Solution End Use Industry: Aerospace, Automotive, Electronics, Coatings Application: Insulation, Adhesives, Composites, Sealants Form: Film, Fiber, Granule, Rod |
| Companies Covered | Jiangsu Sunlight Pharmaceutical Chemicals, Merck KGaA, Mitsubishi Chemical Corporation, Aether Industries, Akron Polymer Systems, UBE Industries, SEIKA Corporation, Hodogaya Chemical, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biphenyltetracarboxylic Dianhydride Market Strategic Shifts
Process intensification in dianhydride production and downstream polyimide formulation are compressing development cycles while regulatory pressure on precursor sustainability intensifies specification layering.
Continuous-flow oxidation reactors are modularizing BPDA manufacturing by replacing batch dimethylbiphenyl conversion with integrated catalytic systems that reduce solvent inventory and thermal degradation byproducts. Japanese chemical producers are deploying these units for electronics-grade output where lot-to-lot consistency determines polyimide molecular weight distribution. The technology is enabling geographic production dispersion without sacrificing the purity thresholds that batch crystallization historically protected.
REACH registration dossier updates under ECHA's substance evaluation program are forcing toxicological data generation for intermediate volume BPDA grades that previously relied on read-across justifications. European electronics manufacturers are now requiring updated safety data sheets and exposure scenario documentation as a condition of qualified supplier status. The policy friction most affects mid-tier polyimide compounders lacking dedicated regulatory affairs infrastructure.
Specification-driven vendor consolidation is compressing approved supplier lists as semiconductor packaging houses reduce qualification overhead by concentrating purchases among dual-source arrangements with full regulatory coverage. Direct contractual relationships between polyimide film manufacturers and dianhydride producers are displacing merchant chemical distribution in high-specification segments. The pattern is most visible in Japan, where Showa Denko and UBE Industries have anchored captive supply structures around major flexible circuit board producers.
Biphenyltetracarboxylic Dianhydride Market Segmentation
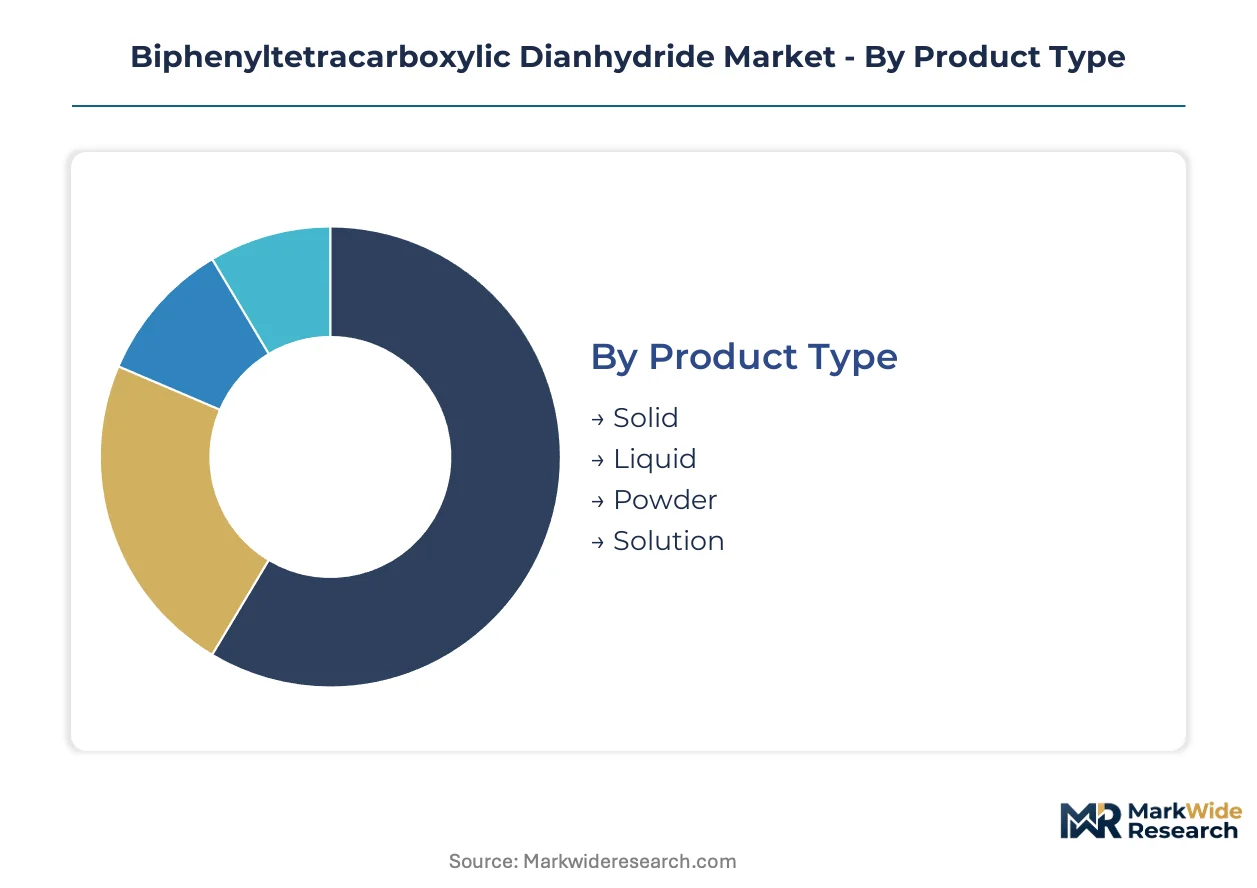
Segmentation in the Biphenyltetracarboxylic Dianhydride market reveals how specification requirements diverge across electronics-grade purity thresholds, aerospace thermal ratings, and regional regulatory compliance tiers. Understanding these divisions exposes where margin concentrates and where qualification barriers protect incumbent positions.
Product Type:
Solid BPDA dominates commercial supply chains due to superior storage stability and precise stoichiometry control during polycondensation reactions with aromatic diamines.
- Solid:Crystalline powder or flake form with sub-ppm metal ion specifications for semiconductor packaging applications. Electronics manufacturers in Japan and South Korea specify solid grades for flexible printed circuit substrate production where lot-to-lot consistency determines polyimide molecular weight distribution.
- Liquid:Molten or dissolved state requiring heated storage and specialized handling infrastructure. Aerospace composite fabricators in the United States favor liquid delivery for automated resin transfer molding of engine nacelle components, though logistics complexity limits geographic reach.
- Powder:Finely milled particulate with controlled particle size distribution for rapid dissolution in polar aprotic solvents. Coatings formulators value powder grades for spray application systems where uniform film formation depends on dissolution kinetics.
- Solution:Pre-dissolved BPDA in N-methyl-2-pyrrolidone or similar solvents, eliminating on-site dissolution steps. Adhesive compounders in European electronics supply chains specify solution forms to reduce volatile organic compound emissions during processing.
Solid leads on scale; liquid leads on momentum.
End Use Industry:
Application-specific thermal and dielectric requirements reshape procurement specifications across vertical markets.
- Electronics:Flexible printed circuit substrates, chip packaging films, and interposer laminates requiring thermal stability above 300°C. Japanese polyimide film manufacturers anchor demand for high-purity dianhydride as semiconductor packaging architectures migrate toward finer-pitch interconnects.
- Aerospace:Engine nacelle composites and thermal protection systems qualifying BPDA-based polyimides for continuous-use temperatures previously held by bismaleimide resins. United States OEM qualification programs are expanding specification windows fastest.
- Automotive:Wire insulation and under-hood components where cost pressures favor standard-grade BPDA over fluorinated alternatives. South Korean automotive electronics suppliers are qualifying polyimide films for electric vehicle power module substrates.
- Coatings:High-temperature protective finishes for industrial equipment and cookware applications. European REACH compliance requirements favor registered BPDA grades over legacy phthalic anhydride derivatives.
Electronics commands volume concentration; aerospace climbs the fastest.
Application:
Functional performance requirements determine formulation complexity and specification layering.
- Insulation:Electrical and thermal barrier applications in motors, generators, and electronic devices. Wire enamel manufacturers in China specify BPDA-based polyimide for high-voltage motor windings under evolving GB standards.
- Adhesives:High-temperature bonding systems for metal-to-substrate attachment in electronics and aerospace. Japanese adhesive compounders require ultra-low ionic content for semiconductor die-attach applications.
- Composites:Fiber-reinforced structures for structural and thermal protection uses. United States aerospace programs are qualifying unidirectional tape and fabric prepregs for engine cowl segments.
- Sealants:Gasket and barrier materials for aggressive chemical and thermal environments. Specialized grades serve semiconductor process equipment where plasma resistance complements thermal stability.
Insulation maintains installed base dominance; composites gain share fastest.
Form:
Downstream processing methods dictate physical presentation requirements.
- Film:Cast polyimide substrates for flexible circuitry and thermal management. Kapton-equivalent grades from Japanese producers set the specification benchmark for electronics applications.
- Fiber:High-tenacity filaments for composite reinforcement and protective textiles. Aerospace programs in the United States evaluate BPDA-based fibers for thermal protection system sewing threads.
- Granule:Pelletized resin for injection molding and extrusion compounding. Automotive suppliers prefer granule form for automated feeding into twin-screw extruders.
- Rod:Machinable stock shapes for prototype fabrication and small-batch component production. Research institutions and specialty equipment manufacturers utilize rod form for custom insulator fabrication.
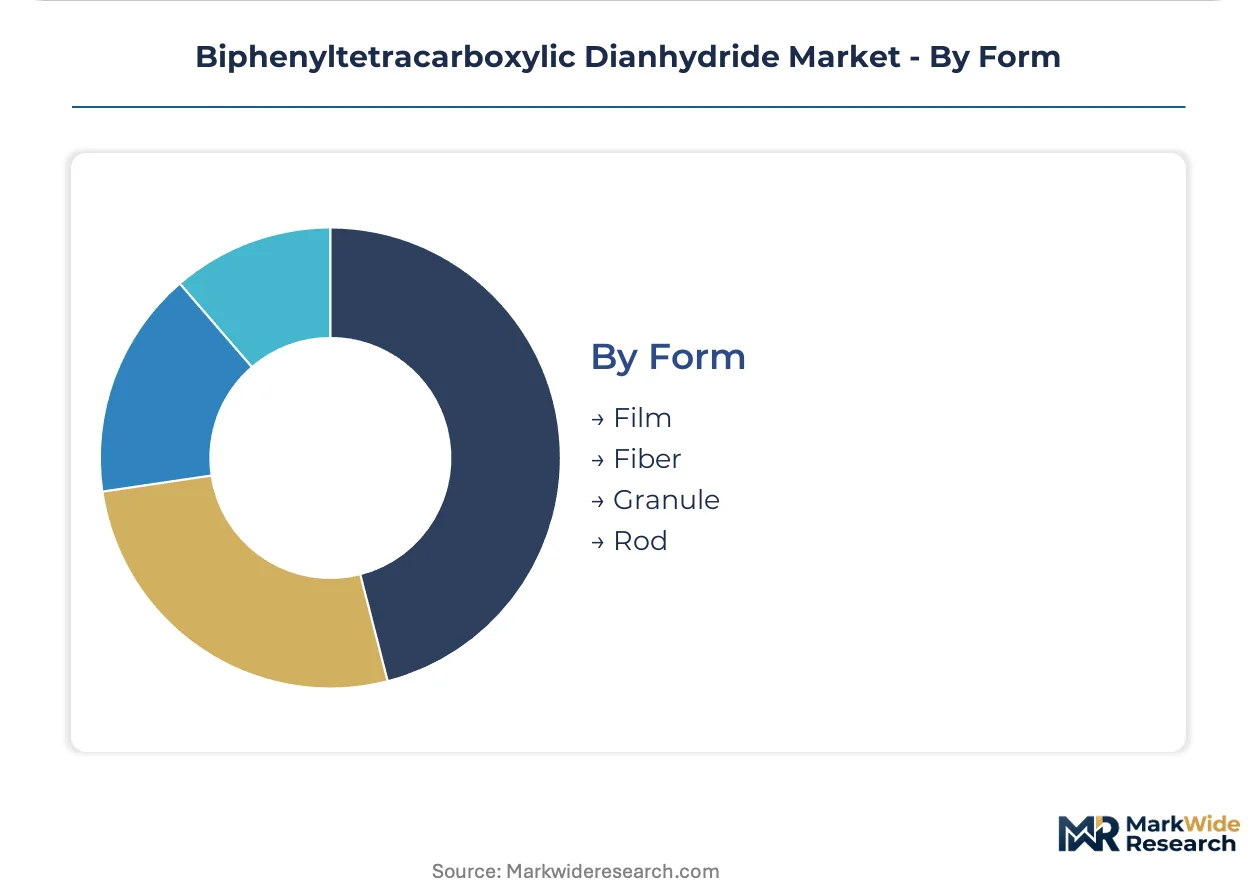
Film leads on revenue scale; fiber shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial BPDA production during the 1970s polyimide film expansion, establishing the technical specifications that electronics-grade dianhydride suppliers still reference today. The country's integrated aromatic chemical complexes seeded quality benchmarks that South Korean and Chinese producers now chase.
Japan
Flexible printed circuit substrate manufacturers in Osaka and Nagoya drive electronics-grade BPDA consumption for chip packaging laminates. METI chemical substance classification system governs manufacturing standards and emission controls for dianhydride facilities. The Chubu region around Nagoya anchors polyimide film production clusters serving semiconductor packaging houses.
United States
Aerospace OEMs in Washington and California qualify BPDA-based polyimides for engine nacelle composites requiring continuous-use temperatures above 300°C. EPA oversight under the Toxic Substances Control Act shapes import licensing and manufacturing standards for dianhydride producers. The Pacific Northwest hosts thermal protection system development programs advancing composite qualification timelines.
South Korea
Semiconductor packaging expansion in Gyeonggi Province pulls high-purity dianhydride volumes for advanced interposer production. MFDS chemical registration requirements align with international standards while maintaining domestic manufacturing oversight. The Seoul Capital Area concentrates flexible circuit board producers qualifying new BPDA supply sources.
Germany
Automotive wire enamel manufacturers specify REACH-registered BPDA grades for high-voltage electric motor windings under evolving EU Green Deal targets. ECHA persistent organic pollutant screening protocols favor established dianhydride suppliers with full toxicological dossiers. The Rhine-Ruhr industrial corridor hosts polyimide compounders serving European OEM supply chains.
China
Domestic polyimide film producers in Jiangsu and Zhejiang accelerate substitution studies favoring BPDA over legacy phthalic anhydride derivatives. MEE pollutant discharge rules under evolving GB standards tighten purity specifications for electronics manufacturing inputs. The Yangtze River Delta concentrates flexible circuit substrate fabrication capacity driving dianhydride procurement.
Biphenyltetracarboxylic Dianhydride Market Competitive Environment
Capital-heavy producers compete with asset-light formulators across the BPDA value chain. Integrated petrochemical groups with captive biphenyl feedstock command cost positions that merchant producers struggle to match. Three archetypes dominate: Japanese integrated chemical conglomerates with upstream aromatic control, European specialty chemical houses with REACH registration depth, and Indian contract manufacturers scaling through pharmaceutical-grade purification infrastructure. Competitive moves concentrate on backward integration into dimethylbiphenyl supply and qualification partnerships with polyimide film houses.
Among Japanese chemical producers, Mitsubishi Chemical Corporation and UBE Industries exemplify integrated archetypes with historical polyimide market presence. Daikin Industries occupies a differentiated position through fluorinated chemistry convergence. Merck KGaA represents European REACH-registered supply serving qualified electronics supply chains.
| Leading Market Players |
|---|
| Jiangsu Sunlight Pharmaceutical Chemicals |
| Merck KGaA |
| Mitsubishi Chemical Corporation |
| Aether Industries |
| Akron Polymer Systems |
| UBE Industries |
| SEIKA Corporation |
| Hodogaya Chemical |
| Daikin Industries |
| Others |
Value Chain & Pricing Dynamics
Captive integration into dimethylbiphenyl feedstock anchors pricing power for Japanese aromatic chemical producers, insulating them from volatility that compresses margins for merchant dianhydride converters lacking upstream control.
Pricing Analysis
Three-tier pricing structure across electronics-grade, aerospace-grade, and industrial-grade levels separates specification tolerances by metal ion content and thermal stability certification. Price differentiation hinges on sub-ppm purity thresholds and REACH registration completeness. Cost compression in standard industrial grades is intensifying because Chinese polyimide compounders are qualifying domestic BPDA sources. Merchant chemical buyers in European coatings applications exhibit highest price sensitivity; semiconductor packaging houses in Japan show least sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Direct contractual channels between dianhydride producers and polyimide film manufacturers displace merchant distribution in high-specification segments. Supply concentrates in Japan, South Korea, and China for electronics-grade output, with the United States anchoring aerospace qualification programs. Raw material flows draw from dimethylbiphenyl, catalytic oxidation catalysts, and specialized crystallization solvents. Single-source vulnerability concentrates around Japanese aromatic feedstock producers, exposing downstream converters to allocation risk during upstream maintenance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where semiconductor packaging architectures are migrating toward finer-pitch interconnects that compress specification tolerances and favor incumbent suppliers with validated process control.
For Market Incumbents: Hedge against fluorinated dianhydride substitution by deepening captive supply of upstream biphenyl feedstock and accelerating co-development programs with semiconductor packaging houses. Prioritize certification investment in India's PLI scheme windows before qualification timelines harden. For New Entrants and Emerging Players: Enter via pharmaceutical-grade purification infrastructure repurposed for electronics-grade BPDA output, targeting India's underpenetrated semiconductor packaging supply chain. White-space concentrates in technical service capacity for flexible circuit board producers seeking dual-source arrangements outside Japanese supply clusters. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory dossier maintenance costs exceed standalone returns for mid-scale producers lacking dedicated toxicology teams. Long-term viability favors integrated aromatic chemical groups with backward control over dimethylbiphenyl and established REACH registration depth. The signal to watch is qualification campaign acceleration by Chinese polyimide film producers seeking non-Japanese supply sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dimethylbiphenyl | Captive feedstock supply insulates Mitsubishi Chemical and UBE Industries from aromatic chemical price volatility. |
| Electronics-Grade Capacity Expansion | Specialized crystallization trains for sub-ppm metal ion removal address semiconductor packaging qualification requirements. |
| REACH Registration Dossier Updates | ECHA substance evaluation compliance preserves qualified supplier status for European electronics supply chains. |
| Fluorinated Polyimide Co-Development | Daikin Industries leverages perfluorinated diamine coupling to capture dielectric constant-sensitive packaging segments. |
| India Technical Service Localization | PLI scheme qualification windows favor first movers establishing local application support for semiconductor packaging houses. |
Study Parameters
Direct dialogue with polyimide film procurement managers, dianhydride plant operations directors, semiconductor packaging material scientists, and REACH regulatory affairs specialists grounded qualitative findings. Secondary validation drew from customs trade data, Japanese chemical industry association reports, ECHA registration dossiers, and SEC filings by listed aromatic chemical producers. Bottom-up volume estimates triangulated against top-down electronics-grade polyimide consumption models.
Bottom-up modeling segmented the market by purity grade, end-use industry, and regional production hub across the projection horizon. CAGRs derived from elasticity-adjusted demand projections for flexible printed circuit substrates and aerospace thermal protection systems. Industry-specific inputs included semiconductor packaging architecture migration timelines and OEM qualification cycle durations.
The model holds under stable dimethylbiphenyl supply availability and continued REACH registration validity; deviation in feedstock allocation crises or ECHA persistent organic pollutant redesignation would shift volume trajectories. Forecasts reflect these base assumptions and acknowledge that regulatory friction or substitution breakthroughs in fluorinated chemistries could accelerate supplier consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Iscotrizinol Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Pyrimidine Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Desalination Chemicals Market
Chemicals
Calcium Hydroxide Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Paint Remover Market
Chemicals
Global Lactate Salts Market