
 Solar Backsheet Films Market | 2026-2036
Solar Backsheet Films Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Backsheet Films Market Analytics
Fluorinated polymer is shifting toward coating-extrusion hybrids as module manufacturers target levelized cost reductions without sacrificing weatherability. DuPont de Nemours, Inc. leverages its Tedlar film heritage to sustain premium positioning in utility-scale projects. Arkema competes through Kynar PVDF chemistry leadership in high-humidity climates. Krempel GmbH anchors European supply with localized lamination expertise.
Solar backsheet films are multilayer barrier structures, typically 250–350 μm thick, that electrically insulate photovoltaic modules while blocking moisture and UV degradation. Polyester formulations dominate cost-sensitive installations where thermal stability requirements are moderate. Polyvinyl fluoride maintains margin concentration in premium utility contracts demanding decades-long field performance. Building Integrated Photovoltaics applications are expanding fastest as architectural codes mandate dual-function building envelopes.
FDA maintains indirect food-contact standards for agricultural solar installations where backsheet films interface with crop processing. EPA regulates fluoropolymer emissions during manufacturing, pushing producers toward water-based coating alternatives. China's MEE enforces dual carbon compliance thresholds that favor low-fluorine backsheet architectures. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions in Europe and North America reshape material qualification pathways and supplier certification requirements.
Market Dynamics
Fluoropolymer-to-coating-extrusion technology migration is compressing traditional laminated backsheet margins while redistributing competitive advantage toward integrated film-coating capabilities. China's dual carbon enforcement and NMPA-aligned quality standards are accelerating this structural transition.
Growth Catalysts
- Utility-scale reliability mandates:Power purchase agreements now specify 30-year module lifespans, driving specification upgrades toward fluorinated barriers in desert and coastal installations.
- China's dual carbon compliance:MEE enforcement thresholds favor low-fluorine coating-extrusion architectures over conventional PVDF lamination in Jiangsu and Zhejiang manufacturing clusters.
- Building Integrated Photovoltaics codes:Architectural dual-function envelope requirements in Germany and California are opening specification pathways for colored and transparent backsheet variants.
Market Restraints
- Fluoropolymer feedstock concentration:PVDF resin supply concentrates among limited chemical producers, exposing backsheet manufacturers to input cost volatility and allocation constraints.
- ECHA per- and polyfluoroalkyl substance restrictions:REACH regulatory friction is forcing reformulation investments and disqualifying legacy fluorinated films from European utility tenders.
- Glass-glass module substitution:Bifacial solar architectures with frameless glass rear barriers are displacing polymer backsheet demand in premium utility segments.
Strategic Opportunities
- Agrivoltaic agricultural solar:FDA indirect food-contact compliance requirements for crop-adjacent installations create certified backsheet specification premiums in California and Spain.
- Water-based coating technology:EPA fluoropolymer emission regulations are accelerating aqueous fluoropolymer dispersion adoption, enabling non-laminated production cost structures.
- Floating solar expansion:Humidity-resistant Kynar PVDF and Tedlar formulations are penetrating reservoir and coastal installations where moisture ingress tolerance exceeds standard polyester capabilities.
Industry Challenges
- Cross-functional coating-extrusion expertise:Conventional lamination engineers lack fluid handling and thin-film coating process knowledge, constraining technology transition velocity.
- Multi-jurisdiction certification timelines:Simultaneous UL, IEC, and GB standard qualification cycles extend product launch schedules by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Backsheet Films Market |
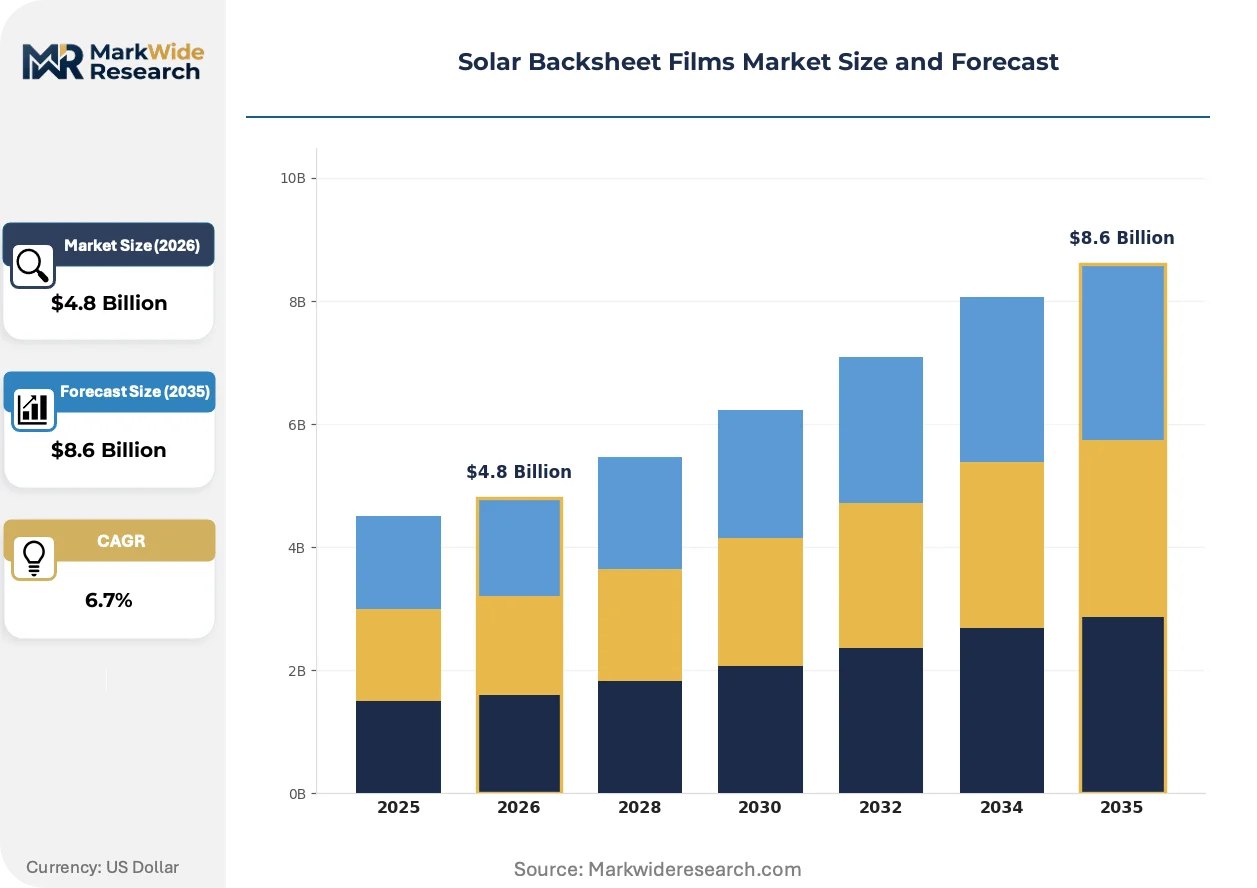
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyester, Polyvinyl Fluoride, Polyamide, Ethylene Vinyl Acetate Thickness: 100 μm, 200 μm, 300 μm, 400 μm End User: Residential, Commercial, Industrial, Utility Application: Building Integrated Photovoltaics, Solar Modules, Off-grid Systems, Agricultural Applications |
| Companies Covered | DuPont de Nemours, Inc., COVEME s.p.a., Arkema, 3M, Krempel GmbH, Targray Technology International Inc., Jolywood (Suzhou) Sunwatt Co., Ltd., Cybrid Technologies Inc., Taiflex Scientific Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Backsheet Films Market Evolving Landscape
Coating-extrusion hybrid manufacturing is displacing conventional lamination as the dominant production architecture. This shift compresses capital intensity while enabling material flexibility for application-specific formulations.
Coating-extrusion hybrid technology applies fluoropolymer dispersions directly onto PET substrates through precision slot-die or roll-to-roll processes. Module manufacturers in China's Yangtze River Delta are adopting these films at accelerating rates for distributed generation projects. The technology is expanding into utility-scale procurement specifications previously reserved for premium laminated constructions.
Europe's F-Gas Regulation and ECHA restriction proposals are systematically reducing permissible fluorinated greenhouse gas emissions across chemical processing. Industrial consequence includes forced phase-out of certain fluoropolymer synthesis pathways and accelerated water-based formulation development. High-humidity coastal installations in Southern Europe are most affected, with project developers now requiring REACH-compliant material certifications in tender documentation.
Buyer concentration among tier-one module manufacturers is consolidating specification authority and compressing supplier qualification cycles. Long-tail distributors and regional integrators are losing influence as direct procurement from film-coating integrated producers displaces layered distribution. This pattern is most visible in India's PLI-linked manufacturing expansion, where domestic content requirements favor vertically qualified local suppliers over import-dependent trading networks.
Solar Backsheet Films Market Segmentation
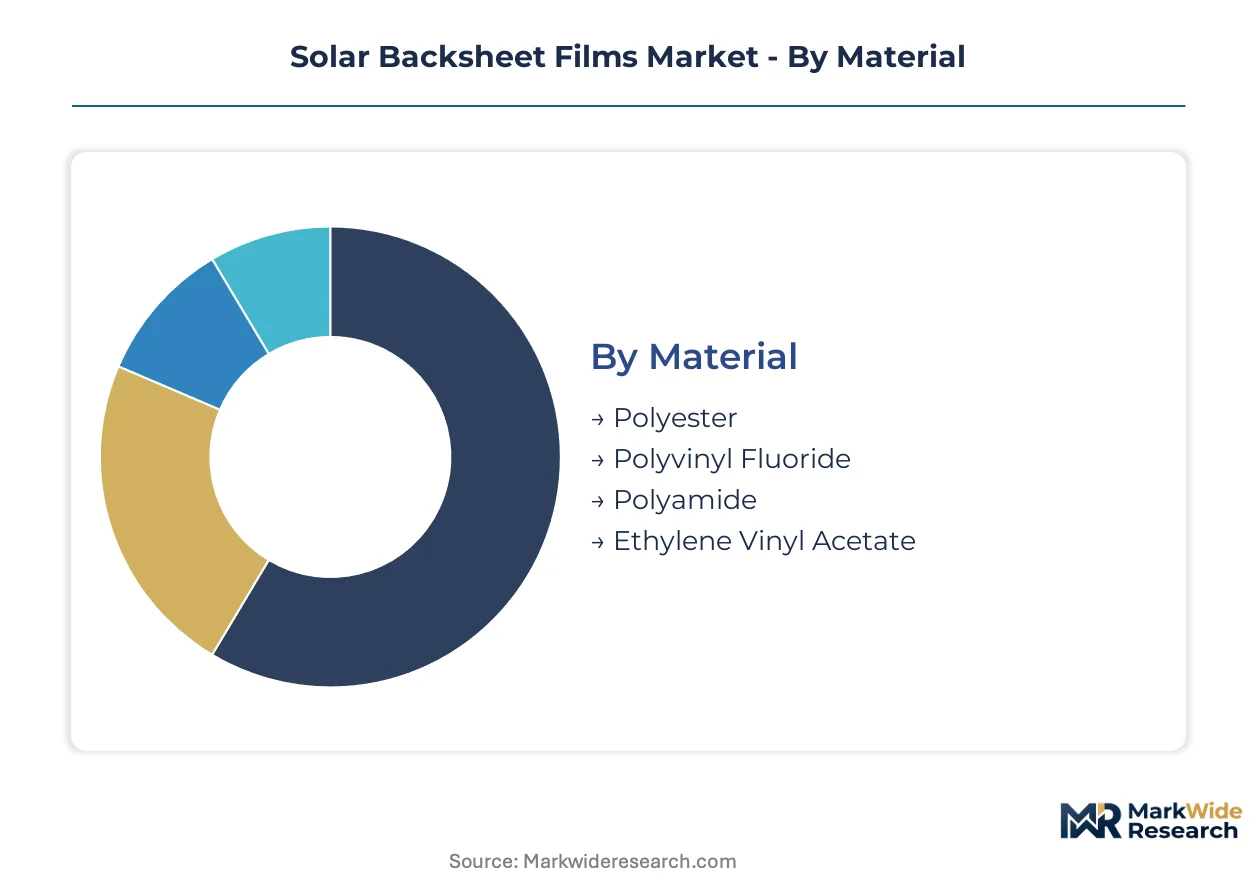
Backsheet film specifications diverge sharply between cost-optimized distributed generation and reliability-critical utility installations. Material selection and thickness calibration determine module warranty terms, manufacturing yield, and field failure rates across climate zones.
Material:
Integration depth separates standalone fluoropolymer films from coating-extrusion hybrids that embed barrier functions within composite architectures.
- Polyester:PET-based formulations deliver baseline electrical insulation and moisture protection at the lowest unit cost. Demand clusters in China's Jiangsu distributed manufacturing corridor where module assemblers prioritize bill-of-material compression over extended warranties.
- Polyvinyl Fluoride:PVF chemistry provides superior UV resistance and hydrolytic stability for desert and coastal utility arrays. Procurement concentrates in premium power purchase agreements specifying 30-year performance guarantees in California and Saudi Arabia.
- Polyamide:PA substrates offer intermediate thermal stability for mid-tier commercial installations. European module manufacturers specify these for rooftop systems with 20-25 year design lives.
- Ethylene Vinyl Acetate:EVA-compatible backsheet variants integrate directly with encapsulant layers, reducing lamination cycle complexity. Adoption is climbing fastest in automated production lines across India's PLI-qualified manufacturing bases.
Polyester leads volumes today; Polyvinyl Fluoride is gaining share fastest in warranty-extended utility procurement.
Thickness:
Cost tier alignment maps thickness selection to module price positioning and climate exposure severity.
- 100 μm:Ultra-thin constructions minimize material consumption for cost-constrained emerging market distributed systems. Specifications dominate Southeast Asian residential rooftop segments where installation labor cost ratios outweigh material durability premiums.
- 200 μm:Standard-thickness films balance mechanical robustness and material efficiency. Procurement volumes concentrate in European commercial building installations governed by IEC 61215 certification requirements.
- 300 μm:Heavy-gauge constructions provide enhanced puncture resistance for utility-scale field handling. Demand localizes in Middle Eastern desert installations where sand abrasion and thermal cycling stress thinner alternatives.
- 400 μm:Maximum-thickness specifications serve extreme-environment off-grid and agricultural solar where maintenance access is limited. Penetration is climbing most quickly in Australian remote mining and African irrigation-powered installations.
200 μm thickness commands the largest procurement volumes; 400 μm specifications are expanding most quickly in extreme-climate segments.
End User:
Customer type determines specification authority concentration and procurement channel structure.
- Residential:Distributed rooftop systems favor standardized polyester backsheets through installer-channel distribution. Procurement fragmentation across thousands of local integrators limits supplier pricing power.
- Commercial:Mid-scale building installations balance cost and warranty terms through engineering-procurement-construction contractor specifications. Demand concentrates in German and Japanese commercial real estate retrofits.
- Industrial:C&I self-consumption projects prioritize reliability for operational continuity. Specifications favor fluoropolymer barriers in food processing and pharmaceutical manufacturing adjacencies where downtime costs dominate material premiums.
- Utility:Centralized solar farms exercise consolidated procurement power through tier-one module manufacturer direct relationships. China's state-owned developers and Middle Eastern sovereign wealth vehicles drive qualification standards.
Utility end users generate the largest revenue concentration; Industrial procurement is climbing fastest as energy-intensive manufacturing decarbonizes.
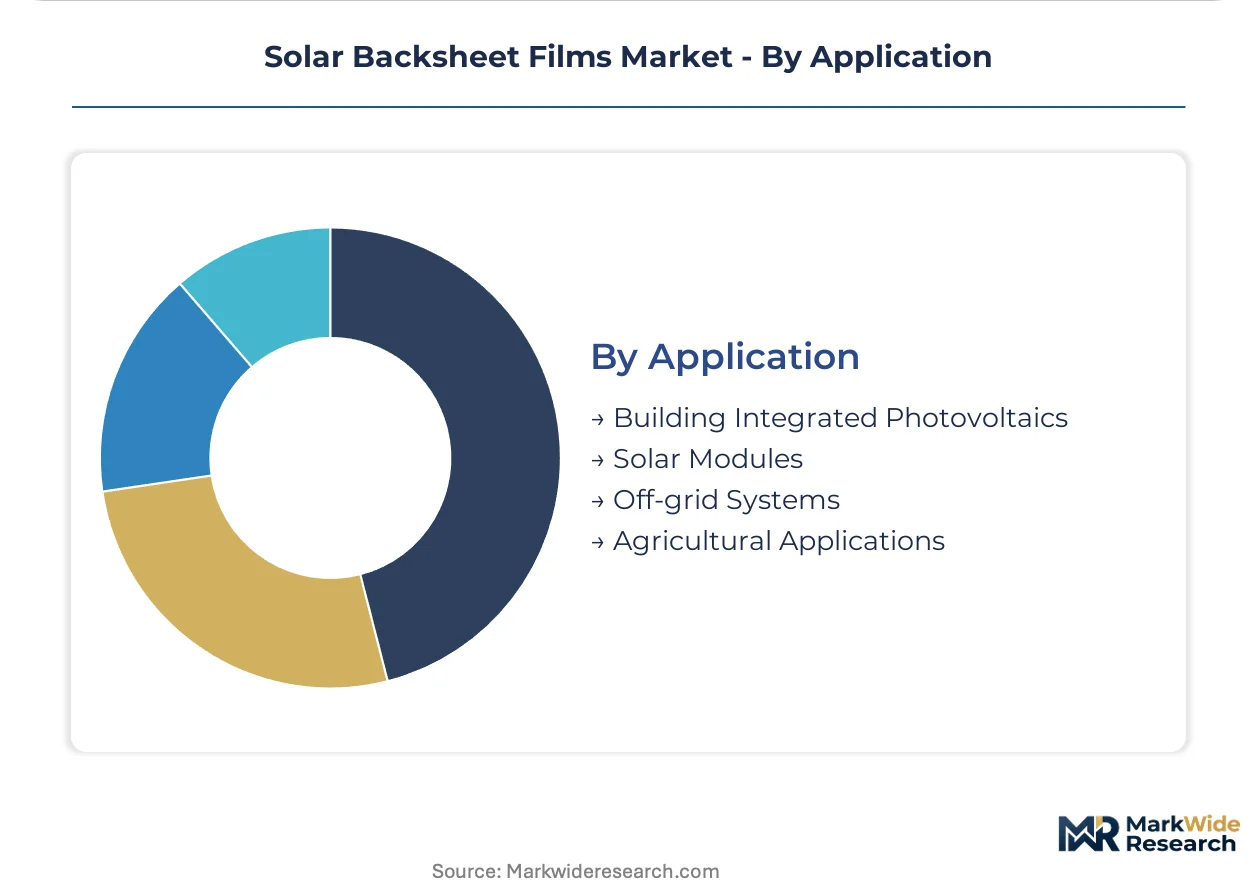
Application:
Functional requirements reshape material selection across module configuration and deployment context.
- Building Integrated Photovoltaics:Architectural integration demands colored, transparent, and patterned backsheet variants. German and California building codes are accelerating specification of aesthetic-functional dual-purpose films.
- Solar Modules:Conventional framed installations represent the baseline volume application. Technology migration from laminated to coating-extrusion production is compressing cost structures across all material grades.
- Off-grid Systems:Remote power applications prioritize durability over efficiency optimization. Procurement localizes in Sub-Saharan African mini-grid and Latin American rural electrification programs.
- Agricultural Applications:Agrivoltaic installations require FDA-compliant indirect food-contact certification for crop-adjacent deployment. Specification premiums are emerging in California Central Valley and Spanish Almería greenhouse complexes.
Solar Modules anchor current procurement volumes; Building Integrated Photovoltaics is expanding most quickly as architectural codes mandate dual-function envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang manufacturing clusters anchor global backsheet film supply chains. China's dual carbon enforcement and NMPA-aligned quality standards accelerate fluoropolymer-to-coating-extrusion technology migration. Module assembly capacity concentrates in the Yangtze River Delta where tier-one producers source qualified films directly.
China
Utility-scale reliability mandates and state-owned developer procurement specifications drive fluorinated barrier demand. MEE enforces dual carbon compliance thresholds favoring low-fluorine coating-extrusion architectures. Suzhou and Hefei host integrated film-coating facilities supplying Jiangsu module assembly corridors.
United States
Thirty-year power purchase agreement terms and desert utility installations elevate premium backsheet specifications. EPA fluoropolymer emission regulations push producers toward water-based coating alternatives. California's Central Valley agricultural solar complexes require FDA indirect food-contact certified films for crop-adjacent deployment.
Germany
Building Integrated Photovoltaics codes mandate dual-function architectural envelopes with colored and transparent backsheet variants. ECHA per- and polyfluoroalkyl substance restrictions under REACH force reformulation investments and disqualify legacy fluorinated films. Bavarian module manufacturers specify REACH-compliant materials for European utility tenders.
India
PLI-linked manufacturing expansion and domestic content requirements favor vertically qualified local suppliers over import-dependent trading networks. BIS certification and CEA grid integration standards shape qualification timelines. Gujarat and Tamil Nadu module assembly bases source standardized polyester backsheets through direct procurement channels.
Saudi Arabia
Desert utility-scale installations with sand abrasion and thermal cycling stress drive heavy-gauge 300-400 μm backsheet specifications. Sovereign wealth vehicle procurement consolidates specification authority through tier-one module manufacturer relationships. NEOM and Riyadh industrial zones concentrate module assembly capacity for Middle Eastern solar deployment.
Solar Backsheet Films Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit lamination lines for coating-extrusion hybrid production. The vendor base separates into integrated chemical-film producers, specialized coating technology developers, and regional lamination specialists. Three archetypes define competitive positioning: heritage fluoropolymer suppliers leveraging chemistry depth, Asian integrated producers capturing scale economies, and European specialists anchoring localized certification expertise. Technology licensing and strategic partnerships represent the dominant competitive moves as conventional lamination engineers acquire fluid handling capabilities.
Among heritage chemical suppliers, DuPont de Nemours, Inc. and Arkema occupy positions defined by fluoropolymer chemistry leadership. Krempel GmbH represents the European specialist archetype with localized lamination expertise. These three entities exemplify how competitive advantage redistributes toward integrated film-coating capabilities as coating-extrusion hybrid manufacturing displaces conventional lamination architectures.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| COVEME s.p.a. |
| Arkema |
| 3M |
| Krempel GmbH |
| Targray Technology International Inc. |
| Jolywood (Suzhou) Sunwatt Co., Ltd. |
| Cybrid Technologies Inc. |
| Taiflex Scientific Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Captive integration into fluoropolymer resin production anchors pricing power for heritage chemical suppliers while compressing margins for standalone laminators dependent on spot resin markets. DuPont's Tedlar and Arkema's Kynar vertical positions insulate against PVDF feedstock volatility that destabilizes coating-extrusion pure-plays in China's Yangtze River Delta manufacturing corridor.
Pricing Analysis
PVDF resin pass-through clauses in long-term supply contracts expose backsheet manufacturers to quarterly renegotiation cycles when fluoropolymer feedstock concentrates among limited chemical producers. Pricing stratifies across premium fluorinated barriers for 30-year utility warranties, standard PET constructions for distributed generation, and economy-grade coating-extrusion hybrids for cost-constrained emerging markets. Cost compression in the polyester tier intensifies as Chinese module assemblers prioritize bill-of-material reduction over extended warranties. Residential rooftop installers exhibit highest price sensitivity; utility-scale state-owned developers accept material premiums for reliability guarantees.
Supply Chain Analysis
Regional distribution centers in Suzhou and Hefei feed Jiangsu module assembly corridors through hub-and-spoke logistics optimized for just-in-time lamination cycles. Manufacturing gravity centers on China, with secondary concentration in Germany and the United States for REACH-compliant and FDA-certified specialty production. Raw material flows draw from fluoropolymer resin synthesis in Japan and the United States, PET substrate production in China and South Korea, and adhesive formulation in Germany. Single-source vulnerability concentrates in PVDF resin allocation from limited chemical producers. Distribution runs through direct procurement channels from tier-one module manufacturers, displacing layered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by utility-scale procurement shifts toward 30-year performance guarantees that disqualify cost-optimized polyester constructions.
For Market Incumbents: Deepen captive fluoropolymer resin positions to defend against glass-glass module substitution threatening premium laminated backsheet demand. Expand coating-extrusion capacity in Jiangsu and Zhejiang clusters to capture dual carbon compliance premiums from MEE enforcement. Prioritize REACH certification investments to maintain European utility tender eligibility as ECHA restrictions phase out legacy fluorinated formulations. For New Entrants and Emerging Players: Tier-two module manufacturers in India's PLI-linked expansion represent the most penetrable channel partner type for coating-extrusion technology licensing. Target agrivoltaic agricultural solar in California Central Valley and Spanish Almería where FDA indirect food-contact certification creates specification premiums with limited qualified suppliers. Pursue white-label coating partnerships with established PET substrate producers to bypass capital-intensive resin synthesis barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional lamination specialists with localized certification expertise because multi-jurisdiction UL, IEC, and GB qualification timelines extend product launch schedules by 18-24 months, creating defensive moats against pure-technology entrants. Long-term viability hinges on coating-extrusion hybrid capabilities displacing conventional lamination architectures. Watch for inflection when water-based fluoropolymer dispersion adoption crosses critical mass in EPA-regulated manufacturing bases.| Strategic Initiative | Industry Significance |
|---|---|
| Coating-Extrusion Capacity Expansion | Captures MEE dual carbon compliance premiums in Jiangsu manufacturing clusters. |
| Backward Integration into PVDF Resin | Insulates Arkema and DuPont against feedstock allocation constraints from limited chemical producers. |
| REACH-Compliant Reformulation Investment | Preserves European utility tender eligibility as ECHA restrictions disqualify legacy fluorinated films. |
| Agrivoltaic Certification Program | Opens FDA indirect food-contact specification premiums in California Central Valley crop-adjacent installations. |
| Water-Based Coating Technology Licensing | Enables non-laminated production cost structures under EPA fluoropolymer emission regulations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with module manufacturer procurement directors, fluoropolymer resin plant managers, EPC contractor specification engineers, and regulatory affairs leads at backsheet producers with secondary validation. Secondary sources included customs and trade data from Chinese and Indian port authorities, SEC 10-K filings from heritage chemical suppliers, IEC certification databases, and MEE dual carbon compliance disclosure records. Bottom-up module assembly capacity estimates triangulated against top-down fluoropolymer resin consumption figures.
Comparable-period anchoring linked projection assumptions to historical reference periods across the modeling period, with CAGR derivation reflecting segment-specific growth differentials. Segmentation dimensions modeled included material chemistry tier, thickness specification, end-user procurement authority concentration, and application functional requirements. Forecast inputs incorporated coating-extrusion technology adoption curves, glass-glass module penetration rates, and regulatory phase-out timelines for fluorinated formulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA restriction finalization, glass-glass bifacial module cost parity achievement, and PVDF resin supply concentration disruptions. Forecasts reflect documented assumptions around technology migration velocity and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
United States Microspheres Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Hornbeam Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Specialty Silica Market