
 Flexible Colored Polyurethane (PU) Foams Market | 2026-2036
Flexible Colored Polyurethane (PU) Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Colored Polyurethane (PU) Foams Market Analysis
Furniture manufacturers are bifurcating from commodity white foam buyers toward specification-driven colored foam purchasers seeking brand differentiation and design flexibility. Covestro AG leverages its upstream polyol capabilities to secure feedstock cost advantages across European production hubs. Wanhua Chemical Group anchors volume supply through integrated MDI manufacturing complexes in Ningbo and Yantai. Huntsman Corporation differentiates via specialty catalyst formulations that enable precise color matching and UV stability in automotive seating grades.
Flexible colored polyurethane foams are thermoset cellular polymers produced by reacting polyols with isocyanates in the presence of colorants, surfactants, and blowing agents, yielding open-cell or closed-cell structures with densities typically ranging from 15 to 80 kg/m³; these materials provide cushioning, thermal insulation, and aesthetic surface finishing across consumer and industrial products. High resilience foams command premium positioning in bedding and seating where durability standards exceed 80,000 double rubs, while reaction injection molding segments serve automotive interior panels requiring complex geometries and integrated color. Open cell structures dominate furniture and bedding applications where breathability and compression set recovery determine specification compliance, whereas closed cell variants serve insulation end uses demanding moisture resistance and dimensional stability.
EPA oversees VOC emissions from foam curing operations under Clean Air Act Title V permitting, while REACH restricts aromatic amines and heavy metal pigments in EU-sourced foams, and China's MEE implements dual carbon goals that elevate energy efficiency mandates for polyol production facilities. California's Department of Toxic Substances Control maintains flammability labeling requirements that shape formulation choices for products entering North American distribution channels. Stakeholders must monitor evolving chemical disclosure rules across multiple jurisdictions while assessing captive pigment compounding capabilities against outsourced color masterbatch supply alternatives.
Market Dynamics
Automotive OEM procurement patterns are restructuring supplier relationships as interior trim specifications migrate from commodity white foam to color-matched, UV-stable formulations requiring captive pigment compounding capabilities and just-in-time delivery contracts.
Growth Catalysts
- REACH aromatic amine restrictions:European formulators are accelerating reformulation investments to eliminate restricted pigments, creating premium positioning for compliant colored foam producers with certified supply chains.
- Reaction injection molding adoption:Automotive interior panel manufacturers are specifying complex-geometry colored foams that integrate directly with dashboard and door trim assemblies, compressing assembly steps.
- Ningbo-Yantai production cluster concentration:Integrated MDI-polyol manufacturing complexes in China are capturing cost advantages that downstream foam converters leverage for export competitiveness.
Market Restraints
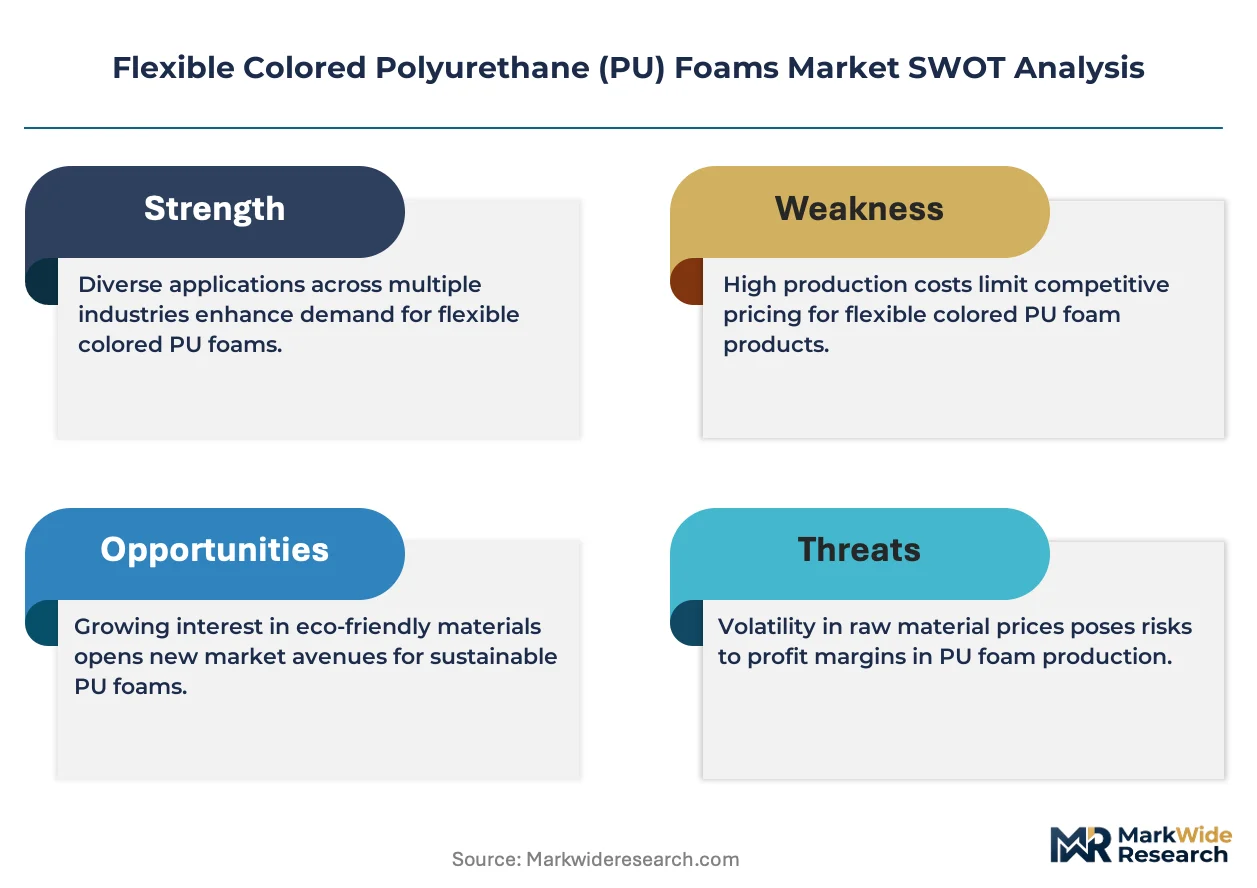
- MDI feedstock volatility:Isocyanate price swings tied to benzene and crude oil movements compress foam converter margins and destabilize annual contract negotiations with furniture OEMs.
- European supply concentration:Polyol production gravity centers on German and Belgian chemical complexes, exposing downstream foam fabricators to single-source disruption risks and logistics bottlenecks.
- Natural latex substitution:Bedding manufacturers in premium segments are pivoting toward plant-based foam alternatives for sustainability positioning, displacing conventional PU volumes in mattress cores.
Strategic Opportunities
- India furniture manufacturing expansion:Domestic upholstery production scaling under PLI scheme incentives is creating first-mover advantages for colored foam suppliers establishing local compounding operations.
- UV-stable automotive seating grades:Precision color-matching capabilities enabling 10-year fade resistance specifications are opening specification-locked supply relationships with luxury vehicle programs.
- Digital color matching platforms:Spectrophotometer-integrated formulation software is collapsing sample-to-production cycles from weeks to days, enabling made-to-order batch economics for mid-volume furniture accounts.
Industry Challenges
- Pigment dispersion chemistry expertise:Formulators with legacy white-foam backgrounds lack competency in masterbatch compatibility and cell-structure preservation during colorant integration.
- Dual carbon compliance timelines:Chinese polyol facilities face compressed deadlines for MEE energy efficiency audits and carbon intensity disclosures that require capital-intensive process upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Colored Polyurethane (PU) Foams Market |
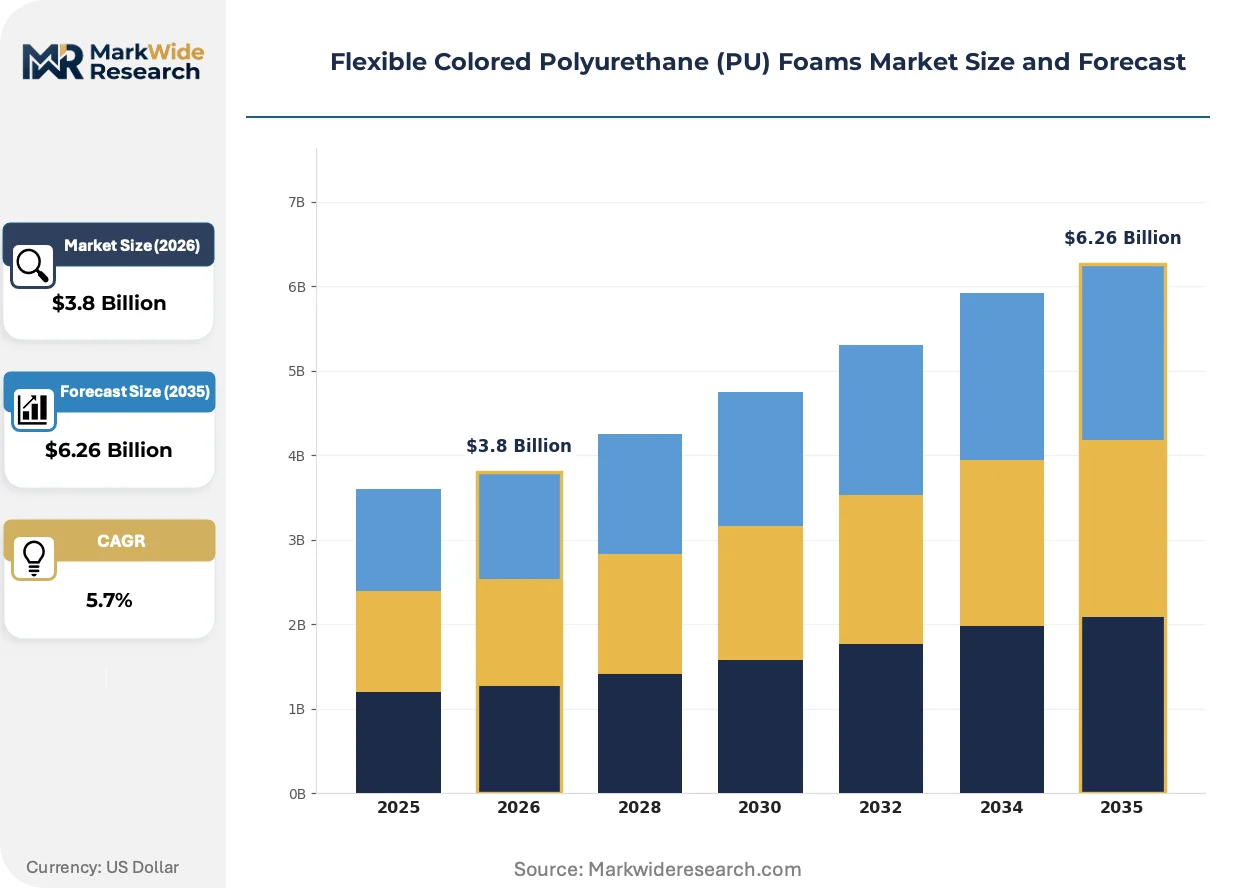
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell, Closed Cell, High Resilience, Reaction Injection Molding Application: Furniture, Automotive Interiors, Insulation, Bedding End User: Furniture Manufacturers, Automotive OEMs, Construction, Bedding Producers Color Type: Solid Colors, Transparent, Metallic, Custom Patterns |
| Companies Covered | Covestro AG, BASF SE, Wanhua Chemical Group Co., Ltd., Dow Inc., Huntsman Corporation, Rogers Corporation, Saint-Gobain Performance Plastics, Sekisui Chemical Co., Ltd., Recticel NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Colored Polyurethane (PU) Foams Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to redefine competitive advantage in colored foam supply, with sustainability certification and digital manufacturing integration emerging as primary differentiation vectors.
Bio-based polyol feedstocks derived from soybean oil and castor oil are fragmenting the raw material sourcing landscape as automotive seating suppliers seek mass-balance certified inputs to satisfy Scope 3 reporting requirements. Tier 1 seat manufacturers in Germany and the US are qualifying these alternatives for production volumes. The technology is fragmenting supply relationships away from petroleum-dependent chemical majors toward agricultural-integrated processors with certified traceability systems.
REACH restrictions on heavy metal pigments and aromatic amines are forcing systematic reformulation across EU-sourced foam production, with ECHA substance evaluation processes extending compliance timelines. Formulators are substituting organic pigment alternatives and inorganic complex colorants that meet migration limits in skin-contact applications. Children's furniture and automotive interior segments are absorbing the highest compliance costs and extending qualification cycles with OEM customers.
Furniture manufacturers are consolidating supplier relationships around full-service color matching and inventory management partnerships that displace transactional spot purchasing. Large-format upholstery producers in China and Italy are negotiating vendor-managed inventory agreements with foam converters who maintain finished-goods buffers at manufacturing plants. This pattern is most pronounced in high-velocity sofa manufacturing clusters where design-to-floor cycles have compressed below eight weeks.
Flexible Colored Polyurethane (PU) Foams Market Segmentation
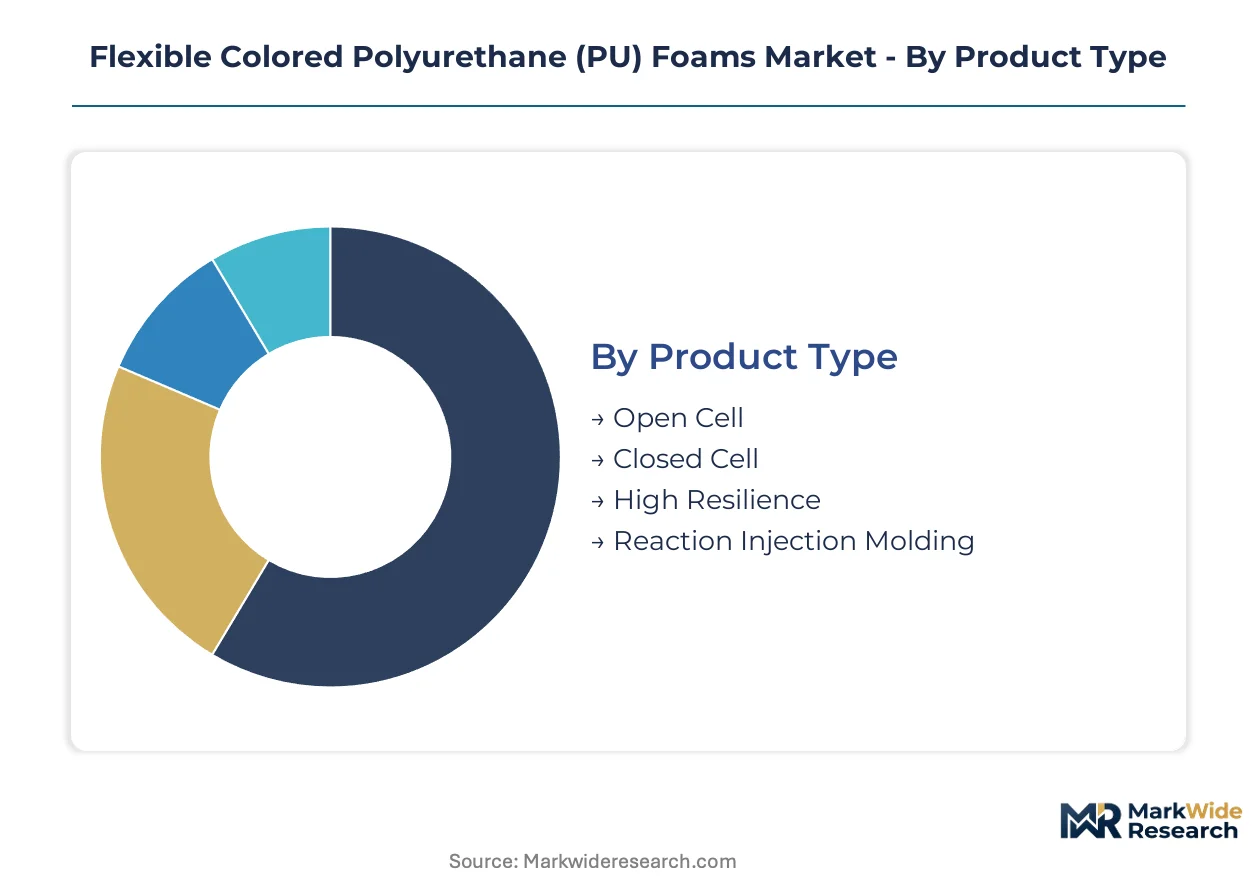
Segmentation in colored PU foams reveals divergent margin structures across cellular architectures and color complexity tiers. Procurement patterns vary sharply between specification-driven automotive contracts and volume-driven furniture spot purchasing.
Product Type:
Geographic demand concentration separates domestic consumption patterns from export-oriented specialty grades.
- Open Cell:Permeable cellular structure with interconnected voids enables moisture vapor transmission and rapid compression set recovery. Chinese furniture clusters in Dongguan and Foshan absorb the majority of export volumes for sofa cushioning applications.
- High Resilience:Modified polyol formulations with increased ethylene oxide content yield superior support factor and durability exceeding 80,000 double rubs. North American bedding producers specify these grades for premium mattress cores where 10-year warranty terms mandate performance retention.
- Closed Cell:Discontinuous cellular architecture provides moisture resistance and dimensional stability for insulation boards. European construction retrofits drive specification compliance with REACH flame retardant thresholds.
- Reaction Injection Molding:Low-pressure processing enables complex geometry integration with in-mold coloration for automotive trim panels. German and US automotive Tier 1s dominate procurement of these system-dependent grades.
Open cell commands the established base. The steepest expansion runs through high resilience grades.
Application:
Cost tier differentiation separates commodity upholstery from premium automotive interior specifications.
- Furniture:Sofa and chair cushioning represents the volume anchor, with Italian and Chinese manufacturers driving specification diversity across velvet-matched and leather-toned color palettes.
- Automotive Interiors:Dashboard padding, door panels, and headliners require UV-stable formulations with 10-year fade resistance certification. German luxury OEMs enforce the most stringent color tolerances.
- Insulation:Closed cell variants serve building envelope applications where thermal conductivity ratings determine bid compliance. Scandinavian energy code upgrades are accelerating specification shifts.
- Bedding:Mattress toppers and core layers prioritize pressure distribution and breathability. US and European producers are qualifying bio-based polyol alternatives for sustainability positioning.
Furniture maintains the volume foundation. Automotive interiors deliver the fastest margin expansion.
End User:
Customer type determines contract structure, with captive pigment compounding requirements separating automotive from furniture procurement.
- Furniture Manufacturers:High-velocity upholstery producers in China and Italy negotiate vendor-managed inventory with just-in-time color matching. Design-to-floor cycles below eight weeks compress supplier qualification timelines.
- Automotive OEMs:Tier 1 seat and trim suppliers enforce system house partnerships with locked formulation access. German and US programs dominate premium colored foam specification.
- Construction:Insulation contractors prioritize cost-per-thermal-unit metrics over aesthetic coloration, limiting colored foam penetration to architectural exposed applications.
- Bedding Producers:Mattress OEMs are bifurcating between commodity white cores and specification-driven colored comfort layers for direct-to-consumer branding differentiation.
Furniture manufacturers anchor volume demand. Automotive OEMs drive the steepest specification escalation.
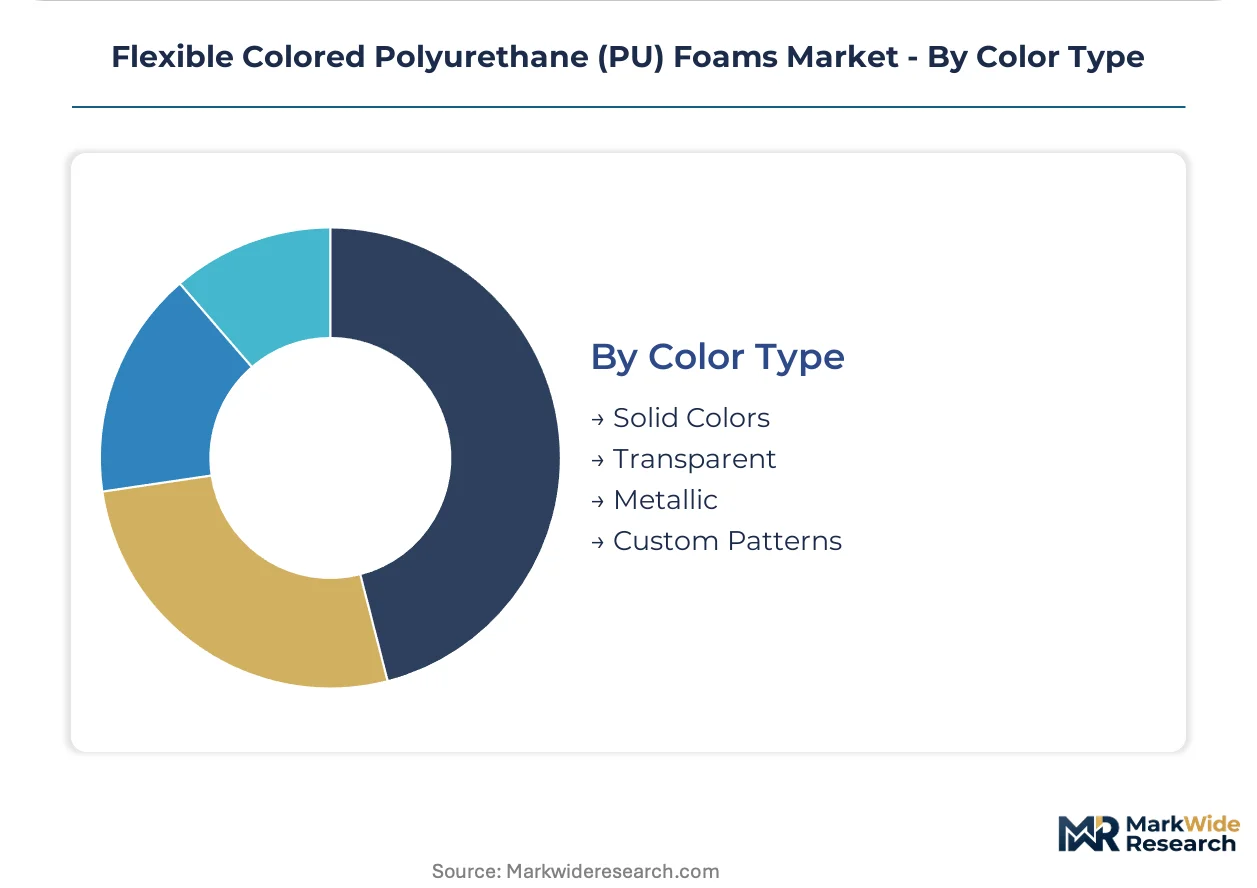
Color Type:
Margin structure escalates with color complexity, from standardized pigment loads to custom pattern development.
- Solid Colors:Standard pigment dispersions in primary and secondary hues serve high-volume furniture applications with minimal batch-to-batch variation requirements.
- Custom Patterns:Multi-tone effects and geometric designs demand specialized mixing head technology and extended formulation development. Italian luxury furniture producers commission exclusive colorways for collection differentiation.
- Transparent:Unpigmented or lightly tinted formulations serve specialty lighting and display applications with optical clarity requirements.
- Metallic:Flake and pearlescent pigment systems create surface effects for automotive accent trim and premium consumer electronics packaging.
Solid colors dominate volume throughput. Custom patterns capture the steepest value escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex anchors Asia-Pacific polyurethane feedstock flows, handling MDI and polyol shipments that supply foam converters across East Asia and export markets.
China
Domestic furniture and automotive production scaling drives colored PU foam absorption, with the country's dual carbon goals under MEE tightening energy efficiency mandates for polyol facilities. Ningbo and Yantai host integrated MDI-polyol manufacturing complexes that downstream converters leverage for export competitiveness.
Germany
Automotive Tier 1 suppliers enforce system house partnerships with locked formulation access for interior trim specifications, while REACH aromatic amine restrictions accelerate reformulation investments. The Cologne-Düsseldorf chemical corridor concentrates polyol production gravity that exposes fabricators to single-source disruption risks.
United States
EPA Clean Air Act Title V permitting shapes VOC emissions compliance for foam curing operations, with California's Department of Toxic Substances Control maintaining flammability labeling requirements that dictate formulation choices. North American bedding producers specify high resilience grades for premium mattress cores with 10-year warranty retention.
India
Domestic upholstery production scaling under PLI scheme incentives creates first-mover advantages for colored foam suppliers establishing local compounding operations. BIS standards govern product quality specifications as manufacturing clusters in Maharashtra and Gujarat absorb specification-driven procurement from furniture OEMs.
Italy
Luxury furniture producers commission exclusive colorways for collection differentiation, negotiating vendor-managed inventory agreements with compressed design-to-floor cycles below eight weeks. The country's national chemical regulator enforces migration limits for skin-contact applications in children's furniture segments.
Flexible Colored Polyurethane (PU) Foams Market Vendor Landscape
Concentration sits with diversified chemical majors possessing upstream polyol and isocyanate capabilities. The vendor base spans three tiers: integrated petrochemical conglomerates with captive feedstock supply, regional foam converters with pigment compounding specialization, and niche system houses serving automotive qualification programs. Two dominant competitive moves define current positioning: backward integration into MDI manufacturing to secure cost advantages, and acquisition of digital color matching platforms to collapse sample-to-production cycles.
Among European-based chemical majors, Covestro AG and BASF SE occupy positions exemplifying integrated petrochemical archetypes with upstream polyol capabilities. Wanhua Chemical Group Co., Ltd. anchors the Asia-Pacific production cluster through integrated manufacturing complexes. Huntsman Corporation sits within the specialty formulation tier, representing system-dependent supply relationships with automotive OEMs.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Wanhua Chemical Group Co., Ltd. |
| Dow Inc. |
| Huntsman Corporation |
| Rogers Corporation |
| Saint-Gobain Performance Plastics |
| Sekisui Chemical Co., Ltd. |
| Recticel NV/SA |
| Others |
Supply Flow & Price Mechanics
Forty-five-day pigment masterbatch lead times concentrate pricing power with converters maintaining captive compounding capabilities in Ningbo and Antwerp, while spot buyers absorb volatility from benzene-linked MDI swings. Furniture OEMs with vendor-managed inventory contracts lock in quarterly price bands that insulate against feedstock spikes.
Pricing Analysis
Volume-discount tiering structures stratify across premium automotive seating grades, standard furniture upholstery batches, and economy insulation boards. Price differentiation hinges on REACH certification tier and captive pigment compounding capability. Pricing pressure intensifies in commodity open-cell furniture grades as Chinese converters expand export volumes. Tier 1 automotive suppliers exhibit lowest price sensitivity due to locked formulation access requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites MDI feedstock flows from Middle Eastern benzene crackers to Ningbo polymerization complexes. Polyol production concentrates in Germany, Belgium, and China. Raw material dependencies span benzene-derived isocyanates, propylene oxide feedstocks, and specialty organic pigments. Single-source vulnerability runs through European aromatic amine-qualified pigment suppliers. Distribution runs through converter-direct contracts with automotive system houses and distributor networks serving fragmented furniture fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture manufacturer consolidation into six-week design-to-floor cycles has shifted procurement leverage toward large-format upholstery producers with vendor-managed inventory demands.
For Market Incumbents: Consolidate backward integration into MDI manufacturing to neutralize benzene price volatility exposure in European and Chinese production hubs. Deepen captive pigment compounding expertise to defend against specialty catalyst formulators qualifying for automotive seating programs. Prioritize certification investment for REACH aromatic amine compliance ahead of ECHA evaluation timelines. For New Entrants and Emerging Players: Lead with digital color matching platforms targeting mid-volume Italian furniture accounts where spectrophotometer-integrated formulation collapses sample cycles. Penetrate India's Maharashtra upholstery clusters under PLI scheme incentives before integrated chemical majors establish local compounding. Anchor go-to-market positioning on bio-based polyol mass-balance certification for bedding OEMs pivoting from natural latex substitution threats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-grade UV-stable foam production as 10-year fade resistance specifications demand precision mixing infrastructure. Five-to-ten year viability favors acquiring regional converters with locked Tier 1 supplier relationships over commodity foam fabricators exposed to MDI margin compression. Monitor ECHA substance evaluation timelines as inflection indicators for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Manufacturing | Covestro and Wanhua Chemical secure captive isocyanate supply against benzene volatility. |
| Digital Color Matching Platform Acquisition | Spectrophotometer-integrated software collapses furniture sample-to-production cycles from weeks to days. |
| REACH Compliant Pigment Reformulation | Organic pigment substitution unlocks premium positioning in EU-sourced children's furniture and automotive interiors. |
| Vendor-Managed Inventory Partnerships | Finished-goods buffers at Dongguan sofa plants compress design-to-floor cycles below eight weeks. |
| Bio-Based Polyol Mass-Balance Certification | Soybean and castor oil feedstocks satisfy German Tier 1 Scope 3 reporting requirements. |
Methodological Framework
Operator-level perspectives from foam plant managers, automotive Tier 1 procurement leads, furniture OEM technical directors, and pigment masterbatch suppliers anchored the qualitative base. Secondary validation drew from ECHA substance evaluation databases, SEC 10-K filings of listed chemical majors, Cefic polyol production statistics, and customs trade flows through Ningbo-Zhoushan Port. Bottom-up volume modeling triangulated against top-down chemical feedstock consumption estimates.
Sensitivity analysis tested forecast outputs against MDI price volatility bands, REACH compliance timeline acceleration, and natural latex substitution rates in premium bedding. Segmentation dimensions spanned cellular architecture, color complexity tier, end-use industry, and regional production hub concentration. CAGRs derived from polynomial trend fitting across historical consumption patterns and projected capacity additions. Industry-specific inputs included automotive interior content-per-vehicle trajectories and furniture manufacturing cluster expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained benzene price stability or ECHA regulatory timeline adherence would require recalibration. Forecasts reflect documented assumptions regarding polyol facility energy efficiency upgrade trajectories under China's MEE dual carbon mandates. Practitioners should keep alternative scenarios live as aromatic amine restriction scope and bio-based feedstock qualification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Hornbeam Market
Specialty Materials
Barium Borate Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Sulphur Bentonite Market