
 High Strength Laminated Adhesives Market | 2026-2036
High Strength Laminated Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
High Strength Laminated Adhesives Market Foresight
Asian chemical producers is expanding high-strength adhesive resin capacity to serve surging regional lamination demand. Henkel AG anchors European automotive bonding applications through specialized epoxy and polyurethane platforms. Dow competes on material science integration, leveraging captive petrochemical feedstocks for consistent polymer supply. 3M differentiates through tape and film-lamination technologies that occupy premium industrial segments in North America and Asia.
High strength laminated adhesives are engineered polymer systems formulated to bond dissimilar substrates under sustained mechanical stress, typically achieving lap-shear strengths exceeding 1,000 psi through cross-linked epoxy, polyurethane, or acrylic chemistries. These adhesives replace mechanical fasteners in weight-critical assemblies, enabling continuous stress distribution across bonded joints in aerospace fuselage panels, automotive body-in-white structures, and architectural glazing systems. Epoxy formulations dominate structural aerospace and wind energy applications where thermal resistance and load-bearing performance justify premium pricing, while polyurethane adhesives lead automotive and construction growth due to flexibility and cure-speed advantages. Water-based technology is displacing solvent-based systems across packaging and footwear lamination as environmental compliance tightens, though hot-melt platforms retain share in high-speed disposable product assembly where instant handling strength proves essential.
EPA regulations on hazardous air pollutants and volatile organic compound emissions are forcing adhesive reformulation across US manufacturing, while REACH restrictions in Europe limit specific isocyanate and solvent chemistries in consumer-facing applications. China's MEE standards on industrial emissions are accelerating domestic water-based adhesive adoption in the Yangtze and Pearl River manufacturing belts. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while evaluating capital allocation between bio-based feedstock development and regional compliance certification.
Market Dynamics
Water-based adhesive formulations are displacing solvent systems as the dominant chemistry class, driven by tightening volatile organic compound limits across manufacturing jurisdictions and automaker sustainability mandates.
Growth Catalysts
- EPA hazardous air pollutant rules:US manufacturers must reformulate bonding systems for automotive and aerospace assemblies, accelerating demand for compliant high-strength laminates.
- Lightweight vehicle structures:German and Japanese automakers expand bonded aluminum and composite body panels to meet fuel efficiency standards.
- Eastern China manufacturing corridor:Packaging and electronics lamination capacity scales in Jiangsu and Guangdong provinces, concentrating adhesive consumption.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with crude oil and propylene pricing, compressing formulation margins.
- MEE emission compliance timelines:Chinese producers face capital-intensive retrofits to meet industrial emission standards in Yangtze River manufacturing belts.
- Cure-speed limitations:Water-based systems require longer drying cycles than hot-melt alternatives, restricting adoption in high-speed disposable product lines.
Strategic Opportunities
- Wind turbine blade manufacturing:Epoxy laminate demand expands as rotor diameters increase and bonded structural joints replace mechanical fasteners.
- EU Green Deal industrial incentives:REACH-compliant bio-based adhesive development qualifies for green transition funding.
- Architectural glazing retrofits:Structural silicone and polyurethane laminates penetrate commercial building renovation markets in urban cores.
Industry Challenges
- Cross-functional formulation expertise:Shortage of chemists combining polymer science with automotive OEM specification navigation slows product qualification.
- Multi-jurisdiction substance registration:Simultaneous EPA, REACH, and MEE compliance testing extends time-to-market by 18-24 months for new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Strength Laminated Adhesives Market |
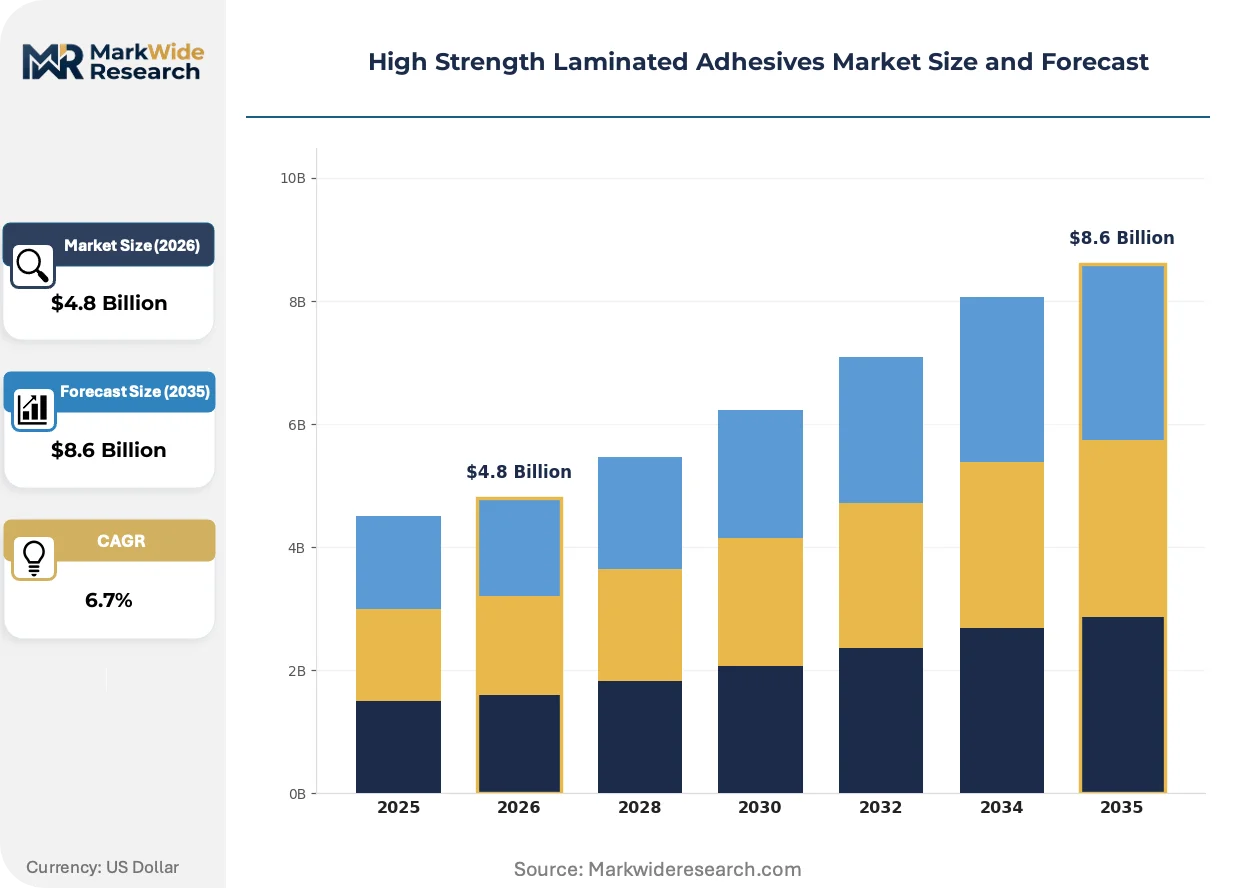
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End Use Industry: Aerospace, Automotive, Construction, Footwear Technology: Hot Melt, Pressure Sensitive, Solvent-Based, Water-Based Application: Bonding, Coating, Sealing, Insulating |
| Companies Covered | 3M, DuPont, H.B. Fuller Company, Henkel AG, Dow, Ashland, Avery Dennison, Bostik, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Strength Laminated Adhesives Market Shifts & Advancements
Reformulation pressure from environmental compliance is compressing technology cycles, while end-users demand faster cure speeds and broader substrate compatibility without sacrificing mechanical performance.
Two-component polyurethane systems with tunable open times are overtaking conventional epoxy platforms in automotive body-in-white applications. Tier 1 suppliers in Germany and Japan specify these chemistries for mixed-material bonding. The shift is overtaking established supply relationships as Asian resin producers capture specification influence.
REACH restrictions on specific isocyanate chemistries in consumer-facing applications are forcing polyurethane adhesive redesign across European footwear and furniture lamination sectors. Formulators substitute blocked isocyanates and waterborne alternatives to maintain bonding strength. Wind energy and aerospace manufacturers face parallel pressure to certify replacement chemistries ahead of substance sunset dates.
Automotive OEMs now require full supply chain carbon disclosure for adhesive procurement decisions. Suppliers must document Scope 3 emissions from resin production through final lamination. This transparency mandate is most visible in German and Japanese supply chains, where Tier 1 bonding system suppliers compete on verified lifecycle data rather than unit cost alone.
High Strength Laminated Adhesives Market Segmentation
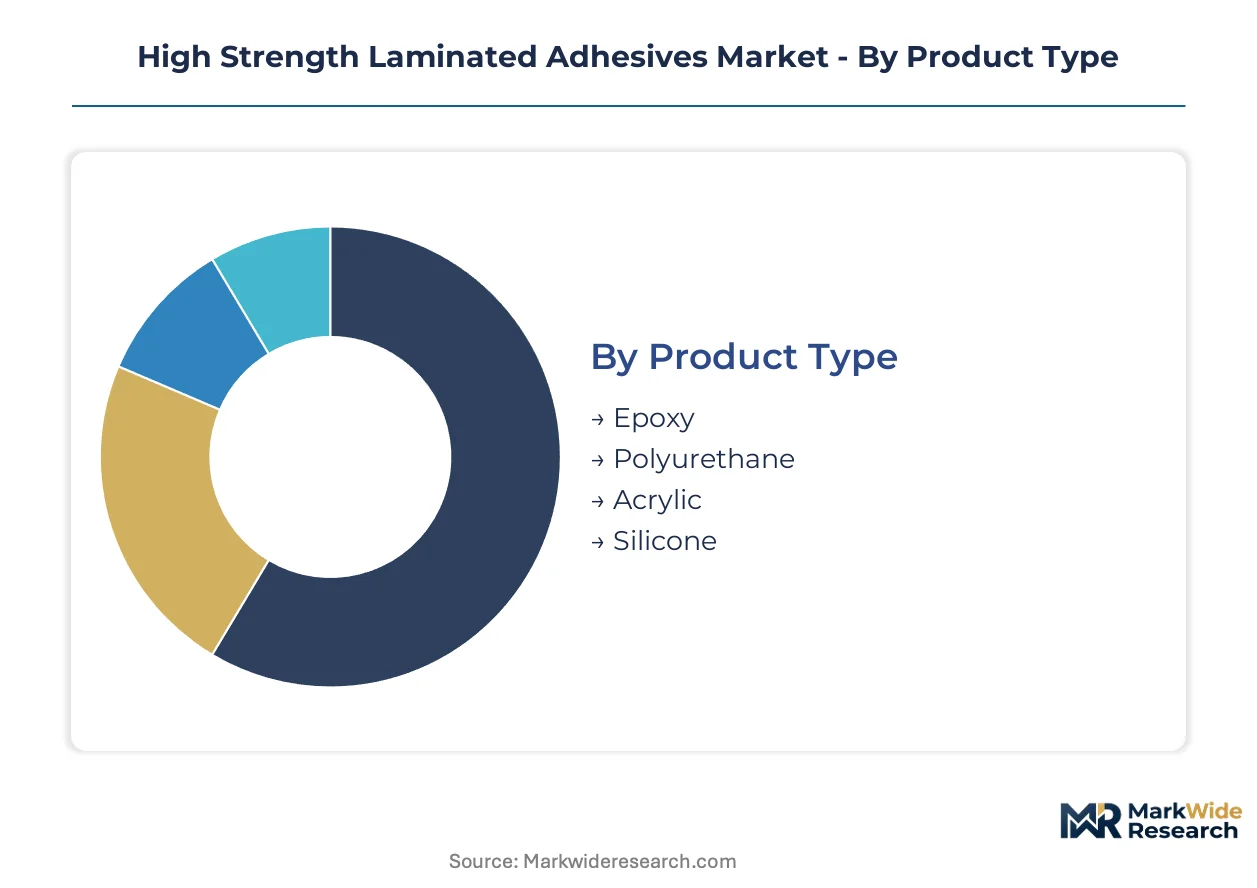
Segmentation in high strength laminated adhesives reveals how chemistry selection, cure technology, and end-use specifications create distinct competitive arenas. Buyers prioritize thermal resistance, environmental compliance, or processing speed depending on their assembly requirements. Formulators must align product portfolios across these dimensions to capture specification influence.
Product Type:
End-users select chemistries based on load-bearing requirements, thermal exposure limits, and substrate compatibility rather than unit cost alone.
- Epoxy:Cross-linked thermoset systems deliver lap-shear strengths exceeding 1,000 psi with excellent thermal resistance. Aerospace fuselage panels and wind turbine blade roots specify epoxy laminates for structural integrity under sustained mechanical stress. German and Japanese automakers now qualify next-generation epoxy variants for bonded aluminum-intensive body structures.
- Polyurethane:Two-component systems offer tunable flexibility and faster cure cycles than epoxy alternatives. Automotive body-in-white applications in Germany and Japan favor polyurethane for mixed-material bonding of steel, aluminum, and composites. REACH restrictions on specific isocyanates are forcing reformulation across European footwear and furniture sectors.
- Acrylic:UV-curable and anaerobic variants serve electronics lamination and precision assembly where rapid handling strength proves essential.
- Silicone:High-temperature stability and weathering resistance position these formulations in architectural glazing and photovoltaic module sealing.
Epoxy leads on scale; polyurethane leads on momentum.
End Use Industry:
Application environments dictate adhesive specification—thermal cycling, dynamic loading, and regulatory exposure vary sharply across sectors.
- Aerospace:FAA-certified structural adhesives bond primary and secondary airframe components, replacing rivets in fuselage panels and control surfaces. Epoxy platforms dominate with qualification cycles spanning multiple years and extensive substrate testing protocols.
- Automotive:OEMs specify bonding systems for lightweight vehicle structures to meet fuel efficiency mandates. German and Japanese manufacturers expand bonded aluminum and composite body panels, driving specification volume for both epoxy and polyurethane chemistries.
- Construction:Structural glazing and curtain wall applications demand weather-resistant laminates with decades-long durability predictions.
- Footwear:Lamination of synthetic uppers and sole attachment requires flexible, fatigue-resistant bonding systems with low volatile organic compound profiles.
Automotive commands the largest specification volume; aerospace maintains the highest performance premiums.
Technology:
Manufacturing line speed and emission compliance requirements determine technology selection more than bond strength alone.
- Hot Melt:Thermoplastic formulations deliver instant handling strength for high-speed disposable product assembly. Packaging lines favor hot-melt platforms where cure-speed limitations of water-based systems prove prohibitive.
- Pressure Sensitive:Tackified acrylic and rubber-based systems serve tape and film-lamination applications in electronics and medical device manufacturing.
- Solvent-Based:Declining share under tightening EPA hazardous air pollutant rules and REACH volatile organic compound limits. Reformulation pressure is accelerating across US and European manufacturing.
- Water-Based:Displacing solvent systems as the dominant chemistry class for packaging, footwear, and furniture lamination. China's MEE standards are accelerating adoption in Jiangsu and Guangdong manufacturing belts despite longer drying cycles.
Water-based systems lead on regulatory compliance trajectory; hot-melt retains share in speed-critical applications.
Application:
Functional requirements—structural load transfer, surface protection, gap filling, or thermal management—determine formulation architecture.
- Bonding:Structural adhesive joints replace mechanical fasteners in weight-critical assemblies. Continuous stress distribution across bonded interfaces enables thinner gauge materials in automotive and aerospace structures.
- Coating:Protective laminates seal substrates against moisture, chemical exposure, and abrasion. Wind turbine blade leading edges specify polyurethane coatings for erosion resistance.
- Sealing:Gap-filling formulations accommodate joint movement in architectural glazing and transportation applications. Structural silicone and polyurethane laminates penetrate commercial building renovation markets in urban cores.
- Insulating:Thermally and electrically resistive adhesives serve electronics packaging and battery assembly where thermal runaway protection proves critical.
Bonding generates the largest formulation volume; insulating applications are climbing the fastest on electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity is shifting toward jurisdictions with lower compliance costs as EPA and REACH emission rules tighten. Manufacturers in China and Southeast Asia capture specification volume from reformulating Western plants. This arbitrage dynamic concentrates capacity expansion in emerging manufacturing belts while mature markets specialize in premium certified formulations.
United States
Automotive OEMs in Michigan and Ohio specify bonded aluminum body structures to meet NHTSA fuel efficiency mandates. EPA hazardous air pollutant rules force reformulation of solvent-based bonding systems across aerospace and industrial assembly. The Southeast manufacturing corridor from Tennessee to South Carolina attracts adhesive compounding investment as producers seek lower regulatory compliance costs than California or Northeast markets.
Germany
BMW, Mercedes-Benz, and Volkswagen expand bonded mixed-material vehicle architectures to satisfy EU CO2 fleet standards. REACH restrictions on specific isocyanate chemistries accelerate polyurethane adhesive redesign across footwear and furniture lamination. The Baden-Württemberg and Bavaria automotive clusters concentrate Tier 1 bonding system suppliers competing on verified lifecycle carbon data.
China
Packaging and electronics lamination capacity scales in Jiangsu and Guangdong provinces, concentrating water-based adhesive consumption. MEE industrial emission standards in the Yangtze and Pearl River manufacturing belts accelerate domestic reformulation away from solvent systems. Zhejiang and Shandong provinces attract resin capacity expansion as Asian chemical producers serve regional demand growth.
Japan
Toyota and Honda qualify next-generation epoxy and polyurethane laminates for aluminum-intensive body structures under METI energy efficiency programs. JIS standards on volatile organic compound emissions in manufacturing tighten specification requirements for domestic adhesive procurement. The Chubu region around Nagoya anchors automotive bonding system development with integrated resin-to-lamination supply chains.
South Korea
Hyundai and Kia expand bonded composite panels in electric vehicle platforms to extend driving range under national carbon neutrality targets. MFDS and environmental ministry rules on industrial emissions push water-based adhesive adoption in Gyeonggi-do electronics lamination facilities. The Busan-Ulsan manufacturing belt concentrates wind turbine component production, driving epoxy laminate demand for rotor blade structural joints.
High Strength Laminated Adhesives Market Competitive Landscape
German and US producers anchor the premium formulation tier; Asian specialists hold volume positions in water-based and hot-melt platforms. The market structures around three tiers: integrated petrochemical players with captive resin supply, diversified adhesive formulators with broad specification portfolios, and regional specialists serving single industries or geographies. Competitive moves concentrate on M&A to acquire formulation expertise and capacity expansion in low-cost manufacturing jurisdictions.
Within the diversified formulation tier, Henkel AG and Dow exemplify archetypes of European industrial integration and petrochemical-backed material science respectively. 3M occupies a position in premium tape and film-lamination technologies across North American and Asian industrial segments. These three companies represent contrasting strategic positions: specialized automotive bonding platforms, upstream-integrated polymer supply, and differentiated industrial application technologies.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| H.B. Fuller Company |
| Henkel AG |
| Dow |
| Ashland |
| Avery Dennison |
| Bostik |
| Arkema |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap German formulators anchor the premium adhesive tier, channeling multi-generational technical expertise into specification-locked automotive supply chains while resisting price erosion through embedded OEM qualification barriers. Their ownership structure permits patient capital allocation toward REACH compliance investments that shorter-horizon competitors cannot match, compressing margins for PE-backed roll-ups chasing quarterly returns.
Pricing Analysis
Distributor margin layers in automotive adhesive procurement typically capture 12-18 points before Tier 1 conversion, though direct-to-OEM contracts for qualified structural laminates bypass this intermediary entirely. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-grade levels separates specification premiums from commodity volume plays. Pricing pressure stems from Asian resin producers capturing specification influence in body-in-white applications, forcing European incumbents to defend position through verified carbon disclosure rather than unit cost alone. Packaging converters exhibit acute price sensitivity due to thin lamination margins, while aerospace OEMs prioritize thermal resistance and qualification pedigree over procurement savings.
Supply Chain Analysis
Dual-sourcing requirements from BMW, Toyota, and Boeing mandate multi-supplier qualification for structural adhesive procurement, preventing single-source dependency even where formulation performance varies. Geographic supply concentration centers on Germany, Japan, and eastern China, with Zhejiang and Shandong provinces attracting resin capacity expansion to serve regional lamination demand. Raw material dependencies rest on petrochemical feedstocks—propylene oxide, bisphenol-A, and MDI isocyanates—subject to crude oil volatility. Tariff exposure on Chinese epoxy intermediates threatens margin stability for US formulators. Distribution runs through integrated chemical distributors and direct OEM technical service teams, with specification influence residing in application engineering relationships rather than catalog availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as bonded lightweight vehicle architectures displace mechanical fasteners across fuel-efficiency mandates. Regulatory compliance timelines create durable competitive moats for qualified formulators.
For Market Incumbents: Hedge specification exposure by qualifying second-source resin partnerships in Zhejiang and Guangdong manufacturing belts before REACH sunset dates harden supply constraints. Deepen captive production of waterborne polyurethane intermediates to offset petrochemical feedstock volatility eroding formulation margins. Certification investment in aerospace-qualified epoxy platforms defends position against Asian entrants capturing automotive specification volume. For New Entrants and Emerging Players: Begin with wind turbine blade manufacturing in the Busan-Ulsan corridor, where epoxy laminate demand for rotor structural joints outpaces qualified supplier capacity. Target footwear lamination in Vietnam and Indonesia, where REACH-compliant waterborne adhesive supply remains underdeveloped relative to export manufacturing scale. Pursue toll-manufacturing partnerships with established German formulators to bypass 18-24 month OEM qualification cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among European mid-cap specialists with stranded solvent-based capacity facing MEE compliance retrofits. Five-to-ten year viability favors formulators with backward integration into bio-based feedstock development qualifying for EU Green Deal industrial incentives. Watch EPA hazardous air pollutant rule enforcement timelines as the signal indicating acceleration or delay in US reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captures EU Green Deal funding while insulating margins from propylene price volatility. |
| Capacity Expansion in Zhejiang Province | Positions resin supply adjacent to Jiangsu and Guangdong lamination demand clusters. |
| Long-Term Supply Agreement with Wind OEMs | Locks epoxy laminate volume as rotor diameters increase bonded joint specifications. |
| Joint Venture with Asian Resin Producer | Accelerates REACH-compliant polyurethane qualification for European footwear export. |
| Green Manufacturing Transition Certification | Enables carbon disclosure competitiveness in German and Japanese automotive procurement. |
Research Methodology
Direct dialogue with adhesive formulator R&D directors, Tier 1 automotive procurement managers, wind turbine blade manufacturing engineers, and chemical distribution channel heads grounded qualitative assessment of specification dynamics and reformulation timelines. Secondary validation drew from EPA hazardous air pollutant rulemakings, ECHA REACH substance restriction updates, MEE industrial emission standards, customs trade data on epoxy resin flows, and SEC filings from diversified chemical producers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Bottom-up volume builds aggregated adhesive consumption by chemistry type, cure technology, and end-use application across named manufacturing clusters. Top-down validation cross-checked against petrochemical feedstock demand indicators and OEM lightweighting content-per-vehicle assumptions. Modeled dimensions included structural performance tier, environmental compliance pathway, regional regulatory jurisdiction, and substrate compatibility matrix. CAGRs derived from elasticity-adjusted penetration curves for bonded versus fastened assembly methods.
Caveats apply where EPA enforcement acceleration, REACH substance sunset date revisions, or MEE compliance timeline extensions could materially shift the outlook. Forecasts reflect assumptions regarding automaker fuel efficiency mandate stringency and wind energy installation trajectories. Deviation in petrochemical feedstock pricing volatility or dual-sourcing qualification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market