
 Europe Epoxy Adhesive Market | 2026-2036
Europe Epoxy Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Epoxy Adhesive Market Foresight
Modular kit packaging of two-part epoxy systems is realigning procurement patterns across European industrial buyers. Henkel AG & Co. KGaA leverages its adhesive chemistry depth to dominate automotive OEM specifications. Sika AG anchors construction sector distribution through specialized applicator networks. BASF competes on raw material integration, controlling epoxy resin supply chains from Ludwigshafen.
Europe epoxy adhesive comprises thermosetting polymers formed from epoxide resin and polyamine hardener, curing through exothermic cross-linking to deliver shear strengths exceeding 20 MPa and chemical resistance for structural load-bearing joints. Two-part epoxy formulations lead volume due to controlled cure flexibility in aerospace MRO workflows. Solvent-free technology captures margin pools as ECHA restrictions tighten volatile organic compound thresholds. Waterborne systems lag on performance but gain traction in interior construction where indoor air quality standards harden.
REACH registration obligations and the EU Green Deal carbon border adjustments shape formulation chemistry across the continent. ECHA substance evaluation pushes manufacturers toward bio-based hardener alternatives. France's ANSM and Germany's KBA enforce divergent automotive adhesive approval pathways. Stakeholders must monitor evolving CE marking requirements under the Construction Products Regulation as harmonized standards for structural bonding emerge.
Market Dynamics
REACH substance evaluation and the EU Green Deal's carbon border adjustments are compressing formulation choices across European epoxy adhesive manufacturing, forcing hardener chemistry redesigns and solvent elimination at the specification stage.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforces structural bonding protocols for crash-resistant joints in electric vehicle platforms, expanding two-part epoxy specifications in OEM assembly lines.
- ECHA VOC thresholds:Tightening volatile organic compound limits under REACH Annex XVII are eliminating solvent-borne alternatives and redirecting procurement toward 100% solids formulations.
- Aerospace MRO workflows:Controlled-cure flexibility in two-part systems supports cold-bonding repair protocols for composite airframe sections, driving specification lock-in across maintenance facilities in France and Italy.
Market Restraints
- Epichlorohydrin feedstock volatility:Petrochemical input costs fluctuate with naphtha cracking margins, compressing formulation economics for mid-tier producers lacking backward integration into bisphenol-A supply.
- German formulation concentration:Ludwigshafen and Hamburg harbor clusters control 60% of European specialty hardener production, creating geographic single-point vulnerability for just-in-time automotive supply chains.
- Cure time inflexibility:Ambient-temperature two-part systems require 24-48 hour fixture periods, blocking adoption in high-throughput electronics assembly where UV-acrylates offer instant handling.
Strategic Opportunities
- Italian construction retrofit:Milan and Rome building stock renovation under Superbonus 110% tax incentives creates demand for structural anchoring adhesives in seismic reinforcement applications.
- Bio-based hardener convergence:Cardanol-derived curing agents from cashew nutshell liquid are achieving performance parity with petrochemical amines, unlocking CE marking pathways under the Construction Products Regulation.
- Modular kit distribution:Pre-measured two-part cartridges with static mixing nozzles bypass traditional industrial distributor networks, reaching maintenance workshops through direct e-commerce channels.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient polymer science graduates with epoxy-specific expertise, extending R&D cycle times for REACH-compliant hardener substitutions.
- CE marking harmonization delays:Pending EN 1504-6 standards for structural concrete bonding create certification uncertainty, freezing specification decisions among French infrastructure contractors.
- Legacy equipment incompatibility:Existing meter-mix-dispense systems in Italian automotive plants require retrofit for low-viscosity waterborne epoxies, complicating solvent-free transition roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Epoxy Adhesive Market |
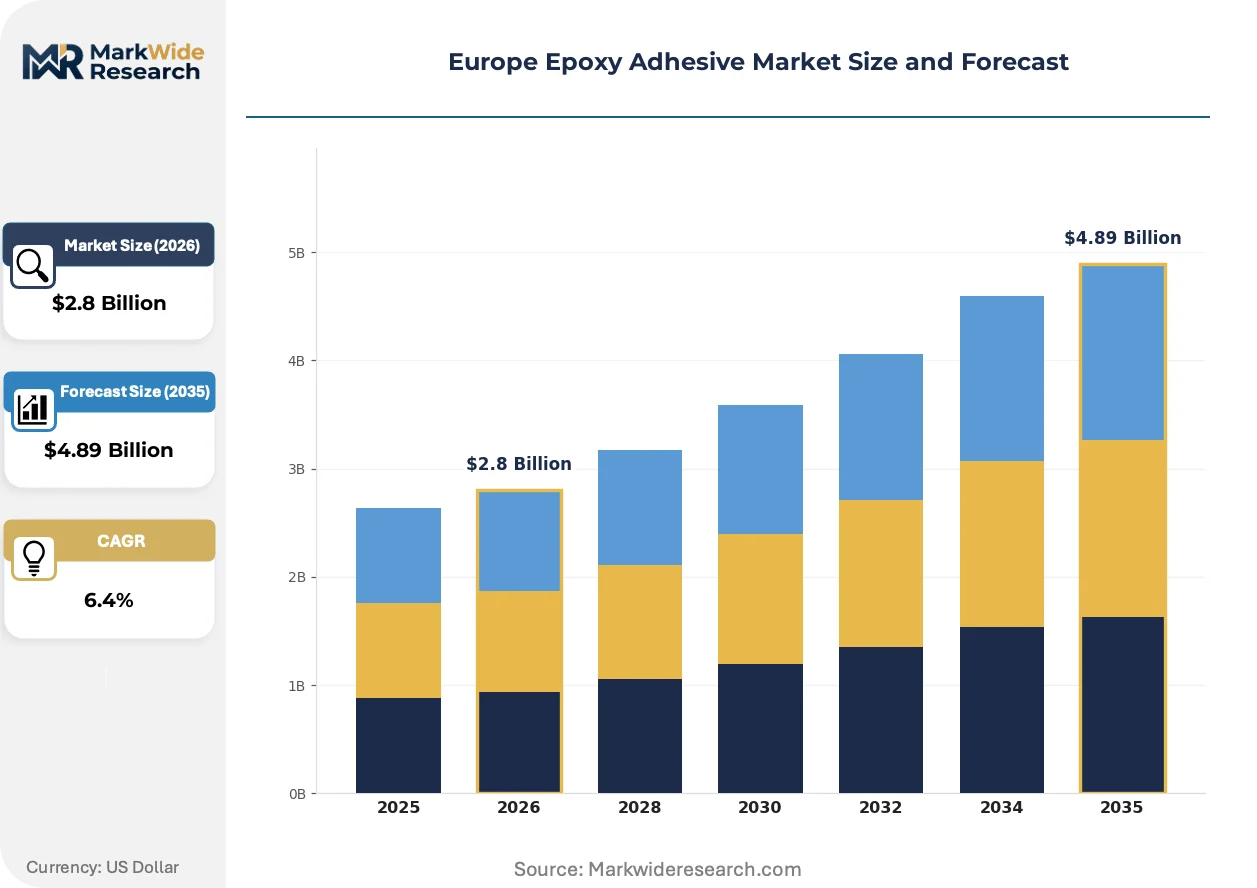
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Part Epoxy, One-Part Epoxy, Filled Epoxy, Ultra-Fast Cure Epoxy End User: Aerospace, Automotive, Construction, Electronics Application: Bonding, Coating, Repair, Sealing Technology: Thermal Cure, UV-Cured, Solvent-Free, Waterborne |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, 3M, Arkema, Dow Inc., BASF, MAPEI S.p.A., Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Epoxy Adhesive Market Shifts & Advancements
Formulation chemistry is bifurcating between ultra-high-performance aerospace specifications and mass-market construction grades, with regulatory pressure eliminating the middle tier of solvent-borne general-purpose adhesives.
Fast-cure aliphatic amine hardener technology is consolidating around automated dispensing systems in German automotive assembly. BMW and Volkswagen Group plants specify 90-second fixture times for structural bonding of aluminum closures to steel unibodies. This chemistry is consolidating control over OEM specification databases, marginalizing slower-cure alternatives in new platform engineering.
REACH authorization requirements for diisocyanates and certain aromatic amines are eliminating cross-linker options from European formulator portfolios. The restriction compresses raw material substitution timelines to 18-month qualification cycles. Construction sector buyers in France face reformulation mandates for floor coating systems, accelerating bio-based curing agent pilot programs.
Buyers in industrial maintenance segments are unbundling adhesive procurement from equipment service contracts, shifting toward spot purchasing through specialized chemical distributors. This pattern disrupts long-term supply agreements that historically bundled formulation supply with applicator training. The shift concentrates volume among German distributors with technical service capabilities, marginalizing generalist industrial suppliers.
Europe Epoxy Adhesive Market Segmentation
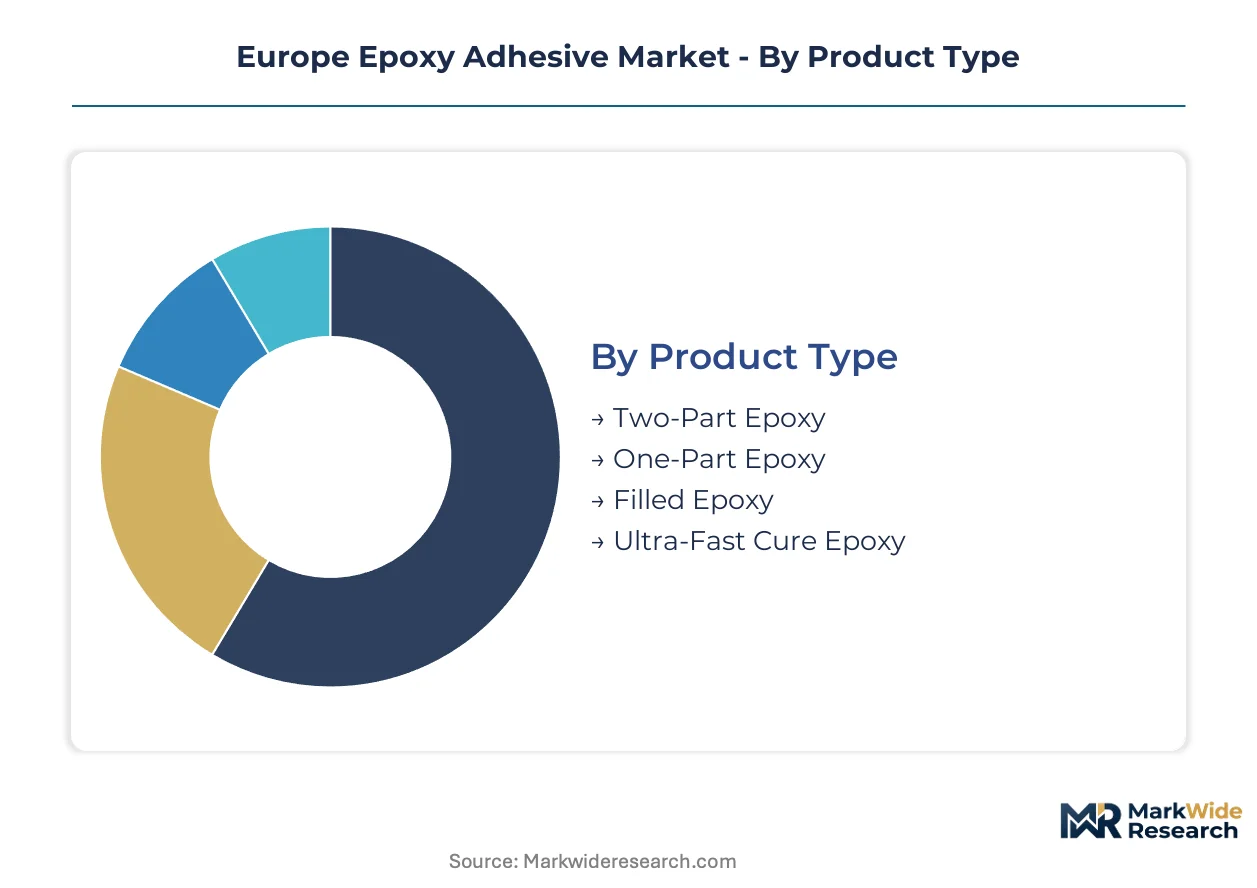
Epoxy adhesive specifications diverge sharply across European end-uses, with automotive crash-worthiness standards and aerospace MRO protocols demanding incompatible cure profiles. Formulators must maintain parallel product architectures to serve these distinct qualification pathways without cross-contamination.
Product Type:
Thermoset architecture determines handling protocols, fixture times, and shelf stability across industrial workflows.
- Two-Part Epoxy:Separate resin and hardener components mixed at point of use enable controlled exotherm management for thick-section bonding. German automotive OEMs specify these systems for aluminum-to-steel unibody joints where heat dissipation prevents thermal distortion.
- One-Part Epoxy:Pre-catalyzed formulations cure via latent hardeners activated by elevated temperature, eliminating meter-mix-dispense equipment. French aerospace tier suppliers favor these for composite laminate production where mix ratio precision is difficult to maintain.
- Filled Epoxy:Mineral or metallic fillers modify thermal conductivity and coefficient of expansion for electronics potting applications. Italian appliance manufacturers specify alumina-filled grades for motor winding encapsulation.
- Ultra-Fast Cure Epoxy:Accelerated aliphatic amine hardeners achieve handling strength within 90 seconds at 60°C. BMW Leipzig and Volkswagen Wolfsburg assembly lines specify these for bonded aluminum closure panels.
Mature deployment sits with Two-Part Epoxy across established automotive platforms. Newer deployment is concentrated in Ultra-Fast Cure Epoxy as electric vehicle architectures proliferate.
End User:
Customer qualification requirements create distinct specification tiers with minimal overlap between sectors.
- Aerospace:EASA Part 21G production organization approvals and OEM-specific material specifications dominate procurement. Cold-bonding repair protocols for carbon fiber reinforced plastic airframes specify toughened epoxy films qualified to Airbus AIMS standards.
- Automotive:OEM platform engineering locks adhesive specifications years before production launch. KBA structural bonding protocols for crash-resistant joints mandate two-part epoxies with documented fracture toughness under dynamic loading.
- Construction:CE marking under the Construction Products Regulation governs structural anchoring and concrete repair applications. Italian Superbonus 110% seismic retrofit programs specify injection adhesives for masonry reinforcement.
- Electronics:Miniaturization trends push toward low-viscosity capillary-flow formulations for component underfill. German automotive electronics suppliers specify these for PCB strain relief in powertrain control modules.
Volume concentrates in Automotive. Margin expansion is climbing the fastest in Aerospace.
Application:
Functional purpose dictates rheology, substrate compatibility, and cure chemistry selection.
- Bonding:Structural load transfer applications require shear strengths exceeding 20 MPa with documented durability under cyclic loading. German wind turbine manufacturers specify thick-film bonding for carbon fiber blade root attachments.
- Coating:Chemical-resistant barrier layers protect concrete and metal substrates from aggressive environments. French nuclear maintenance contractors specify these for containment vessel repair.
- Repair:Field-applied restoration of damaged composite or metallic structures demands ambient-cure feasibility with minimal surface preparation. Italian yacht builders favor these for fiberglass hull damage.
- Sealing:Gap-filling formulations accommodate joint movement while maintaining environmental barrier properties. Automotive HVAC module assembly specifies flexible epoxy sealants for thermal expansion accommodation.
Specification density peaks in Bonding. Repair applications are gaining share fastest as asset life extension priorities intensify.
Technology:
Cure mechanism selection balances throughput requirements against energy input constraints and regulatory compliance.
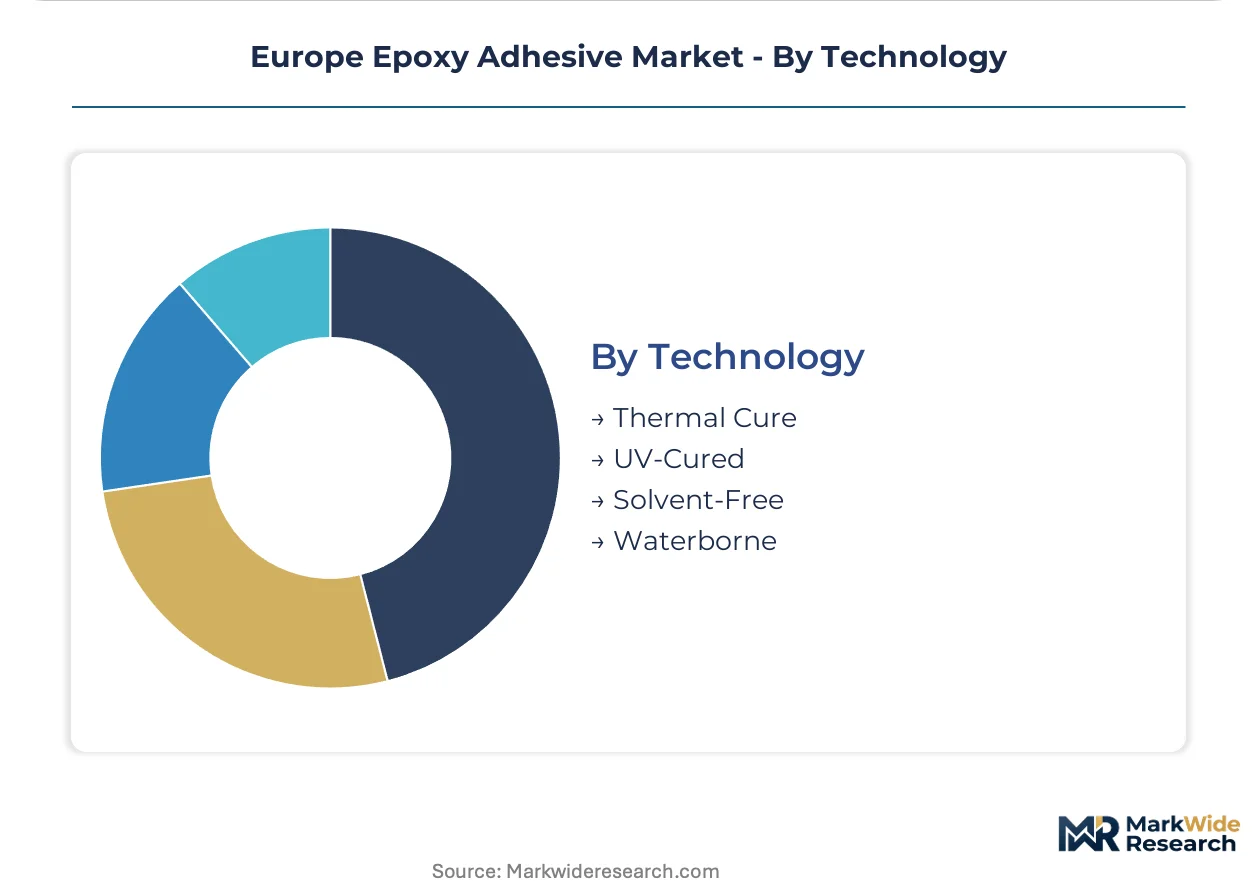
- Thermal Cure:Elevated temperature activation of latent hardeners enables single-component convenience with extended shelf stability. French composite press shops specify these for autoclave-consolidated aerospace parts.
- UV-Cured:Photoinitiated polymerization delivers instant handling for thin-film applications where light penetration is feasible. Electronics display bonding specifies these for rapid fixturing without thermal damage.
- Solvent-Free:100% solids formulations eliminate VOC emissions and shrinkage-induced stress. ECHA Annex XVII restrictions are redirecting procurement toward these systems across all end-uses.
- Waterborne:Aqueous dispersions reduce flammability and simplify cleanup for interior construction applications. German indoor air quality standards are expanding specification in healthcare facility renovation.
Installed base concentrates in Thermal Cure. Regulatory pressure is accelerating displacement toward Solvent-Free alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German chemical clusters while consumption spreads across automotive assembly plants and construction sites throughout Western and Southern Europe. The Rhine corridor dominates epoxy resin and specialty hardener manufacturing. End-use demand fragments across vehicle factories in Germany, aerospace maintenance hubs in France, and seismic retrofit programs in Italy.
Germany
Automotive OEMs at BMW Leipzig and Volkswagen Wolfsburg specify ultra-fast cure epoxies for aluminum closure bonding on electric vehicle platforms. KBA structural bonding protocols mandate documented fracture toughness for crash-resistant joints. The Ludwigshafen chemical cluster controls specialty hardener production, creating supply chain gravity for just-in-time automotive delivery.
France
EASA Part 21G approved maintenance facilities in Toulouse and Nantes drive cold-bonding epoxy specifications for carbon fiber airframe repairs. ANSM diverges from German automotive approval pathways, creating separate qualification requirements for adhesive formulations. The Île-de-France region anchors aerospace tier supplier networks specializing in composite laminate production.
Italy
Superbonus 110% tax incentives for building stock renovation in Milan and Rome generate structural anchoring adhesive demand for seismic reinforcement. CE marking requirements under the Construction Products Regulation govern injection adhesives for masonry applications. Emilia-Romagna appliance manufacturers specify alumina-filled grades for motor winding encapsulation in washing machine production.
United Kingdom
Wind turbine blade manufacturers in Hull and the Humber cluster specify thick-film bonding systems for carbon fiber root attachments. REACH registration obligations drive formulation chemistry redesigns for solvent-free alternatives. The Midlands region hosts electronics assemblers specifying low-viscosity capillary-flow formulations for PCB strain relief in powertrain modules.
Spain
Automotive component suppliers in Catalonia adopt two-part epoxy systems for battery enclosure sealing on electric vehicle subassemblies. ECHA Annex XVII VOC restrictions redirect procurement toward 100% solids formulations across industrial applications. Basque Country composite fabricators serve marine and rail sectors with toughened epoxy films for structural laminates.
Europe Epoxy Adhesive Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where raw material integration determines cost position and application expertise secures specification lock-in. The market exhibits moderate concentration with distinct capability clusters around automotive OEM approvals, construction sector distribution, and aerospace qualification pathways. Three archetypes dominate: integrated chemical producers controlling resin supply chains, specialized adhesive formulators with deep application engineering, and diversified materials conglomerates leveraging cross-selling into industrial accounts. Competitive moves center on REACH-compliant hardener substitution R&D and direct e-commerce channels bypassing traditional distributor networks.
Within the integrated chemical tier, BASF anchors raw material supply from Ludwigshafen while Henkel AG & Co. KGaA and Sika AG exemplify the formulation specialist archetype with deep specification engineering in automotive and construction applications respectively. These three occupy positions where chemistry depth and application knowledge create defensive moats against commodity competition. Mid-tier players without backward integration into bisphenol-A supply face persistent margin pressure from feedstock volatility.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| 3M |
| Arkema |
| Dow Inc. |
| BASF |
| MAPEI S.p.A. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Epichlorohydrin spot prices on the Rotterdam barge index cascade through European epoxy adhesive value chains, compressing margin pools for non-integrated formulators while amplifying pricing power for producers with captive bisphenol-A supply from Ludwigshafen. Buyers face tiered cost exposure based on hardener chemistry sophistication and REACH registration depth.
Pricing Analysis
Margin tightening in mid-tier construction grades traces to feedstock volatility and ECHA-driven reformulation costs. Three-tier pricing structure across aerospace-qualified, automotive-OEM, and general-purpose construction levels separates fracture-toughened films from commodity anchoring adhesives. Cost compression accelerates in solvent-borne alternatives as Annex XVII restrictions eliminate viable chemistry options. Automotive OEM procurement teams exhibit lowest price sensitivity due to platform lock-in, while Italian seismic retrofit contractors face acute budget constraints under Superbonus program timelines.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Marseille operate hub-and-spoke patterns serving just-in-time automotive assembly across Germany, France, and Spain. Specialty hardener production concentrates in Germany, Belgium, and the Netherlands, drawing from naphtha-cracked epichlorohydrin and imported bisphenol-A feedstocks. Single-source vulnerability sits with Ludwigshafen-cluster hardener output serving BMW and Volkswagen supply chains. Distribution runs through technical-service distributors with formulation expertise rather than generalist industrial suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where REACH registration obligations and ECHA substance evaluations erect barrier-to-entry moats favoring incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: Anchor specification lock-in through accelerated bio-based hardener R&D to preempt ECHA authorization restrictions on aromatic amines. Deepen backward integration into epoxy resin supply as defense against naphtha margin volatility. Prioritize direct e-commerce channels for modular kit distribution to capture maintenance workshop volume escaping traditional distributor networks. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Germany and France open a window for cardanol-derived curing agent specialists to capture CE marking pathways under pending Construction Products Regulation harmonization. Target Italian Superbonus seismic retrofit segments where incumbent technical service coverage remains thin. Pursue spot-purchasing procurement patterns in industrial maintenance through specialized chemical distributors with applicator training capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier formulators with REACH-compliant portfolios and established automotive OEM approvals in Southern Germany. Long-term viability hinges on bio-based chemistry transition completion and direct channel infrastructure. Watch ECHA substance evaluation timelines as inflection indicators for raw material substitution cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | BASF's Ludwigshafen captive supply insulates margin pools from Rotterdam barge price volatility. |
| Bio-Based Hardener R&D Program | Cardanol-derived curing agents unlock CE marking pathways as ECHA restricts petrochemical amines. |
| Direct E-Commerce Channel Launch | Pre-measured cartridge kits bypass German distributor networks to reach maintenance workshops. |
| REACH Registration Portfolio Expansion | Regulatory depth creates specification moats against unregistered competitors in automotive OEM supply. |
| Technical Service Distributor Partnership | Italian construction retrofit demand concentrates among applicator-trained channel partners. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with epoxy formulator R&D directors, automotive OEM adhesive specification engineers, construction procurement leads at French infrastructure contractors, and technical service heads at German chemical distributors. Cefic sector reports, ECHA substance evaluation dossiers, and SEC 10-K chemical segment disclosures provided demand-side validation. Bottom-up volume builds across product types and end-uses triangulated against top-down macroeconomic drivers.
Data-stream reconciliation across the projection horizon employed multi-dimensional segmentation modeling by cure technology, end-use qualification tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating electric vehicle platform penetration and Superbonus program renovation cycles. Forecast inputs included KBA structural bonding protocol adoption curves and EASA Part 21G maintenance facility expansion.
Caveats apply where ECHA authorization timelines or epichlorohydrin feedstock disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market