
 Long-Chain Dicarboxylic Acid Market | 2026-2036
Long-Chain Dicarboxylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Chain Dicarboxylic Acid Market Outlook
REACH is realigning the cost-of-entry calculus for European producers of long-chain dicarboxylic acids by mandating rigorous chemical safety documentation and restricting certain petrochemical feedstocks. Evonik Industries AG leverages its integrated C4 chemistry platform to sustain cost-competitive dodecanedioic acid output despite regulatory headwinds. Cathay Biotech Inc. anchors its position through industrial-scale bio-fermentation of sebacic acid from renewable feedstocks.
Long-chain dicarboxylic acids comprise aliphatic compounds with ten to fourteen carbon atoms and terminal carboxyl functional groups, synthesized via chemical oxidation of fatty acids or microbial fermentation of alkanes, serving primarily as monomer building blocks for high-performance polyamides and engineering thermoplastics. Sebacic acid dominates volume flows due to mature supply chains serving polyamide 6,10 and 10,10 resin grades, while dodecanedioic acid registers the fastest structural expansion on penetration into bioplastics formulations and low-friction lubricant base stocks. Polyamide applications command the deepest margin pools owing to specification-grade purity requirements and long-term supply contracts with automotive tier suppliers.
EMA chemical substance evaluations, EPA TSCA Section 5 premanufacture notices, and China's GB standards for industrial chemicals collectively shape product registration timelines, testing burdens, and cross-border market access protocols for long-chain dicarboxylic acid manufacturers. EMA's ongoing scrutiny of C10-C14 diacid environmental persistence profiles elevates compliance costs for European entrants without bio-based process certification. Stakeholders must monitor regulatory divergence between bio-preferred frameworks and conventional petrochemical pathways to anticipate which production routes retain commercial viability across jurisdictions.
Market Dynamics
Fermentation-based sebacic acid production from renewable castor oil feedstocks is concentrating supply chain control among integrated Chinese biorefinery operators, compressing margins for European petrochemical oxidation routes burdened by REACH compliance costs.
Growth Catalysts
- Polyamide 6,10 demand in automotive lightweighting:European OEMs specify bio-based sebacic acid for under-hood components to meet EU Green Deal embodied carbon targets.
- REACH bio-preferred pathway incentives:ECHA's streamlined registration for renewable-sourced C10-C14 diacids reduces testing burdens versus petrochemical equivalents.
- Castor bean cultivation expansion in Gujarat:India's National Mission on Edible Oils subsidizes non-edible oilseed farming, securing fermentation feedstock supply.
Market Restraints
- Castor oil price volatility:Weather-driven Indian harvest fluctuations transmit directly to sebacic acid production economics.
- Supply concentration in Shandong Province:Over 60% of global fermentation capacity clusters within 200km of Qingdao port infrastructure.
- Technical purity ceiling for electronic-grade applications:Fermentation-derived dodecanedioic acid struggles to meet semiconductor encapsulant ionic contamination thresholds.
Strategic Opportunities
- Brazilian castor value chain development:Embrapa's drought-resistant cultivar programs could replicate Indian feedstock security in South America.
- Bioplastic polyamide penetration in food contact:FDA food additive petitions for bio-based C12 diacid open packaging substitution routes.
- Algae-to-alkane fermentation convergence:Synthetic biology platforms combining autotrophic cultivation with yeast bioconversion bypass agricultural land use constraints.
Industry Challenges
- Industrial microbiology talent scarcity:Strain engineering and bioprocess optimization expertise concentrates at elite fermentation institutes in China and the Netherlands.
- Multi-year REACH registration timelines:Novel bio-based C14 diacid variants face 18-24 month ECHA evaluation periods before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Chain Dicarboxylic Acid Market |
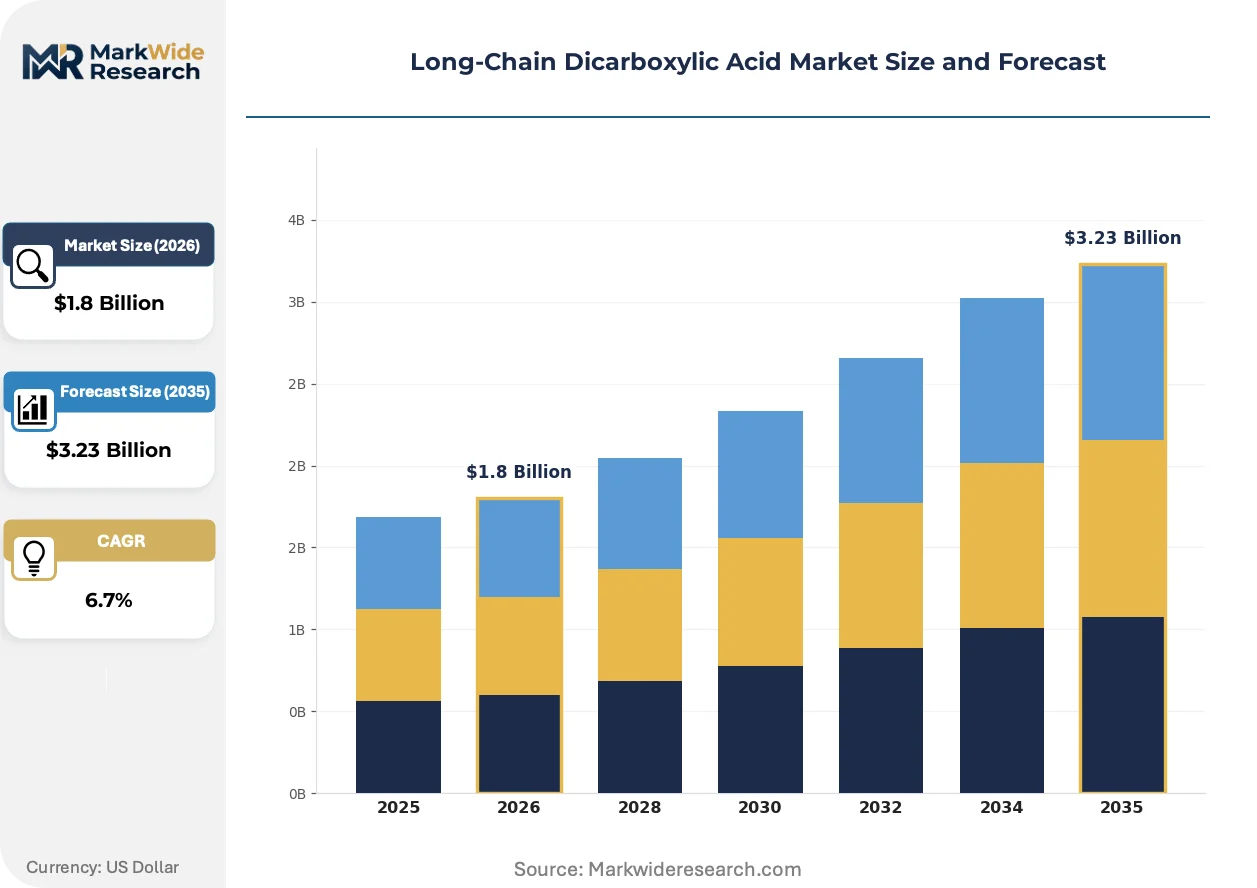
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sebacic Acid, Araconic Acid, Dodecanedioic Acid, Undecanedioic Acid Application: Polyamide, Bioplastics, Coatings, Lubricants End User: Aerospace, Automotive, Textile, Packaging Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Evonik Industries AG, dsm-firmenich, Cathay Biotech Inc., Henan Junheng Industrial Group Biotechnology Co., Ltd., BASF SE, INVISTA, Zibo Guangtong Chemical Co., Ltd., Croda International Plc, Shandong Hilead Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Chain Dicarboxylic Acid Market Strategic Shifts
Process intensification in microbial fermentation and downstream crystallization is collapsing production costs for bio-based long-chain diacids, eroding the historical cost advantage of petrochemical oxidation routes.
Continuous fermentation with cell retention technology is rewriting the capital efficiency calculus for sebacic acid manufacturing. Chinese operators deploy perfusion bioreactors achieving cell densities above 150 g/L dry weight, cutting unit capital costs by half versus batch alternatives. This platform is compressing the minimum efficient scale for viable entry, enabling mid-size fermentation facilities to challenge incumbent oxidation plants.
EU F-Gas Regulation phase-down schedules are accelerating demand for low-global-warming-potential refrigerants in polymer processing equipment. Polyamide compounders serving HVAC and appliance sectors now specify bio-based diacid monomers to align finished product carbon footprints with CSRD disclosure requirements. German automotive suppliers lead this specification shift, embedding renewable content mandates into tier-n supplier contracts.
Specification-grade purchasing contracts with automotive OEMs are displacing spot market transactions for C10-C12 diacid volumes. Tier-1 resin compounders in Stuttgart, Wolfsburg, and Munich negotiate three-year offtake agreements with fixed purity bands and audit rights over fermentation feedstock provenance. This contractual shift is most pronounced in Germany, where supply chain due diligence obligations under the Supply Chain Due Diligence Act drive documentation depth.
Long-Chain Dicarboxylic Acid Market Segmentation
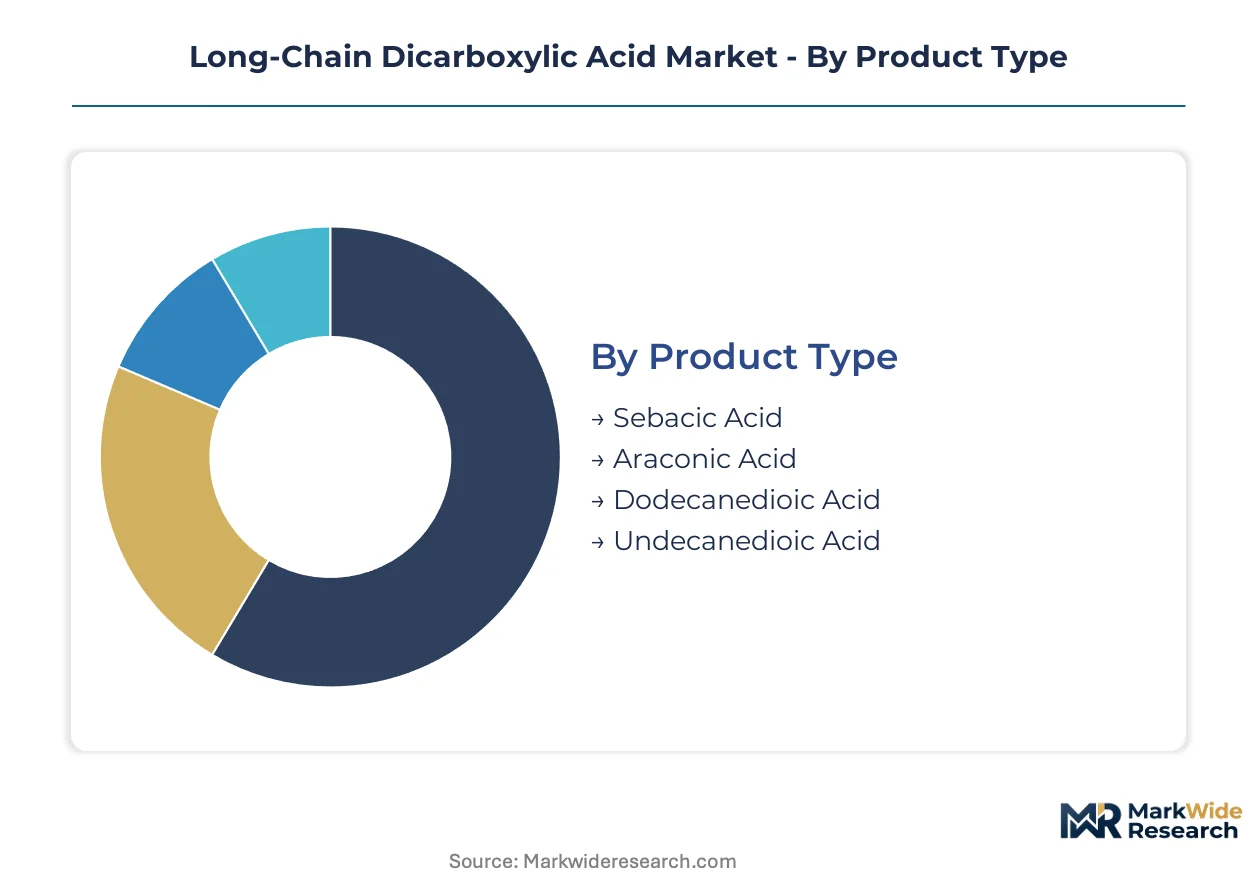
Long-chain dicarboxylic acid producers face divergent margin structures across product chemistries and end-use specifications. Segmentation reveals where fermentation-based bio-routes command premium pricing versus where petrochemical oxidation retains cost advantages.
Product Type:
Supply concentration in fermentation-derived C10 diacids is compressing margins for European petrochemical oxidation routes burdened by REACH compliance costs.
- Sebacic Acid:Ten-carbon aliphatic diacid synthesized via castor oil fermentation dominates volume flows. Chinese biorefinery clusters in Shandong Province serve polyamide 6,10 and 10,10 resin grades for automotive under-hood components, with EU Green Deal embodied carbon targets accelerating bio-preferred procurement.
- Dodecanedioic Acid:Twelve-carbon chain length registers the steepest expansion trajectory on penetration into bioplastics formulations and low-friction lubricant base stocks. Evonik's integrated C4 chemistry platform sustains cost-competitive output despite regulatory headwinds from EMA substance evaluations.
- Araconic Acid:Unsaturated C18 diacid derived from tung oil feedstocks serves specialized coating applications requiring oxidative crosslinking.
- Undecanedioic Acid:Odd-chain C11 diacid bridges performance gaps between sebacic and dodecanedioic grades in niche polyamide intermediates.
Today's leader: Sebacic Acid. Tomorrow's challenger: Dodecanedioic Acid.
Application:
Cost tier differentiation separates specification-grade polyamide monomers from commodity coating intermediates.
- Polyamide:Engineering thermoplastic applications command the deepest margin pools owing to automotive tier supplier purity requirements and long-term supply contracts. German OEMs in Stuttgart and Wolfsburg embed renewable content mandates into tier-n supplier agreements.
- Bioplastics:FDA food additive petitions for bio-based C12 diacid are opening packaging substitution routes, with EU F-Gas Regulation phase-down schedules accelerating demand for low-global-warming-potential polymer processing.
- Coatings:Alkyd and epoxy curing agent applications tolerate broader purity bands, sourcing from mixed oxidation and fermentation supply.
- Lubricants:Synthetic ester base stocks for high-performance applications favor dodecanedioic acid's thermal stability profile.
Polyamide claims the premium tier. Bioplastics is climbing the fastest.
End User:
Customer type fragmentation across industrial sectors drives divergent certification and documentation requirements.
- Automotive:European OEMs specify bio-based sebacic acid for lightweight under-hood components, with Supply Chain Due Diligence Act obligations in Germany driving audit rights over fermentation feedstock provenance.
- Aerospace:Specification-grade purchasing contracts with fixed purity bands dominate, though volumes remain constrained by qualification timelines.
- Textile:Polyamide 6,10 fiber applications for industrial yarns source from established sebacic acid supply chains.
- Packaging:Food contact applications await regulatory clearance for bio-based C12 diacid variants, with GB standards in China and FDA pathways in the US shaping market access.
Automotive anchors current value. Packaging holds latent volume potential.
Distribution Channel:
Volume scale determines channel selection, with specification-grade transactions favoring direct relationships.
- Direct Sales:Three-year offtake agreements with fixed purity bands and fermentation feedstock audit rights characterize automotive tier-1 resin compounder procurement in Germany.
- Distributors:Mid-volume coating and lubricant formulators access sebacic acid through regional chemical distributors with inventory positioning in Rotterdam and Qingdao.
- Online Retail:Small-lot research and sampling quantities for specialty chemical procurement.
- Specialty Stores:Niche channels for laboratory-scale and custom synthesis applications.
Direct sales captures the premium tier. Distributors serve the volume middle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-chain dicarboxylic acid production originated in German chemical complexes during the mid-twentieth century, with petrochemical oxidation routes scaling first. Fermentation-based manufacturing later concentrated in Chinese coastal provinces, shifting the industry's geographic center of gravity eastward.
China
Polyamide 6,10 resin manufacturers in Jiangsu and Zhejiang provinces absorb the majority of sebacic acid fermentation output. GB standards for industrial chemicals administered by SAMR govern product registration and cross-border shipment protocols. Shandong Province hosts over sixty percent of global fermentation capacity, with Qingdao port infrastructure enabling integrated biorefinery-to-polymer supply chains.
Germany
Automotive tier-1 compounders in Stuttgart and Wolfsburg specify bio-based diacid monomers for under-hood lightweighting components. The Supply Chain Due Diligence Act mandates audit rights over fermentation feedstock provenance for imported materials. Evonik Industries AG maintains integrated C4 chemistry operations in Marl Chemical Park despite REACH compliance cost pressures.
United States
Specialty polyamide compounders serving aerospace and electronics sectors source specification-grade dodecanedioic acid through direct procurement channels. EPA TSCA Section 5 premanufacture notice requirements extend registration timelines for novel bio-based C14 variants. Texas Gulf Coast petrochemical complexes retain oxidation-route capacity for industrial-grade coating intermediates.
India
Castor bean cultivation in Gujarat supplies renewable feedstock for fermentation-based sebacic acid production serving domestic textile polyamide demand. The National Mission on Edible Oils subsidizes non-edible oilseed farming to secure biorefinery input security. Mumbai-based resin compounders negotiate long-term offtake agreements with Shandong fermentation operators.
Japan
Electronic-grade polyamide encapsulant manufacturers impose ionic contamination thresholds that fermentation-derived diacids struggle to satisfy. METI industrial standards differentiate between petrochemical and bio-based process certifications for chemical imports. Osaka-based engineering thermoplastic compounders qualify suppliers through multi-year specification trials.
Long-Chain Dicarboxylic Acid Market Competitive Environment
The competitive structure tilts toward integrated biorefinery operators with captive castor oil supply chains. Chinese fermentation specialists command volume leadership through continuous perfusion bioreactor technology, while European petrochemical incumbents defend specification-grade positions in automotive and electronics applications. Three archetypes dominate: integrated Chinese biorefineries, diversified German chemical conglomerates, and specialty Indian-Chinese joint ventures. Capacity expansion and strategic feedstock partnerships constitute the primary competitive moves, with fermentation technology licensing emerging as a secondary vector.
Within the integrated biorefinery tier, Cathay Biotech Inc. and Shandong Hilead Biotechnology Co., Ltd. occupy positions shaped by Shandong Province fermentation cluster economics. Evonik Industries AG exemplifies the diversified chemical conglomerate archetype, leveraging Marl Chemical Park infrastructure to sustain oxidation-route output. Henan Junheng Industrial Group Biotechnology Co., Ltd. represents the specialty fermentation segment, with Zhengzhou-based operations reflecting central Chinese industrial positioning. These three entities anchor distinct competitive vectors without overlapping strategic territories.
| Leading Market Players |
|---|
| Evonik Industries AG |
| dsm-firmenich |
| Cathay Biotech Inc. |
| Henan Junheng Industrial Group Biotechnology Co., Ltd. |
| BASF SE |
| INVISTA |
| Zibo Guangtong Chemical Co., Ltd. |
| Croda International Plc |
| Shandong Hilead Biotechnology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Specification-grade polyamide monomers diverge sharply from commodity coating intermediates in both cost structure and sourcing complexity, with automotive tier-1 compounders in Stuttgart and Wolfsburg paying purity premiums while coating formulators access spot volumes through Rotterdam distributors. This bifurcation concentrates pricing power among Shandong fermentation operators for C10 diacids while compressing margins for European oxidation routes burdened by REACH compliance documentation.
Pricing Analysis
Long-term offtake contracts dominate specification-grade transactions, with three-year agreements carrying fixed purity bands and fermentation feedstock audit rights displacing spot market activity for automotive resin compounders. Price differentiation rests on certification tier—REACH bio-preferred pathway status commands premiums over conventional petrochemical equivalents—and volume scale, with mid-volume coating buyers sourcing through distributors at standard grades. Cost compression in commodity sebacic acid intensifies as Chinese perfusion bioreactor deployments collapse unit production economics, while electronic-grade dodecanedioic acid buyers show lowest price sensitivity due to ionic contamination thresholds that fermentation routes struggle to satisfy.
Supply Chain Analysis
Freight cost differentials between Qingdao port infrastructure and Rotterdam chemical hubs shape procurement economics for European polyamide compounders sourcing Shandong fermentation output. Supply concentrates in China, India, and Germany, with castor oil feedstock dependency anchoring input security to Gujarat cultivation cycles and Shandong biorefinery integration. Single-source vulnerability runs through the 60 percent capacity clustering within 200 kilometers of Qingdao, where weather-driven Indian harvest fluctuations transmit directly to sebacic acid availability. Distribution runs through direct sales channels for automotive tier-1 relationships and regional distributors for mid-volume coating and lubricant formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-burdened European oxidation routes and Chinese fermentation platforms benefiting from streamlined ECHA bio-preferred registration, with compliance cost differentials exceeding production economics in specification-grade tiers.
For Market Incumbents: Extend fermentation capacity in Shandong Province to defend against emerging Brazilian castor value chain development, while securing backward integration into Gujarat castor cultivation through offtake agreements with National Mission on Edible Oils subsidized farms. Threats from algae-to-alkane synthetic biology platforms require strain engineering talent retention at elite fermentation institutes in the Netherlands and China. For New Entrants and Emerging Players: A mid-tier pricing gap between premium automotive specification grades and economy coating intermediates creates entry space for FDA food additive petition-ready C12 diacid producers targeting bioplastic packaging substitution. The most penetrable segment sits in food contact applications awaiting regulatory clearance, with go-to-market leverage through direct engagement with German automotive suppliers embedding renewable content mandates into tier-n supplier contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where industrial microbiology talent scarcity concentrates bargaining power among elite strain engineering institutes. Long-term viability favors integrated biorefinery operators with captive castor oil supply chains over standalone fermentation facilities exposed to feedstock volatility. Acquisition targets should display perfusion bioreactor technology deployment and Qingdao-adjacent logistics positioning. The signal to watch is EMA substance evaluation timelines for novel C14 variants, which compress commercialization windows for bio-based entrants lacking regulatory pre-approval.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Cultivation | Secures fermentation feedstock against Gujarat weather volatility and price spikes. |
| Perfusion Bioreactor Technology Licensing | Enables mid-scale European entrants to challenge incumbent oxidation plant economics. |
| REACH Bio-Preferred Certification Investment | Unlocks streamlined ECHA registration and premium pricing in automotive supply chains. |
| Long-term Supply Agreement with Tier-1 Compounders | Locks in three-year offtake volumes with audit rights over feedstock provenance. |
| Joint Venture with Algae Fermentation Platforms | Bypasses agricultural land use constraints through autotrophic cultivation convergence. |
Study Parameters
Multiple input streams—primary interviews with fermentation plant managers, polyamide procurement leads at automotive OEMs, and Shandong distribution channel partners; secondary validation through customs trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings of listed chemical conglomerates; plus technical R&D director surveys—were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical production capacity trends were cross-referenced against panel input from bioprocess engineers and regulatory affairs specialists to anchor growth projections across the analysis window. Segmentation dimensions modeled include carbon chain length tier, end-use application grade, regional production hub classification, and feedstock source certification status. CAGRs were derived from supply-demand balance assessments incorporating polyamide 6,10 resin grade qualification timelines and EMA substance evaluation period assumptions.
Caveats apply where EMA environmental persistence scrutiny, EPA TSCA Section 5 registration delays, or castor oil harvest volatility could materially shift the outlook for fermentation route competitiveness. Forecasts embed assumptions about regulatory pathway efficiency and biorefinery technology diffusion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
US Humate Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Chlorocyclopentane Market