
 Emulsion Pressure Sensitive Adhesives Market | 2026-2036
Emulsion Pressure Sensitive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion Pressure Sensitive Adhesives Market Analysis
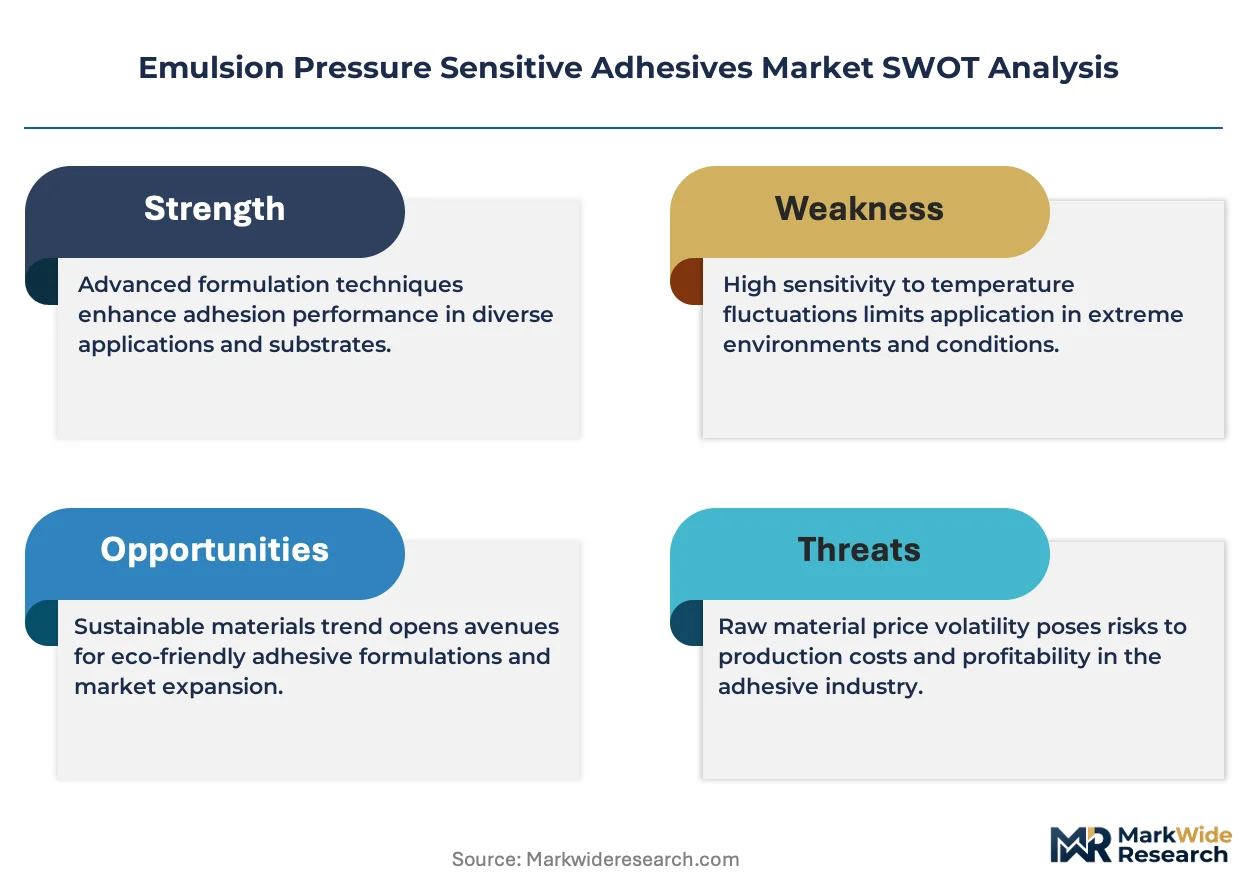
Aftermarket service revenue for adhesive formulation tuning is narrowing as manufacturers push integrated supply contracts. Henkel AG & Co. KGaA leverages its European technical centers to anchor water-based emulsion development for automotive tier suppliers. H.B. Fuller Company competes through geographic dominance in North American packaging adhesives, while Arkema Group specializes in high-performance acrylic emulsions for medical-grade applications.
Emulsion pressure sensitive adhesives are aqueous polymer dispersions, typically 40-60% solids content, that form a tacky film upon drying and bond to surfaces through light pressure without chemical reaction or heat activation. Their primary purpose spans temporary fixation, protective masking, and permanent lamination across paper, film, and fabric substrates. Permanent emulsion PSAs dominate packaging and labeling volumes where fiber tear and cold-temperature adhesion are critical performance parameters. Water-based technology leads formulation choices as converters eliminate solvent recovery systems, though UV-curable variants are gaining share in electronics assembly where instant handling strength and clean edges are required.
EPA VOC regulations in the United States, REACH chemical restrictions in Europe, and China's MEE emission standards are collectively mandating lower volatile content in adhesive systems, which directly favors water-based emulsion platforms over solvent alternatives. FDA biocompatibility requirements for skin-contact medical devices and EU MDR compliance for wearable patches further narrow acceptable material chemistries. Stakeholders must monitor regulatory convergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
The transition from solvent-based to water-based adhesive systems constitutes the dominant structural force reshaping competitive positioning, as converters dismantle solvent recovery infrastructure and OEMs face mounting regulatory pressure to eliminate volatile organic compound emissions from assembly operations.
Growth Catalysts
- EPA VOC regulations:The United States Environmental Protection Agency mandates on industrial coatings and adhesives are compelling manufacturers to reformulate with aqueous polymer dispersions, eliminating thermal oxidizer investments.
- Automotive interior bonding:OEMs in Germany and Japan are specifying emulsion PSAs for lightweight dashboard lamination and headliner assembly to meet fleet weight reduction targets.
- Acrylic emulsion technology:Advances in particle size control and tackifier compatibility are expanding cold-temperature performance envelopes for freezer-grade labeling applications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and tackifier resin prices fluctuate with crude oil derivatives, compressing formulation margins during supply shocks.
- Water sensitivity limitation:Emulsion PSAs exhibit performance degradation in high-humidity or direct water exposure applications, restricting use in marine and certain medical device assemblies.
- REACH authorization delays:ECHA substance evaluation timelines for novel tackifier chemistries extend product development cycles by eighteen to thirty-six months.
Strategic Opportunities
- Indian packaging conversion:Food and beverage labeling demand in Maharashtra and Gujarat is outpacing domestic emulsion PSA supply, creating import substitution potential for regional production.
- UV-curable hybrid systems:Convergence of water-based dispersion chemistry with photoinitiated crosslinking addresses electronics assembly requirements for instant handling strength without thermal damage.
- EU Green Deal procurement mandates:Public sector purchasing rules favoring bio-based content are opening specification windows for emulsion PSAs derived from renewable tackifier feedstocks.
Industry Challenges
- Rheology formulation expertise:Shortage of adhesive scientists capable of balancing peel strength, shear resistance, and coating speed across divergent substrate chemistries constrains product pipeline velocity.
- FDA 510(k) pathway complexity:Wearable medical device manufacturers face extended biocompatibility testing timelines for skin-contact emulsion PSA layers, delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion Pressure Sensitive Adhesives Market |
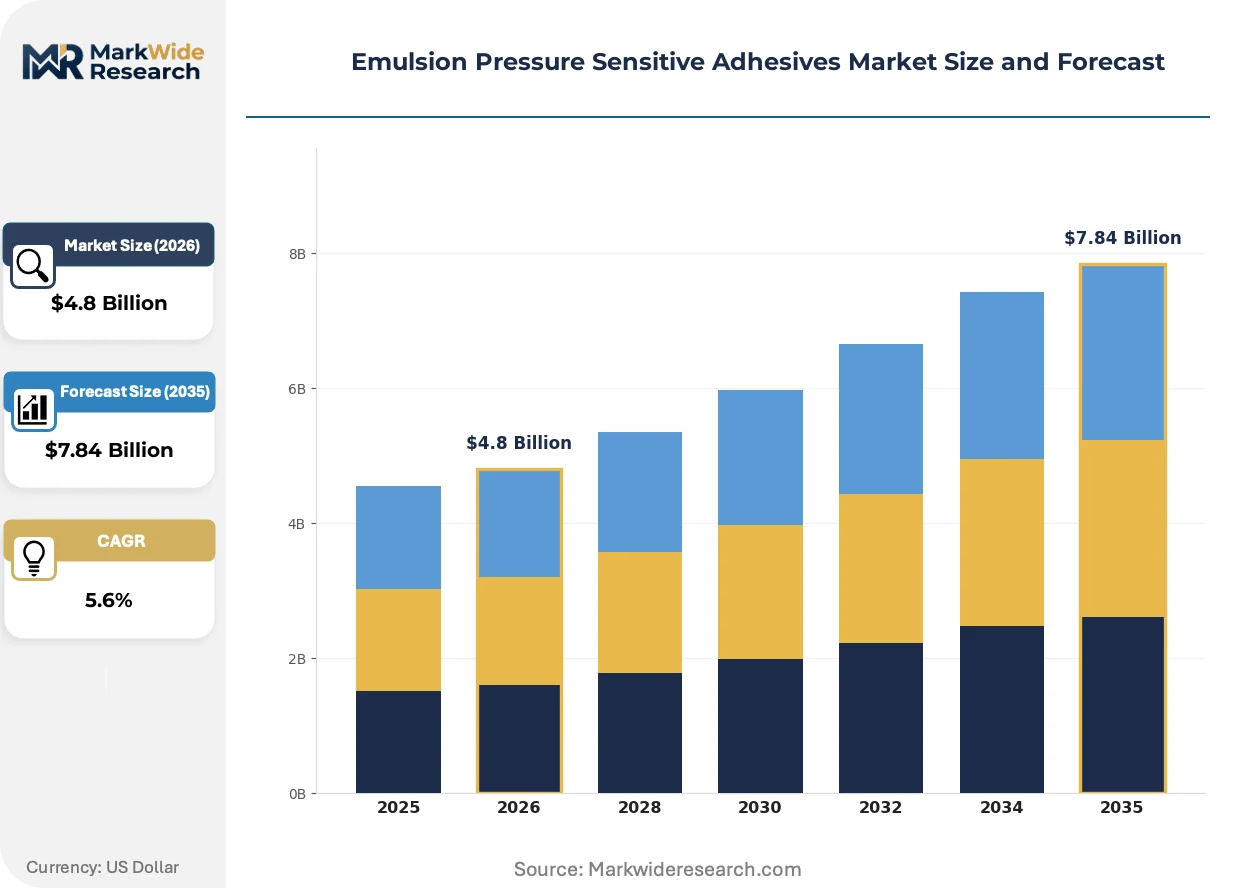
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Removable, Semi-Permanent, Specialty Application: Packaging, Labeling, Automotive, Medical End User: Consumer Goods, Electronics, Industrial, Construction Technology: Water-Based, UV-Curable, Solvent-Based, Hot Melt |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Arkema Group, H.B. Fuller Company, Dow, Avery Dennison Corporation, Ashland Inc., American Biltrite Inc., APEC, Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion Pressure Sensitive Adhesives Market Emerging Trajectories
Digital specification tools and predictive performance modeling are compressing traditional formulation development cycles, while sustainability metrics increasingly gate supplier qualification for major converting accounts.
Hybrid acrylic-styrene emulsion polymers with engineered glass transition temperatures are virtualizing the trade-off between room-temperature tack and elevated-temperature shear resistance that previously required separate product lines. Automotive tier suppliers in Stuttgart and Toyota City are qualifying these materials for instrument panel bonding within compressed twelve-week validation windows. The technology is virtualizing inventory complexity by collapsing multiple SKU grades into single-platform formulations.
REACH restriction proposals on microplastic release from consumer products are pressuring labelstock converters to demonstrate biodegradation pathways for adhesive residues. ECHA consultation timelines suggest Annex XVII listing by mid-decade for non-biodegradable filmic label constructions. German packaging converters are responding by accelerating trials of emulsion PSAs formulated with enzymatically degradable tackifier systems.
Integrated supply contracts now bundle adhesive formulation with substrate specification and die-cutting services, displacing the traditional model of converter-procured materials. Major beverage brands in North America are consolidating vendor bases to three preferred adhesive-coating partners per region. This concentration is most visible in California and Wisconsin, where legacy distributor networks are losing specification influence to direct technical partnerships.
Emulsion Pressure Sensitive Adhesives Market Segmentation
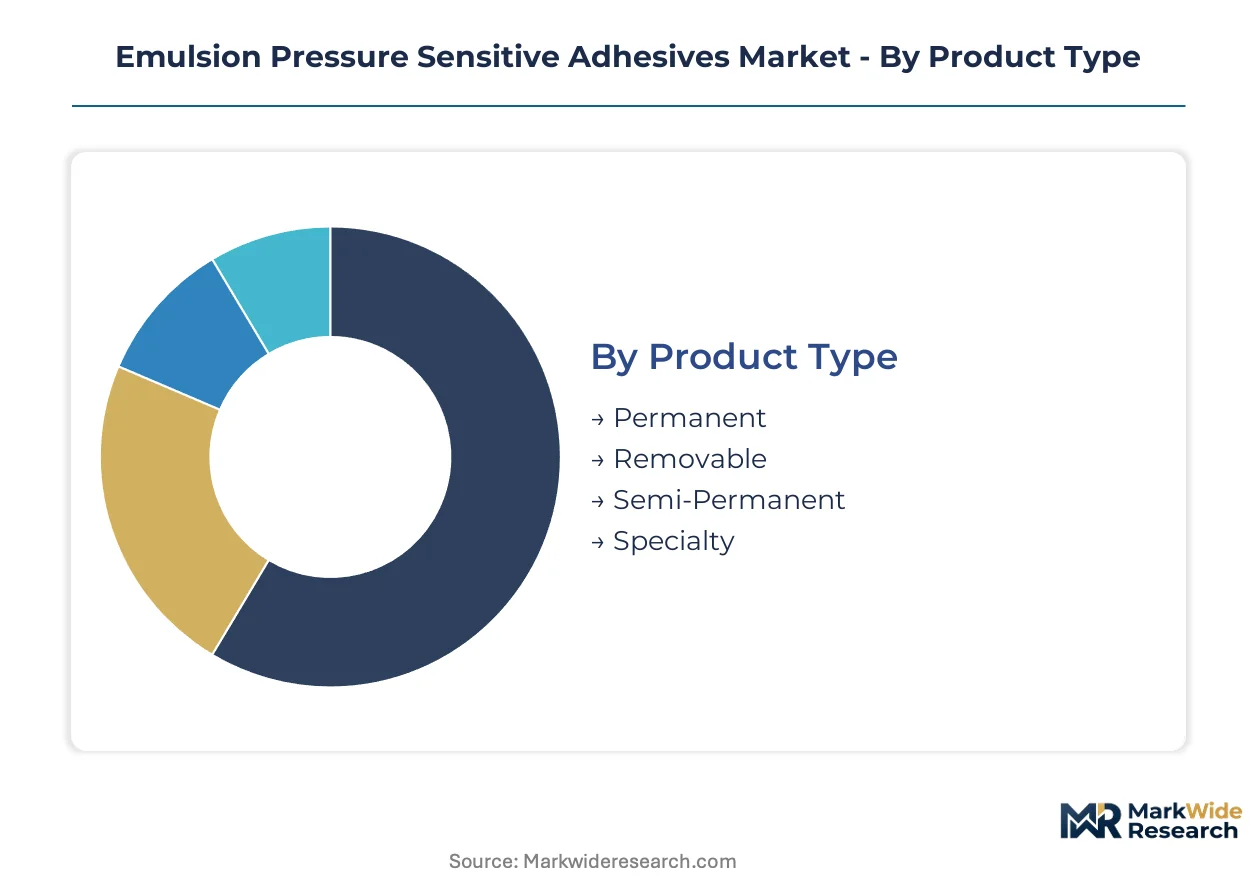
Emulsion pressure sensitive adhesives serve divergent bonding requirements across packaging, automotive, and medical sectors where peel strength, repositionability, and biocompatibility demands vary dramatically. Segmentation reveals how formulation chemistry and curing technology align with specific end-use performance thresholds and regulatory constraints.
Product Type:
Permanent formulations dominate fiber-tear applications while removable and specialty grades address repositionable and regulated use-cases.
- Permanent:Acrylic emulsion polymers formulated for aggressive adhesion to paper, film, and corrugated substrates. Demand concentrates in German automotive interior lamination where OEMs specify cold-temperature fiber tear for dashboard assemblies. REACH compliance on VOC content drives specification toward water-based permanent grades.
- Removable:Controlled-tack formulations enabling clean removal without residue from glass, painted metal, and plastic surfaces. Japanese electronics manufacturers specify these for temporary protective masking during display panel assembly. UV-curable hybrid variants are gaining traction for instant handling strength requirements.
- Semi-Permanent:Intermediate adhesion for repositionable labels and promotional graphics with 6-12 month service life.
- Specialty:FDA-compliant skin-contact grades for wearable medical devices and enzymatically degradable tackifier systems responding to ECHA microplastic consultation timelines.
Established volume favors Permanent; emerging adoption favors Specialty.
Application:
Application segmentation tracks how substrate compatibility and environmental exposure dictate formulation architecture.
- Packaging:High-speed coating on corrugated and folding carton substrates requiring balanced tack and shear resistance. North American beverage converters in California and Wisconsin are consolidating vendor bases to direct technical partnerships. Water-based emulsions eliminate thermal oxidizer investments at coating facilities.
- Labeling:Freezer-grade performance for food logistics and clear-film applications demanding optical clarity. Acrylic emulsion advances in particle size control are expanding cold-temperature adhesion envelopes for frozen supply chains.
- Automotive:Dashboard lamination, headliner assembly, and lightweight bonding for fleet weight reduction targets.
- Medical:Biocompatible skin-contact layers for wearable patches and device fixation meeting FDA and EU MDR compliance pathways.
Packaging commands current procurement volumes; Medical is climbing the fastest on regulatory tailwinds.
End User:
End-user segmentation reflects how procurement scale and technical specification authority distribute across value chains.
- Consumer Goods:High-volume labeling and packaging for food, beverage, and personal care products. Major brands are reducing adhesive-coating partners to three per region, concentrating specification influence.
- Electronics:Temporary fixation and protective masking for display and semiconductor assembly. UV-curable hybrid emulsion systems address instant handling strength without thermal damage to sensitive components.
- Industrial:General assembly, splicing, and protective applications across manufacturing operations.
- Construction:Flooring installation tapes, vapor barrier sealing, and temporary surface protection with humidity resistance requirements.
Consumer Goods anchors procurement scale; Electronics shows steepest expansion trajectory on assembly automation trends.
Technology:
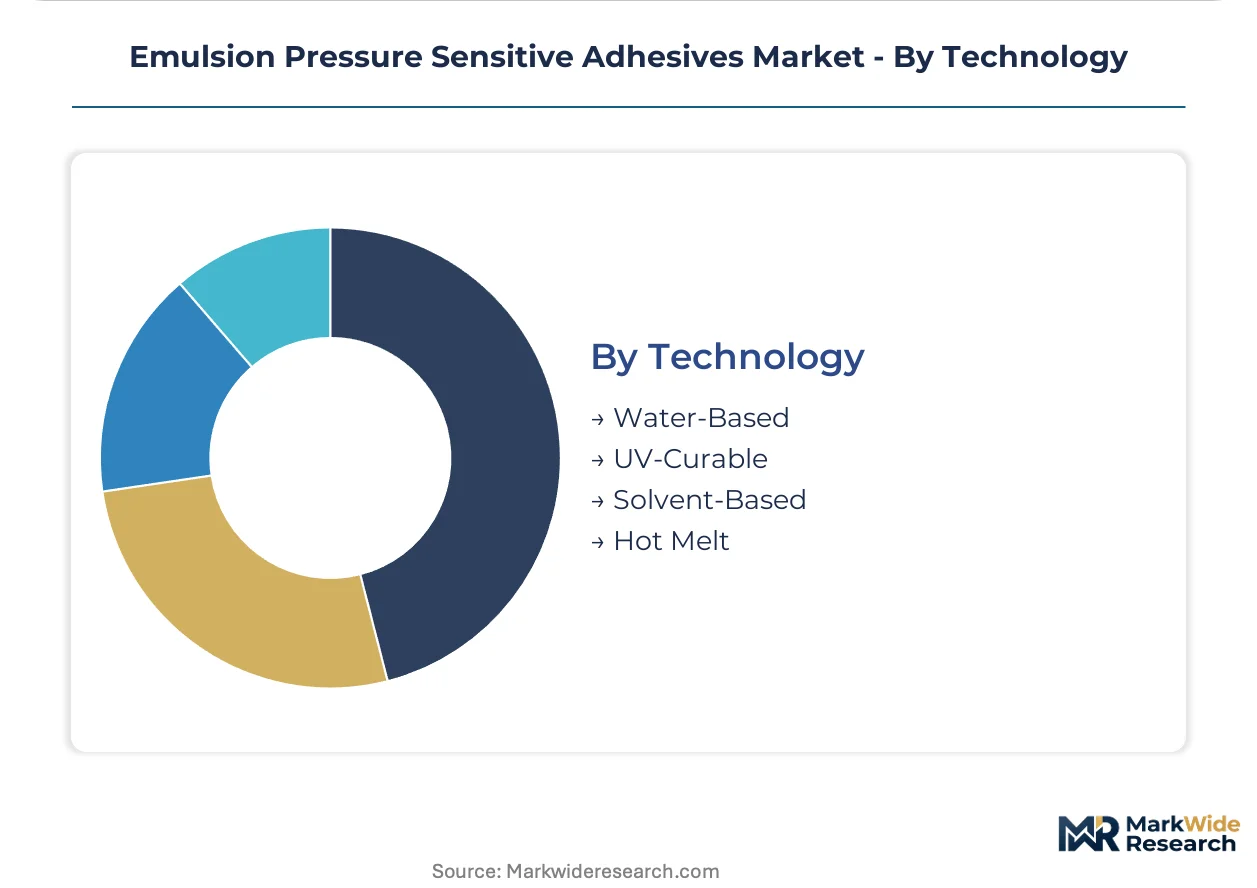
Technology segmentation captures the platform shift from solvent systems to aqueous and energy-cured alternatives.
- Water-Based:40-60% solids acrylic emulsion dispersions forming tacky films upon drying. EPA VOC mandates and China's MEE emission standards are accelerating converter transitions away from solvent recovery infrastructure.
- UV-Curable:Photoinitiated crosslinking of water-based dispersions for instant handling strength. Electronics assemblers in Japan and Germany specify these for clean-edge bonding without thermal damage.
- Solvent-Based:Declining share as thermal oxidizer investments become uneconomic under tightening emission regulations.
- Hot Melt:100% solids block copolymer systems competing in high-speed packaging applications where water-based drying speeds are insufficient.
Water-Based holds dominant position; UV-Curable is gaining share fastest on electronics assembly requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity as automotive OEMs prioritize performance certification over formulation cost, while Indian packaging converters and Chinese industrial assemblers drive hard volume negotiations that compress regional margin structures.
Germany
Automotive interior lamination and headliner assembly specifications from Stuttgart-based OEMs anchor premium-grade emulsion PSA procurement. REACH compliance timelines for novel tackifier chemistries extend development cycles through ECHA substance evaluation protocols. Suppliers in Baden-Württemberg are consolidating technical service capabilities to meet compressed twelve-week validation windows.
United States
EPA VOC mandates on industrial coatings are dismantling solvent recovery infrastructure at Wisconsin and California coating facilities. Beverage brand procurement consolidation to three preferred adhesive partners per region is displacing legacy distributor networks. Midwest packaging converters are eliminating thermal oxidizer investments through aqueous system transitions.
China
MEE emission standards and dual carbon goals are accelerating converter shifts from solvent-based systems in Yangtze River Delta manufacturing clusters. Electronics assemblers in Shenzhen specify UV-curable hybrid emulsions for display panel bonding without thermal damage. Domestic supply gaps in high-performance acrylic emulsions sustain import dependence for medical-grade applications.
Japan
METI industrial efficiency guidelines and automotive lightweighting targets drive dashboard lamination specifications in Toyota City supplier parks. Electronics manufacturers in Osaka prefecture demand instant-handling-strength formulations for semiconductor temporary masking. PMDA biocompatibility pathways for wearable device adhesives extend qualification timelines.
India
Food and beverage labeling demand in Maharashtra and Gujarat outpaces domestic emulsion PSA production capacity, creating import substitution openings. FSSAI packaging safety regulations and DGFT chemical import classifications complicate formulation standardization. Gujarat-based converters are trialing freezer-grade acrylic emulsions for cold-chain logistics expansion.
Emulsion Pressure Sensitive Adhesives Market Vendor Landscape
Integrated chemical conglomerates and specialized adhesive formulators split the market between scale-driven supply contracts and technical service-intensive niche applications. Three archetypes dominate: diversified materials science groups with captive polymer production, regional packaging adhesive specialists with coating-line integration, and medical-grade purity players with FDA pathway expertise. Competitive intensity centers on M&A consolidation of regional coating assets and strategic partnerships with automotive tier suppliers for co-development programs.
Among European-based diversified groups, Henkel AG & Co. KGaA and Arkema Group exemplify the technical-center archetype for automotive and medical applications respectively. H.B. Fuller Company occupies a position within North American packaging adhesive supply. These three entities represent the spectrum from integrated materials science to geographic specialization, with each anchoring distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Avery Dennison Corporation |
| Ashland Inc. |
| American Biltrite Inc. |
| APEC, Ltd |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility determines both tiered pricing spreads across premium acrylic emulsions and standard water-based grades and the geographic clustering of polymer production assets near naphtha crackers in Germany, South Korea, and the United States. This single-source dependency on crude oil derivatives compresses formulation margins during supply shocks while concentrating supply chain leverage with integrated chemical conglomerates.
Pricing Analysis
Aftermarket service revenue for adhesive formulation tuning is narrowing as manufacturers push integrated supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant medical grades from automotive certification tiers and commodity packaging formulations. Cost compression in standard grades is intensifying because beverage brand procurement consolidation to three preferred partners per region squeezes converter margins. Indian packaging converters exhibit highest price sensitivity, while German automotive OEMs prioritize performance certification over formulation cost.
Supply Chain Analysis
Upstream acrylic monomer production draws from naphtha crackers concentrated in Germany, South Korea, and the United States. Formulators depend on imported tackifier resins from pine chemical processors in the southeastern United States and Southeast Asian gum rosin operations. Single-source vulnerability in high-purity acrylic acid for medical-grade emulsions threatens supply continuity for wearable device manufacturers. Distribution runs through direct technical partnerships with major converting accounts, displacing legacy distributor networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH authorization timelines and FDA 510(k) pathways create eighteen-to-thirty-six-month barriers that protect qualified incumbents from rapid competitive entry.
For Market Incumbents: Entrench position by consolidating technical service capabilities in Baden-Württemberg to meet compressed twelve-week automotive validation windows. Backward integration into captive acrylic emulsion production mitigates petrochemical feedstock volatility. Certification investment in FDA biocompatibility pathways for skin-contact grades creates switching-cost barriers against emerging Asian suppliers.
For New Entrants and Emerging Players: Mid-market freezer-grade labeling demand in Maharashtra and Gujarat represents the most penetrable entry point, with domestic supply gaps sustaining import substitution premiums. UV-curable hybrid emulsion systems for Japanese electronics assemblers offer technology-differentiated positioning without direct confrontation with established water-based incumbents. Go-to-market execution should anchor on direct technical partnerships with regional beverage converters rather than distributor channel penetration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional coating asset acquisition over greenfield capacity buildout. Long-term viability hinges on exposure to medical-grade purity segments with FDA pathway expertise rather than commodity packaging volumes. Watch ECHA microplastic restriction timelines as an inflection indicator for enzymatically degradable tackifier system adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply of high-purity monomers insulates margin structures from naphtha price volatility. |
| Green Manufacturing Transition | EU Green Deal procurement mandates favor bio-based tackifier feedstocks for public sector specification windows. |
| Long-term Supply Agreement | Integrated contracts bundling adhesive formulation with substrate specification displace legacy converter procurement models. |
| Joint Venture with Automotive Tier Supplier | Co-development programs in Stuttgart and Toyota City compress validation cycles for dashboard lamination specifications. |
| Capacity Expansion in Gujarat | Regional production addresses import substitution potential as FSSAI regulations complicate standardization for Maharashtra converters. |
Methodological Framework
Desk research of trade association publications, customs filings, and regulatory submission databases preceded structured interviews with adhesive formulation scientists, automotive tier supplier procurement managers, packaging converter operations heads, and medical device regulatory affairs leads. Secondary validation drew from ECHA substance evaluation protocols, EPA VOC compliance filings, SEC 10-K disclosures from diversified chemical groups, and ACC sector reports. Bottom-up volume modeling across end-use segments triangulated against top-down macroeconomic indicators.
Assumptions held regulatory timelines and crude oil derivative pricing as variable inputs while fixing polymerization technology diffusion curves and automotive lightweighting targets across the projection horizon. Segmentation dimensions modeled include formulation permanence grade, substrate application, curing technology platform, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating OEM specification shifts and converter infrastructure replacement cycles. Industry-specific inputs captured REACH authorization delays and MEE emission standard enforcement trajectories.
Practitioners should monitor ECHA microplastic consultation outcomes and FDA 510(k) backlog clearance rates for early signals of qualification timeline compression. Cross-checking against IHS Markit automotive production forecasts and Cefic chemical output indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market