
 Melamine Formaldehyde (MF) Market | 2026-2036
Melamine Formaldehyde (MF) Market Size, Share, and Industry Trends Forecast 2026-2036
Melamine Formaldehyde (MF) Market Foresight
REACH is broadening the cost-of-entry calculus for European melamine formaldehyde suppliers by mandating stricter formaldehyde emission classifications and expanded chemical safety documentation. BASF SE leverages its integrated precursor supply chain to absorb regulatory compliance costs without fragmenting its European manufacturing footprint. Hexion Inc. anchors its competitive position through specialized low-emission resin technology that aligns with evolving EU product standards. Mitsui Chemicals, Inc. competes by extending its Asia-Pacific distribution network to serve laminate exporters seeking REACH-equivalent certification for European market access.
Melamine formaldehyde is a thermosetting amino resin synthesized from melamine and formaldehyde condensation, typically cured at 130-160°C to produce cross-linked polymers with high hardness, thermal stability, and scratch resistance for surface coatings, decorative laminates, and wood adhesives. Powder formulations dominate volume consumption in laminate manufacturing due to their storage stability and precise metering in hot-press applications, while liquid resins command margin premiums in automated adhesive coating systems for engineered wood panels. The construction end-user segment leads absolute demand as residential and commercial building activity sustains consumption of MF-impregnated decorative papers and flooring substrates.
EMA maintains stringent oversight of formaldehyde-based substances under REACH and CLP classifications, compelling reformulation investments that reshape supplier cost structures and product portfolios. EPA regulations in the United States, particularly the Formaldehyde Standards for Composite Wood Products Act, impose parallel compliance burdens on imports and domestic manufacturers alike. GB standards in China govern indoor air quality thresholds for wood-based panels, creating divergent testing regimes that multinational suppliers must navigate simultaneously. Stakeholders should monitor regulatory harmonization pressures between major economies, as alignment or divergence in emission standards will determine which formulation technologies and geographic production bases capture sustained preference.
Market Dynamics
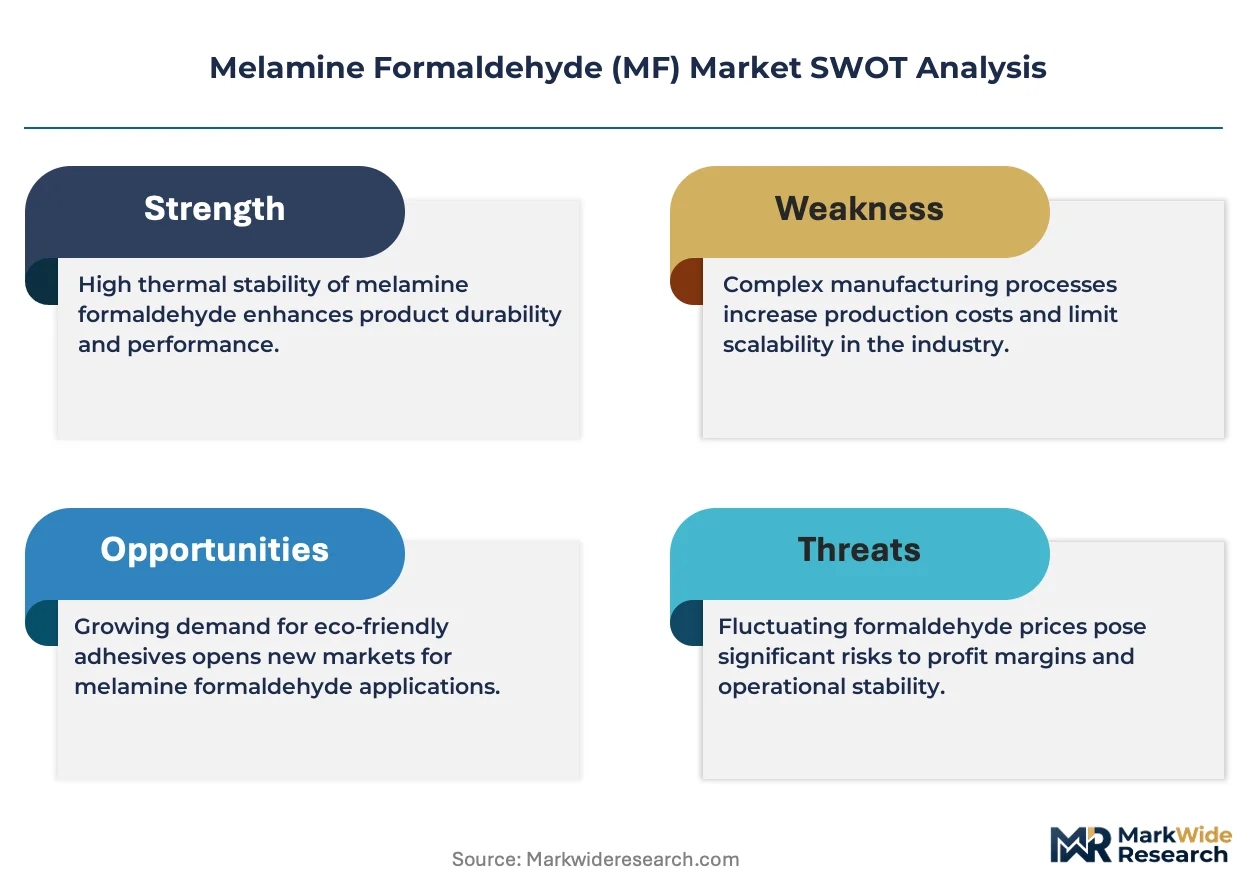
REACH compliance costs are restructuring European supplier economics while Chinese laminate exports absorb incremental volume, creating divergent margin pressures across production bases.
Growth Catalysts
- Residential construction recovery:Housing starts in Germany and France sustain decorative laminate consumption for kitchen cabinetry and flooring substrates.
- REACH low-emission mandates:ECHA's tightened formaldehyde classification pushes reformulation demand that locks in premium resin pricing for compliant suppliers.
- Hot-press automation:Powder MF formulations enable precise metering systems that reduce waste in high-speed laminate manufacturing lines.
Market Restraints
- Formaldehyde price volatility:Methanol feedstock fluctuations transmit directly to MF resin cost structures, compressing blender margins during energy price spikes.
- European supply concentration:BASF and Hexion control majority regional capacity, limiting buyer negotiating leverage on specialty low-emission grades.
- Cross-link density limitations:Thermoset curing above 150°C restricts MF applications in temperature-sensitive substrate bonding.
Strategic Opportunities
- India furniture manufacturing:BIS certification alignment with EU emission standards opens export pathways for laminate producers seeking REACH-equivalent market access.
- Electric vehicle interior panels:Lightweight MF-impregnated decorative layers meet automotive OEM flame-retardancy requirements for cabin trim applications.
- EU Green Deal procurement:Public construction tenders now mandate EPD-certified materials, creating preference pull for low-carbon resin formulations.
Industry Challenges
- Specialized resin chemist scarcity:Formulation expertise for sub-0.1 ppm emission targets concentrates among retiring technical staff at legacy European producers.
- Multi-jurisdiction testing burden:Simultaneous EPA TSCA Section 5, REACH SVHC, and GB 18580 compliance requires redundant analytical protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melamine Formaldehyde (MF) Market |
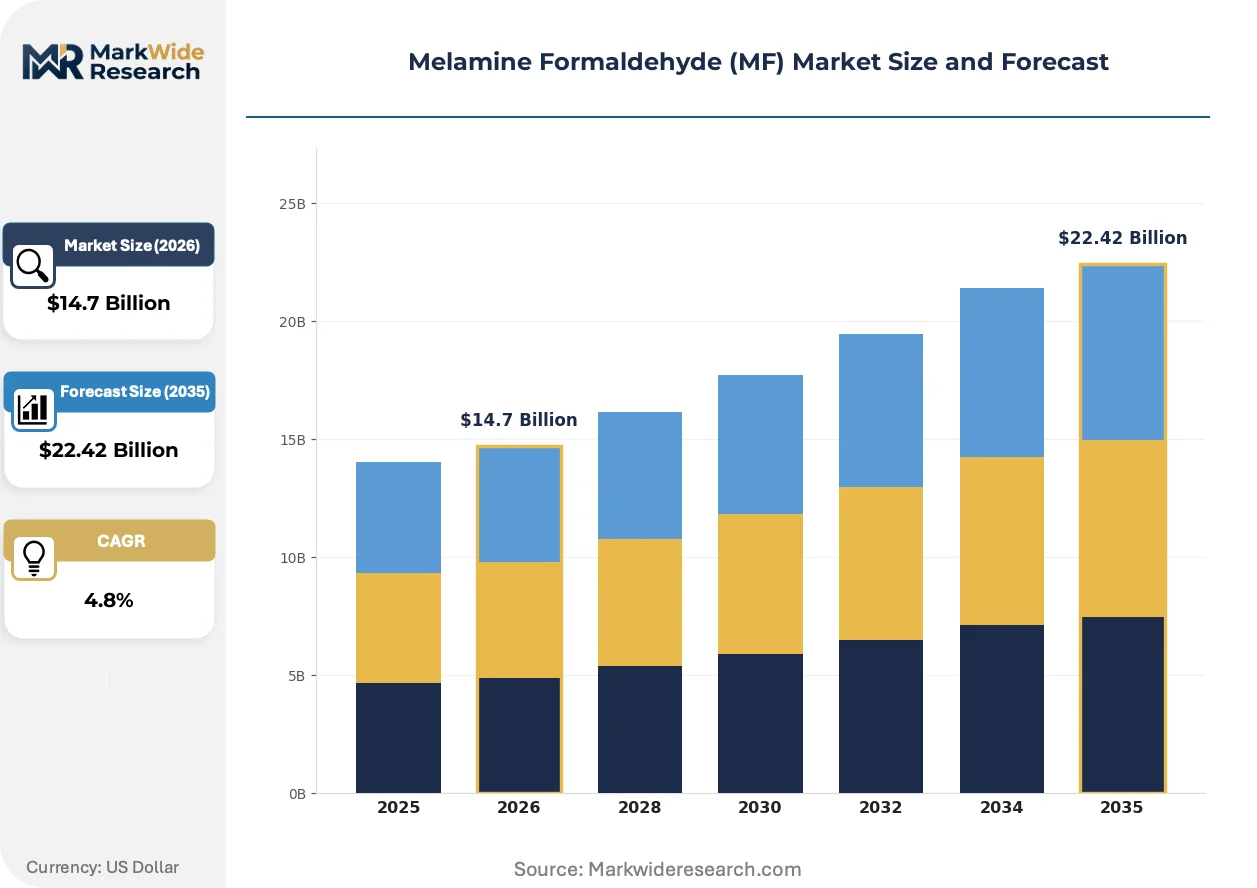
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Liquid, Resin Application: Adhesives, Coatings, Surface Materials, Laminates End User: Construction, Automotive, Furniture, Electronics Delivery Mode: Direct Supply, Retail, Online Distribution, Wholesale |
| Companies Covered | BASF SE, Hexion Inc., Allnex GmbH, Prefere Resins Holding GmbH, Georgia-Pacific Chemicals LLC, Mitsui Chemicals, Inc., INEOS Melamines GmbH, Huntsman International LLC, OCI Nitrogen BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melamine Formaldehyde (MF) Market Shifts & Advancements
Formulation chemistry and regulatory measurement protocols are converging to redefine competitive advantage around emission performance rather than traditional hardness metrics.
Low-emission melamine-urea-formaldehyde hybrid resins are consolidating technical preference among European decorative paper impregnators. Flooring manufacturers in Belgium and the Netherlands specify these systems to preempt ECHA reclassification risks. The technology is consolidating supplier tiers by eliminating mid-tier blenders lacking precursor integration.
REACH Annex XVII formaldehyde restrictions are tightening testing protocols for wood-based panels sold in EU member states. Laminate producers must now demonstrate compliance through chamber testing rather than derived emission calculations. German kitchen furniture exporters face the steepest adaptation curve as their supply chains retool analytical capabilities.
Certification-driven specification is displacing price-first procurement in commercial construction channels. Facility managers in France and Sweden now require EPD and Cradle-to-Cradle documentation for interior fit-out materials. This shift concentrates purchase authority among technical buyers at major construction groups, reducing distributor influence.
Melamine Formaldehyde (MF) Market Segmentation
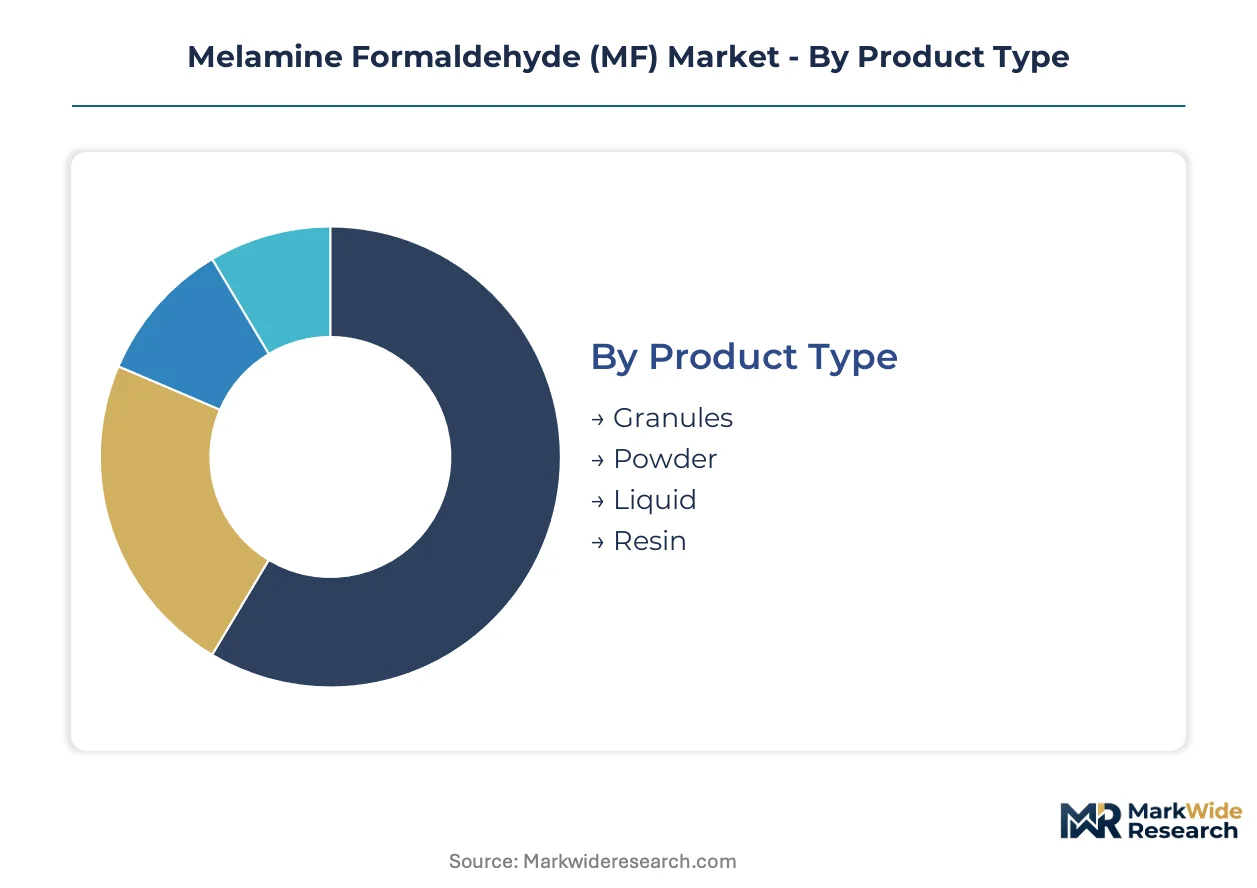
MF market segmentation reveals how formulation chemistry and delivery logistics create divergent margin profiles. Buyers select product formats and supply channels based on press automation levels, emission compliance requirements, and batch scale economics.
Product Type:
Upgrade cycles in laminate manufacturing favor formats that reduce press changeover downtime and stabilize inventory holding costs.
- Granules:Pelletized MF resins offer controlled dissolution rates for batch adhesive blending in mid-scale furniture operations. European decorative paper impregnators favor granules for their reduced dust exposure during manual handling.
- Powder:Spray-dried formulations dominate high-speed laminate lines through precise metering compatibility and extended storage stability without refrigeration. German flooring manufacturers specify powder grades for continuous hot-press operations where moisture control determines surface quality.
- Liquid:Aqueous resin solutions serve automated roll-coating systems in engineered wood panel production. Viscosity stability requirements limit liquid adoption to facilities with temperature-controlled storage infrastructure.
- Resin:Unprocessed condensation intermediates supply captive blending operations at integrated laminate producers. Chinese decorative panel manufacturers source resin intermediates to customize cure profiles for regional substrate variations.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid as coating automation spreads beyond traditional laminate centers.
Application:
Application selection tracks substrate bonding requirements and surface durability specifications across end-use industries.
- Adhesives:MF-urea hybrid resins bond particleboard and medium-density fiberboard in furniture and construction panels. REACH low-emission mandates in Belgium and the Netherlands push adhesive formulators toward reduced formaldehyde release classifications.
- Coatings:Cross-linked MF resins provide hard, thermally stable surface finishes for metal and wood substrates. Automotive interior trim specifications in Germany leverage MF coatings for scratch resistance and flame-retardant performance.
- Surface Materials:Impregnated decorative papers create wear-resistant laminates for countertops and flooring. Swedish kitchen furniture exporters specify surface materials with EPD certification to satisfy public procurement requirements.
- Laminates:High-pressure decorative laminates represent the largest volume outlet through residential and commercial construction demand. French hospital and school renovation programs sustain laminate consumption for hygienic, durable interior surfaces.
Margin concentration sits with Laminates; Coatings are climbing the fastest as automotive lightweighting drives interior panel specification changes.
End User:
End-user demand patterns reflect construction cycle timing, automotive platform launches, and furniture export certification requirements.
- Construction:Residential and commercial building activity consumes MF-impregnated flooring substrates and decorative panels. German housing starts and French public infrastructure programs anchor construction demand for emission-compliant laminate systems.
- Automotive:Electric vehicle cabin trim applications specify lightweight MF-impregnated layers meeting OEM flame-retardancy standards. Tier-1 suppliers in Stuttgart and Munich coordinate resin qualification for next-generation interior platforms.
- Furniture:Kitchen cabinetry and office systems drive decorative laminate consumption through durability and aesthetic requirements. Indian furniture manufacturers seek BIS certification alignment with EU emission standards to unlock export pathways.
- Electronics:Printed circuit board substrates and electrical insulation components utilize MF resins for thermal stability. Japanese electronics manufacturers specify high-purity grades for miniaturized component housings.
Revenue scale favors Construction; Automotive offers the steepest expansion trajectory as EV interior redesigns accelerate material qualification cycles.
Delivery Mode:
Delivery channel selection depends on order scale, formulation customization needs, and inventory financing constraints.
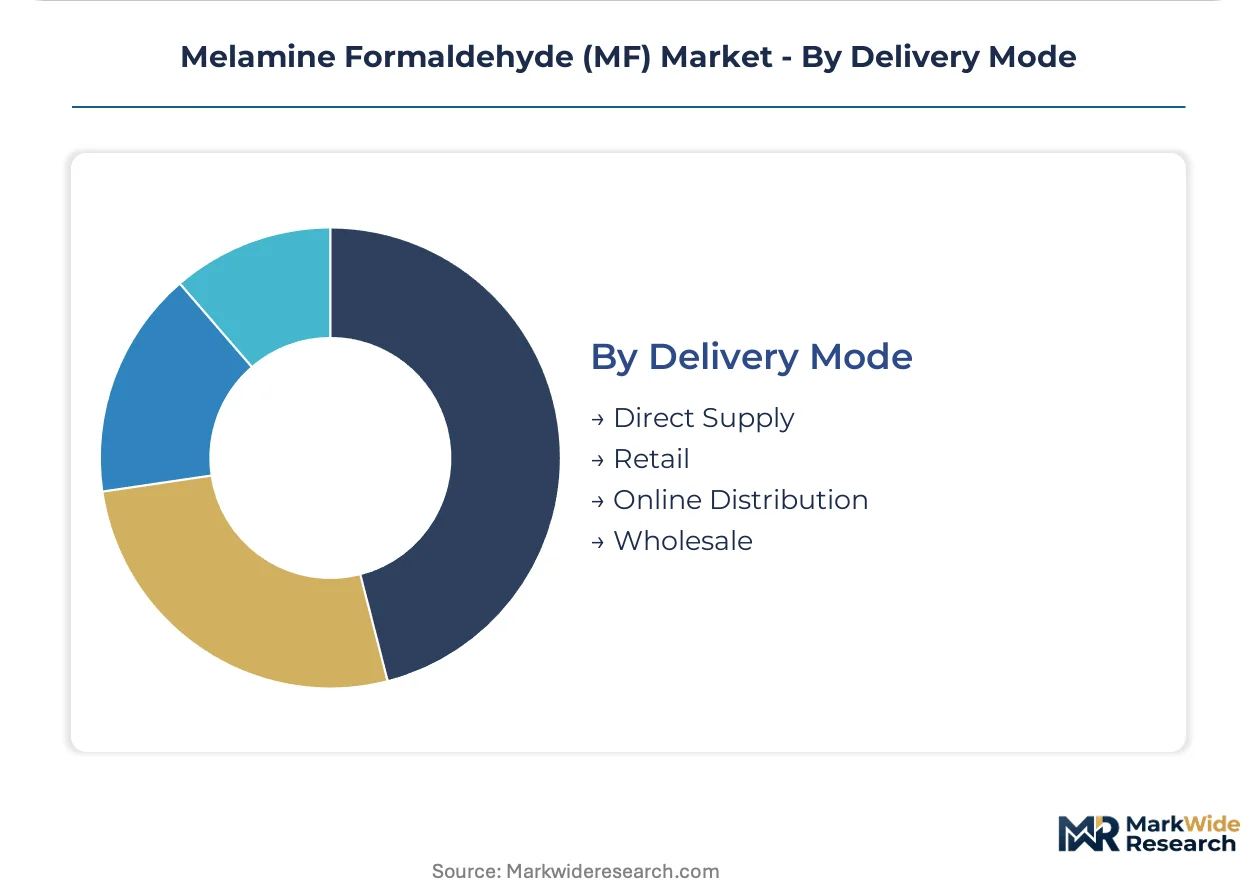
- Direct Supply:Long-term contracts link integrated resin producers with high-volume laminate manufacturers. BASF and Hexion anchor European direct supply relationships through dedicated tanker delivery and technical service support.
- Retail:Small-batch powder and liquid resins reach independent furniture workshops through specialized chemical distributors. French and Italian woodworking supply chains rely on retail channels for just-in-time adhesive replenishment.
- Online Distribution:Digital procurement platforms serve mid-scale buyers seeking transparent pricing and rapid order fulfillment. Chinese laminate producers utilize cross-border e-commerce for REACH-certified resin sourcing.
- Wholesale:Regional distributors aggregate demand from fragmented furniture and construction customers. German wholesale networks consolidate smaller orders to achieve tank-wagon pricing thresholds.
Shipment value concentrates in Direct Supply; Online Distribution is gaining share fastest as procurement digitization penetrates mid-tier manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese laminate exports and European regulatory compliance reshape regional demand distribution, with construction cycles and emission standards driving divergent procurement patterns across major economies.
China
Urbanization sustains decorative panel consumption for residential interiors and furniture export manufacturing. GB standards govern indoor air quality thresholds for wood-based panels sold domestically. The Yangtze River Delta hosts concentrated laminate production serving both domestic construction and international buyers seeking REACH-equivalent certification.
Germany
Housing starts in metropolitan regions sustain decorative laminate demand for kitchen cabinetry and flooring substrates. ECHA's tightened formaldehyde classification under REACH mandates reformulation investments from resin suppliers. The Cologne-Düsseldorf industrial corridor anchors European MF resin production capacity with integrated precursor supply chains.
United States
Residential construction recovery drives consumption of MF-impregnated flooring and decorative panels. EPA regulations under the Formaldehyde Standards for Composite Wood Products Act impose compliance burdens on imports and domestic manufacturers. Georgia-Pacific Chemicals LLC anchors southern production capacity serving Gulf Coast and Southeast building markets.
India
Furniture manufacturing expansion creates demand for adhesive-grade MF resins in particleboard and medium-density fiberboard bonding. BIS certification alignment with EU emission standards opens export pathways for laminate producers. Gujarat and Maharashtra host emerging decorative panel clusters seeking technical qualification for European market access.
Japan
Electronics and automotive interior applications sustain demand for high-purity MF grades in printed circuit board substrates and cabin trim components. METI oversees chemical safety documentation requirements for resin formulations. The Nagoya industrial zone coordinates resin qualification for next-generation electric vehicle interior platforms.
Melamine Formaldehyde (MF) Market Competitive Landscape
German producers anchor the premium resin tier; Chinese specialists hold volume positions in standard-grade laminate feedstocks. The market structure concentrates among integrated chemical conglomerates with captive melamine supply and regional specialists serving formulation-specific niches. Three archetypes dominate: integrated precursors-to-resin operators, low-emission technology licensors, and Asia-Pacific distribution networks. Capacity expansion and regulatory technology licensing constitute the dominant competitive vectors.
Among European integrated operators, BASF SE exemplifies the precursor-integrated archetype with cost absorption capacity for compliance investments. Hexion Inc. and Mitsui Chemicals, Inc. occupy distinct positioning vectors—Hexion as a technology-focused formulator, Mitsui as an Asia-Pacific network anchor serving export-oriented laminate manufacturers. These three represent the strategic poles around which mid-tier blenders and regional distributors organize.
| Leading Market Players |
|---|
| BASF SE |
| Hexion Inc. |
| Allnex GmbH |
| Prefere Resins Holding GmbH |
| Georgia-Pacific Chemicals LLC |
| Mitsui Chemicals, Inc. |
| INEOS Melamines GmbH |
| Huntsman International LLC |
| OCI Nitrogen BV |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap resin blenders in Belgium and the Netherlands anchor spot-market liquidity for standard-grade powder formulations, while their limited balance-sheet capacity constrains inventory financing and amplifies price volatility during methanol feedstock spikes. Their ownership structure limits long-term contracting discipline, forcing reliance on quarterly price negotiations that cascade volatility downstream to laminate manufacturers.
Pricing Analysis
Short-lead-time premiums of 8-12% apply to REACH-certified liquid resins ordered on sub-30-day cycles, while spot inventory of uncertified powder trades at discounts to contract benchmarks. Contract-based long-term offtake dominates volume placement, with price differentiation resting on emission certification tier and captive melamine supply. Cost compression in standard-grade powder is intensifying because Chinese export capacity is expanding into European spot channels. Small-batch furniture workshops show highest price sensitivity; automotive Tier-1 suppliers show least.
Supply Chain Analysis
EU Green Deal domestic-content mandates for public construction procurement are reshaping sourcing toward European-formulated low-emission grades, reducing reliance on imported intermediates. Geographic supply concentrates in Germany, China, and Belgium, with raw material dependencies drawing from methanol, melamine crystal, and formaldehyde gas feedstocks. Single-source vulnerability sits with melamine precursor supply from integrated petrochemical complexes. Distribution runs through direct tanker delivery for high-volume laminate producers and regional wholesale networks for fragmented furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance investments are forcing a consolidation play as mid-tier blenders lacking precursor integration face exit pressure from reformulation cost burdens.
For Market Incumbents: Cement market position by acquiring distressed formulation assets in the Cologne-Düsseldorf corridor to lock in technical staff scarcity for sub-0.1 ppm emission targets. Expand captive melamine supply through backward integration into regional precursor production, neutralizing formaldehyde price volatility that compresses blender margins. For New Entrants and Emerging Players: Automated coating system compatibility offers entry leverage into automotive interior panel supply chains, where EV platform redesigns are accelerating material qualification cycles. Target Indian laminate exporters seeking BIS certification alignment with EU emission standards, deploying technical service teams to guide certification navigation as the go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor European low-emission technology licensors with stranded customer relationships from failing mid-cap blenders. Long-term viability over a 5-10 year window rests on regulatory technology licensing revenue streams rather than commodity resin volume. Watch ECHA formaldehyde reclassification timing as the inflection signal for premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Precursors | Captive supply from BASF's Ludwigshafen complex neutralizes feedstock volatility for European resin production. |
| REACH-Equivalent Certification Program | BIS alignment unlocks export pathways for Indian laminate producers targeting EU public procurement tenders. |
| Automotive Interior Platform Qualification | Stuttgart and Munich Tier-1 supplier coordination secures specification for EV cabin trim flame-retardant layers. |
| Low-Emission Formulation Licensing | Hexion's specialized resin technology transfers compliance burden to mid-tier blenders lacking R&D capacity. |
| Digital Procurement Platform Expansion | Cross-border e-commerce penetration reduces distributor influence among Chinese mid-scale laminate manufacturers. |
Research Methodology
Multi-period observation of housing starts, laminate export volumes, and formaldehyde emission test submission rates anchored the trend analysis, supplemented by interviews with resin plant managers, procurement leads at German flooring OEMs, distribution channel partners in France and Italy, and technical R&D directors at integrated chemical producers. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed resin producers, and ECHA substance registration databases. Bottom-up volume estimates from press capacity utilization and top-down demand calibration from construction activity indices were triangulated to cross-check segment outputs.
Segment-weighting across product format, application, end-use industry, and regional production hub dimensions structured the analytical framework across the analysis window. CAGRs were derived from regression-based trend extrapolation with elasticity adjustments for regulatory threshold effects. Industry-specific forecast inputs included methanol price trajectory assumptions and REACH implementation timeline phasing for formaldehyde emission reclassification.
Several conditions sit outside the modeled scope, including potential REACH-EPA regulatory harmonization or divergence, unforeseen feedstock supply disruptions from energy market shocks, and technology substitution by bio-based adhesive platforms. Forecasts reflect documented assumptions about construction cycle continuity and emission standard enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Anti-Tacking Agents Market