
 Global Butanediol Market | 2026-2036
Global Butanediol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butanediol Market Foresight
EU REACH chemical registration is recalibrating the cost-of-entry calculus for butanediol producers serving European polymer buyers. BASF SE leverages its integrated Ludwigshafen complex to sustain captive tetrahydrofuran output. LyondellBasell Industries Holdings B.V. anchors North American supply through propylene oxide-based route economics. Mitsubishi Chemical Group Corporation competes on specialized pharmaceutical-grade purity standards.
Butanediol (BDO) comprises a four-carbon diol with terminal hydroxyl groups, produced industrially via Reppe acetylene chemistry, propylene oxide hydrogenation, or maleic anhydride esterification routes yielding polymer-grade material with purities exceeding 99.5 weight percent. Its primary commercial purpose centers on tetrahydrofuran polymerization to polytetramethylene ether glycol, the soft-segment backbone for spandex elastane fibers and thermoplastic polyurethanes. Among product type segments, 1,4-Butanediol dominates volume as the feedstock standard for downstream tetrahydrofuran and gamma-butyrolactone conversion, while bio-based synthesis technology is attracting capital as fermentation routes using engineered yeast strains achieve titer improvements that narrow the cost gap against fossil-derived material. Application segments show polymers commanding the largest value pool due to spandex integration into textile manufacturing, though pharmaceutical-grade specifications carry premium pricing for solvent and synthesis intermediate uses.
The US EPA oversees chemical facility emissions under Clean Air Act provisions affecting Reppe process acetylene handling, while China's MEE enforces dual carbon goals that tighten energy-intensity benchmarks for coal-based BDO routes. Japan's METI promotes bio-based chemical roadmaps that redirect R&D subsidies toward fermentation technology scale-up. Stakeholders must monitor regulatory divergence between carbon-border adjustment mechanisms and domestic bio-preference schemes when siting new capacity or qualifying product for premium segments.
Market Dynamics
Integrated petrochemical complexes in China are compressing global production economics through backward integration into coal-based acetylene feedstocks, forcing Western producers to defend margin positions via specialty grades and bio-based differentiation.
Growth Catalysts
- Automotive lightweighting mandates:Spandex integration into seat fabrics and interior trim reduces vehicle mass. OEMs in Germany and Japan specify thermoplastic polyurethane composites derived from butanediol feedstocks.
- REACH compliance premiums:EU chemical registration creates qualified supplier lists for polymer-grade material. Registered producers capture preferential offtake from European textile manufacturers.
- Fermentation technology maturation:Engineered yeast strains achieve titer improvements that narrow cost gaps against fossil routes. Capital flows toward bio-based demonstration plants in the Netherlands and Singapore.
Market Restraints
- Propylene oxide feedstock volatility:LyondellBasell's North American route faces margin compression when propylene prices spike. Alternative Reppe chemistry requires acetylene security of supply.
- Coal-based concentration risk:Xinjiang and Ningxia provinces host over half of global nameplate capacity. Regional energy policy shifts or logistics disruptions transmit immediately to spot markets.
- Gamma-butyrolactone substitution:N-methyl-2-pyrrolidone and dimethyl sulfoxide displace GBL in select pharmaceutical solvent applications. Purity requirements limit direct substitution in polymer-grade chains.
Strategic Opportunities
- Indian spandex capacity buildout:Reliance Industries and Indorama Ventures commission downstream fiber plants. Domestic BDO qualification opens import substitution revenue.
- Japan METI bio-chemical subsidies:Fermentation scale-up grants redirect toward C4 diol platforms. Mitsubishi Chemical leverages existing pharmaceutical-grade expertise.
- Direct-to-textile-mill distribution:Integrated producers bypass merchant chemical distributors. Captive logistics contracts with Zhejiang and Guangdong fabricators secure volume commitments.
Industry Challenges
- Fermentation scale-up engineering:Contamination control and continuous processing expertise resides with industrial biotechnology specialists. Petrochemical operators face learning-curve penalties.
- Pharmaceutical-grade certification timelines:US FDA and EU EMA drug master file submissions require multi-year validation. Working capital ties up during qualification periods.
- Acetylene handling safety protocols:Reppe process operators maintain specialized pressure vessel certifications. Talent scarcity elevates maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butanediol Market |
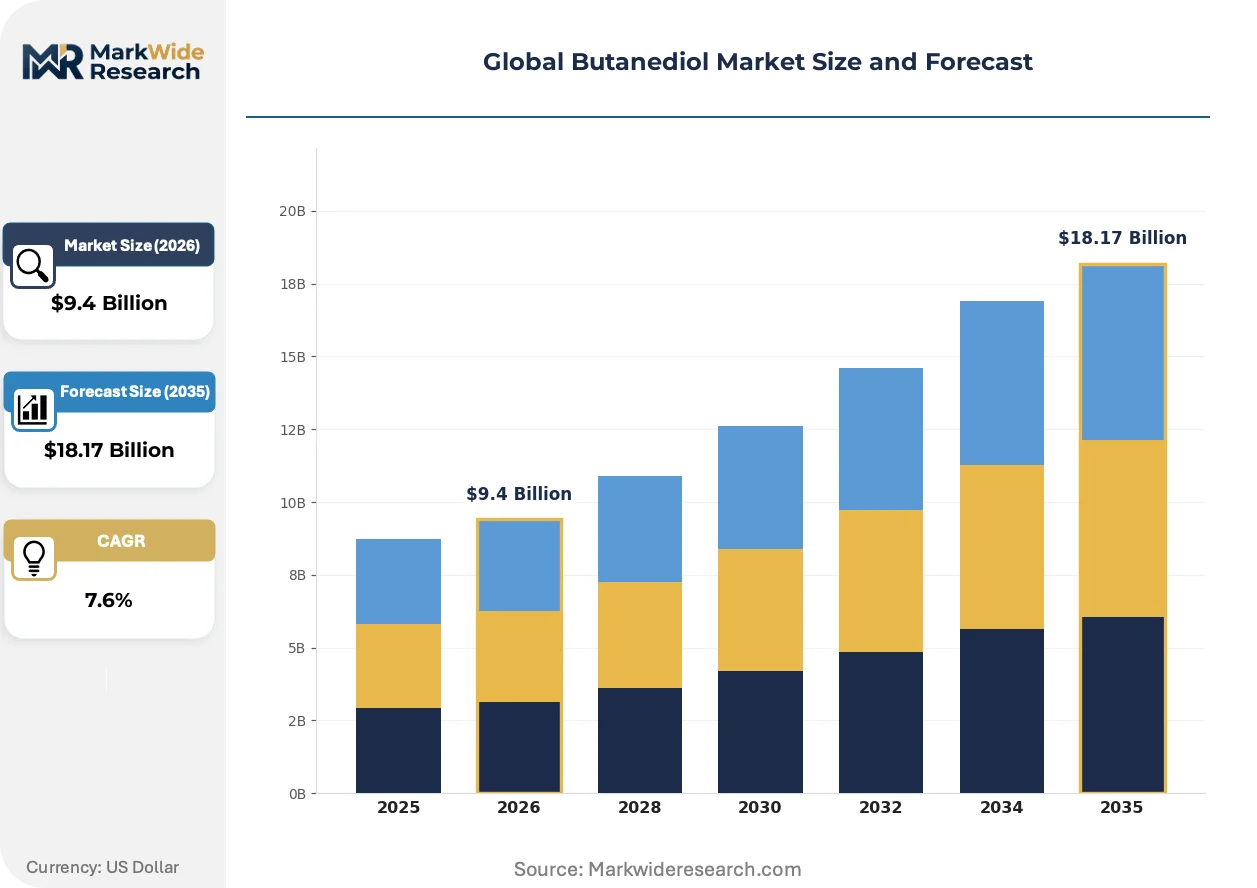
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.17 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1,4-Butanediol, 2,3-Butanediol, Tetrahydrofuran, Gamma-Butyrolactone Application: Solvents, Plasticizers, Polymers, Paints & Coatings, Pharmaceuticals, Automotive Chemicals End User Industry: Textile Manufacturing, Adhesives Production, Electronics Manufacturing, Packaging Industry Technology: Bio-Based Synthesis, Catalytic Hydrogenation, Fermentation, Chemical Synthesis |
| Companies Covered | BASF SE, LyondellBasell Industries Holdings B.V., Dairen Chemical Corporation, Mitsubishi Chemical Group Corporation, Nan Ya Plastics Corporation, Xinjiang Tianye Group Co., Ltd., Ashland, Evonik Industries AG, Sipchem Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butanediol Market Shifts & Advancements
Bio-based synthesis routes are advancing from pilot to demonstration scale, while regulatory carbon-accounting frameworks and buyer consolidation in textile manufacturing reshape competitive positioning.
Genomatica engineered yeast strains convert sugar feedstocks to bio-butane-diol through metabolic pathway optimization. Apparel brands including Lululemon and H&M specify renewable content in spandex supply agreements. This fermentation platform is expanding into polymer-grade specifications previously reserved for petrochemical material.
EU Carbon Border Adjustment Mechanism implementation creates embodied-emission tracking requirements for imported BDO derivatives. European textile manufacturers now demand supply-chain carbon disclosures from Asian suppliers. German automotive seating producers qualify lower-carbon THF streams for premium vehicle programs.
Chinese textile mills consolidate procurement through integrated chemical-fiber conglomerates. Merchant BDO distributors lose share to direct mill-gate contracts. This concentration is most visible in Zhejiang province where Sinopec and private fiber producers negotiate annual volume frameworks bypassing traditional spot markets.
Global Butanediol Market Segmentation
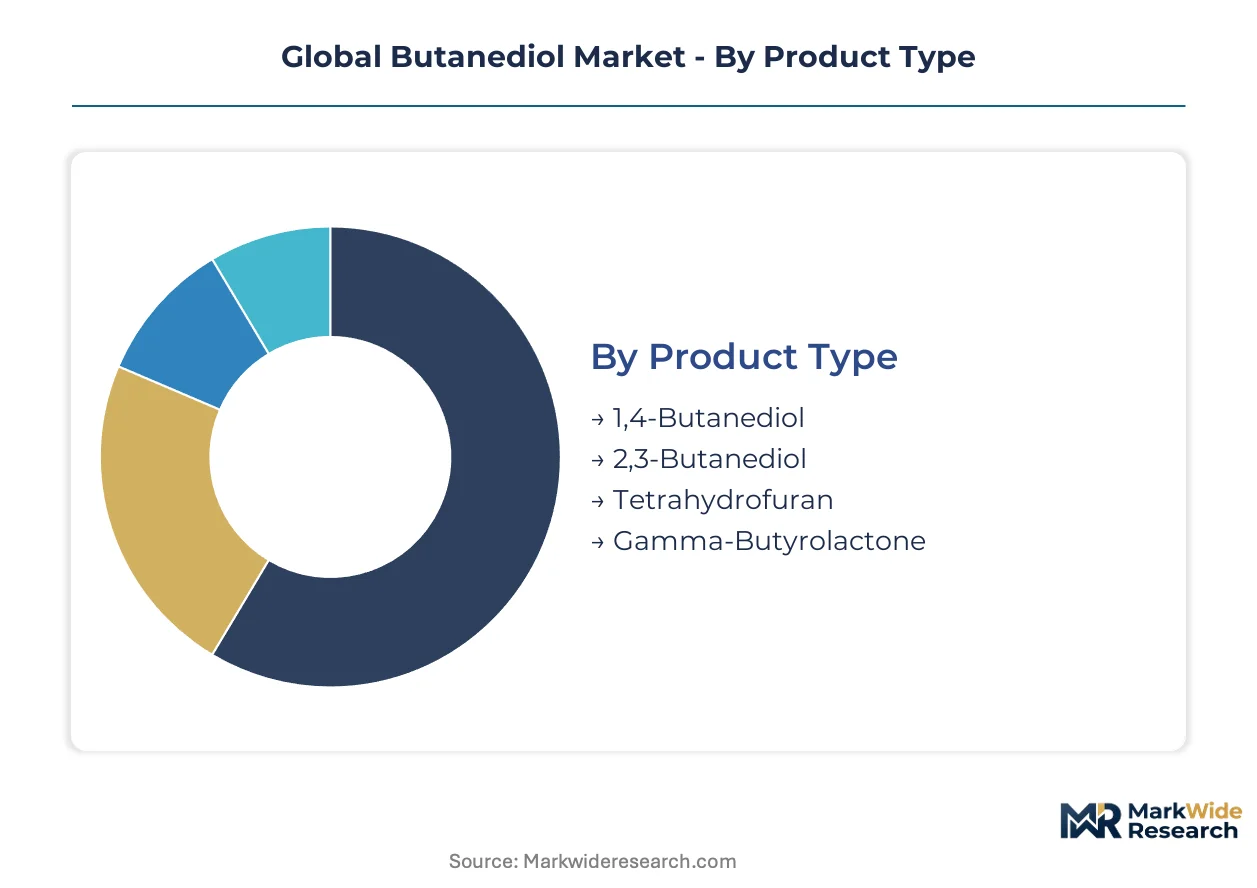
Butanediol market segmentation reveals how certification requirements, feedstock routes, and end-use specifications fragment commercial opportunities. Each dimension carries distinct regulatory burdens and margin profiles that determine supplier positioning.
Product Type:
REACH registration in Europe and US EPA chemical data reporting impose divergent documentation loads across molecular variants, with polymer-grade chains demanding the most extensive toxicology dossiers.
- 1,4-Butanediol:The standard four-carbon diol with terminal hydroxyl groups serves as the primary feedstock for tetrahydrofuran polymerization and gamma-butyrolactone conversion. Demand concentrates in China's Zhejiang and Jiangsu provinces where integrated spandex fiber producers operate captive offtake agreements with coal-based BDO suppliers.
- Tetrahydrofuran:Cyclic ether derived from BDO dehydration constitutes the essential monomer for polytetramethylene ether glycol, the soft-segment backbone in spandex elastane and thermoplastic polyurethanes. German automotive seating manufacturers specify THF-derived composites for lightweight interior programs, creating qualified supplier lists that exclude unregistered merchants.
- 2,3-Butanediol:Stereoisomer with distinct metabolic pathway applications in pharmaceutical synthesis intermediates.
- Gamma-Butyrolactone:Lactone solvent facing substitution pressure from N-methyl-2-pyrrolidone in select pharmaceutical applications.
Leading the category by volume: 1,4-Butanediol. Expanding most quickly: Tetrahydrofuran.
Application:
Cost stratification across application tiers reflects raw material sensitivity and specification stringency, with pharmaceutical and polymer grades commanding premiums over commodity solvent positions.
- Polymers:Spandex fiber production and thermoplastic polyurethane compounding absorb the majority of merchant BDO volume. Textile mills in China, India, and Vietnam qualify suppliers through annual volume frameworks that bypass spot market exposure.
- Pharmaceuticals:Solvent and synthesis intermediate applications require US FDA drug master file submissions and EU EMA certifications. Mitsubishi Chemical and BASF leverage existing pharmaceutical-grade infrastructure to defend margin positions against commodity entrants.
- Solvents:Industrial degreasing and extraction applications with lower purity thresholds.
- Plasticizers:Polyvinyl chloride compounding and flexible polymer modification.
- Paints & Coatings:Coalescing agents and flow modifiers in industrial formulations.
- Automotive Chemicals:Interior trim adhesives and sealant components.
Highest margin capture: Pharmaceuticals. Volume concentration: Polymers.
End User Industry:
Customer procurement maturity varies sharply, with textile conglomerates consolidating chemical purchasing through direct mill-gate contracts while electronics manufacturers maintain distributor relationships.
- Textile Manufacturing:Integrated fiber-chemical conglomerates in China consolidate procurement through annual volume commitments. Sinopec and private producers negotiate direct supply agreements that displace traditional merchant distributors.
- Adhesives Production:Hot-melt and reactive adhesive formulations for packaging and construction applications.
- Electronics Manufacturing:Printed circuit board cleaning and semiconductor processing solvents.
- Packaging Industry:Flexible film lamination and barrier coating applications.
Procurement consolidation furthest advanced: Textile Manufacturing. Distributor dependence persists: Electronics Manufacturing.
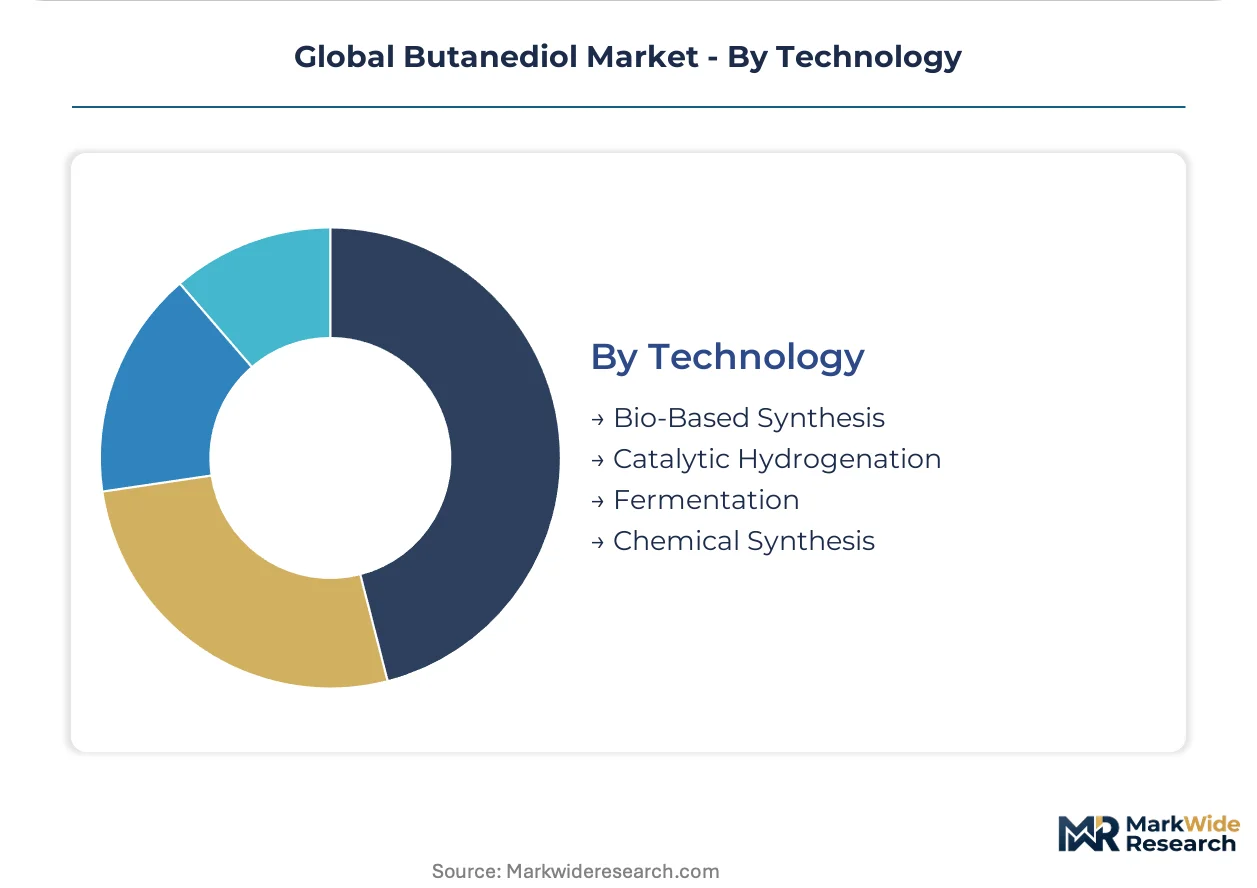
Technology:
Route economics and carbon intensity credentials increasingly determine technology selection, with fermentation platforms attracting capital despite scale-up engineering challenges.
- Bio-Based Synthesis:Genomatica engineered yeast strains convert sugar feedstocks to bio-BDO through metabolic pathway optimization. Lululemon and H&M specify renewable content in spandex supply agreements, redirecting capital toward demonstration plants in the Netherlands and Singapore.
- Chemical Synthesis:Reppe acetylene chemistry and maleic anhydride esterification routes dominate current nameplate capacity. BASF's Ludwigshafen complex and LyondellBasell's North American propylene oxide-based operations anchor fossil-derived supply.
- Fermentation:Continuous processing expertise resides with industrial biotechnology specialists; petrochemical operators face contamination control learning curves.
- Catalytic Hydrogenation:Propylene oxide hydrogenation route sensitive to olefin feedstock volatility.
Fastest capacity additions: Bio-Based Synthesis. Lowest production cost: Chemical Synthesis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's coal-chemical industrial parks concentrate over half of global butanediol nameplate capacity, leveraging stranded coal reserves and subsidized electricity tariffs to undercut naphtha-based economics. Zhejiang's integrated spandex clusters consume this captive output through direct pipeline connections, bypassing merchant markets entirely.
China
Coal-based acetylene routes in Xinjiang and Ningxia provinces supply Zhejiang's spandex fiber producers through dedicated pipeline networks. MEE dual carbon enforcement tightens energy-intensity benchmarks for coal-chemical complexes, accelerating efficiency retrofits. Ningxia's energy-chemical industrial zone hosts integrated BDO-THF-PTMEG chains serving domestic textile conglomerates.
Germany
BASF's Ludwigshafen Verbund complex sustains captive tetrahydrofuran output for European automotive seating programs. REACH registration requirements create qualified supplier barriers that exclude unregistered Asian merchants from polymer-grade offtake. Lower Rhine chemical corridor facilities qualify lower-carbon THF streams for premium OEM specifications.
United States
LyondellBasell's Gulf Coast propylene oxide-based operations anchor North American supply amid volatile olefin feedstock costs. EPA Clean Air Act provisions govern acetylene handling at Reppe process facilities, elevating compliance burdens. Texas Gulf Coast petrochemical clusters maintain strategic inventory positions for spandex and polyurethane compounders.
Japan
Mitsubishi Chemical leverages pharmaceutical-grade purity expertise to defend margin positions against commodity imports. METI bio-chemical roadmaps redirect R&D subsidies toward fermentation technology scale-up for C4 diol platforms. Kawasaki and Yokkaichi chemical complexes specialize in high-specification solvent and synthesis intermediate grades.
India
Reliance Industries and Indorama Ventures commission downstream spandex capacity, creating import substitution opportunities for qualified BDO suppliers. BIS certification requirements for polymer-grade material establish technical barriers to entry. Gujarat's chemical special economic zones attract capital for integrated fiber-chemical projects.
Global Butanediol Market Competitive Landscape
Chinese producers anchor the scale-driven tier through coal-based backward integration; European and Japanese specialists hold premium-grade positions through certification infrastructure. Market structure bifurcates between commodity volume players and purity-differentiated operators. Three archetypes dominate: integrated petrochemical conglomerates, fermentation technology developers, and pharmaceutical-grade specialists. Capacity expansion and bio-based technology licensing constitute the primary competitive vectors.
Among Germany-based chemical conglomerates, BASF SE exemplifies integrated Verbund operations that convert captive BDO through downstream tetrahydrofuran and polyurethane chains. LyondellBasell Industries Holdings B.V. occupies a position within North American olefin-based supply, representing propylene oxide route economics. Mitsubishi Chemical Group Corporation sits within the pharmaceutical-grade specialist tier, leveraging existing purity infrastructure against commodity competition.
| Leading Market Players |
|---|
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Dairen Chemical Corporation |
| Mitsubishi Chemical Group Corporation |
| Nan Ya Plastics Corporation |
| Xinjiang Tianye Group Co., Ltd. |
| Ashland |
| Evonik Industries AG |
| Sipchem Company |
| Others |
Supply & Pricing Matrix
Bio-based fermentation technology maturation simultaneously compresses production cost curves and redistributes supply chain control toward industrial biotechnology specialists with continuous processing expertise. This dual shift fragments pricing power away from traditional petrochemical conglomerates while creating new premium tiers for carbon-accounted material.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade material widen spreads against contract polymer-grade offtake, with spot inventory discounts deepening during Xinjiang capacity ramp-ups. Three-tier pricing structure across pharmaceutical, polymer-grade, and solvent-tier specifications anchors differentiation. Cost compression in commodity polymer chains intensifies because Chinese coal-based acetylene routes flood Zhejiang mill-gate contracts. Textile conglomerates exhibit highest price sensitivity; pharmaceutical compounders absorb premiums for FDA drug master file qualified supply.
Supply Chain Analysis
Acetylene feedstock supply rests on Xinjiang and Ningxia coal-chemical complexes, with propylene oxide routes anchored in Texas Gulf Coast olefin infrastructure. Critical inputs span metallurgical coal for Reppe chemistry, sugar feedstocks for Genomatica fermentation platforms, and hydrogen for catalytic hydrogenation. Single-source vulnerability concentrates in Xinjiang's pipeline-connected industrial parks. Distribution runs through direct mill-gate contracts with Zhejiang spandex producers, bypassing merchant chemical distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into coal-based acetylene or sugar-feedstock fermentation platforms defines competitive survival, with downstream THF-PTMEG chain control separating margin leaders from price-takers.
For Market Incumbents: To counter bio-based fermentation cost convergence, BASF and LyondellBasell must deepen captive THF-PTMEG integration while accelerating REACH-registered pharmaceutical-grade capacity in Ludwigshafen and Rotterdam corridors. Certification infrastructure investment defends premium positioning against commodity Chinese imports. For New Entrants and Emerging Players: EU Carbon Border Adjustment Mechanism implementation in Europe opens a window for bio-based BDO qualification with German automotive seating producers and Dutch textile manufacturers. India's Reliance-Indorama spandex buildout offers the most penetrable demand node; partner with Gujarat chemical zone developers for integrated BDO-THF-PTMEG project structuring. For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation technology licensing platforms and pharmaceutical-grade certification specialists with existing FDA drug master files. Long-term viability hinges on carbon-accounting compliance infrastructure rather than pure scale. Watch EU CBAM enforcement stringency as the inflection signal for bio-based premium capture sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Xinjiang coal-chemical complexes secure captive supply against propylene oxide volatility. |
| Bio-Based Fermentation Scale-Up | Genomatica yeast platforms qualify for Lululemon and H&M renewable content specifications. |
| REACH Registration Investment | EU chemical registration barriers exclude unregistered Asian merchants from polymer-grade offtake. |
| Direct Mill-Gate Distribution Contracts | Zhejiang textile conglomerates bypass merchant distributors through annual volume frameworks. |
| Pharmaceutical-Grade Certification | FDA drug master file submission unlocks premium solvent and synthesis intermediate pricing tiers. |
Research Methodology
Independent corroboration across plant managers at coal-chemical complexes, procurement leads at Zhejiang spandex producers, and technical R&D directors at fermentation technology developers underwrites the qualitative findings. Secondary validation draws from China customs trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings from listed petrochemical conglomerates. Bottom-up capacity tallies and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical production and consumption patterns structures the projection horizon across the analysis window. Segmentation dimensions span product grade tier, end-use industry concentration, regional production hub configuration, and technology route economics. CAGRs derive from regression-adjusted trend extrapolation incorporating spandex fiber demand elasticity, automotive lightweighting content-per-vehicle trajectories, and fermentation yield improvement curves.
The model assumes a particular technology adoption path; alternative pathways for bio-based BDO scale-up would alter the outlook if contamination control breakthroughs accelerate or sugar feedstock costs spike. Forecasts reflect documented assumptions about EU CBAM implementation timing and Chinese dual carbon enforcement intensity. A small set of triggers—MEE energy-intensity benchmark revisions, FDA pharmaceutical-grade inspection backlogs, and Indian BIS certification timeline shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Coagulant Market
Chemicals
Power Plant Chemicals Market
Chemicals
Calcium Hydride Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Thioacetic Acid Market
Chemicals
Spirodiclofen Market
Chemicals
5 Dinitroaniline Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Fluoroboric Acid Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Ethyl Chloride Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Guanidine Carbonate Market