
 Hot Melt Adhesives Market | 2026-2036
Hot Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Melt Adhesives Market Analysis
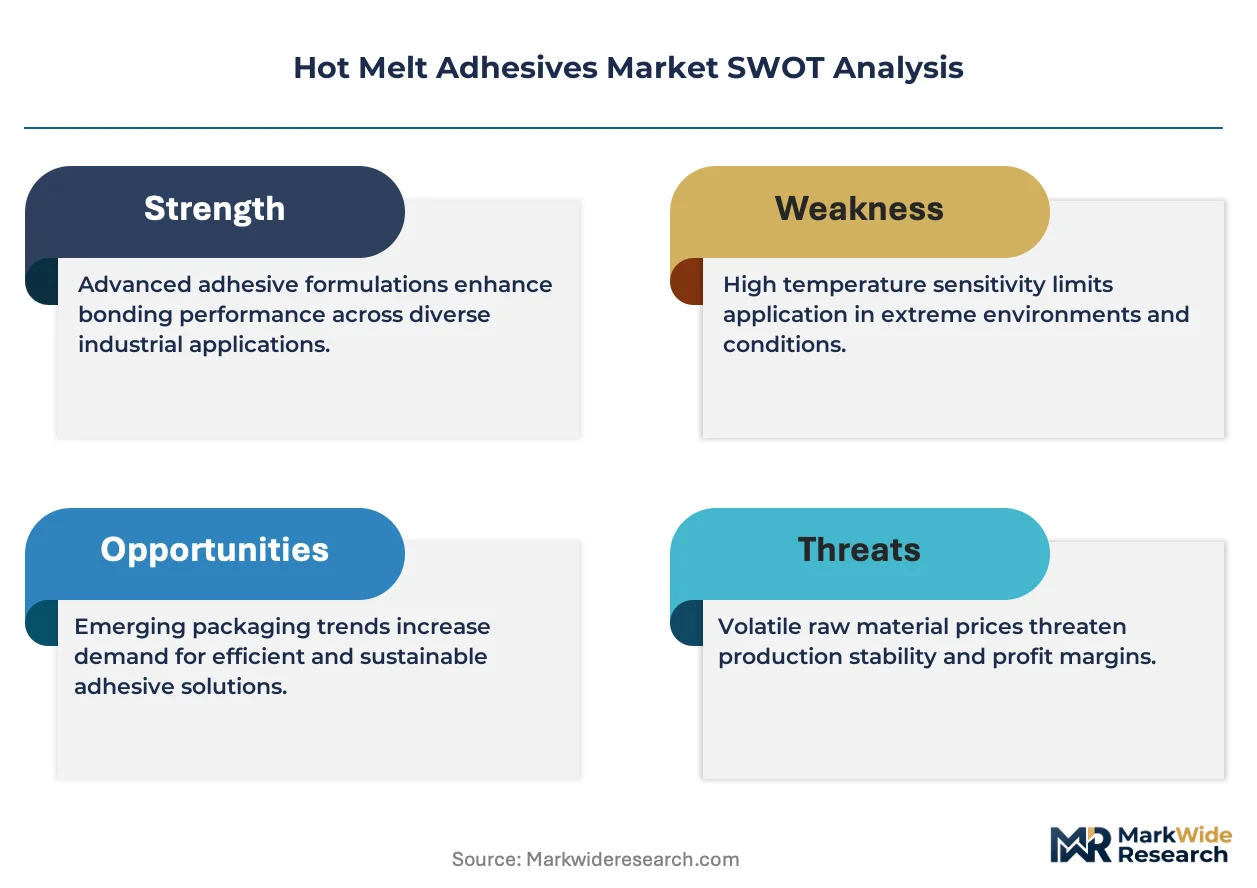
Asset-light toll manufacturing and third-party resin supply agreements is tilting competitive dynamics toward firms that avoid captive polymer production. Henkel AG & Co. KGaA leverages its European formulation network to sustain margin on customized automotive grades. H.B. Fuller Company anchors North American packaging demand through direct mill relationships. Dow Inc. competes on backward integration into ethylene vinyl acetate feedstock, while Sika AG specializes in construction-adjacent assembly applications.
Hot melt adhesives are thermoplastic polymers applied in molten state that solidify upon cooling to form bonds without solvent carriers, typically formulated from ethylene vinyl acetate, polyamide, or polyurethane base resins with tackifiers and wax modifiers for viscosity control and open-time adjustment. They serve primary industrial functions in high-speed packaging lines, automotive interior trim fixation, and electronics component mounting where rapid set speeds and clean processing matter. Ethylene vinyl acetate formulations dominate volume due to mature supply chains and cost positioning in corrugated box sealing and bookbinding. Polyurethane grades command premium positioning in automotive and electronics assembly where thermal cycling resistance and flexibility justify higher formulation costs. Polyamide adhesives occupy niche but stable demand in woodworking and specialty coating where oil and solvent resistance prove critical.
EPA industrial emissions standards and REACH chemical registration requirements in Europe shape formulation chemistry by restricting certain tackifier classes and mandating hazard communication. China's MEE enforces volatile organic compound limits on adhesive production facilities, pushing domestic manufacturers toward water-dispersed and reactive hot melt alternatives. FDA food-contact regulations in the United States govern labeling and packaging adhesive migration limits, creating compliance barriers for imported formulations. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation tailoring or unified global product platforms offer superior returns.
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization are compressing open-time requirements and thermal performance specifications, forcing reformulation cycles that favor polyurethane and polyamide grades over commodity ethylene vinyl acetate.
Growth Catalysts
- EPA Emissions Standards:Tightening volatile organic compound limits on solvent-based alternatives accelerate hot melt displacement in US packaging and automotive assembly lines.
- Polyurethane Formulation Advances:Enhanced thermal cycling resistance opens electronics mounting applications where flexible circuit boards replace rigid substrates.
- East Asian Electronics Clusters:Concentrated demand from Shenzhen, Seoul, and Tokyo drives specification premiums for high-purity polyamide grades in semiconductor packaging.
Market Restraints
- Ethylene Vinyl Acetate Feedstock Concentration:Gulf Coast petrochemical complex disruptions transmit price volatility directly to corrugated sealing and bookbinding formulations.
- REACH Chemical Registration:ECHA hazard classification requirements for certain rosin ester tackifiers force European formulators toward costlier synthetic alternatives.
- Hot Melt Equipment Capex:Precision dispensing systems for electronics assembly carry payback periods that exclude smaller contract manufacturers from specification-grade procurement.
Strategic Opportunities
- India Packaging Modernization:FSSAI food-contact compliance requirements and organized retail expansion create first-mover advantage for FDA-validated formulation suppliers.
- Construction-Adjacent Assembly:Sika AG's demonstrated model in prefabricated building modules suggests transferable positioning for hot melt specialists in modular housing joints.
- Water-Dispersed Reactive Hot Melts:China's MEE volatile organic compound enforcement pushes domestic manufacturers toward hybrid chemistries with lower facility emissions profiles.
Industry Challenges
- Polymer Rheology Expertise Scarcity:Formulation chemists capable of balancing open time, viscosity, and thermal resistance command compensation premiums that compress mid-tier margins.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, REACH, and GB standard compliance extends product launch cycles by 18-24 months for unified global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Melt Adhesives Market |
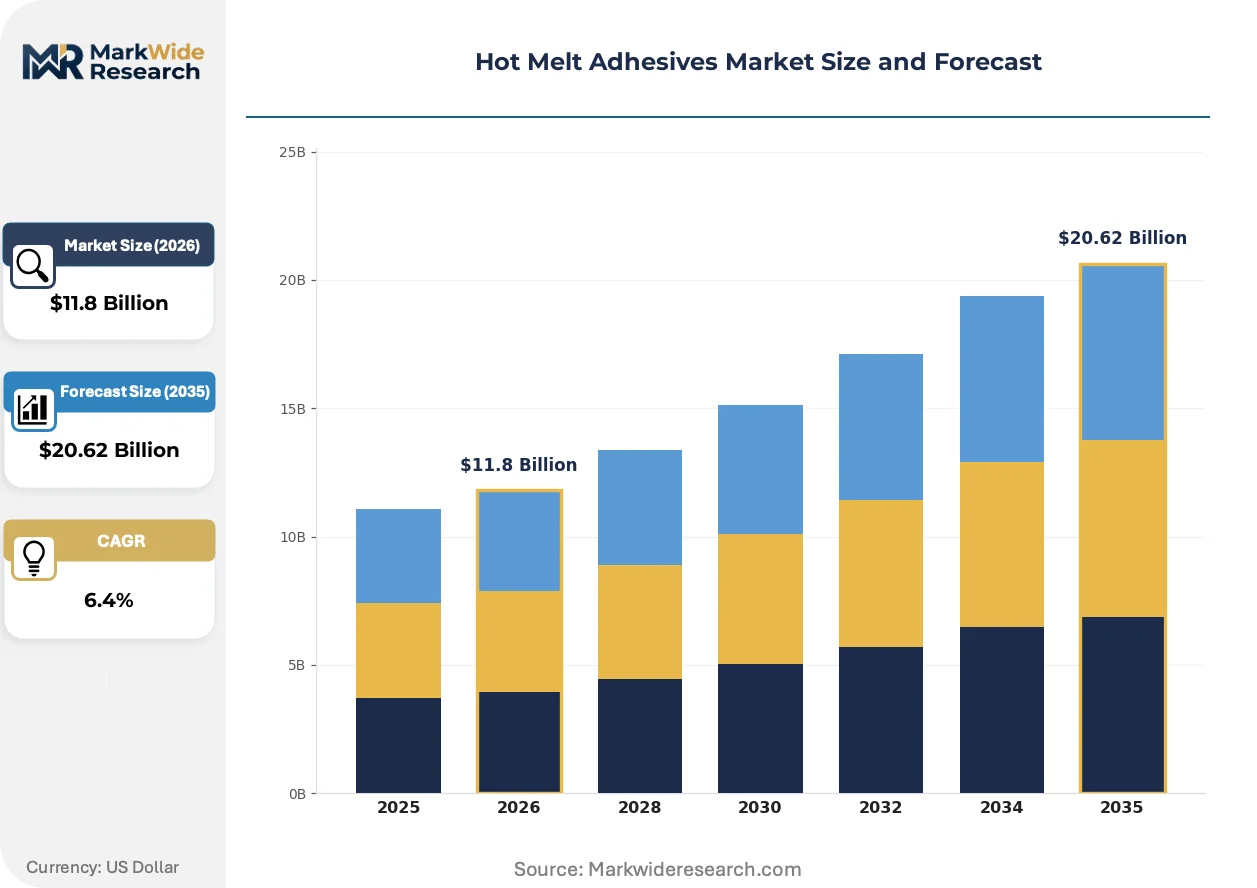
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Ethylene Vinyl Acetate, Polyamide, Polyurethane End User: Packaging, Automotive, Electronics, Woodworking Application: Labeling, Bookbinding, Assembly, Coating Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Sika AG, Arkema S.A., Dow Inc., Jowat SE, Avery Dennison Corporation, Texyear Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Melt Adhesives Market Emerging Trajectories
Reactive polyurethane hot melt chemistry and precision dispensing automation are collapsing traditional performance trade-offs between set speed and bond durability, enabling specification-grade penetration into load-bearing automotive and medical device assembly.
Reactive polyurethane hot melt technology combines initial thermoplastic processing with moisture-cured crosslinking to deliver structural bond strength previously requiring mechanical fasteners. Tier-1 automotive seating suppliers in Germany and China are adopting these systems for frame-to-foam attachment at cycle times under 90 seconds. This chemistry is collapsing the historical separation between packaging-grade commodity adhesives and structural assembly applications.
REACH authorization requirements for certain aromatic amine curing agents are forcing reformulation toward aliphatic alternatives with equivalent performance profiles. European adhesive producers face 2026 sunset dates for legacy hardener chemistries in construction and transportation grades. Electronics packaging manufacturers in the Netherlands and Czech Republic are accelerating qualification programs to maintain CE-marked product continuity.
Direct mill relationships between adhesive suppliers and corrugated board producers are displacing traditional distribution intermediaries in North American packaging procurement. H.B. Fuller's established direct service model demonstrates the operational template, with technical service engineers co-located at major containerboard mills. This channel compression is most visible in the US Southeast and Midwest where consolidated packaging conglomerates concentrate purchasing leverage.
Hot Melt Adhesives Market Segmentation
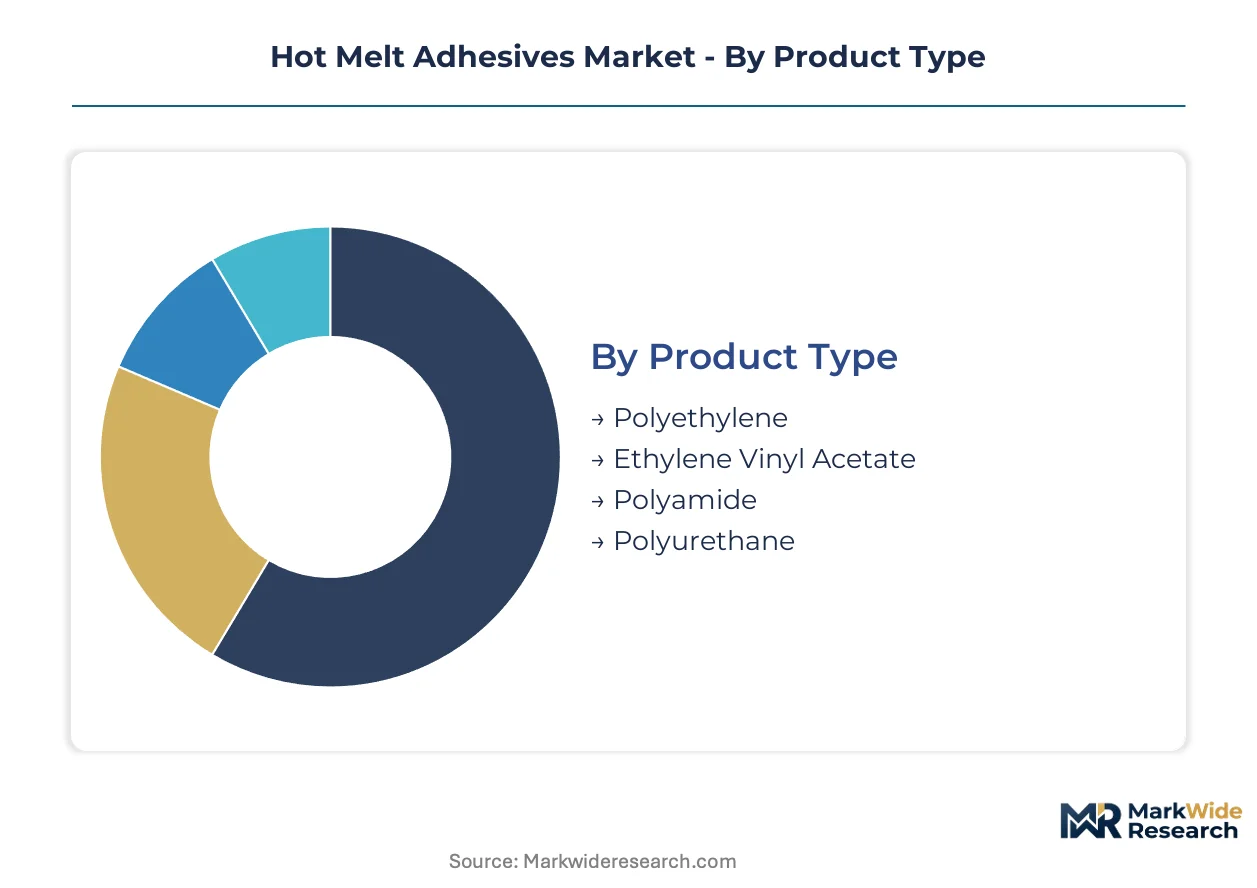
Hot melt adhesive procurement patterns diverge sharply across resin chemistry, end-use performance requirements, and supply chain configuration. Formulation margins and specification premiums concentrate in segments where thermal cycling resistance or food-contact compliance create technical barriers.
Product Type:
Cost tier differentiation separates commodity volume grades from structural assembly formulations with moisture-cure or polyamide backbone chemistry.
- Ethylene Vinyl Acetate:Copolymer formulations dominate corrugated box sealing and bookbinding through mature ethylene supply chains and adjustable vinyl acetate content for peel strength. Demand concentrates in North American packaging mills where FDA food-contact migration limits favor validated EVA grades over untested alternatives.
- Polyurethane:Reactive and non-reactive grades command specification premiums in automotive seating assembly and flexible electronics mounting where thermal cycling resistance prevents bond line failure. German and Chinese Tier-1 seating suppliers are expanding procurement of moisture-cure systems for frame-to-foam attachment under 90-second cycle constraints.
- Polyamide:Nylon-based hot melts serve woodworking and specialty coating applications requiring oil resistance and elevated temperature performance.
- Polyethylene:Homopolymer and copolymer grades occupy cost-sensitive packaging niches where open time and set speed requirements are less stringent.
Ethylene vinyl acetate holds installed capacity. Polyurethane is rotating up the share rankings.
End User:
Application maturity and specification intensity separate packaging volume from automotive and electronics value concentration.
- Packaging:Corrugated box sealing, folding carton manufacturing, and flexible food packaging represent the highest volume consumption segment. Direct mill relationships between adhesive suppliers and containerboard producers in the US Southeast are compressing distribution margins and favoring technical service co-location.
- Automotive:Interior trim fixation, seating assembly, and lightweight structural bonding drive demand for low-VOC formulations compliant with EPA emissions standards. German manufacturers are expanding hot melt procurement for instrument panel and door module assembly as solvent-based alternatives face regulatory displacement.
- Electronics:Semiconductor packaging and flexible circuit board mounting in Shenzhen, Seoul, and Tokyo clusters specify high-purity polyamide grades with controlled ionic content.
- Woodworking:Edge banding, profile wrapping, and assembly applications favor polyamide and EVA grades with tailored open times for automated processing lines.
Packaging commands volume share. Electronics is climbing the fastest on value per kilogram metrics.
Application:
Processing speed requirements and bond durability specifications determine formulation selection and equipment capital intensity.
- Assembly:Structural and semi-structural bonding in automotive, furniture, and appliance manufacturing requires precise open time control and substrate-specific adhesion promoters. Precision dispensing systems with 18-24 month payback periods exclude smaller contract manufacturers from specification-grade procurement.
- Labeling:Pressure-sensitive and permanent label applications in beverage and pharmaceutical packaging demand clean cut-off characteristics and refrigerated distribution stability.
- Bookbinding:Spine and side gluing in commercial printing favors EVA formulations with optimized viscosity for high-speed perfect binding lines.
- Coating:Barrier and protective layer applications in specialty paper and textile finishing occupy niche demand with customized rheology requirements.
Assembly carries the steepest specification ladder. Labeling is gaining share fastest in emerging market packaging modernization.
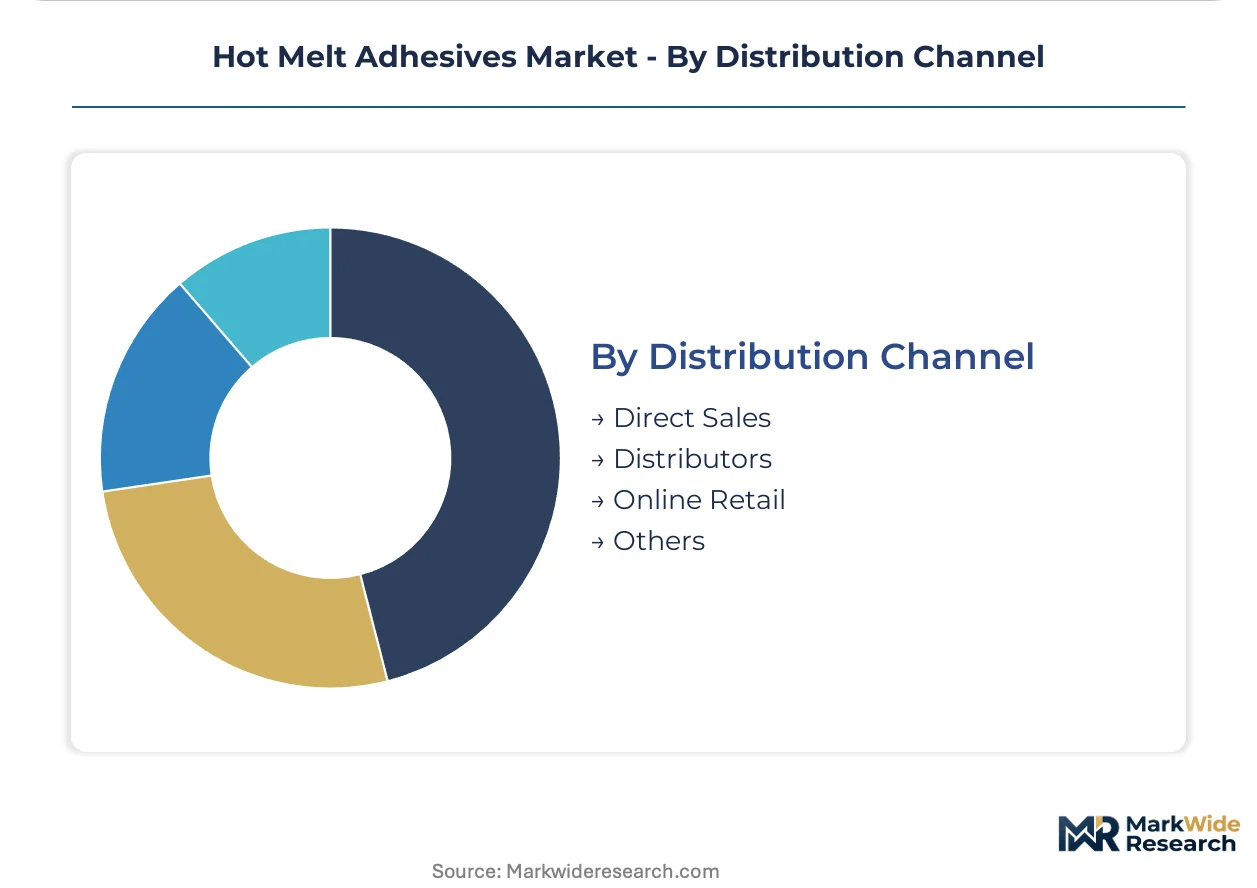
Distribution Channel:
Customer scale and formulation customization needs determine channel economics and supplier margin structure.
- Direct Sales:Large packaging conglomerates and automotive Tier-1 suppliers procure through mill-embedded technical service relationships. H.B. Fuller's direct service model demonstrates operational template with engineers co-located at major containerboard facilities.
- Distributors:Regional chemical distributors serve mid-tier manufacturers with standard EVA and polyethylene grades where technical support requirements are limited.
- Online Retail:E-commerce channels capture small-volume maintenance, repair, and operations procurement for woodworking and specialty assembly applications.
- Others:Toll manufacturing arrangements and private label supply agreements serve brand owners avoiding captive formulation capacity.
Direct sales holds relationship density. Distributors are rotating up the share rankings through consolidation of regional packaging accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive supply chains where specification premiums exceed commodity EVA grades by multiples, while Chinese electronics clusters extract volume discounts through consolidated procurement leverage.
United States
Containerboard mill consolidation in the Southeast and Midwest drives direct technical service relationships with adhesive suppliers. EPA volatile organic compound limits on solvent-based alternatives accelerate hot melt displacement in corrugated sealing lines. The Georgia-Alabama packaging corridor anchors North American EVA consumption.
Germany
Tier-1 automotive seating manufacturers expand moisture-cure polyurethane procurement for frame-to-foam assembly under 90-second cycle constraints. REACH authorization deadlines for aromatic amine curing agents force reformulation toward aliphatic alternatives by 2026. The Stuttgart-Munich automotive belt concentrates demand for low-VOC interior trim fixation grades.
China
Shenzhen and Shanghai electronics clusters specify high-purity polyamide grades with controlled ionic content for semiconductor packaging. MEE volatile organic compound enforcement pushes domestic manufacturers toward water-dispersed reactive hot melt alternatives. The Pearl River Delta absorbs disproportionate volume in flexible circuit board mounting applications.
Japan
Tokyo and Osaka precision electronics manufacturers demand thermal cycling resistance specifications that justify premium polyurethane positioning. METI industrial standards govern adhesive migration limits in food-contact packaging applications. The Nagoya automotive corridor integrates hot melts into lightweight vehicle assembly programs.
India
FSSAI food-contact compliance requirements and organized retail expansion create procurement openings for FDA-validated formulation suppliers. BIS certification timelines extend product registration cycles for imported grades. The Maharashtra-Gujarat packaging belt modernizes corrugated production lines toward hot melt dispensing systems.
Hot Melt Adhesives Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin supply and toll manufacturing arrangements. The vendor base stratifies across three tiers: multinational formulators with direct mill relationships, regional distributors serving mid-tier packaging accounts, and captive resin producers backward integrated into ethylene supply. Two dominant competitive moves define current positioning: asset-light toll manufacturing partnerships that avoid fixed polymer capacity, and technical service co-location at major containerboard and automotive Tier-1 facilities.
Among European-headquartered formulators, Henkel AG & Co. KGaA and Sika AG exemplify divergent specialization archetypes—Henkel anchors automotive and packaging formulation networks, while Sika occupies construction-adjacent assembly applications. H.B. Fuller Company represents the North American direct-service model with technical engineers embedded at major containerboard mills. These three firms illustrate how geographic formulation density and end-use specialization separate premium positioning from commodity supply.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Sika AG |
| Arkema S.A. |
| Dow Inc. |
| Jowat SE |
| Avery Dennison Corporation |
| Texyear Industries Inc. |
| Others |
Supply Flow & Price Mechanics
The US Gulf Coast petrochemical complex anchors global ethylene vinyl acetate feedstock availability, and disruptions at these facilities transmit price volatility directly to corrugated sealing and bookbinding formulations downstream. This concentration of upstream capacity creates asymmetric pricing power where resin suppliers capture margin during supply crunches while formulators absorb cost compression in oversupply cycles.
Pricing Analysis
The customization-premium spread separates commodity EVA grades from configured-to-order polyurethane formulations for automotive seating assembly. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH chemical registration requirements forcing European formulators toward costlier synthetic tackifier alternatives. Small woodworking shops exhibit highest price sensitivity through e-commerce maintenance procurement, while German Tier-1 automotive suppliers accept premium positioning for validated low-VOC grades.
Supply Chain Analysis
Export-control regimes on advanced dispensing equipment limit precision system flows into certain electronics manufacturing jurisdictions. Feedstock draws from US Gulf Coast ethylene crackers, Saudi Arabian petrochemical complexes, and Northeast Asian naphtha crackers. Key inputs encompass vinyl acetate monomer, rosin ester tackifiers, and aliphatic isocyanate curing agents. Single-source vulnerability concentrates in aromatic amine hardeners facing REACH authorization sunset. Distribution runs through direct mill relationships at major containerboard facilities alongside regional chemical distributors serving mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service co-location represents the fastest-expanding recurring-revenue layer as adhesive suppliers embed formulation engineers at customer facilities, outpacing hardware-only supply arrangements. This service-attach model transforms transactional resin supply into multi-year partnership contracts with integrated R&D support.
For Market Incumbents: Pre-empt margin erosion in commodity EVA grades by accelerating moisture-cure polyurethane qualification programs with German and Chinese automotive seating suppliers. Defensive consolidation through toll manufacturing partnerships avoids captive polymer capacity while maintaining formulation network density. Channel control via direct mill relationships at US Southeast containerboard facilities protects share against distributor consolidation. For New Entrants and Emerging Players: India's Maharashtra-Gujarat packaging belt offers the most penetrable entry point as FSSAI food-contact compliance requirements and organized retail expansion create procurement openings for FDA-validated formulation suppliers. Water-dispersed reactive hot melt hybrid chemistries for China's MEE-compliant domestic manufacturers represent a second white-space target. Go-to-market execution should prioritize technical service partnerships over asset-heavy manufacturing investment. For Investors and Strategic Acquirers: Long-term, this sits as a formulation-specialist consolidation play because asset-light toll manufacturing networks command premium multiples versus commodity resin production. Acquisition targets should display regional formulation density with established automotive or electronics customer validation. The signal to watch is REACH authorization timeline acceleration forcing smaller European formulators toward distressed sale scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Dow Inc.'s captive EVA supply chain demonstrates margin protection against Gulf Coast price volatility. |
| Technical Service Co-location | H.B. Fuller's embedded engineers at US containerboard mills create switching costs that compress distributor margins. |
| REACH-Compliant Reformulation | Aliphatic curing agent substitution ahead of 2026 sunset dates preserves CE-marked product continuity for European producers. |
| Water-Dispersed Reactive Hot Melt Development | Hybrid chemistries address China's MEE volatile organic compound enforcement without sacrificing set speed performance. |
| Direct Mill Relationship Expansion | Channel compression at consolidated packaging conglomerates favors suppliers with co-located formulation support capabilities. |
Methodological Framework
Cross-validation between primary interviews with adhesive formulators, automotive Tier-1 procurement leads, and containerboard mill technical directors anchors the qualitative findings against secondary validation. Plant managers at US Gulf Coast petrochemical facilities, distribution channel partners in European packaging networks, and R&D directors at polyurethane specialty houses provided operational perspective. Secondary sources encompass customs and trade flow data, American Chemistry Council and Cefic industry reports, and SEC 10-K disclosures from listed chemical companies. Bottom-up segment sizing and top-down macro anchoring were reconciled through iterative triangulation.
Calibration against historical capacity utilization rates and end-use demand elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass resin chemistry tier, end-use industry vertical, application processing requirement, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring. Industry-specific forecast inputs include EPA emissions standard enforcement timelines and MEE volatile organic compound compliance phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock pricing, automotive production volumes, or electronics capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between adhesive chemistries. Material shifts in REACH authorization implementation pace or Gulf Coast petrochemical complex operating rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market