
 Asia-Pacific Epoxy Adhesive Market | 2026-2036
Asia-Pacific Epoxy Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Epoxy Adhesive Market Outlook
Chinese specialty chemical producers is pivoting toward high-purity epoxy resin output for electronics-grade adhesives. Kangda New Materials leverages captive bisphenol-A supply to sustain cost competitiveness across two-part formulations. Hubei Huitian New Materials anchors its position in domestic automotive assembly through direct OEM qualification programs. NANPAO RESINS CHEMICAL GROUP dominates Taiwan's printed circuit board adhesive layer with specialized low-ionic-content epoxies.
Asia-Pacific epoxy adhesives are thermosetting polymers formed from epichlorohydrin and bisphenol-A reactions, curing through amine or anhydride hardeners to achieve shear strengths exceeding 20 MPa and thermal resistance above 150°C, primarily serving structural bonding where mechanical fasteners fail. Two-part systems lead volume due to room-temperature cure flexibility and extended pot life demanded by automotive and construction contractors. One-part heat-cure epoxies capture premium margin pools in electronics underfill and semiconductor packaging where automated dispensing requires precise viscosity control. Modified epoxy grades incorporating rubber toughening or flexibility agents represent the fastest structural expansion as aerospace tier suppliers in Japan adopt damage-tolerant bonding for composite primary structures.
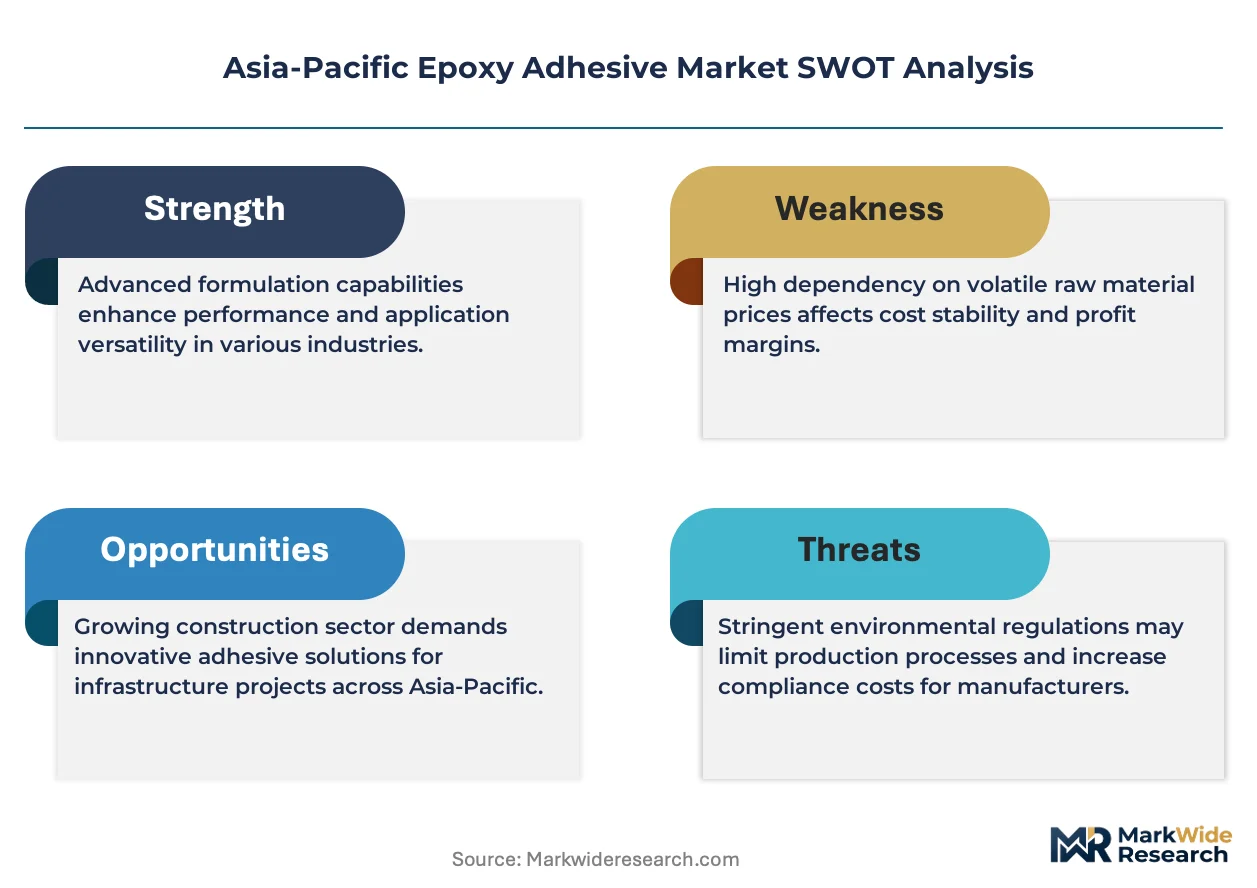
China's MIIT enforces GB standards limiting hazardous substance content in electronics adhesives, while Japan's METI promotes JIS-certified materials through green procurement guidelines for public infrastructure. South Korea's MFDS and environmental ministry jointly regulate volatile organic compound emissions from adhesive manufacturing facilities, pushing waterborne and high-solids epoxy transitions. India's BIS mandatory certification for construction chemicals creates compliance barriers for unqualified imports while opening domestic formulation opportunities. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple Asia-Pacific jurisdictions, as fluorinated surfactants historically used in epoxy wetting agents face phased elimination timelines that will force reformulation investments and supplier qualification resets.
Market Dynamics
China's dual carbon mandates and tightening GB standards on volatile organic compounds are forcing immediate solvent-free epoxy transitions across eastern China's manufacturing corridor, compressing formulation timelines while elevating qualification costs for adhesive suppliers serving automotive and electronics OEM clusters.
Growth Catalysts
- Automotive lightweighting mandates:Japan and South Korea's electric vehicle platforms are expanding structural bonding applications where mechanical fasteners fail, pulling high-shear epoxy formulations into battery enclosure and body-in-white assembly.
- MIIT's GB standard enforcement:China's hazardous substance limits in electronics adhesives are accelerating domestic high-purity resin investments, creating captive supply advantages for qualified formulators.
- Semiconductor packaging automation:One-part heat-cure epoxies with precise viscosity control are displacing legacy underfill materials as Taiwan's PCB and advanced packaging fabs scale automated dispensing lines.
Market Restraints
- Bisphenol-A feedstock concentration:Epoxy resin production depends on petrochemical intermediates concentrated in coastal China refineries, exposing formulators to input cost volatility and import dependency for specialty grades.
- Fluorinated surfactant phase-outs:Per- and polyfluoroalkyl substance restrictions across multiple Asia-Pacific jurisdictions are forcing wetting agent reformulations that reset supplier qualification timelines and raise R&D burdens.
- Construction chemical certification barriers:India's BIS mandatory certification creates structural import friction while privileging domestic formulation investments with extended compliance timelines.
Strategic Opportunities
- Aerospace composite bonding in Japan:Damage-tolerant modified epoxies with rubber toughening represent underpenetrated white space as tier suppliers adopt primary structure bonding for next-generation aircraft programs.
- Waterborne epoxy transitions in South Korea:MFDS and environmental ministry joint VOC regulations are creating regulatory tailwinds for high-solids and aqueous formulations in automotive assembly plants.
- Two-part system channel innovation:Extended pot-life formulations are enabling direct-to-contractor distribution models that bypass traditional distributor markups in Southeast Asian construction markets.
Industry Challenges
- Amine hardener formulation expertise gap:Solvent-free transitions require specialized curing chemistry knowledge that concentrates among senior formulators in Japan and eastern China, constraining regional expansion.
- OEM qualification timeline compression:Automotive and electronics direct qualification programs demand 18-24 month validation cycles that strain working capital for mid-cap adhesive specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Epoxy Adhesive Market |
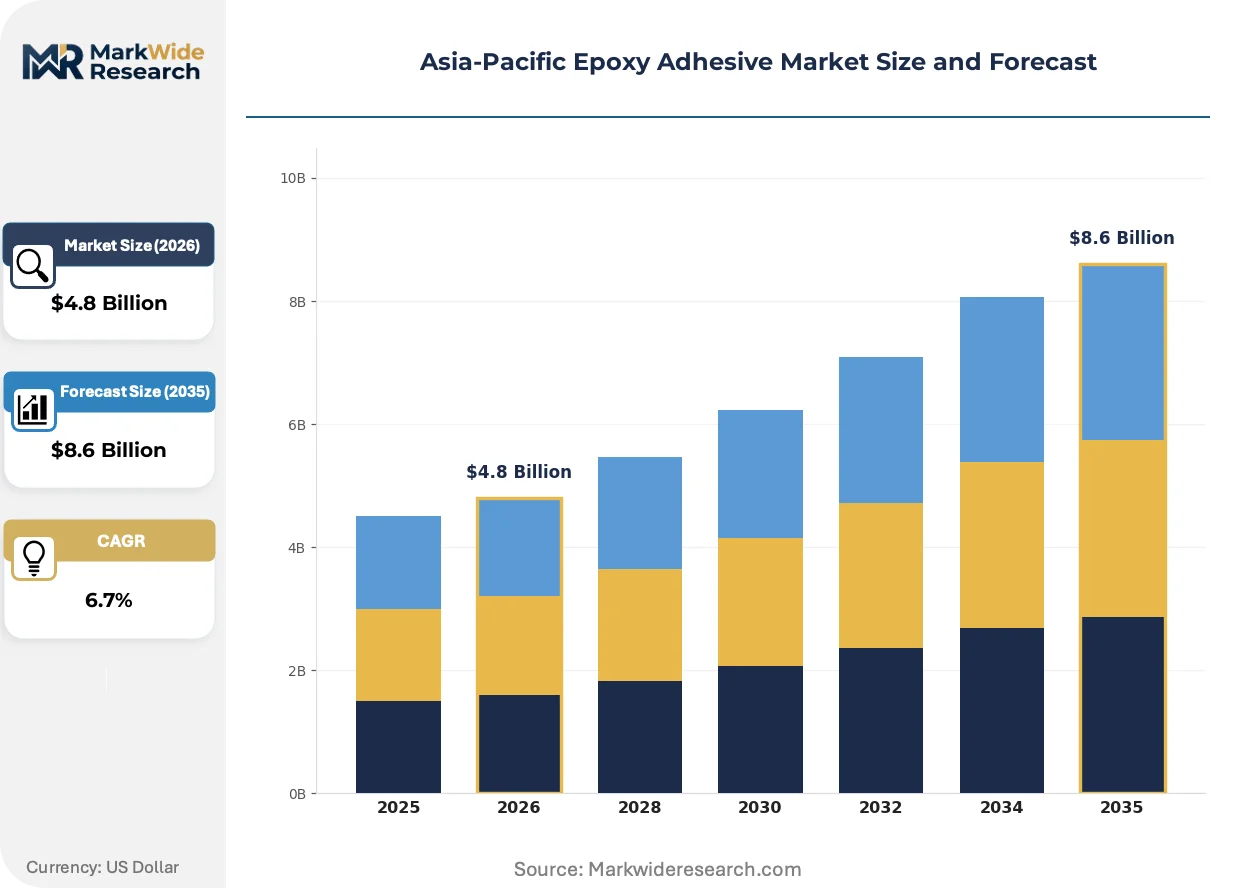
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Part, One-Part, Modified, Specialty Application: Aerospace, Automotive, Electronics, Construction End User: Manufacturers, Contractors, Repair Shops, DIY Enthusiasts Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Kangda New Materials (Group) Co Ltd, NANPAO RESINS CHEMICAL GROUP, Henkel AG & Co KGaA, H B Fuller Company, Huntsman International LLC, Pidilite Industries Ltd, Hubei Huitian New Materials Co Ltd, Sika AG, 3M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Epoxy Adhesive Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and procurement logic are simultaneously restructuring how epoxy adhesives are specified, supplied, and consumed across Asia-Pacific industrial clusters.
Room-temperature curing two-part systems with tunable pot life are decentralizing adhesive application authority from centralized OEM engineering teams to tier suppliers and on-site contractors. Automotive assembly plants in South Korea and construction sites across eastern China are adopting cartridge-dispensed formulations that bypass traditional mixing equipment. This shift is compressing capital requirements for bonding operations while elevating technical service demands on formulators.
Japan's METI green procurement guidelines for public infrastructure are mandating JIS-certified low-emission materials in bridge and building applications. The industrial consequence is a bifurcation between qualified domestic suppliers and import-dependent competitors facing extended certification timelines. Construction contractors in Osaka and Tokyo metropolitan zones are consolidating purchasing around pre-approved material lists that privilege METI-recognized formulations.
Specification authority is migrating from procurement departments to plant-floor engineering teams with direct responsibility for bond-line performance. Electronics assemblers in Taiwan and automotive tier suppliers in Japan are unbundling adhesive selection from consolidated chemical purchasing agreements, creating direct vendor relationships with specialty formulators. This pattern is most visible in semiconductor packaging and electric vehicle battery module assembly where process yield sensitivity outweighs volume pricing leverage.
Asia-Pacific Epoxy Adhesive Market Segmentation
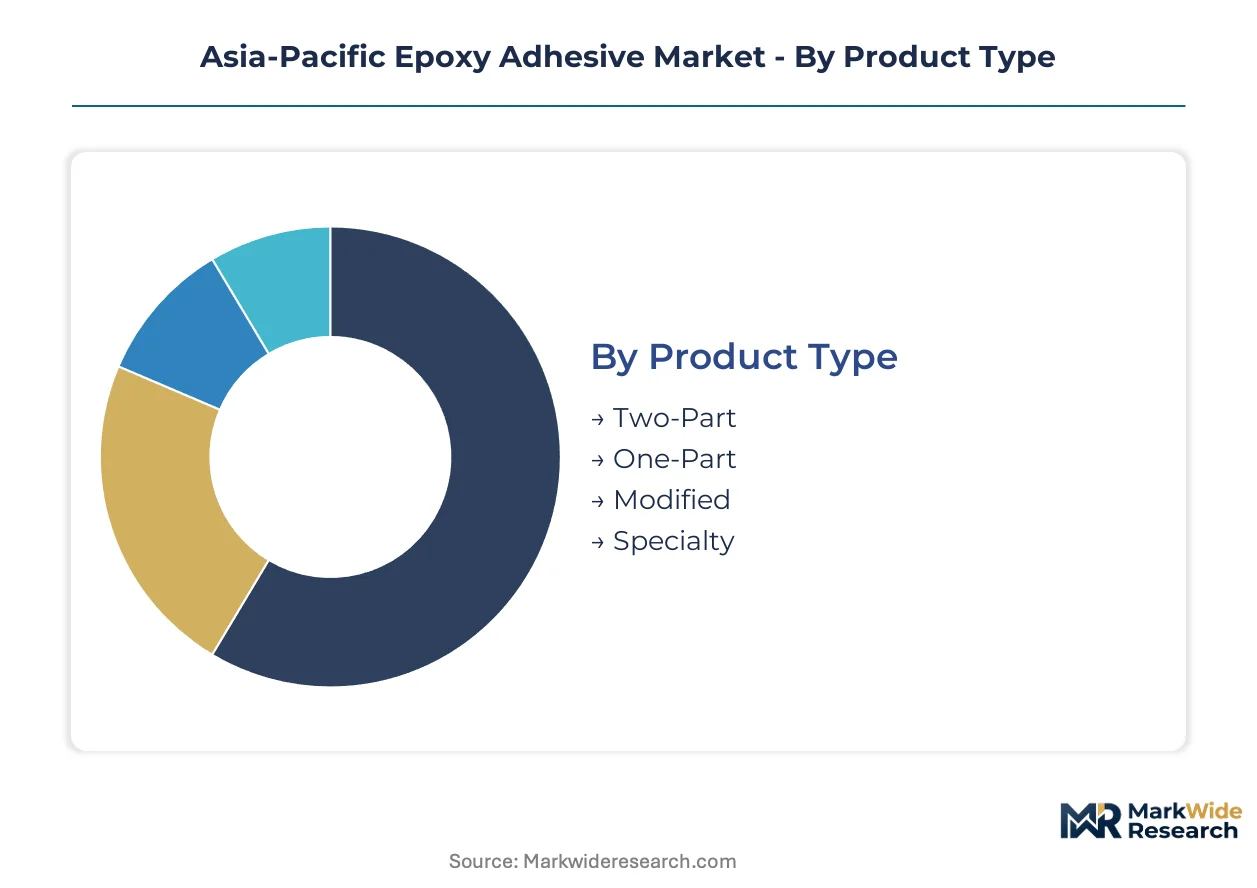
Epoxy adhesive specification across Asia-Pacific industrial clusters hinges on curing chemistry, application environment, and procurement authority. Buyers prioritize pot-life flexibility in field assembly, thermal stability in automated electronics lines, and regulatory compliance in public infrastructure tenders.
Product Type:
Cost tier and formulation complexity drive buyer selection between standardized commodity grades and engineered specialty systems.
- Two-Part:Room-temperature curing systems combine epoxy resin with separate amine or anhydride hardeners. Automotive assembly plants in South Korea and construction contractors across eastern China demand extended pot-life formulations that accommodate large-area bonding without accelerated gelation.
- One-Part:Pre-catalyzed heat-cure systems achieve precise viscosity control through elevated temperature activation. Taiwan's semiconductor packaging fabs and Japan's automotive electronics suppliers specify these for automated underfill dispensing where process yield sensitivity dominates procurement decisions.
- Modified:Rubber-toughened or flexibility-enhanced grades serve damage-tolerant bonding in Japan's aerospace composite primary structures.
- Specialty:Electronics-grade low-ionic-content formulations meet MIIT GB standards for hazardous substance limits in China's manufacturing corridor.
Volume sits with Two-Part systems; growth tilts toward Modified grades as aerospace tier suppliers adopt damage-tolerant bonding.
Application:
End-use performance requirements fragment specification authority across engineering disciplines with distinct thermal, mechanical, and regulatory demands.
- Aerospace:Primary structure bonding in Japan's next-generation aircraft programs requires modified epoxies with damage tolerance and fatigue resistance. METI green procurement guidelines mandate JIS-certified materials, creating qualification barriers for import-dependent suppliers.
- Automotive:Structural bonding in electric vehicle battery enclosures and body-in-white assembly displaces mechanical fasteners. South Korea's lightweighting mandates and China's dual carbon goals accelerate epoxy adoption across OEM platforms.
- Electronics:Semiconductor packaging and PCB assembly in Taiwan demand high-purity formulations with automated dispensing compatibility.
- Construction:Bridge and building applications in Japan's public infrastructure sector require low-emission JIS-certified materials under METI guidelines.
Automotive commands the largest volume share; aerospace offers the steepest expansion trajectory as composite bonding penetrates primary structures.
End User:
Procurement authority concentrates differently across centralized manufacturing, decentralized field application, and aftermarket service channels.
- Manufacturers:OEM engineering teams in Japan's automotive and Taiwan's electronics sectors specify adhesives directly, bypassing consolidated chemical purchasing agreements.
- Contractors:Construction firms in Osaka and Tokyo metropolitan zones consolidate purchasing around METI-recognized pre-approved material lists.
- Repair Shops:Automotive and electronics service operations across Southeast Asia source through distributor networks with technical support requirements.
- DIY Enthusiasts:Small-volume consumers in emerging Asian markets access cartridge-dispensed formulations through retail and online channels.
Manufacturers dominate absolute consumption; Contractors represent the fastest-climbing segment as infrastructure investment accelerates.
Distribution Channel:
Channel selection reflects order scale, technical service intensity, and geographic proximity to formulator technical support resources.
- Online:E-commerce platforms serve small-batch procurement by DIY users and remote contractors with standardized product requirements.
- Retail:Hardware and industrial supply stores stock commodity two-part systems for construction trades in China's eastern manufacturing corridor.
- Direct Sales:Specialty formulators maintain direct relationships with semiconductor packaging fabs in Taiwan and automotive tier suppliers in Japan for process-integrated technical support.
- Distributors:Regional chemical distributors with formulation expertise serve mid-cap manufacturers requiring localized inventory and application engineering.
Direct Sales captures the highest-margin transactions; Distributors retain the broadest geographic coverage across fragmented Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical intermediates for epoxy resin production concentrate in coastal China refineries, exposing formulators across Asia-Pacific to input cost volatility while shaping regional competitive dynamics around captive bisphenol-A supply chains.
China
Electric vehicle battery enclosure assembly and semiconductor packaging fabs drive epoxy consumption across the Yangtze River Delta and Pearl River Delta manufacturing corridors. MIIT enforces GB standards limiting hazardous substance content in electronics adhesives, accelerating domestic high-purity resin investments by qualified formulators. Kangda New Materials leverages captive bisphenol-A supply in eastern China to sustain cost competitiveness across two-part formulations serving automotive OEM clusters.
Japan
Aerospace tier suppliers adopt damage-tolerant modified epoxies for next-generation aircraft primary structure bonding. METI promotes JIS-certified materials through green procurement guidelines for public infrastructure projects, creating qualification barriers for import-dependent competitors. Construction contractors in Osaka and Tokyo metropolitan zones consolidate purchasing around pre-approved material lists privileging METI-recognized formulations.
South Korea
Automotive lightweighting mandates expand structural bonding applications in electric vehicle platforms where mechanical fasteners fail. MFDS and the environmental ministry jointly regulate volatile organic compound emissions from adhesive manufacturing facilities, pushing waterborne and high-solids epoxy transitions. Automotive assembly plants in Ulsan and Pyeongtaek adopt cartridge-dispensed formulations that bypass traditional mixing equipment.
Taiwan
Semiconductor packaging and printed circuit board assembly demand high-purity formulations with automated dispensing compatibility. NANPAO RESINS CHEMICAL GROUP anchors the domestic supply base with specialized low-ionic-content epoxies for PCB adhesive layers. Advanced packaging fabs in Hsinchu and Taichung scale automated dispensing lines that displace legacy underfill materials with one-part heat-cure systems.
India
Construction chemical applications face mandatory BIS certification requirements that create structural import friction while opening domestic formulation opportunities. Infrastructure investment acceleration drives contractor segment expansion across Maharashtra and Gujarat industrial corridors. Domestic formulators with extended compliance timelines capture share from unqualified import competitors in bridge and building applications.
Asia-Pacific Epoxy Adhesive Market Competitive Environment
Global majors compete with regional champions across formulation expertise and captive feedstock access. The vendor base stratifies between multinational chemical conglomerates with broad adhesive portfolios and Asia-Pacific specialists with deep vertical integration into epoxy resin production. Three archetypes dominate: petrochemical-integrated Chinese formulators, Japanese precision-chemistry specialists, and European adhesive multinationals with regional compounding facilities. Competitive dynamics center on qualification timeline compression for direct OEM relationships and backward integration into bisphenol-A supply.
Among China-based integrated producers, Kangda New Materials and Hubei Huitian New Materials exemplify the petrochemical-anchored archetype, while NANPAO RESINS CHEMICAL GROUP represents Taiwan's electronics-grade specialization. These three occupy distinct competitive positions: Kangda leverages captive feedstock for cost leadership, Hubei Huitian pursues direct automotive OEM qualification, and NANPAO dominates PCB adhesive layers through ionic purity control. European and Japanese multinationals compete through technical service intensity and JIS-certified formulation libraries rather than feedstock integration.
| Leading Market Players |
|---|
| Kangda New Materials (Group) Co Ltd |
| NANPAO RESINS CHEMICAL GROUP |
| Henkel AG & Co KGaA |
| H B Fuller Company |
| Huntsman International LLC |
| Pidilite Industries Ltd |
| Hubei Huitian New Materials Co Ltd |
| Sika AG |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across eastern China and Taiwan anchor pricing discipline through captive bisphenol-A production, insulating qualified formulators from petrochemical volatility while compressing margins for import-dependent competitors serving automotive and electronics OEM clusters.
Pricing Analysis
Technical service bundling separates premium formulations from commodity grades, with JIS-certified systems for Japanese infrastructure commanding sustained premiums while standardized two-part cartridges face cost compression in Southeast Asian construction channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales support intensity. Price erosion runs through economy-tier imports as domestic Chinese producers expand high-purity resin output. Electronics assemblers in Taiwan exhibit lowest price sensitivity due to process yield requirements, while Southeast Asian contractors prioritize per-unit cost over performance guarantees.
Supply Chain Analysis
Specialized formulator workforce availability concentrates in Japan's precision-chemistry hubs and eastern China's Yangtze River Delta, constraining regional expansion for solvent-free formulation expertise. Bisphenol-A feedstock draws from coastal China refineries, with specialty amine hardeners sourced from South Korean and Japanese chemical producers. Single-source vulnerability persists for electronics-grade low-ionic-content resins, where NANPAO and qualified Chinese suppliers dominate. Distribution runs through direct technical service relationships with semiconductor fabs and automotive tier suppliers, bypassing traditional chemical distributor networks for high-specification grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific epoxy adhesives occupy a solvent-to-solvent-free transition phase, with waterborne and high-solids formulations displacing legacy systems under tightening VOC regulations across China and South Korea.
For Market Incumbents: To counter fluorinated surfactant phase-outs forcing wetting agent reformulations, accelerate amine hardener R&D partnerships with Japanese precision-chemistry specialists and secure captive bisphenol-A supply through backward integration into eastern China petrochemical corridors. Prioritize JIS certification investments for Japanese public infrastructure pre-approved material lists. For New Entrants and Emerging Players: BIS mandatory certification in India opens a window for domestic formulation facilities serving Maharashtra and Gujarat infrastructure corridors, bypassing import friction faced by unqualified competitors. Target waterborne epoxy transitions in South Korean automotive assembly plants under MFDS joint VOC regulations. Pursue direct-to-contractor cartridge distribution models in Southeast Asian construction markets to bypass traditional distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor electronics-grade specialists with MIIT GB qualification and established Taiwan PCB fab relationships during periods of semiconductor capital expenditure contraction. Long-term viability hinges on solvent-free formulation capability and direct OEM qualification timelines. Watch for inflection in China's dual carbon enforcement intensity as a demand trigger for qualified domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A | Kangda New Materials leverages captive feedstock to sustain cost competitiveness across two-part automotive formulations. |
| JIS Certification Investment | Construction contractors in Osaka and Tokyo consolidate purchasing around METI-recognized pre-approved material lists. |
| Waterborne Formulation Transition | MFDS and South Korean environmental ministry joint VOC regulations create regulatory tailwinds for aqueous systems. |
| Direct OEM Qualification Program | Hubei Huitian New Materials anchors domestic automotive assembly share through bypassing distributor networks. |
| Fluorinated Surfactant Reformulation | Per- and polyfluoroalkyl substance phase-outs across multiple Asia-Pacific jurisdictions force R&D investments and supplier qualification resets. |
Study Parameters
Document review covered customs and trade flow databases, MIIT GB standard filings, and METI green procurement guidelines, complemented by interviews with adhesive formulator technical directors, automotive Tier 1 procurement leads, semiconductor packaging fab engineers, and construction chemical distributors across the Asia-Pacific region. Secondary validation drew from SEC 10-K chemical segment disclosures, Japan Chemical Industry Association reports, and Taiwan Printed Circuit Board Association production statistics. Bottom-up demand modeling triangulated against top-down petrochemical feedstock consumption patterns.
Segment-level projections across product type, application, end user, and distribution channel dimensions were generated through elasticity-adjusted extrapolation over the projection horizon. CAGRs were derived from regression analysis against automotive production forecasts, electronics capital expenditure cycles, and infrastructure investment pipelines. Industry-specific inputs included electric vehicle platform bonding penetration rates and semiconductor packaging automation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for solvent-free epoxy curing chemistry would alter the outlook if amine hardener formulation expertise concentrates more rapidly than projected. Material deviation in China's dual carbon enforcement intensity or per- and polyfluoroalkyl substance restriction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Germany Adhesives Market