
 UV Cured Adhesives Market | 2026-2036
UV Cured Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
UV Cured Adhesives Market Insights
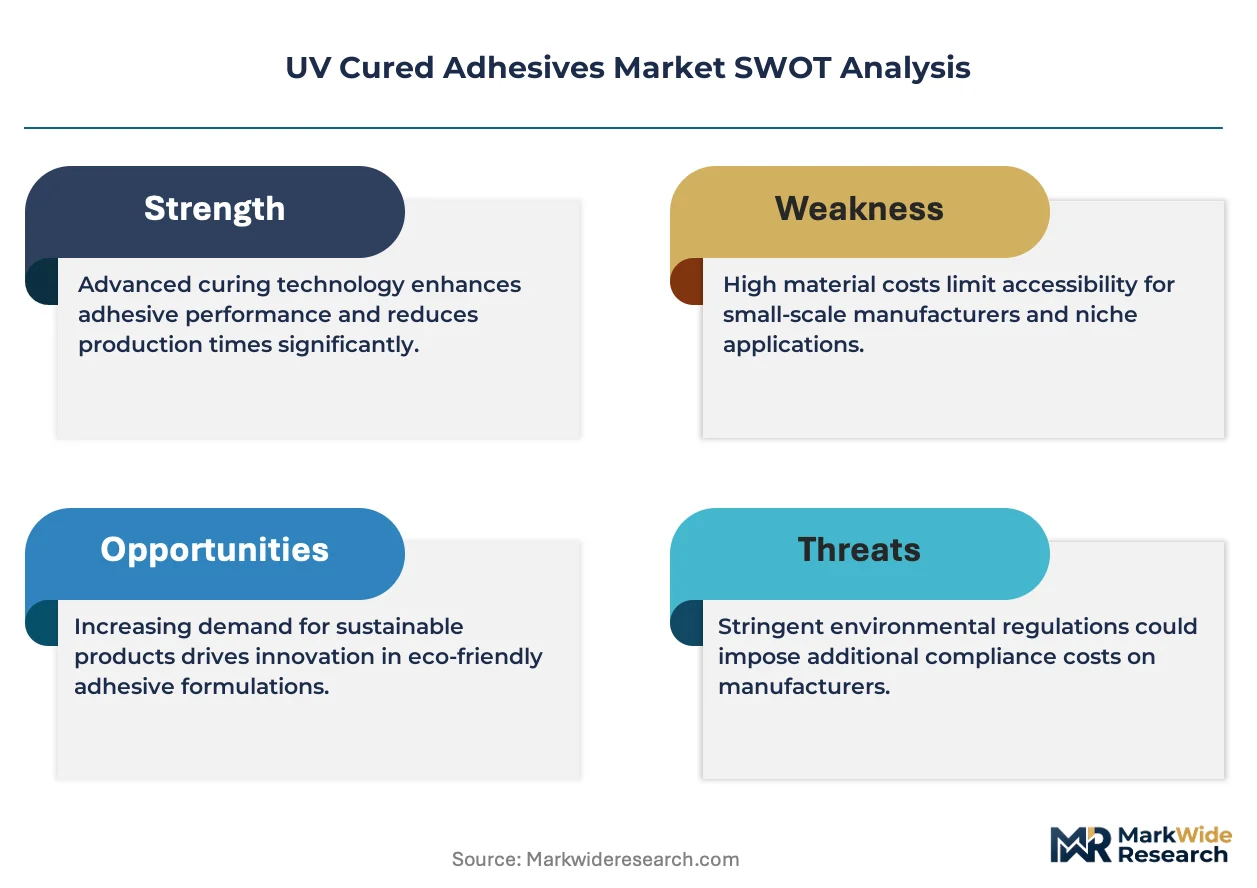
REACH solvent restrictions is expanding compliance costs for European adhesive formulators. Henkel AG & Co. KGaA leverages captive resin synthesis to absorb regulatory-driven input inflation. H.B. Fuller Company anchors its position through North American electronics assembly partnerships. Dymax Corporation specializes in medical-grade acrylates that navigate biocompatibility certification thresholds.
UV cured adhesives are photochemically reactive bonding systems that polymerize upon exposure to ultraviolet radiation in the 200–400 nm wavelength range, typically formulated from acrylate oligomers and photoinitiator packages. These materials deliver fixture times under ten seconds, enabling high-throughput assembly in automated manufacturing lines where thermal curing would damage heat-sensitive substrates. Epoxy formulations dominate structural bonding applications where tensile shear strength exceeds 20 MPa, while acrylate resins capture the fastest growth in electronics display lamination due to optical clarity and low yellowing indices. One-component systems command the largest volume share in automotive headlamp sealing, though hybrid formulations are displacing conventional thermal cures in medical device catheter assembly where dual-cure mechanisms ensure shadow-area polymerization.
FDA 21 CFR Part 175.105 food-contact adhesives standards and EPA VOC emission limits under NESHAP reshape formulation chemistry across US manufacturing. ECHA REACH Annex XVII restrictions on isocyanate-containing products accelerate polyurethane substitution in European industrial bonding. China's GB 30982 standard for construction adhesives and MEE air quality enforcement tighten domestic formulation requirements. Stakeholders must monitor divergence between EU F-Gas Regulation phase-down timelines and US state-level adhesive VOC rules to anticipate regional supply chain reconfiguration.
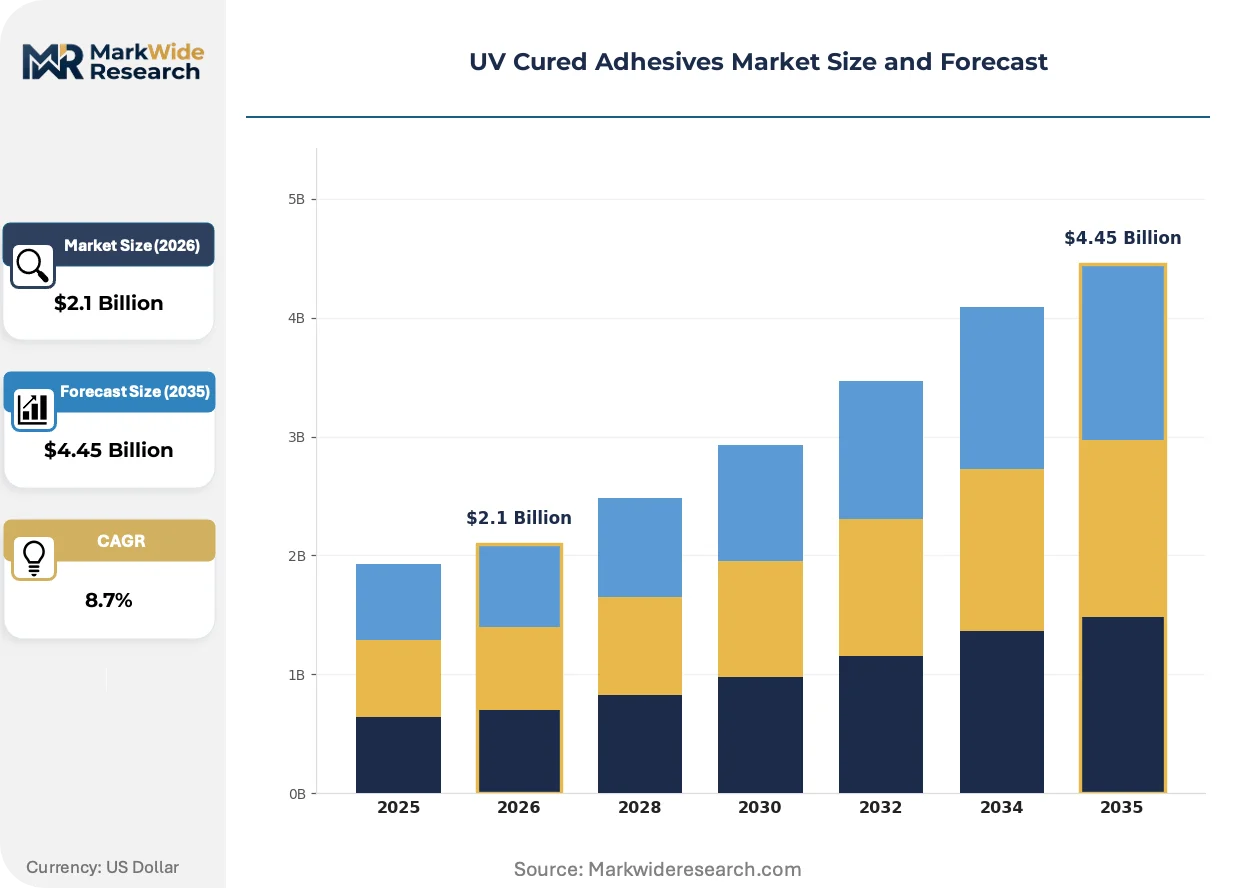
Market Dynamics
Photoinitiator supply concentration in China and Taiwan is compressing formulation economics for European and North American adhesive producers, forcing backward integration into captive photoinitiator synthesis or regional supply reconfiguration.
Growth Catalysts
- REACH Annex XVII solvent restrictions:German electronics assemblers are accelerating UV acrylate procurement to replace solvent-borne polyurethane alternatives ahead of 2025 compliance deadlines.
- Medical device miniaturization:Catheter and endoscope manufacturers in Shenzhen and Shanghai are concentrating demand for biocompatible UV formulations that survive NMPA clearance pathways.
- Automotive LED headlamp sealing:One-component UV epoxies are capturing assembly line retrofits as thermal curing damages polycarbonate lens substrates.
Market Restraints
- Photoinitiator cost volatility:Benzoin ether and phosphine oxide feedstocks face price swings tied to Chinese petrochemical output curbs under MEE air quality enforcement.
- Shadow-cure limitations:Pure UV systems fail in joint geometries where light cannot penetrate, requiring hybrid thermal-UV formulations that add process complexity.
- Acrylate monomer supply concentration:Three Taiwanese resin producers control bulk oligomer supply to Asian electronics laminators, creating geographic chokepoints.
Strategic Opportunities
- Brazilian medical device assembly:ANVISA regulatory alignment with ISO 10993 biocompatibility standards is opening import substitution for UV adhesive localization.
- Dual-cure hybrid platforms:Convergence of cationic epoxy and free-radical acrylate chemistries enables through-cure in opaque medical device housings.
- Indian electronics manufacturing:PLI scheme incentives for display and semiconductor packaging are concentrating greenfield assembly demand in Tamil Nadu and Karnataka clusters.
Industry Challenges
- Photochemistry formulation expertise:Shortage of photoinitiator package optimization specialists delays new product qualification timelines for medical-grade submissions.
- ISO 10993-5 cytotoxicity certification:Extended biocompatibility testing cycles for new UV adhesive platforms stretch R&D-to-revenue intervals to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Cured Adhesives Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylate Formulation Type: One-Component, Two-Component, Hybrid, Water-Based End User: Automotive, Electronics, Medical Devices, Construction Application: Coatings, Potting, Bonding, Sealants |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dymax Corporation, Arkema, Permabond LLC, Master Bond Inc., Panacol-Elosol GmbH, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Cured Adhesives Market Trends and Innovations
Formulation chemistry is pivoting toward hybrid cure mechanisms and bio-based feedstocks as regulatory pressure on petrochemical inputs intensifies across multiple geographies.
LED-optimized photoinitiator packages are consolidating around 365-405 nm wavelength systems that match solid-state UV lamp outputs. Automotive headlamp sealers and electronics display laminators in Germany and Japan are retrofitting mercury arc lines with LED arrays to reduce energy intensity and eliminate mercury handling. This wavelength standardization is consolidating supplier tiers around photoinitiator specialists with 395 nm-optimized phosphine oxide portfolios.
ECHA REACH restrictions on isocyanate-containing products are accelerating polyurethane displacement in European industrial bonding applications. Formulators are reformulating structural adhesives around UV-curable epoxy-acrylate hybrids to maintain shear strength above 20 MPa while eliminating diisocyanate exposure. German automotive suppliers and Italian furniture manufacturers are qualifying these alternatives ahead of anticipated Annex XVII amendments.
Buyers in medical device assembly are compressing supplier qualification cycles from multi-year frameworks to 12-month pilot-to-production timelines. Shanghai and Shenzhen catheter manufacturers are demanding adhesive vendors provide pre-validated ISO 10993-5 cytotoxicity data packages rather than conducting independent testing. This certification-driven preference shift favors formulators with established biocompatibility dossiers over commodity adhesive producers.
UV Cured Adhesives Market Segmentation
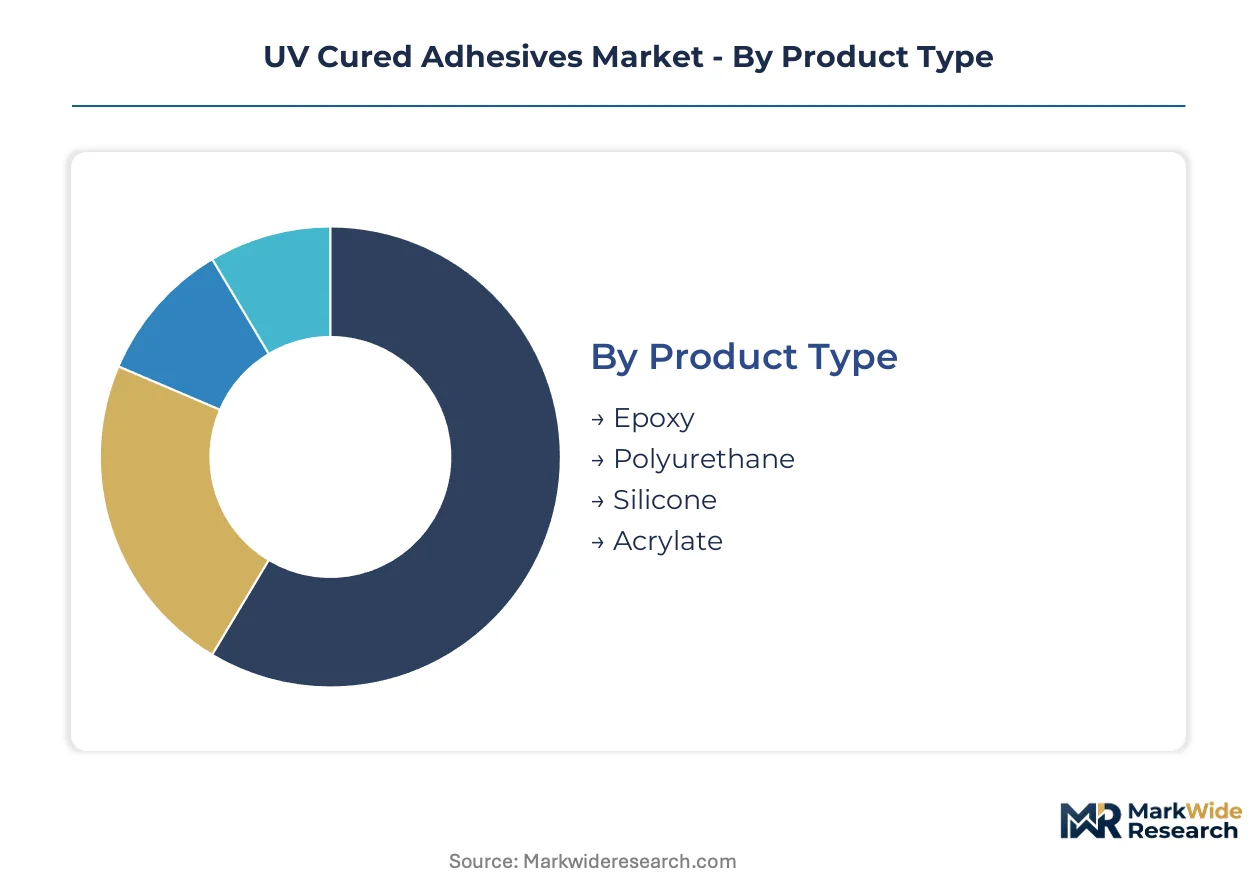
UV cured adhesives segment across chemistry, cure mechanism, and end-use requirements that dictate photoinitiator selection and regulatory compliance pathways. Buyers prioritize optical clarity for electronics lamination, biocompatibility for medical devices, or thermal stability for automotive underhood applications.
Product Type:
Buyers differentiate by structural load requirements and substrate compatibility rather than price alone.
- Epoxy:Cationic cure systems deliver tensile shear strength exceeding 20 MPa for structural bonding. German automotive suppliers specify these for LED headlamp lens-to-housing joints where polycarbonate thermal damage rules out heat curing.
- Acrylate:Free-radical oligomers polymerize in under ten seconds under 365-405 nm LED arrays. Electronics laminators in Japan and Germany accelerate procurement as REACH solvent restrictions tighten compliance costs for polyurethane alternatives.
- Polyurethane:Diisocyanate-containing formulations face substitution pressure from ECHA REACH Annex XVII restrictions.
- Silicone:Flexible cure systems accommodate thermal expansion mismatches in outdoor sealing applications.
Volume sits with acrylate resins in electronics assembly; growth tilts toward epoxy-acrylate hybrids displacing thermal cures in structural automotive bonding.
Formulation Type:
Process integration complexity separates high-throughput automated lines from batch assembly operations.
- One-Component:Pre-mixed systems eliminate metering equipment and reduce line changeover downtime. Automotive headlamp sealers in Germany standardize on these for robotic dispensing cells.
- Hybrid:Dual thermal-UV cure mechanisms ensure polymerization in shadow areas of opaque medical device housings. Shenzhen catheter manufacturers specify these for NMPA clearance pathways where pure UV systems fail.
- Two-Component:Meter-mix-dispense systems suit large-gap potting applications with extended work life requirements.
- Water-Based:Low-VOC formulations address EPA NESHAP emission limits in US manufacturing facilities.
One-component systems dominate automotive volume; hybrid platforms are climbing the fastest in medical device assembly.
End User:
Regulatory jurisdiction determines supplier qualification timelines and testing cost allocation.
- Electronics:Display laminators demand low-yellowing acrylates with optical clarity specifications. Shanghai and Shenzhen assembly clusters concentrate procurement as China's NMPA and MIIT tighten domestic device standards.
- Medical Devices:Catheter and endoscope manufacturers require ISO 10993-5 cytotoxicity pre-validation. Buyers compress supplier qualification from multi-year frameworks to 12-month pilot-to-production cycles.
- Automotive:LED headlamp sealing and sensor potting drive specification of thermal-stable epoxies.
- Construction:Structural glazing and facade bonding applications favor high-modulus formulations meeting GB 30982 standards.
Electronics captures current volume concentration; medical devices show steepest expansion trajectory as miniaturization intensifies adhesive performance requirements.
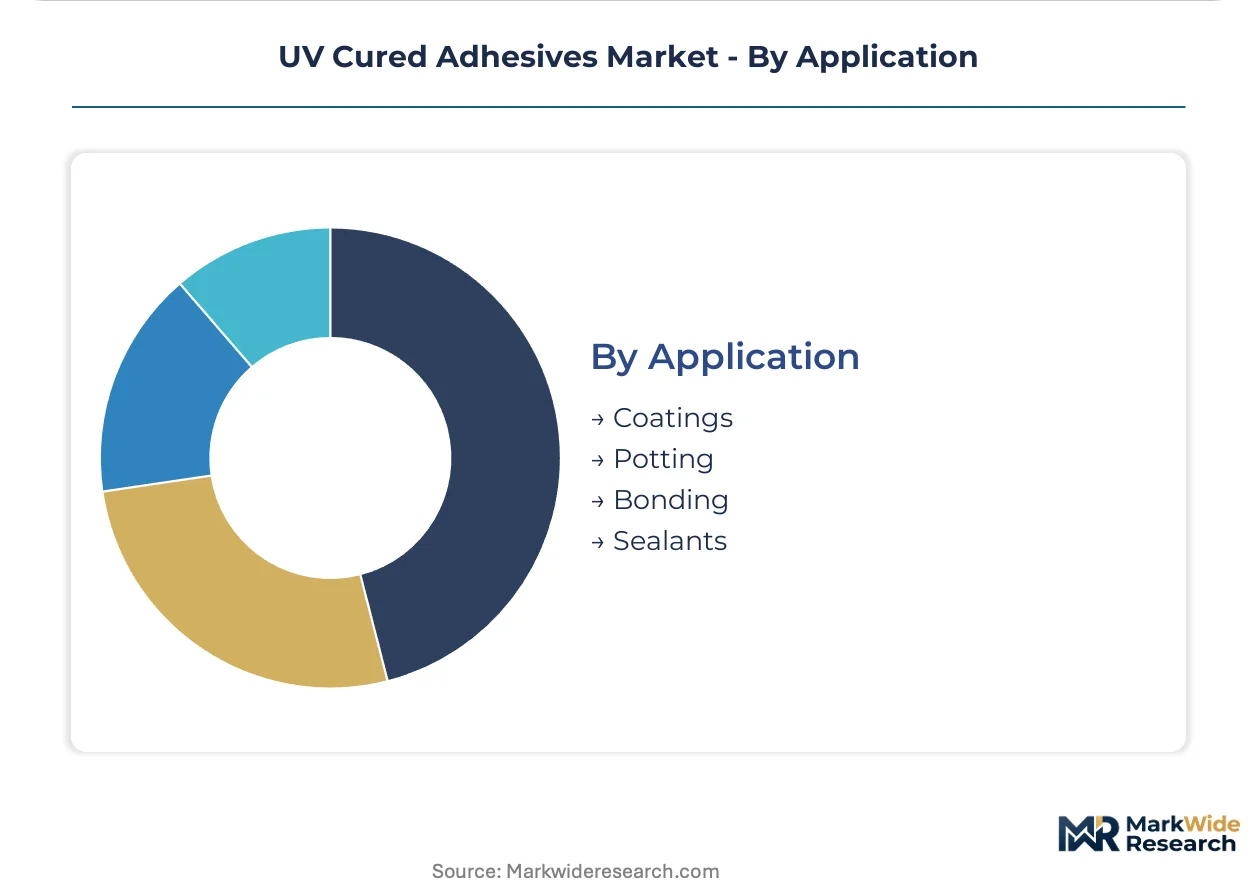
Application:
Film thickness and cure depth requirements dictate photoinitiator package selection and lamp intensity specifications.
- Bonding:Thin-film adhesive layers between 25-100 microns enable display lamination with minimal optical distortion. Japanese electronics manufacturers retrofit mercury arc lines with 395 nm LED arrays to reduce energy intensity.
- Potting:Deep-section cure up to 10 mm requires phosphine oxide photoinitiators with through-cure capability. Automotive sensor manufacturers specify these for underhood electronic control modules.
- Coatings:Surface cure systems protect printed circuit boards and decorative finishes.
- Sealants:Flexible formulations accommodate joint movement in automotive lamp housings and construction glazing.
Bonding commands volume in electronics display assembly; potting is gaining share fastest in automotive electrification applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free Trade Zone tax incentives are concentrating UV adhesive procurement for medical device exporters navigating NMPA clearance pathways. Electronics assembly clusters in Germany's Bavaria and Japan's Kansai region are retrofitting production lines with LED curing systems ahead of regulatory deadlines.
Germany
Automotive LED headlamp manufacturers in Bavaria and Baden-Württemberg are specifying one-component UV epoxies to avoid polycarbonate thermal damage. ECHA REACH Annex XVII restrictions on isocyanate-containing products are accelerating polyurethane substitution in Stuttgart supplier parks. Henkel AG anchors formulation supply through captive resin synthesis in Düsseldorf.
China
Display laminators in Shanghai and Shenzhen are compressing supplier qualification cycles for biocompatible acrylates under NMPA medical device standards. MEE air quality enforcement is constraining photoinitiator feedstock availability from domestic petrochemical producers. Yangtze River Delta electronics clusters are retrofitting mercury arc lines with 395 nm LED arrays.
United States
EPA NESHAP VOC emission limits are reshaping formulation chemistry for construction adhesives meeting FDA 21 CFR Part 175.105 food-contact standards. Electronics manufacturers in Texas and Arizona are qualifying LED-optimized photoinitiator packages for automated display lamination. Midwest automotive suppliers specify thermal-stable epoxies for sensor potting applications.
Japan
METI energy efficiency directives are driving mercury arc-to-LED retrofits in Osaka and Nagoya electronics assembly facilities. PMDA medical device regulations are concentrating demand for ISO 10993-5 pre-validated adhesive platforms in Tokyo catheter manufacturing. Acrylate oligomer procurement is accelerating as REACH solvent restrictions raise European competitor costs.
Brazil
ANVISA regulatory alignment with ISO 10993 biocompatibility standards is opening import substitution opportunities for UV adhesive localization. São Paulo medical device assemblers are piloting dual-cure hybrid platforms for catheter production. Electronics manufacturing in Minas Gerais is scaling procurement for display lamination under local content incentives.
UV Cured Adhesives Market Competitive Landscape
German producers anchor one tier; American specialists hold formulation expertise in medical-grade applications. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive resin synthesis, mid-cap adhesive specialists with regional formulation capabilities, and photoinitiator-focused technology licensors. Strategic moves center on backward integration into photoinitiator production and pre-validated biocompatibility dossier development.
Within the multinational tier, Henkel AG & Co. KGaA and BASF SE exemplify European chemical conglomerates with integrated supply chains. H.B. Fuller Company occupies a position among North American specialists with electronics assembly partnerships. These three anchors represent distinct competitive archetypes: German integrated chemical production, diversified European materials science, and American application-focused formulation expertise.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Dymax Corporation |
| Arkema |
| Permabond LLC |
| Master Bond Inc. |
| Panacol-Elosol GmbH |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
LED curing system retrofits across German and Japanese electronics assembly lines are simultaneously compressing photoinitiator cost structures and concentrating procurement power among 395 nm-optimized formulation specialists. This wavelength standardization is reshaping supplier tiers as buyers consolidate around vendors with captive phosphine oxide synthesis capabilities.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to ISO 10993-5 pre-validated medical-grade acrylates demanded by Shanghai catheter manufacturers under compressed 12-month qualification cycles. Three-tier pricing structure across premium, standard, and economy levels separates biocompatibility-certified formulations from industrial-grade alternatives. Cost compression in standard-grade electronics laminating resins is intensifying because Taiwanese oligomer producers face MEE air quality enforcement curbs. Medical device assemblers show least price sensitivity due to regulatory switching costs, while construction adhesive buyers in US manufacturing facilities drive hardest bargain on EPA NESHAP-compliant water-based formulations.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific petrochemical hubs is amplifying landed cost spreads for European and North American adhesive formulators dependent on benzoin ether feedstocks. Photoinitiator production concentrates in China and Taiwan, while acrylate oligomer synthesis anchors in South Korea and Japan. Raw material dependencies span phosphine oxide photoinitiators, specialty acrylate monomers, and cationic epoxy resins. Single-source vulnerability from three Taiwanese resin producers controlling bulk electronics-grade oligomer supply creates geographic chokepoints. Distribution runs through regional formulation specialists who blend captive resins with imported photoinitiator packages for just-in-time delivery to automated assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mercury arc-to-LED curing transitions are displacing legacy lamp technologies across electronics and automotive assembly, creating asymmetric opportunities for formulation specialists with 395 nm-optimized portfolios.
For Market Incumbents: Extend biocompatibility certification dossiers to capture medical device procurement cycles compressed under NMPA and PMDA regulatory timelines. Backward integration into phosphine oxide photoinitiator synthesis defends margin position against Chinese petrochemical output curbs. Capacity expansion in Tamil Nadu and Karnataka clusters captures PLI-scheme electronics manufacturing growth while reducing freight exposure to Taiwan oligomer chokepoints. For New Entrants and Emerging Players: The premium-to-economy pricing gap in medical-grade acrylates opens white-space for mid-tier formulators offering pre-validated ISO 10993-5 data packages at 20-30 percent discount to established suppliers. Brazilian ANVISA-aligned catheter assembly presents most penetrable geography given import substitution incentives and nascent local formulation capacity. Direct technical service partnerships with São Paulo medical device assemblers bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap adhesive specialists possessing captive photoinitiator synthesis and established biocompatibility dossiers given REACH Annex XVII substitution catalysts. Long-term viability over the projection horizon favors formulators with dual-cure hybrid platforms addressing shadow-cure limitations in opaque medical device housings. Monitor ECHA F-Gas Regulation phase-down timelines against US state-level VOC adhesive rules as signal for regional supply chain reconfiguration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Synthesis | Captive phosphine oxide production absorbs MEE enforcement-driven feedstock volatility for European formulators. |
| Dual-Cure Hybrid Platform Development | Convergence of cationic epoxy and free-radical acrylate chemistries unlocks through-cure in opaque medical device geometries. |
| Pre-Validated Biocompatibility Dossier Investment | ISO 10993-5 cytotoxicity data packages compress supplier qualification cycles for NMPA-cleared Shanghai catheter manufacturers. |
| LED Curing System Retrofit Partnerships | 395 nm wavelength standardization consolidates procurement around photoinitiator specialists matching solid-state lamp outputs. |
| Regional Formulation Capacity in India | Tamil Nadu and Karnataka greenfield plants capture PLI-scheme display and semiconductor packaging demand. |
Research Methodology
Independent corroboration across adhesive formulator technical directors, medical device procurement managers, and electronics manufacturing engineers underwrites the qualitative findings in this study. Primary interviews with plant managers at German automotive LED headlamp facilities, distribution channel partners in Asian resin markets, and regulatory affairs leads navigating REACH Annex XVII compliance were cross-referenced against secondary validation. Trade data from customs authorities, ECHA restriction dossiers, SEC 10-K disclosures from listed chemical conglomerates, and NMPA medical device registration databases anchored quantitative estimates. Bottom-up demand modeling across chemistry, formulation, and end-use segments was reconciled with top-down market sizing from industry association reports.
Comparable historical periods spanning pre- and post-REACH restriction implementation anchored the forecast window's growth trajectory assumptions. The analytical framework disaggregated volume and value across product type, formulation mechanism, end-user industry, and application depth dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate synthesis calibrated to electronics lamination, medical device assembly, and automotive sealing demand drivers. Photoinitiator supply concentration indices, LED curing adoption curves, and biocompatibility certification timeline data fed industry-specific forecast inputs.
Inputs from ECHA regulatory filings, NMPA clearance databases, and Asian petrochemical producer disclosures were available through the study window; gaps in real-time inventory positioning data from Taiwanese oligomer producers introduce uncertainty bands around near-term supply elasticity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market