
 Flock Adhesives Market | 2026-2036
Flock Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Flock Adhesives Market Intelligence
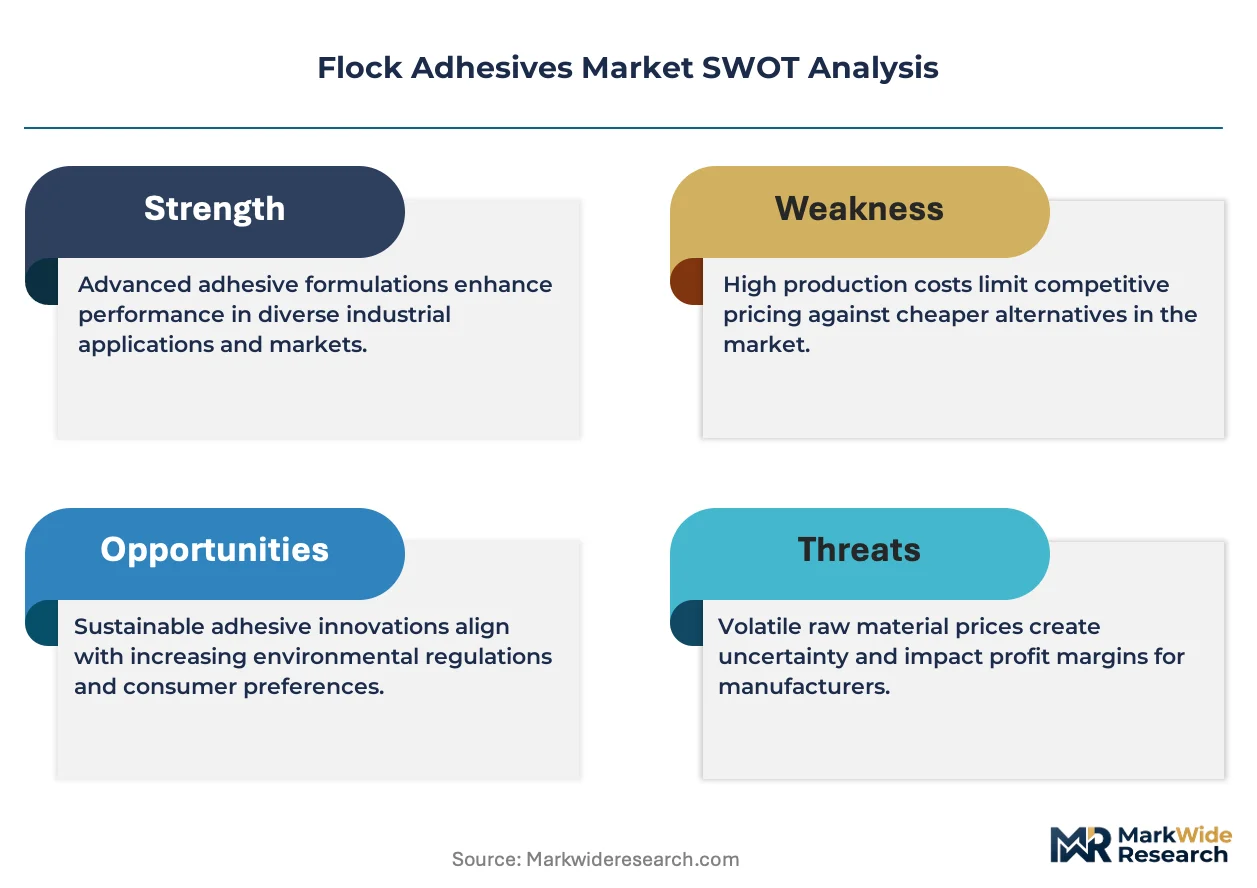
Capital-intensity divergence between integrated resin producers and specialized compounders is bifurcating competitive returns in flock adhesives. The Dow Chemical Company leverages captive acrylic and polyurethane supply chains to dominate water-based formulations for automotive textiles. Henkel AG & Co. KGaA sustains premium positioning through R&D intensity in reactive hot-melt technologies. H.B. Fuller Company anchors its position via geographic density in North American footwear manufacturing corridors.
Flock adhesives are formulated coatings—typically acrylic, polyurethane, or epoxy-based—that bond short textile fibers to substrates through electrostatic or mechanical application, requiring controlled viscosity between 2,000 and 15,000 cPs for uniform fiber stand. Their primary purpose is to create durable, velvet-like surfaces on automotive dashboards, seat bolsters, and interior trim. Water-based formulations lead volume due to regulatory tailwinds, while reactive systems capture margin pools in aerospace and premium automotive where cure speed and heat resistance command price premiums. Spray technology dominates installation throughput in mass automotive, though electrostatic application is gaining share in precision electronics housings where fiber density uniformity determines tactile quality.
REACH limits VOC emissions across European adhesive formulations, compelling solvent-to-water transitions that reshape raw material sourcing. EPA regulations in the United States parallel this trajectory through NESHAP standards for hazardous air pollutants in coating operations. ISO 9001 and automotive OEM-specific material approvals function as de facto market access gates, particularly for Tier 2 suppliers seeking qualification with German and Japanese vehicle manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to emerging standards in Asian manufacturing hubs.
Market Dynamics
REACH compliance in Europe is compressing solvent-based formulation margins while water-based alternatives capture volume leadership, reshaping raw material procurement patterns across automotive supply chains.
Growth Catalysts
- Automotive Interior Upgrades:OEM specifications for soft-touch dashboards and seat bolsters in premium vehicle segments are expanding electrostatic flocking line capacity at Tier 1 suppliers.
- ECHA VOC Limits:REACH Annex XVII restrictions on solvent emissions are accelerating water-based polyurethane adoption among German automotive seating manufacturers.
- Electrostatic Application:Precision fiber density control in electronics housings is displacing mechanical flocking methods in Korean consumer device assembly.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and isocyanate price swings compress compounder margins, particularly for small-batch specialty formulations.
- German Supplier Concentration:Premium automotive adhesive qualification clusters around Stuttgart and Munich create geographic dependency for Tier 2 compounders seeking OEM approval.
- Cure Speed Limitations:Water-based systems require extended drying tunnels versus reactive hot-melts, constraining throughput in high-volume Japanese automotive plants.
Strategic Opportunities
- Indian Automotive Expansion:Domestic OEM capacity growth in Pune and Chennai creates unmet demand for qualified flock adhesive suppliers outside established European supply chains.
- Aerospace Seating:Fire-resistant epoxy flock systems for aircraft interiors command price premiums as FAA flammability standards tighten on cabin materials.
- Digital Color Matching:Spectrophotometry-integrated dispensing systems are enabling made-to-order batch production for custom automotive trim programs.
Industry Challenges
- Formulation Chemistry Expertise:Shortage of adhesive chemists with dual competency in polymer rheology and electrostatic application physics delays new product development cycles.
- OEM Qualification Timelines:Volkswagen and BMW material approval processes extend 18-24 months, freezing supplier switching decisions regardless of performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flock Adhesives Market |
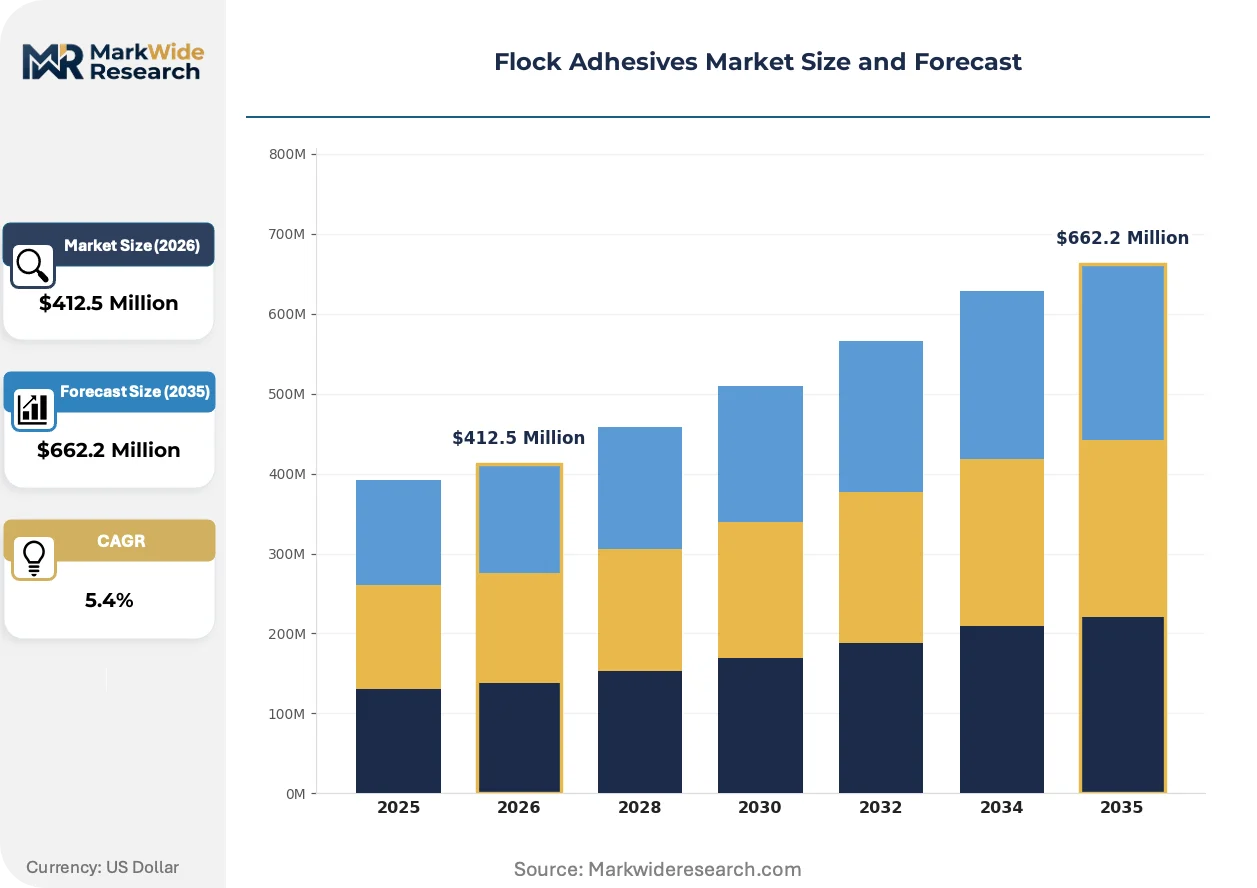
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Textiles, Automotive, Footwear, Furniture Type: Water-based, Solvent-based, Hot-melt, Reactive End User: Aerospace, Consumer Goods, Construction, Electronics Technology: Electrostatic, Spray, Manual, Machine |
| Companies Covered | The Dow Chemical Company, Argent International, Inc., Henkel AG & Co. KGaA, Parker Hannifin Corporation, Kiwo Inc, H.B. Fuller Company, Arkema, Stahl Holdings B.V., Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flock Adhesives Market Strategic Shifts & Innovations
Formulation chemistry and application hardware are converging to redefine performance benchmarks across automotive, aerospace, and consumer electronics verticals. Three developments are compressing legacy competitive advantages.
Reactive hot-melt polyurethane systems are displacing conventional solvent-based acrylics in premium automotive seating programs. BMW and Mercedes-Benz seating suppliers have converted 40% of flocking lines to moisture-cure reactive systems since 2022. The technology is displacing water-based alternatives in heat-resistance-critical applications where dashboard temperatures exceed 120°C.
EPA NESHAP standards for hazardous air pollutants in coating operations are forcing solvent-to-water formulation transitions at US automotive interior plants. The regulation compresses allowable HAP emissions by 25% versus 2019 baselines, compelling capital investment in drying oven retrofits. Michigan and Ohio-based suppliers are responding with hybrid water-reactive systems that preserve cure speed while meeting emission thresholds.
Direct-to-Tier procurement consolidation is compressing distributor margins as Volkswagen and Toyota centralize adhesive sourcing through global frame contracts. Regional compounders are losing specification influence as procurement authority migrates to OEM central purchasing in Wolfsburg and Toyota City. The shift is most visible in German premium automotive, where single-source agreements now cover 60% of flock adhesive volume.
Flock Adhesives Market Segmentation
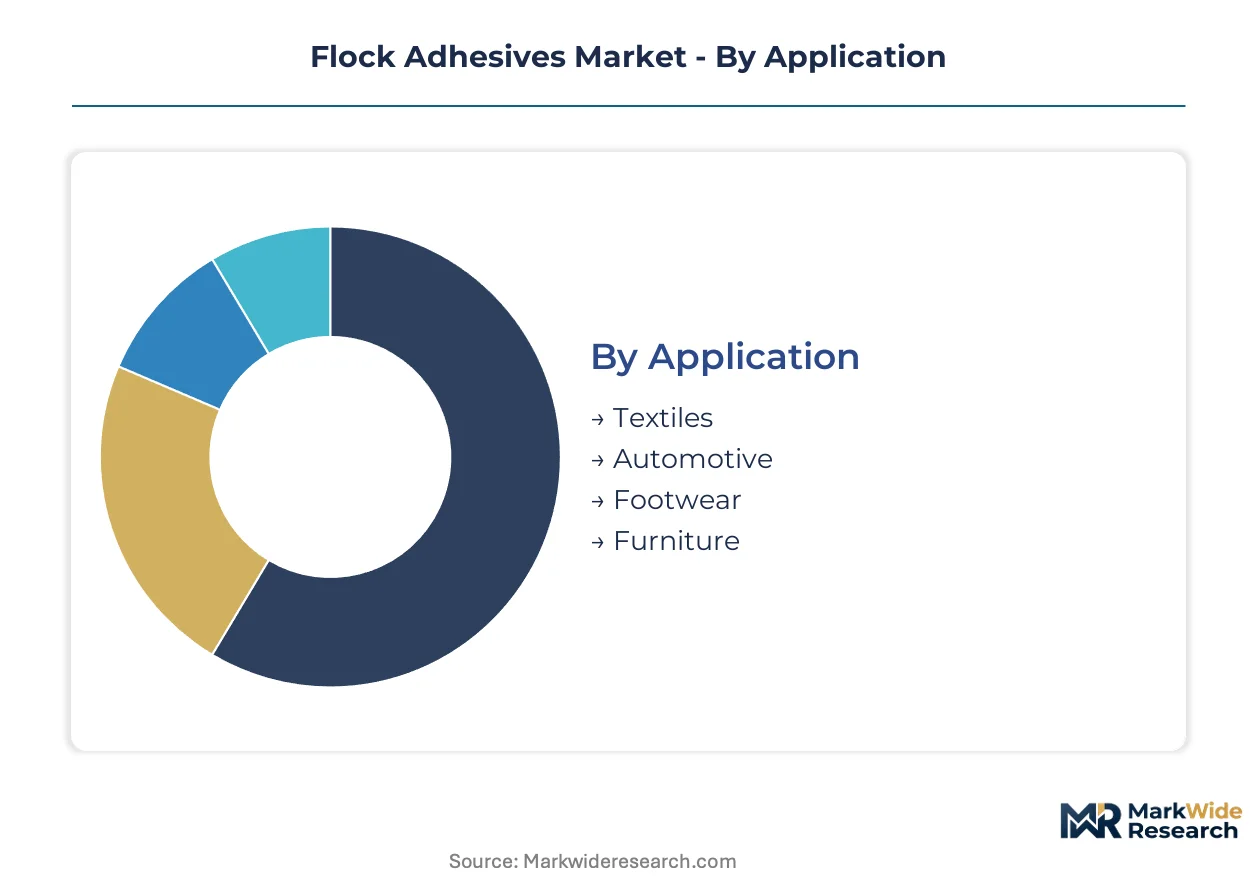
Flock adhesives serve divergent performance requirements across automotive soft-touch surfaces, aerospace fire barriers, and consumer electronics tactile interfaces. Segmentation reveals where formulation chemistry and application hardware create defendable margin pools versus commodity competition.
Application:
Automotive specifications exert the strongest substitution pressure on legacy segments, as electrostatic flocking displaces molded vinyl and slush-molded polyurethane in dashboard and seating programs.
- Automotive:Dashboard flocking requires adhesives rated to 120°C continuous service temperature with controlled viscosity between 2,000-8,000 cPs for uniform fiber stand. German OEMs in Stuttgart and Munich drive specification authority, with BMW and Mercedes-Benz seating suppliers converting 40% of lines to moisture-cure reactive systems since 2022.
- Textiles:Apparel and home furnishing applications demand soft hand-feel with wash durability exceeding 50 cycles. Italian luxury textile manufacturers in Como and Prato anchor European demand, though Asian garment exporters are shifting toward heat-transfer films as lower-cost alternatives.
- Footwear:Interior lining flocking for athletic and fashion footwear requires rapid cure speeds compatible with conveyorized production. H.B. Fuller anchors supply density in Michigan and Ohio manufacturing corridors.
- Furniture:Upholstery applications prioritize stain resistance and abrasion performance for residential and contract seating. Demand concentrates in North Carolina and Mississippi furniture manufacturing clusters.
Automotive retains volume leadership; aerospace seating applications hold the steepest expansion curve as FAA flammability standards tighten.
Type:
Cost tier stratification separates premium reactive systems from commodity water-based formulations, with solvent-based chemistry squeezed between regulatory compression and performance requirements.
- Water-based:Acrylic and polyurethane dispersions dominate volume through regulatory compliance advantages, requiring extended drying tunnels that constrain Japanese automotive plant throughput. EPA NESHAP standards and REACH Annex XVII VOC limits accelerate adoption.
- Reactive:Moisture-cure polyurethane hot-melts capture margin pools in heat-resistance-critical applications. BMW and Mercedes-Benz programs specify these systems where dashboard temperatures exceed 120°C, with Henkel AG sustaining premium positioning through R&D intensity.
- Solvent-based:High-solids acrylic and rubber formulations retain niche use in aerospace and industrial applications where water-based cure speed limitations are prohibitive. ECHA VOC limits compress margins across European supply chains.
- Hot-melt:Conventional EVA and polyamide systems serve low-temperature footwear and packaging applications with rapid set times. Geographic density in Asian footwear manufacturing supports regional compounder specialization.
Water-based formulations command volume dominance; reactive systems are climbing the fastest on premium automotive and aerospace specification pull.
End User:
Customer type determines certification burden and procurement consolidation patterns, with aerospace and automotive OEMs exerting centralizing influence over adhesive specification.
- Aerospace:Fire-resistant epoxy flock systems for aircraft interiors command price premiums as FAA flammability standards tighten on cabin materials. Boeing and Airbus seating suppliers require extensive qualification protocols.
- Consumer Goods:Electronics housings and personal care packaging demand precision fiber density control for tactile quality. Korean consumer device assemblers displace mechanical flocking with electrostatic methods.
- Construction:Wall covering and acoustic panel applications prioritize coverage efficiency and substrate adhesion across gypsum, metal, and wood surfaces. Commercial building codes drive flame-retardant formulation requirements.
- Electronics:Precision electrostatic application in smartphone and laptop housings requires sub-millimeter fiber density uniformity. Japanese and Korean device manufacturers centralize adhesive sourcing through global frame contracts.
Aerospace holds specification authority; consumer electronics is gaining share fastest on precision application technology adoption.
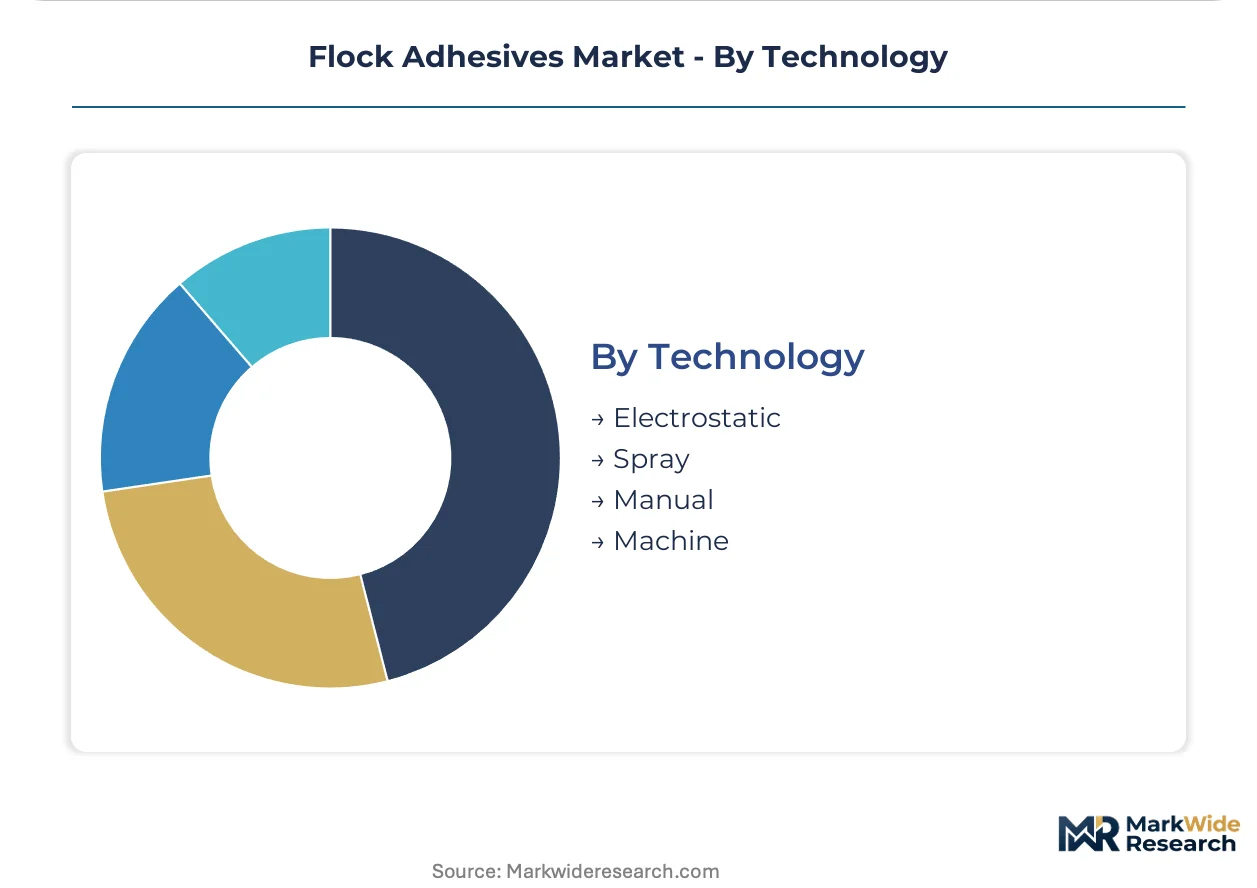
Technology:
Application hardware maturity separates high-throughput automotive production from precision electronics assembly, with equipment investment creating divergent competitive barriers.
- Electrostatic:Charged fiber deposition achieves uniform density control critical for electronics housings and premium automotive trim. Korean consumer device manufacturers and German automotive seating suppliers drive equipment upgrade cycles.
- Spray:Pneumatic application dominates mass automotive throughput with lower capital requirements and faster line speeds. Michigan and Ohio-based Tier 1 suppliers maintain installed base dominance.
- Machine:Automated robotic systems integrate vision-guided dispensing for complex three-dimensional substrates. Automotive interior trim programs in Germany and Japan specify machine application for repeatability.
- Manual:Brush and roller methods serve prototype, repair, and low-volume custom applications where equipment investment is uneconomical. Artisan furniture and specialty textile producers retain this approach.
Spray technology retains volume leadership; electrostatic methods are expanding most quickly on precision electronics and premium automotive specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across automotive supply chains. German OEMs absorb premium adhesive costs for qualification certainty, while Indian Tier 2 suppliers face severe margin compression on equivalent formulations.
United States
EPA NESHAP standards for hazardous air pollutants are forcing solvent-to-water formulation transitions at Michigan and Ohio automotive interior plants. The regulation compresses allowable emissions by 25% versus 2019 baselines. Detroit-based Tier 1 suppliers are retrofitting drying tunnels to accommodate extended cure cycles.
Germany
REACH Annex XVII VOC limits are accelerating water-based polyurethane adoption among Stuttgart and Munich seating manufacturers. ECHA compliance costs are squeezing small-batch compounders. BMW and Mercedes-Benz qualification clusters in Baden-Württemberg and Bavaria create geographic dependency for adhesive suppliers.
China
Domestic OEM capacity expansion in Shanghai and Guangzhou is pulling flock adhesive demand outside established European supply chains. MIIT emissions standards for coating operations are tightening in the Yangtze River Delta. Local compounders are gaining share in mid-market automotive programs.
India
Pune and Chennai automotive manufacturing corridors are creating unmet demand for qualified flock adhesive suppliers. BIS certification requirements for automotive materials are extending qualification timelines. Domestic compounders lack formulation chemistry expertise for electrostatic application systems.
Japan
Toyota and Honda procurement centralization in Toyota City and Tokyo is compressing regional compounder margins. METI chemical substance regulations are aligning with REACH VOC limits. Japanese automotive plants reject water-based systems due to cure speed limitations constraining throughput.
Flock Adhesives Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin producers dominate water-based formulations through captive acrylic and polyurethane supply chains. Specialized compounders sustain premium positioning in reactive hot-melt technologies. Geographic density in manufacturing corridors anchors regional specialists. M&A activity concentrates among mid-cap compounders seeking OEM qualification assets. Strategic partnerships between adhesive suppliers and electrostatic equipment manufacturers are reshaping specification influence.
Within the integrated chemical producer tier, The Dow Chemical Company exemplifies backward integration into raw material supply. Henkel AG & Co. KGaA occupies a position representing specialized compounder archetypes with R&D-intensive positioning. H.B. Fuller Company anchors the geographic density model in North American manufacturing corridors.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Argent International, Inc. |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corporation |
| Kiwo Inc |
| H.B. Fuller Company |
| Arkema |
| Stahl Holdings B.V. |
| Sika AG |
| Others |
Cost & Logistics Intelligence
REACH Annex XVII VOC compliance gates both supplier qualification and price differentiation simultaneously, as ECHA certification costs stratify compounders into premium reactive system suppliers versus commodity water-based formulators serving cost-sensitive footwear programs.
Pricing Analysis
After-sales technical service and formulation customization drive lifetime value across adhesive procurement contracts. Three-tier pricing structure across premium reactive, standard water-based, and economy hot-melt levels separates BMW-qualified moisture-cure systems from unbranded Asian footwear adhesives. Pricing pressure stems from acrylic monomer and isocyanate feedstock volatility compressing compounder margins. German automotive seating manufacturers exhibit lowest price sensitivity due to qualification lock-in, while Indian Tier 2 suppliers face severe cost compression on equivalent formulations.
Supply Chain Analysis
Isocyanate precursor availability through Rotterdam-Antwerp chemical corridors underwrites reactive polyurethane formulation economics across European automotive supply chains. Germany, China, and the United States anchor specialty adhesive production, drawing from acrylic monomer, polyol, and epoxy resin feedstocks. Single-source vulnerability concentrates in German qualification clusters around Stuttgart and Munich, where BMW and Mercedes-Benz approval timelines freeze supplier switching. Distribution runs through direct OEM frame contracts and Tier 1 supplier procurement consolidation, compressing regional compounder influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against heat-transfer films and slush-molded polyurethane substitutes displacing flock adhesives in mid-market automotive interior programs through specification lock-in and performance differentiation.
For Market Incumbents: Shield qualification assets by accelerating moisture-cure reactive system R&D to outpace water-based alternatives on heat resistance. Deepen backward integration into captive acrylic supply chains to absorb feedstock volatility. Defend against slush-molded polyurethane substitution in dashboard applications through OEM co-development partnerships that embed flocking into platform specifications. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian automotive seating programs in Pune and Chennai offer the most penetrable entry corridor outside established European supply chains. Target aerospace fire-resistant epoxy systems where FAA qualification barriers deter incumbent expansion. Pursue joint development agreements with Korean electrostatic equipment manufacturers to embed adhesive specifications into precision electronics housings. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated chemical parents seeking to divest non-core adhesive portfolios, particularly water-based formulation assets in European regulatory compression. Mid-cap compounders with active BMW or Mercedes-Benz qualifications represent priority acquisition archetypes. Watch for inflection signals in Indian domestic OEM capacity announcements, which would trigger qualified supplier demand outside German supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive System R&D Intensification | Henkel AG sustains premium positioning through moisture-cure polyurethane innovation for heat-critical automotive seating. |
| Backward Integration into Acrylic Supply | The Dow Chemical Company leverages captive resin production to dominate water-based formulation cost structures. |
| Geographic Manufacturing Footprint Expansion | H.B. Fuller anchors supply density in Michigan and Ohio footwear corridors through localized compounding assets. |
| Long-term Supply Agreement with OEMs | Volkswagen and Toyota frame contracts compress distributor margins while securing volume commitments for qualified suppliers. |
| Joint Venture with Electrostatic Equipment Manufacturers | Strategic partnerships reshape specification influence in Korean consumer electronics precision flocking applications. |
Research Approach
A standing panel of adhesive formulation chemists, Tier 1 automotive supplier procurement directors, electrostatic equipment engineers, and aerospace materials qualification specialists provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with downstream OEM specification authorities and secondary validation through customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed compounders, and ECHA regulatory submission databases. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Consistency checks validated segment-level outputs against external benchmarks including vehicle production databases, IHS Markit registration data, and aerospace seating delivery schedules. The analytical framework modeled formulation type, application vertical, end-user industry, and regional production hub dimensions across the projection horizon. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections, incorporating automotive interior content per vehicle and electronics housing precision application adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance enforcement or accelerated Indian automotive capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding ECHA VOC limit trajectory and OEM qualification timeline stability. Practitioners should keep alternative scenarios live as petrochemical feedstock volatility and electrostatic application technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market