
 Solvent Based Laminating Adhesives Market | 2026-2036
Solvent Based Laminating Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent Based Laminating Adhesives Market Analytics
Flexible packaging bundling around portion-controlled and single-serve formats is hardening buyer preference for high-performance laminating systems. Henkel AG & Co. KGaA leverages its European coating technology base to supply premium polyurethane grades for food barrier films. H.B. Fuller anchors North American distribution through direct technical service relationships with mid-sized converters. Dow competes on manufacturing scale, operating integrated polyol and isocyanate streams that lower raw material cost volatility for adhesive formulations.
Solvent based laminating adhesives are two-component systems, typically comprising polyurethanes or epoxies dissolved in organic carriers such as ethyl acetate or toluene, applied via gravure or roll coating before solvent evaporation and chemical crosslinking bond dissimilar substrates. Their primary purpose is to join films, foils, and papers into multilayer structures that deliver oxygen barrier, moisture resistance, and print protection in flexible packaging and industrial laminates. Polyurethane formulations lead volume due to versatility across film substrates and cure speeds that match high-speed converting lines. Epoxy segments occupy narrower positions in electronics and rigid industrial laminates where thermal stability and chemical resistance command price premiums. Acrylic technology is gaining traction in pressure-sensitive transitions and lower-temperature applications where reduced energy curing aligns with sustainability targets.
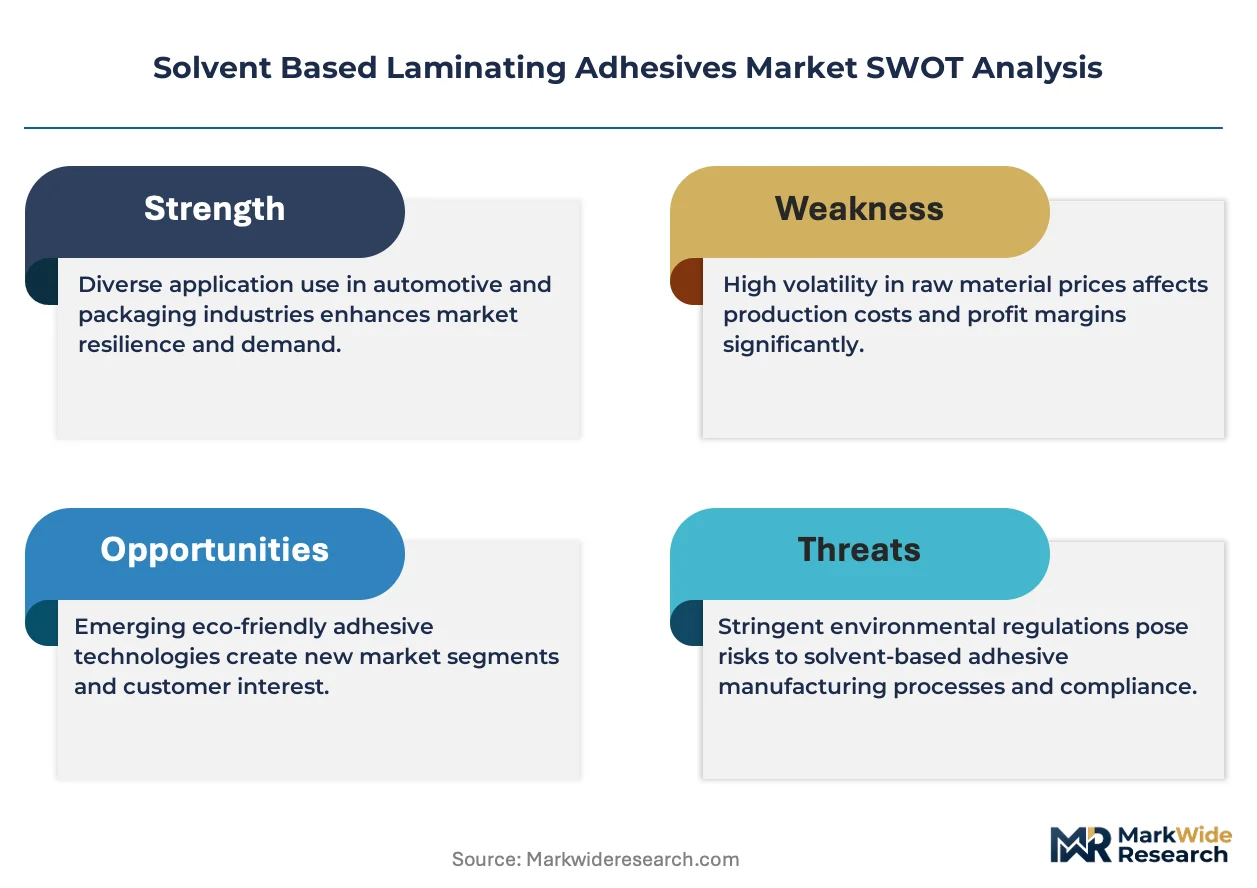
EPA regulations in the United States enforce National Emission Standards for Hazardous Air Pollutants that limit solvent emissions from coating operations, compelling adhesive producers to invest in recovery systems or waterborne alternatives. REACH and the EU F-Gas Regulation in Europe classify specific solvent chemistries as substances of very high concern, restricting market access for non-compliant formulations and redirecting R&D toward exempt carrier systems. China's MEE enforces GB standards on volatile organic compound emissions from packaging material production, creating compliance cost differentiation between domestic and import suppliers. Stakeholders must monitor regulatory divergence across these three jurisdictions to determine where reformulation investment yields durable competitive position versus stranded asset risk.
Market Dynamics
REACH and the EU F-Gas Regulation are forcing systematic reformulation of solvent-based laminating adhesives toward lower-VOC carriers, while Chinese domestic capacity expansion concentrates procurement decisions in Asia-Pacific converting clusters.
Growth Catalysts
- Flexible packaging demand:Food and beverage converters are expanding high-barrier multilayer film production to serve portion-controlled and single-serve formats, sustaining procurement of solvent-based polyurethane systems.
- China capacity expansion:Domestic flexible packaging manufacturing clusters in Jiangsu and Zhejiang provinces are scaling fastest globally, pulling regional adhesive supply chain investment.
- GB standards enforcement:China's MEE volatile organic compound emission limits for packaging material production are accelerating compliant solvent recovery system deployment among domestic suppliers.
Market Restraints
- Raw material volatility:Polyol and isocyanate feedstock costs fluctuate with crude oil derivatives, compressing formulation margins for non-integrated producers.
- Regulatory friction:EPA National Emission Standards for Hazardous Air Pollutants impose solvent recovery capital requirements that disadvantage small-scale US converters.
- Waterborne substitution:Acrylic and polyurethane dispersion technologies are capturing lower-performance flexible packaging segments where barrier requirements permit.
Strategic Opportunities
- India packaging growth:Underpenetrated flexible packaging conversion in Maharashtra and Gujarat states offers white space for solvent-based adhesive suppliers meeting BIS quality certifications.
- Electronics laminates:Epoxy-based solvent systems command thermal stability premiums in rigid industrial applications for printed circuit board manufacturing.
- Dual carbon alignment:China's national carbon neutrality targets are creating preferential financing for adhesive producers deploying solvent recovery and thermal oxidation systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in polyurethane crosslinking kinetics and substrate adhesion is concentrating among senior technical staff at established suppliers.
- Multijurisdictional compliance:Divergent VOC thresholds across EPA, REACH, and GB standards force parallel product line maintenance, elevating R&D overhead.
- Legacy equipment retrofit:Gravure coating lines designed for high-solvent formulations require capital-intensive modification to handle lower-viscosity carrier systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent Based Laminating Adhesives Market |
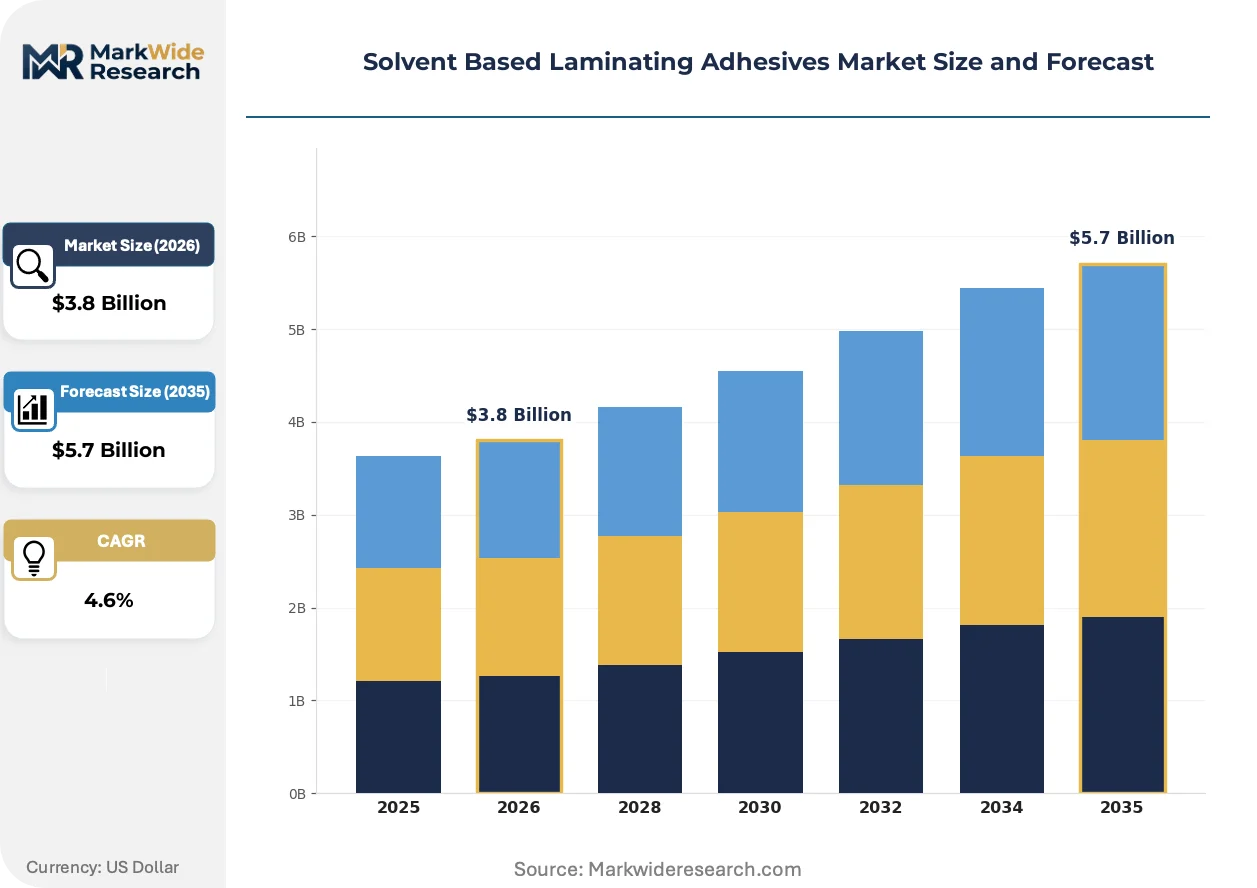
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Rubber Application: Packaging, Automotive, Construction, Electronics End User: Manufacturers, Distributors, Retailers, Contractors Technology: Coating, Extrusion, Printing, Hot Melt |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller, Arkema, Dow, BASF, Sika AG, Ashland, Flint Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent Based Laminating Adhesives Market Evolving Landscape
Digital process control systems and inline spectroscopic monitoring are automating quality assurance in adhesive application, while regulatory pressure on volatile organic compounds accelerates carrier chemistry diversification across major producing regions.
Inline near-infrared spectroscopy is automating real-time coating weight verification and solvent residual detection on high-speed laminating lines. Flexible packaging converters in Germany and Japan are deploying these systems to reduce offline laboratory testing and accelerate lot release. The technology is automating compliance documentation for REACH and FDA food contact audits, compressing the window between production and shipment.
The EU F-Gas Regulation is reclassifying hydrofluorocarbon and certain hydrocarbon solvent carriers as restricted substances, compelling adhesive formulators to qualify exempt alternatives such as methyl acetate and specific glycol ethers. European coating operations face retrofit deadlines that favor suppliers with established low-solvent polyurethane grades. Food barrier film producers are responding by consolidating procurement around formulators with verified regulatory dossiers.
Converter consolidation across North American flexible packaging is compressing supplier negotiation cycles and unbundling technical service from material pricing. Mid-sized adhesive distributors are losing share to direct manufacturer relationships as buyer concentration elevates volume-based contracting. The shift is most visible in Wisconsin and Ohio converting clusters where private equity-backed roll-up strategies have reduced active supplier counts by half.
Solvent Based Laminating Adhesives Market Segmentation
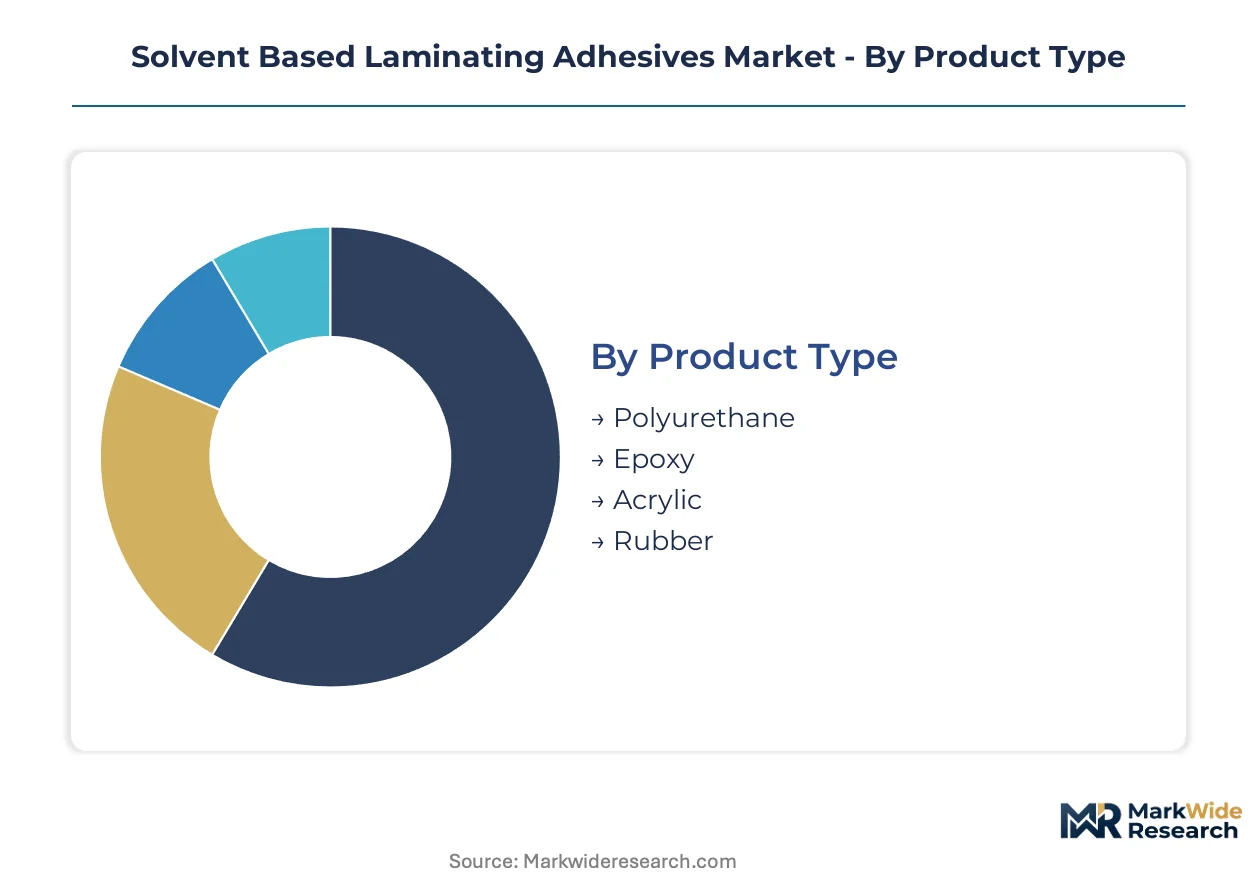
Segmentation in solvent-based laminating adhesives determines which formulations qualify for food contact approvals, automotive specifications, and electronics-grade certifications. Each product type and application carries distinct regulatory burdens that shape supplier qualification timelines and customer switching costs.
Product Type:
Polyurethane and epoxy systems face the heaviest certification loads, with polyurethane requiring FDA food contact dossiers and epoxy demanding REACH SVHC screening for electronics applications.
- Polyurethane:Two-component systems combining polyols with aromatic or aliphatic isocyanates dissolved in ethyl acetate carriers. Flexible packaging converters in Jiangsu province are scaling procurement for high-barrier multilayer films serving portion-controlled food formats, though REACH VOC thresholds are forcing reformulation toward lower-solvent grades.
- Epoxy:Bisphenol-A or novolac-based resins cured with amine hardeners in aromatic solvents. Demand concentrates in rigid industrial laminates for printed circuit board manufacturing, where thermal stability and chemical resistance command specification premiums despite higher raw material costs.
- Acrylic:Pressure-sensitive formulations gaining traction in lower-temperature applications where reduced energy curing aligns with sustainability targets.
- Rubber:Natural and synthetic elastomer solutions serving niche industrial bonding applications with less stringent barrier requirements.
Polyurethane sits at the top of the volume ranking, with acrylic climbing the fastest as converters seek lower-VOC alternatives.
Application:
Cost tier stratification separates premium food barrier films from commodity construction laminates, with packaging commanding formulation investment and electronics driving specification intensity.
- Packaging:Flexible food and beverage films requiring oxygen barrier, moisture resistance, and print protection. High-speed gravure coating lines in Wisconsin and Ohio converting clusters are consolidating procurement around direct manufacturer relationships, compressing distributor margins.
- Automotive:Interior trim laminates and structural bonding applications where flame retardancy and fogging resistance specifications vary by OEM.
- Construction:Building membrane and insulation facings where cost sensitivity favors higher-solvent formulations despite regulatory pressure.
- Electronics:Rigid industrial laminates for PCB manufacturing where epoxy systems dominate and thermal stability premiums justify specialized supply chains.
Packaging commands the largest revenue pool, while electronics delivers the steepest margin expansion trajectory.
End User:
Customer type determines technical service intensity, with manufacturers demanding formulation customization and retailers prioritizing logistics reliability over product engineering.
- Manufacturers:Flexible packaging converters and industrial laminators requiring direct technical service relationships and customized viscosity specifications for existing gravure equipment.
- Distributors:Mid-sized regional players losing share to direct manufacturer relationships as buyer consolidation elevates volume-based contracting.
- Retailers:Private label packaging suppliers prioritizing supply security and documentation compliance over formulation innovation.
- Contractors:Construction and automotive applicators with intermittent demand patterns and lower switching costs.
Manufacturers anchor the highest volume concentration, with distributor relevance contracting fastest amid procurement consolidation.
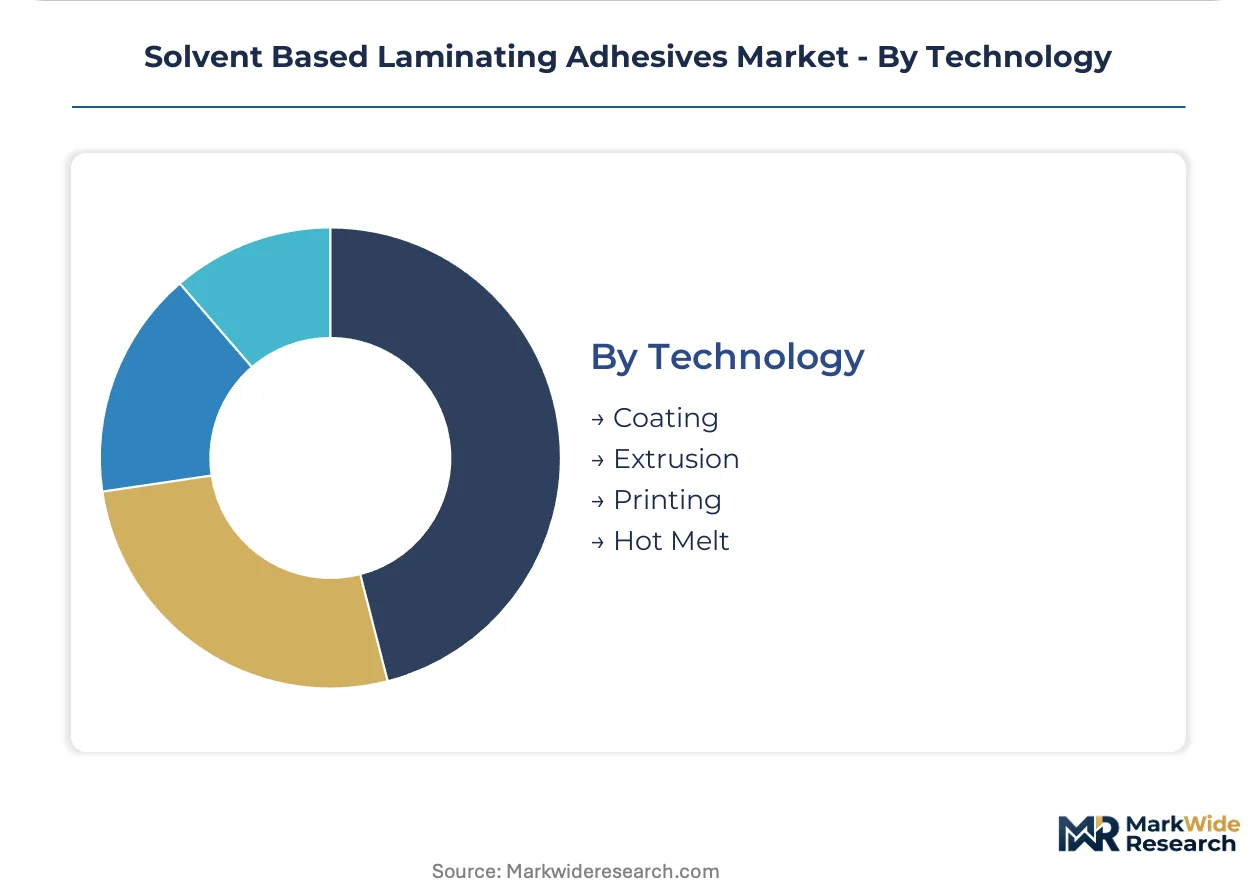
Technology:
Application method maturity correlates with capital intensity, with coating technology dominating installed base and hot melt representing the displacement threat.
- Coating:Gravure and roll coating systems applying dissolved adhesives before solvent evaporation and chemical crosslinking. Inline near-infrared spectroscopy is automating real-time coating weight verification in German and Japanese facilities.
- Extrusion:Molten polymer application eliminating solvent carriers entirely, capturing share where barrier requirements permit.
- Printing:Integrated adhesive-printing systems for decorative and functional laminates with reduced process steps.
- Hot Melt:Solvent-free polyurethane and metallocene polyolefin systems displacing solvent-based grades in lower-performance packaging segments.
Coating retains the dominant installed base position, with hot melt gaining share fastest in sustainability-sensitive procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial laminating adhesive chemistry during post-war reconstruction of its packaging machinery sector. Japanese converters later scaled solvent-based polyurethane systems for electronics and food barrier films. Chinese domestic capacity now drives the majority of new adhesive demand.
Germany
Automotive interior laminates and high-barrier food packaging sustain steady demand for solvent-based systems. REACH and the EU F-Gas Regulation enforce strict VOC thresholds, compelling formulators toward exempt carrier chemistries. The Rhine-Ruhr industrial corridor hosts specialized coating operations serving premium flexible packaging converters.
United States
Flexible packaging consolidation in Wisconsin and Ohio elevates volume contracting for polyurethane laminating adhesives. EPA National Emission Standards for Hazardous Air Pollutants mandate solvent recovery capital investments that disadvantage small-scale converters. Technical service relationships anchor supplier-customer bonds amid procurement centralization.
China
Jiangsu and Zhejiang provinces scale domestic flexible packaging manufacturing faster than any other region globally. MEE enforcement of GB standards on VOC emissions accelerates compliant solvent recovery system deployment among adhesive suppliers. Yangtze River Delta converting clusters pull regional supply chain investment toward integrated polyol and isocyanate streams.
Japan
Electronics-grade epoxy laminates for printed circuit board manufacturing command thermal stability premiums. METI industrial standards govern chemical emissions from coating operations, shaping formulation portfolios. Kanto region facilities deploy inline near-infrared spectroscopy for real-time quality assurance on high-speed laminating lines.
India
Underpenetrated flexible packaging conversion in Maharashtra and Gujarat states offers expansion opportunity for compliant adhesive suppliers. BIS quality certifications create qualification barriers that favor established formulators with documented regulatory dossiers. Domestic converters are upgrading gravure equipment to handle higher-performance multilayer film structures.
Solvent Based Laminating Adhesives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance depth and technical service intensity. The market exhibits tiered consolidation, with integrated chemical producers commanding raw material cost advantages while specialized adhesive formulators compete on formulation customization. Three archetypes dominate: diversified multinational chemical conglomerates with captive feedstock supply, focused adhesive specialists leveraging direct technical relationships, and regional formulators serving price-sensitive construction segments. Capacity expansion and portfolio diversification toward lower-VOC alternatives represent the dominant competitive moves.
Among diversified chemical conglomerates, Dow exemplifies scale-driven positioning through integrated polyol and isocyanate manufacturing. Henkel AG & Co. KGaA occupies the specialist tier, anchoring premium polyurethane supply through European coating technology heritage. H.B. Fuller represents the technical service-intensive archetype, maintaining direct relationships with mid-sized North American converters. These three entities illustrate how competitive positioning stratifies across manufacturing integration, regional regulatory expertise, and customer intimacy vectors.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller |
| Arkema |
| Dow |
| BASF |
| Sika AG |
| Ashland |
| Flint Group |
| Others |
Value Network & Pricing Analysis
Flexible packaging converter consolidation in Wisconsin and Ohio is compressing supplier negotiation cycles and elevating volume-based contracting, forcing adhesive formulators to absorb polyol and isocyanate feedstock volatility or cede share to integrated chemical producers with captive raw material supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant food contact formulations from industrial-grade epoxies and commodity construction adhesives. Price differentiation rests on certification grade and volume scale, with REACH-compliant low-VOC carriers commanding premiums amid regulatory divergence. Cost compression in standard-tier polyurethane systems is intensifying because Chinese domestic capacity expansion feeds oversupply into Asia-Pacific spot markets. Distributors exhibit highest price sensitivity as direct manufacturer relationships disintermediate their technical service bundling.
Supply Chain Analysis
Freight cost differentials between integrated producers in Germany and import-dependent converters in India are widening procurement preference for regional supply bases. Raw material supply concentrates in China, Germany, and the United States, with polyol and isocyanate production anchored in Yangtze River Delta and Rhine-Ruhr chemical corridors. Feedstock costs hinge on crude oil derivative volatility, creating margin compression for non-integrated formulators. Single-source vulnerability runs through aromatic solvent carriers facing EU F-Gas reclassification. Distribution runs through direct technical service relationships with large converters and regional distributors serving mid-tier packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solvent-based laminating adhesives market functions as a stable compounder, with flexible packaging demand for high-barrier multilayer films sustaining procurement volume despite regulatory pressure on volatile organic compound emissions.
For Market Incumbents: Hedge formulation portfolios by accelerating low-solvent polyurethane qualification for REACH-exempt carrier systems while maintaining high-solvent grades for price-sensitive construction segments. Backward integration into captive polyol streams defends margin position against feedstock volatility from crude oil derivatives. Technical service capacity expansion in Jiangsu and Zhejiang provinces captures procurement consolidation among Chinese flexible packaging converters scaling fastest globally. For New Entrants and Emerging Players: Enter via underpenetrated flexible packaging conversion in Maharashtra and Gujarat states, where BIS certification barriers favor established formulators but equipment upgrade cycles create technical service gaps. Electronics-grade epoxy laminates for printed circuit board manufacturing offer specification-intensive entry points with thermal stability premiums that justify specialized supply chain investment. Partner with gravure equipment OEMs to bundle adhesive formulation with retrofit consulting for legacy coating lines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized European adhesive specialists possessing verified REACH regulatory dossiers and direct relationships with premium food barrier film producers. Long-term viability centers on formulation chemistry expertise that concentrates among senior technical staff at established suppliers, creating scarcity value as waterborne substitution pressures commodity segments. Monitor GB standards enforcement intensity in China as inflection indicator for compliant solvent recovery system deployment rates among domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive feedstock production insulates margin compression from crude oil derivative volatility. |
| Low-VOC Formulation Qualification | REACH-exempt carrier systems secure premium positioning amid EU F-Gas reclassification deadlines. |
| Direct Technical Service Expansion | Manufacturer-converter relationships disintermediate distributors as buyer consolidation elevates volume contracting. |
| Solvent Recovery System Deployment | MEE-compliant thermal oxidation equipment unlocks preferential financing under China's dual carbon targets. |
| Regional Supply Base Localization | Jiangsu and Zhejiang proximity reduces freight differentials against integrated German producers. |
Research Methodology
Bottom-up flexible packaging converter modeling reconciled against top-down adhesive production tracking forms the analytical core of this study. Primary interviews with plant managers at laminating facilities, procurement leads at food and beverage OEMs, distribution channel partners, and technical R&D directors at formulation houses were validated against secondary sources including customs and trade data, chemical industry association reports, and SEC regulatory filings. Triangulation between demand-side procurement patterns and supply-side capacity announcements ensures cross-verification of volume estimates across the analysis window.
Input-output matrices map polyol and isocyanate feedstock availability through adhesive formulation to end-use application demand across packaging, automotive, construction, and electronics segments. Modeled dimensions include product chemistry tier, regulatory compliance grade, application performance specification, and regional production hub concentration. CAGRs were derived from segment-level volume trajectories weighted against capacity expansion announcements and equipment investment cycles. Forecast inputs incorporate REACH and EPA regulatory timeline assumptions, GB standards enforcement intensity, and converter gravure line retrofit adoption curves.
Inputs from laminating facility operators and chemical trade databases were available through the study window; gaps in real-time inventory positioning data among private-label packaging suppliers introduce uncertainty bands around quarterly demand inflection points. Forecasts reflect documented assumptions regarding regulatory implementation schedules and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context, particularly regarding solvent recovery capital deployment timelines and buyer consolidation trajectories in regional converting clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Amine Curing Agents Market