
 Mexico Data Center Construction Market | 2026-2036
Mexico Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Construction Market Insights
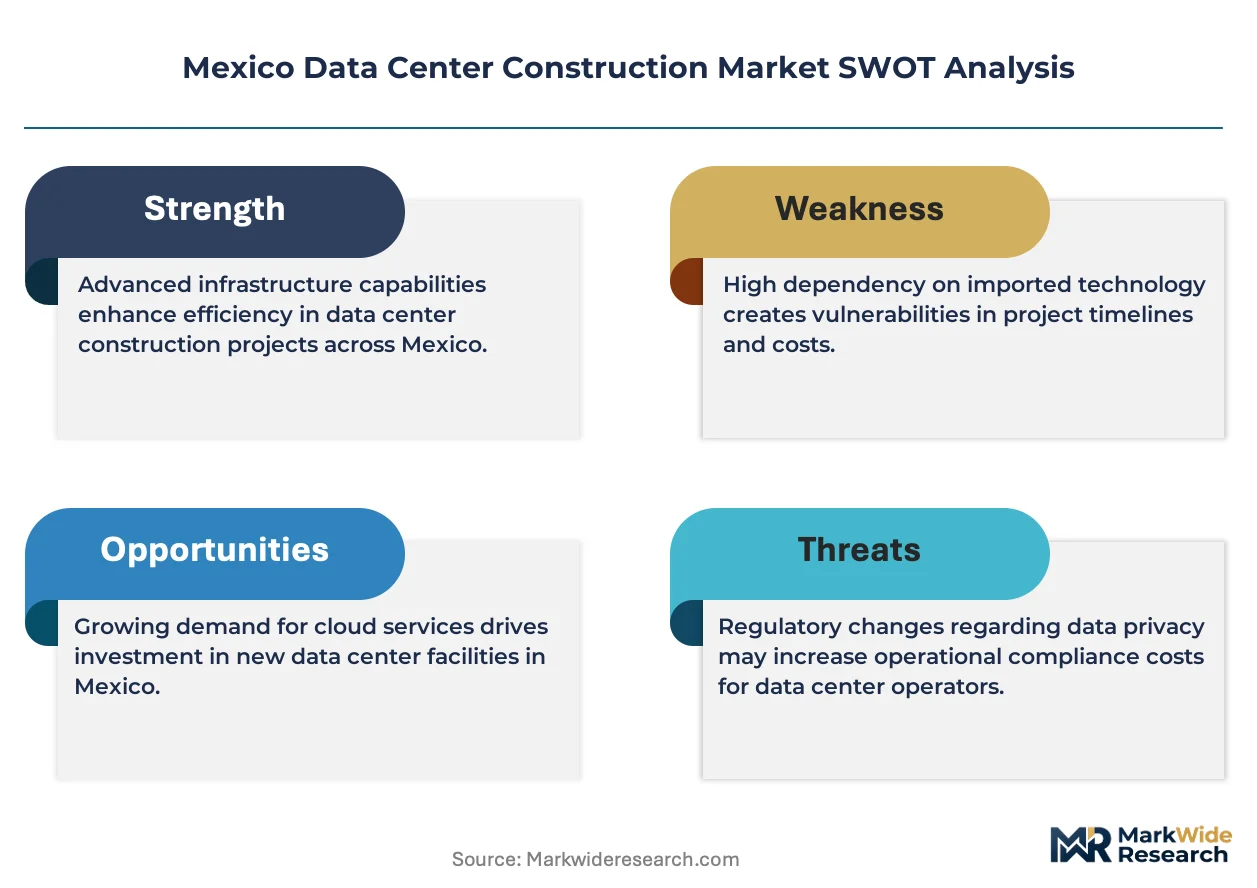
Mexico is tilting toward data center capacity expansion as North American enterprises seek geographic diversification from US primary markets. Scala Data Centers leverages its Brazilian heritage to anchor hyperscale deployments in Querétaro and Mexico City. Equinix sustains interconnection density through carrier-neutral campuses that dominate financial and cloud exchange traffic. KIO Networks specializes in sovereign-compliant facilities that navigate Mexico's data localization pressures for government and enterprise clients.
Data center construction encompasses the engineering, procurement, and assembly of purpose-built facilities housing servers, storage systems, and network equipment with redundant power distribution, precision cooling maintaining 18-27°C, and fire suppression infrastructure. These structures serve as the physical backbone for digital service delivery across cloud, colocation, and enterprise IT architectures. Modular product types are capturing accelerated deployment cycles as operators compress commissioning timelines for cloud computing workloads. Edge computing installations within colocation frameworks are generating premium margin pools where latency-sensitive applications demand distributed presence.
CRE and PROFECO oversight shapes commercial contracting standards for construction services, while NOM-001-SEDE electrical specifications mandate grounding, protection, and energy efficiency thresholds for facility certification. CFE interconnection agreements and tariff structures directly influence site selection economics and power redundancy design decisions. Stakeholders must monitor regulatory evolution around renewable energy sourcing requirements as sustainability criteria increasingly filter into permitting timelines and operator procurement specifications.
Market Dynamics
Hyperscaler deployment timelines are compressing construction cycles across Mexico's central corridor, forcing modular prefabrication methods to displace traditional stick-built approaches in facility delivery.
Growth Catalysts
- Cloud computing adoption:Financial institutions in Mexico City are expanding colocation footprints to meet latency requirements for real-time trading platforms and digital banking infrastructure.
- NOM-001-SEDE electrical standards:The national electrical regulator's updated grounding and protection mandates are modernizing facility certification, accelerating replacement of aging infrastructure.
- Querétaro aerospace corridor:Defense and aviation manufacturers are co-locating mission-critical IT with data center operators to satisfy sovereign data requirements and supply chain security protocols.
Market Restraints
- Copper and electrical steel volatility:Transformer and switchgear lead times have extended to 26-32 weeks, constraining power distribution commissioning schedules.
- CFE interconnection bottlenecks:The national utility's 115kV and 230kV queue backlogs in Mexico State and Nuevo León are delaying hyperscaler site energization by 8-14 months.
- Liquid cooling retrofit limitations:Legacy raised-floor facilities cannot accommodate direct-to-chip cooling densities above 30kW per rack without structural reinforcement.
Strategic Opportunities
- Guadalajara tech corridor:Software development clusters are underserved by Tier III facilities, creating white space for edge computing nodes serving SaaS and fintech workloads.
- Renewable energy procurement:CFE's self-supply and legacy contract frameworks now permit direct power purchase agreements with wind and solar developers, reducing carbon intensity for sustainability-mandated clients.
- AI training cluster convergence:GPU-intensive workloads are driving demand for liquid-cooled hyperscale halls that integrate with existing fiber routes to Texas and California.
Industry Challenges
- Certified commissioning engineers:Uptime Institute and TIA-942 accredited professionals are concentrated in Mexico City, creating talent scarcity for Querétaro and Monterrey deployments.
- NOM-001-SEDE compliance timelines:Third-party electrical inspection backlogs are extending final connection authorizations by 4-6 weeks beyond mechanical completion.
- Legacy facility integration:Brownfield expansions must reconcile 480V/60Hz legacy distribution with 400V/50Hz European equipment specifications prevalent in modern prefabricated power modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Construction Market |
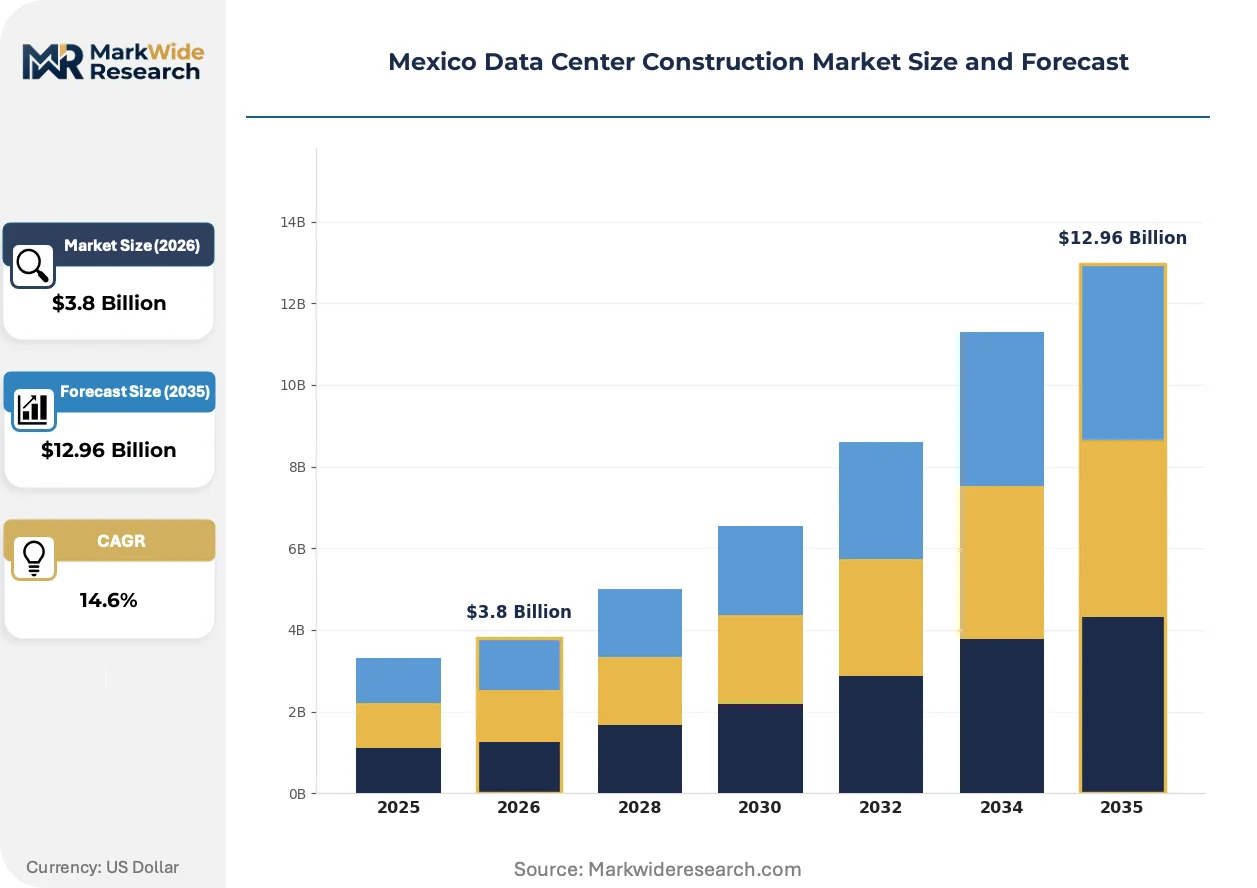
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Containerized, Traditional, Hybrid Technology: Cloud Computing, Edge Computing, Colocation, Bare Metal End User: Telecommunications, Healthcare Providers, IT Firms, Financial Institutions Installation: On-site Construction, Prefabricated Installation, Retrofitting, Maintenance Services |
| Companies Covered | Scala Data Centers, Layer 9 Data Centers, CloudHQ, ODATA, Ascenty, Equinix, EdgeConneX, Terranova, KIO Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Construction Market Trends and Innovations
Facility delivery methods are pivoting toward factory-integrated systems that compress on-site assembly, while regulatory pressure on energy efficiency and water usage reshapes mechanical design priorities.
Modular data center enclosures are migrating from steel-skid containers to concrete-composite prefabricated buildings that integrate UPS, cooling, and fire suppression in factory-controlled conditions. Hyperscalers deploying in Querétaro and Mexico City are specifying 12-16 week delivery windows versus 9-12 months for traditional construction. This compression is enabling phased capacity expansion that matches cloud revenue ramps without stranded capital.
CRE and PROFECO commercial oversight is tightening contracting transparency for construction services, mandating detailed milestone-based payment structures and performance bonds. The national consumer protection agency's enforcement actions against delayed delivery penalties are forcing EPC firms to refine project scheduling methodologies. Mid-market colocation operators are responding by adopting fixed-price modular contracts that transfer completion risk to integrators.
Water-stressed site selection is elevating adiabatic and closed-loop cooling architectures over traditional evaporative systems in northern Mexico. Buyers in Monterrey and Chihuahua are specifying zero-water cooling as a procurement threshold, disqualifying conventional cooling tower designs. This preference shift is concentrating mechanical innovation investment in dry-cooler and refrigerant-based systems that maintain PUE targets without municipal water dependence.
Mexico Data Center Construction Market Segmentation
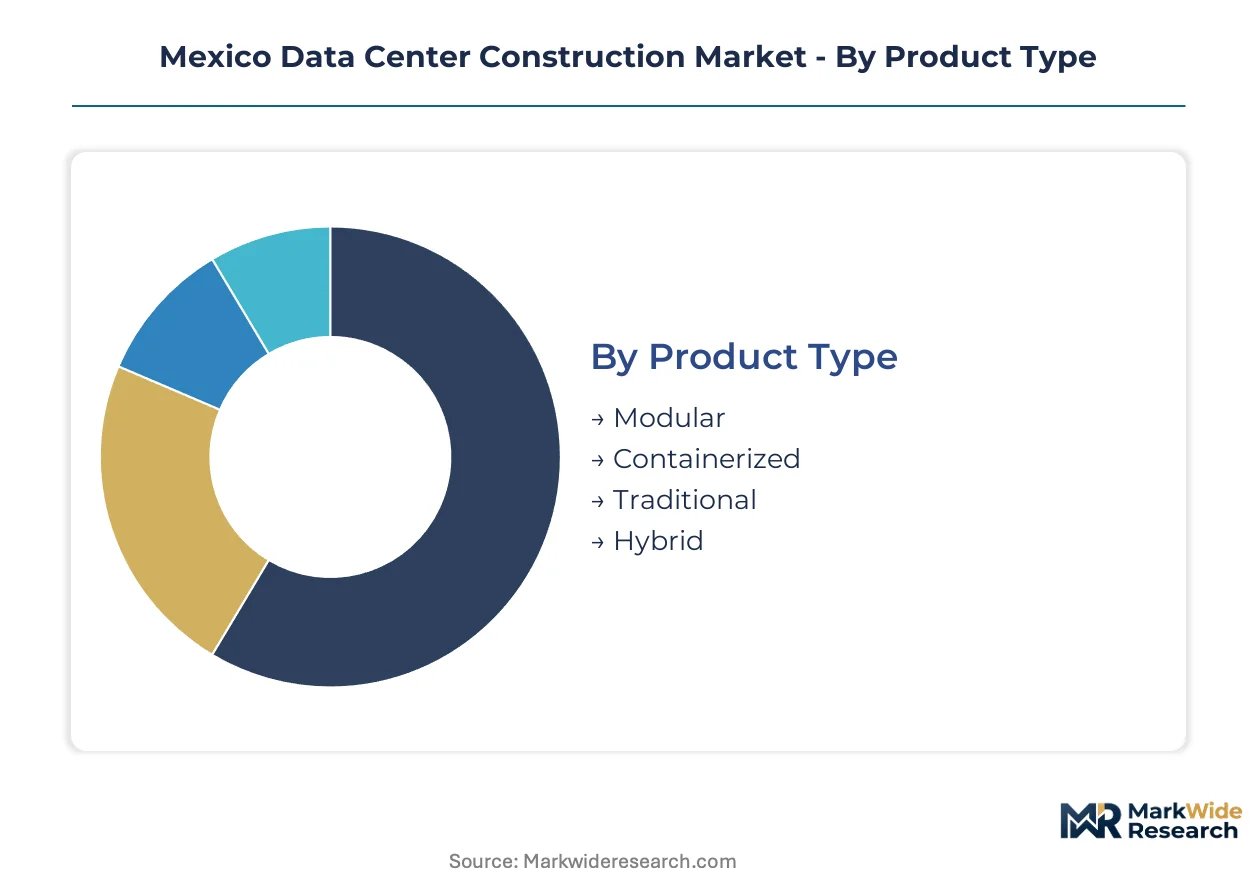
Mexico's data center construction market fragments across deployment methodologies, processing architectures, and client verticals. Each segment carries distinct engineering requirements, certification timelines, and margin structures that shape vendor positioning.
Product Type:
Deployment velocity separates procurement strategies across Mexico's central corridor, with hyperscalers prioritizing speed-to-market over capital intensity.
- Modular:Factory-integrated power and cooling modules arrive pre-tested to Querétaro and Mexico City sites, compressing commissioning from 9-12 months to 12-16 weeks. Financial institutions facing NOM-001-SEDE compliance deadlines favor this approach for brownfield expansions.
- Containerized:Steel-skid enclosures house 100-500kW capacity blocks suited to edge computing nodes in Guadalajara's software corridor. CFE interconnection bottlenecks in Nuevo León constrain rapid scaling of this format despite its mobility advantages.
- Traditional:Stick-built concrete structures dominate legacy campus expansions in Mexico City where land scarcity and zoning stability justify extended construction cycles.
- Hybrid:Combinations of prefabricated mechanical halls with traditional administrative wings balance speed against customization for sovereign-compliant government facilities.
Established volume favors Traditional; emerging adoption favors Modular.
Technology:
Workload characteristics dictate facility specifications, with latency sensitivity and data sovereignty requirements driving divergent infrastructure investments.
- Cloud Computing:Hyperscale halls in Querétaro's aerospace corridor integrate 30MW+ capacity blocks with direct fiber routes to Texas. GPU-intensive training clusters are forcing liquid cooling retrofits that strain legacy raised-floor specifications.
- Edge Computing:Distributed nodes serving real-time trading platforms in Mexico City require sub-10ms latency, commanding premium colocation rates. KIO Networks and Equinix are anchoring metropolitan presence to capture this demand.
- Colocation:Carrier-neutral campuses aggregate financial and cloud exchange traffic, with interconnection density determining tenant stickiness.
- Bare Metal:Dedicated server deployments satisfy defense and aviation manufacturers' sovereign data requirements in the Querétaro corridor.
Cloud Computing commands the largest capital allocation; Edge Computing is climbing the fastest as fintech workloads proliferate.
End User:
Regulatory exposure and uptime requirements segment client procurement behavior across Mexico's data center market.
- Telecommunications:Mobile network operators building 5G core infrastructure drive demand for distributed edge capacity with 99.999% availability guarantees.
- Healthcare Providers:Patient data protection mandates under Mexican health privacy frameworks require sovereign-compliant facilities with encrypted storage architectures.
- IT Firms:SaaS developers in Guadalajara's technology cluster seek scalable colocation without hyperscale minimum commitments.
- Financial Institutions:Real-time trading platforms and digital banking infrastructure in Mexico City mandate Tier III certification with sub-15ms latency to primary exchanges.
Financial Institutions anchor premium pricing; IT Firms represent the most price-elastic demand pool.
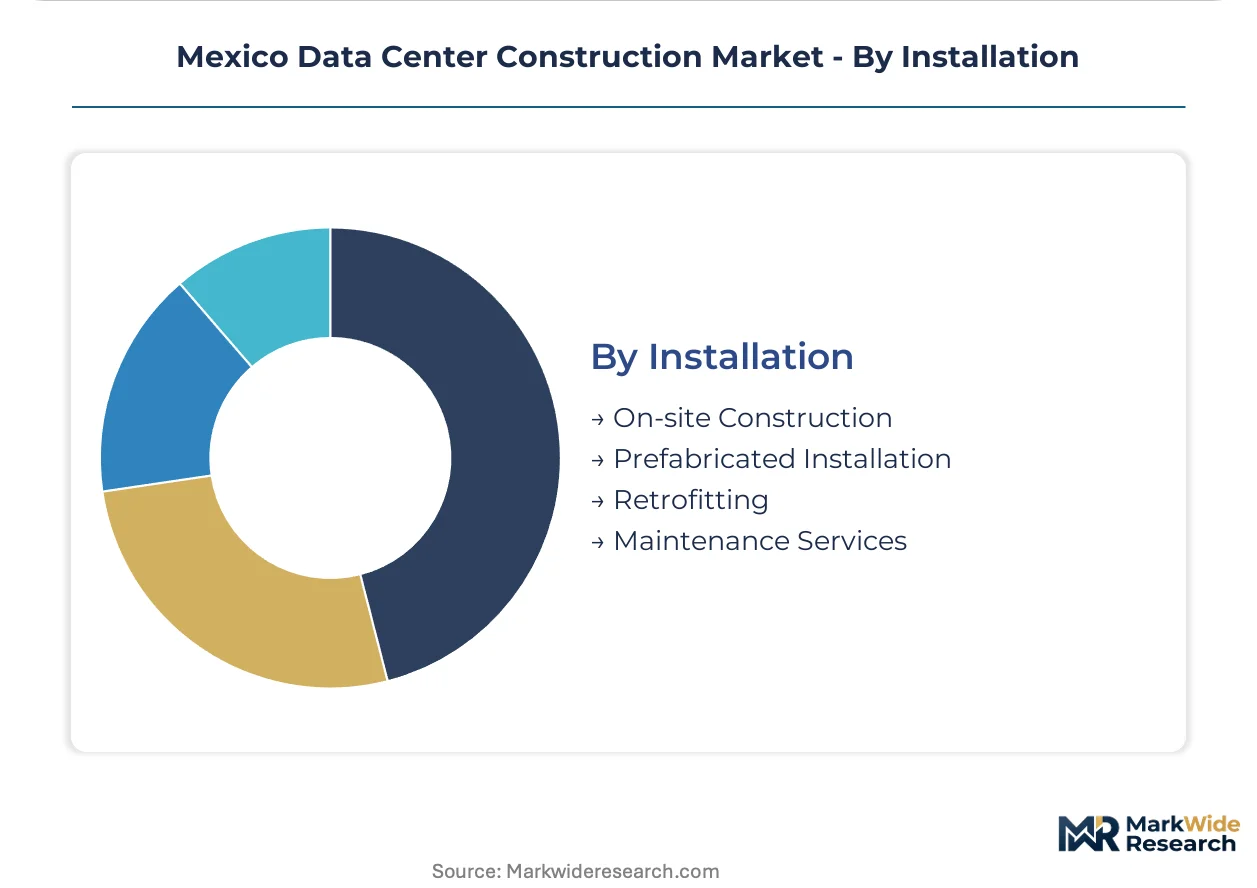
Installation:
Project delivery models are shifting risk allocation between operators and construction firms under tightening CRE and PROFECO oversight.
- On-site Construction:Traditional build methods persist for hyperscale campuses where customization outweighs speed, though CFE interconnection delays extend overall project timelines.
- Prefabricated Installation:Factory-controlled assembly transfers completion risk to integrators, aligning with fixed-price contract structures that PROFECO enforcement actions are mandating.
- Retrofitting:Legacy facility upgrades face NOM-001-SEDE electrical inspection backlogs that extend final connection authorizations by 4-6 weeks.
- Maintenance Services:Ongoing operations contracts concentrate in Mexico City where certified commissioning engineers are most available.
Prefabricated Installation is gaining share fastest; Maintenance Services provide recurring revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility investment clusters along Mexico's central corridor where CFE grid infrastructure and fiber density converge. NOM-001-SEDE electrical mandates and state-level permitting frameworks differentiate deployment economics across sub-regions.
Mexico City Metro
Financial institutions and cloud exchanges drive Tier III demand for sub-15ms latency to trading platforms. CFE interconnection queues for 115kV service extend energization timelines by 8-14 months. The Santa Fe and Tlalnepantla corridors concentrate carrier-neutral campuses serving fintech and digital banking workloads.
Querétaro
Aerospace manufacturers and defense contractors anchor sovereign-compliant capacity for supply chain security protocols. PROFECO milestone-based contracting mandates reshape EPC payment structures for brownfield expansions. The El Marqués technology corridor hosts prefabricated modular deployments compressing commissioning to 12-16 weeks.
Nuevo León
Monterrey's industrial base generates enterprise colocation demand for manufacturing ERP and IoT platforms. CFE 230kV queue backlogs constrain hyperscaler site selection despite favorable land availability. Apodaca and Escobedo sub-markets attract edge computing nodes for cross-border logistics optimization.
Jalisco
Guadalajara's software development cluster creates underserved demand for Tier III facilities among SaaS developers. State economic development incentives target data center investment through infrastructure tax abatements. The Zapopan technology corridor remains supply-constrained for scalable colocation without hyperscale minimum commitments.
Bajío Region
Automotive and electronics manufacturing clusters drive mission-critical IT co-location for just-in-time production systems. NOM-001-SEDE third-party inspection backlogs extend final connection authorizations by 4-6 weeks. León and Aguascalientes sub-markets favor hybrid deployment models balancing prefabricated mechanical halls with traditional administrative wings.
Mexico Data Center Construction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electrical and mechanical supply chains. The vendor base separates into three strategic tiers: hyperscale developers anchoring multi-hundred-megawatt campuses, regional specialists delivering sovereign-compliant facilities, and modular integrators compressing deployment cycles. Consolidation pressure intensifies as CFE interconnection scarcity forces capacity aggregation. Competitive moves center on fixed-price EPC contracting transfer and prefabrication capability acquisition.
Among Brazil-origin platform operators, Scala Data Centers and Ascenty exemplify the hyperscale deployment archetype leveraging Latin American heritage for cross-border capacity planning. Equinix occupies the interconnection-density tier with carrier-neutral positioning across Mexico City financial corridors. KIO Networks represents the sovereign-specialist archetype navigating data localization mandates for government and defense clients.
| Leading Market Players |
|---|
| Scala Data Centers |
| Layer 9 Data Centers |
| CloudHQ |
| ODATA |
| Ascenty |
| Equinix |
| EdgeConneX |
| Terranova |
| KIO Networks |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Querétaro's prefabricated module supply is tightening supplier pricing power while compressing EPC margins, forcing buyers toward longer-term offtake structures that lock in capacity allocation before CFE interconnection delays materialize.
Pricing Analysis
NOM-001-SEDE dictates the pricing tier structure across Mexico's data center construction market, separating Tier III-certified facilities with full electrical compliance from uncertified legacy builds. Price differentiation hinges on certification grade and volume scale, with hyperscale commitments commanding standard-tier rates while edge nodes absorb premium pricing for sub-10MW deployments. Cost compression in the traditional stick-built segment is intensifying because CFE queue backlogs extend project carrying costs. Financial institutions exhibit the lowest price sensitivity due to latency mandates, whereas SaaS developers in Guadalajara represent the most elastic demand pool.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for electrical steel and transformer components critical to power distribution assembly. Manufacturing concentrates in the United States, China, and Germany for switchgear and UPS systems, while precision cooling equipment sources primarily from Japan and South Korea. Raw material dependencies span copper, electrical steel, and refrigerants, with single-source vulnerability concentrated in 230kV transformer cores. Distribution runs through EPC integrators who bundle factory-integrated modules with on-site mechanical completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's data center construction market is approaching a platform-economics inflection where interconnection density and CFE queue position determine ecosystem value capture, with fiber route convergence to Texas and California creating interoperability premiums for cross-border capacity.
For Market Incumbents: Build switching-cost moats through long-term CFE interconnection reservations and NOM-001-SEDE certification lock-in that raises replacement costs for financial institution tenants. Defensive consolidation should prioritize prefabrication capability acquisition to compress delivery windows against modular specialists. Threats from Brazilian-origin hyperscale operators with Latin American cross-border planning heritage intensify margin pressure in Querétaro. For New Entrants and Emerging Players: Build out sovereign-compliant facility expertise targeting defense and aerospace manufacturers in the Querétaro corridor where data localization mandates create protected demand pools. Guadalajara's underserved Tier III gap for SaaS developers offers the most penetrable white space. Go-to-market positioning should emphasize zero-water cooling architectures that satisfy procurement thresholds in Monterrey and Chihuahua. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among maintenance services operators concentrated in Mexico City where certified commissioning engineer scarcity creates retention premiums. Long-term viability across the projection horizon favors modular integrators with factory-controlled assembly capabilities that transfer completion risk under PROFECO-mandated fixed-price structures. Watch CFE renewable energy self-supply contract evolution as the inflection signal for sustainability-mandated client procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Module Capacity Expansion | Factory-integrated power and cooling modules compress Querétaro commissioning from months to weeks. |
| CFE Interconnection Queue Positioning | Early 115kV and 230kV reservation secures Mexico State and Nuevo León site energization timelines. |
| NOM-001-SEDE Certification Investment | Third-party electrical inspection accreditation accelerates final connection authorizations for brownfield expansions. |
| Liquid Cooling Infrastructure Partnership | Direct-to-chip systems integration enables GPU-intensive AI training clusters above 30kW per rack. |
| Renewable Energy Procurement Agreement | CFE self-supply framework permits direct wind and solar PPAs for carbon-intensity reduction. |
Research Methodology
Initial hypotheses were tested against primary input from EPC project directors, CFE interconnection planners, data center operators, and commissioning engineers and refined through secondary validation against SEC filings from hyperscale deployers, CFE tariff schedules, NOM-001-SEDE regulatory texts, and customs data for electrical equipment imports. Bottom-up project pipeline aggregation was cross-checked with top-down capacity forecasts across the analysis window.
Demand-supply balance framing anchored the analytical approach, modeling deployment methodology, processing architecture, and client vertical dimensions throughout the forecast period. CAGRs were derived from installed capacity trajectories and construction spend patterns, with CFE queue backlogs and NOM-001-SEDE compliance timelines as industry-specific forecast inputs.
Stress conditions across CFE interconnection delays, copper and electrical steel price volatility, and certified engineer availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Transportation Infrastructure Construction Market