
 US Pipeline Construction Market | 2026-2036
US Pipeline Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US Pipeline Construction Market Insights
Permian Basin infrastructure build-out is fragmenting across multiple contractor tiers as project scale and technical complexity diverge. Kiewit Corporation anchors large-diameter interstate projects through integrated engineering-procurement-construction capabilities. Michels Corporation specializes in horizontal directional drilling deployments beneath sensitive waterways and urban corridors. Mastec, Inc. competes aggressively in last-mile distribution networks serving municipal gas utilities.
US pipeline construction encompasses the engineering, fabrication, and installation of tubular conduit systems for hydrocarbon and fluid transport, typically employing API 5L-grade steel with cathodic corrosion protection and operating pressures ranging from 200 to 1,440 psi depending on service class. Gas pipeline installation dominates capital allocation as utilities replace aging cast-iron distribution mains and expand takeaway capacity from Appalachian and Permian production zones. Horizontal directional drilling commands premium pricing in environmentally sensitive corridors where open-cut trenching faces permitting restrictions, while microtunneling gains traction beneath major river crossings and rail corridors where depth and accuracy requirements escalate.
PHMSA regulations govern pipeline safety standards, material certification, and operator qualification protocols, while EPA wetland permitting under Section 404 of the Clean Water Act shapes route selection and construction timing across interstate projects. FERC certificate authority for interstate natural gas pipelines creates a multi-year pre-construction review cycle that filters market participation toward capitalized entities with regulatory endurance. Stakeholders must monitor evolving methane emissions rules and state-level renewable natural gas injection mandates that could redirect pipeline investment toward biogas-compatible infrastructure.
Market Dynamics
PHMSA's 2024 integrity management mandates are compressing contractor qualification timelines while Appalachian shale operators accelerate gathering line replacements ahead of federal deadlines. This regulatory pressure is restructuring bid competitiveness around welding certification depth rather than equipment scale alone.
Growth Catalysts
- Natural gas distribution modernization:Municipal utilities in Texas and Pennsylvania are replacing century-old cast-iron mains with polyethylene and steel infrastructure, creating sustained demand for trenchless installation crews.
- FERC interstate certificate activity:The Federal Energy Regulatory Commission's streamlined environmental review for certain pipeline categories is shortening pre-construction cycles for cross-state projects.
- Permian Basin takeaway expansion:Midstream operators are building lateral connections between well pads and processing facilities, requiring extensive gathering network deployment across West Texas and southeast New Mexico.
Market Restraints
- Specialized labor scarcity:API 1104-certified welders command premium wages exceeding standard construction rates, compressing margins on fixed-bid contracts.
- Steel tariff volatility:Domestic plate and coil pricing fluctuations disrupt project budgeting for large-diameter transmission lines dependent on API 5L-grade material.
- EPA Section 404 permitting delays:Wetland crossing authorizations in the Upper Midwest frequently extend project timelines by 18-24 months beyond original schedules.
Strategic Opportunities
- Renewable natural gas injection infrastructure:California and Oregon mandates for biogas pipeline compatibility are creating retrofit demand for corrosion-resistant coating systems and upgraded compressor stations.
- Carbon capture transport corridors:Emerging CO2 pipeline networks linking ethanol plants to sequestration sites in North Dakota and Illinois require specialized metallurgy and pressure-rated welding protocols.
- Hydrogen blending pilot programs:Texas and Louisiana utility trials for 5-20% hydrogen injection into existing distribution mains are driving research partnerships between contractors and materials laboratories.
Industry Challenges
- Operator qualification recertification cycles:PHMSA-mandated requalification every three years strains training infrastructure and creates workforce scheduling conflicts during peak construction seasons.
- Legacy GIS data reconciliation:Many municipal utilities lack accurate mapping of pre-1970 distribution networks, forcing costly pre-construction verification through potholing and ground-penetrating radar.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pipeline Construction Market |
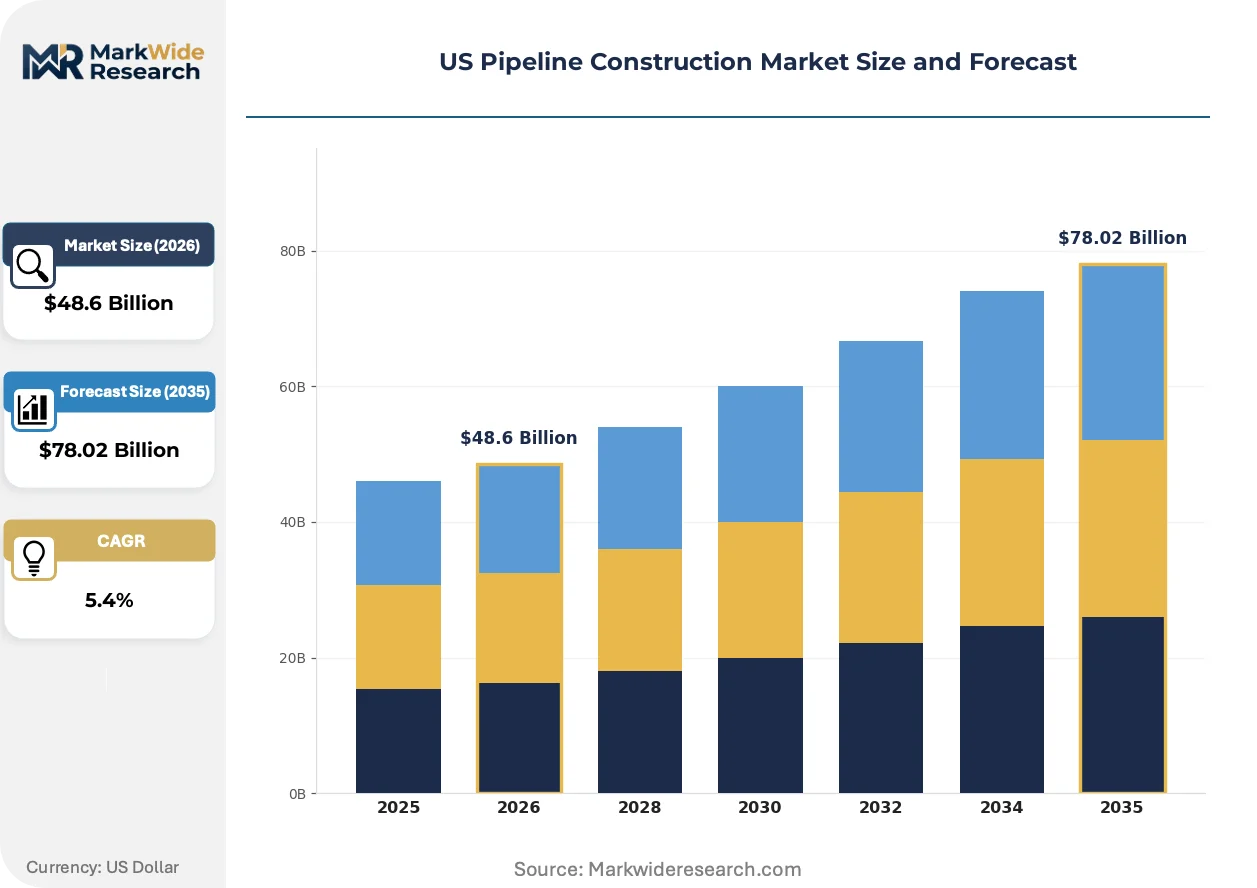
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Inspection, Rehabilitation Product Type: Gas Pipeline, Water Pipeline, Oil Pipeline, Multi-Utility Pipeline End User: Oil & Gas Companies, Municipalities, Industrial Plants, Energy Providers Technology: Trenching, Horizontal Directional Drilling, Microtunneling, Excavation |
| Companies Covered | Mastec, Inc., Michels Corporation, Kiewit Corporation, U.S. Pipeline, McDermott International, Bechtel Corporation, Fluor Corporation, Willbros Group, Northwest Pipe Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pipeline Construction Market Trends and Innovations
Digital twin technology and automated welding systems are converging to transform how contractors validate joint integrity before burial. These advances are compressing inspection timelines while elevating documentation standards for regulatory submission.
Automated ultrasonic testing (AUT) systems are replacing traditional radiographic inspection for girth weld verification on large-diameter transmission projects. Pipeline operators in the Marcellus and Utica shale regions are mandating AUT for all Class 3 and Class 4 location installations. This technology is hybridizing quality assurance workflows by combining real-time defect detection with machine-learning pattern recognition that flags anomalous fusion profiles before final acceptance.
PHMSA's updated Mega Rule requirements for gas transmission pipelines are mandating material traceability from mill certification through final installation. Operators must now maintain verifiable records linking each pipe joint to original heat numbers and chemical composition data. Midstream companies operating across the Appalachian Basin are responding by deploying blockchain-based documentation systems that create immutable audit trails for regulatory examination.
Integrated project delivery contracts are displacing traditional design-bid-build arrangements for complex river crossings and urban corridor work. Municipal gas utilities in Dallas-Fort Worth and Pittsburgh are bundling engineering, permitting, and construction risk within single-source agreements. This model concentrates accountability with contractors possessing in-house directional drilling expertise and established relationships with state environmental agencies.
US Pipeline Construction Market Segmentation
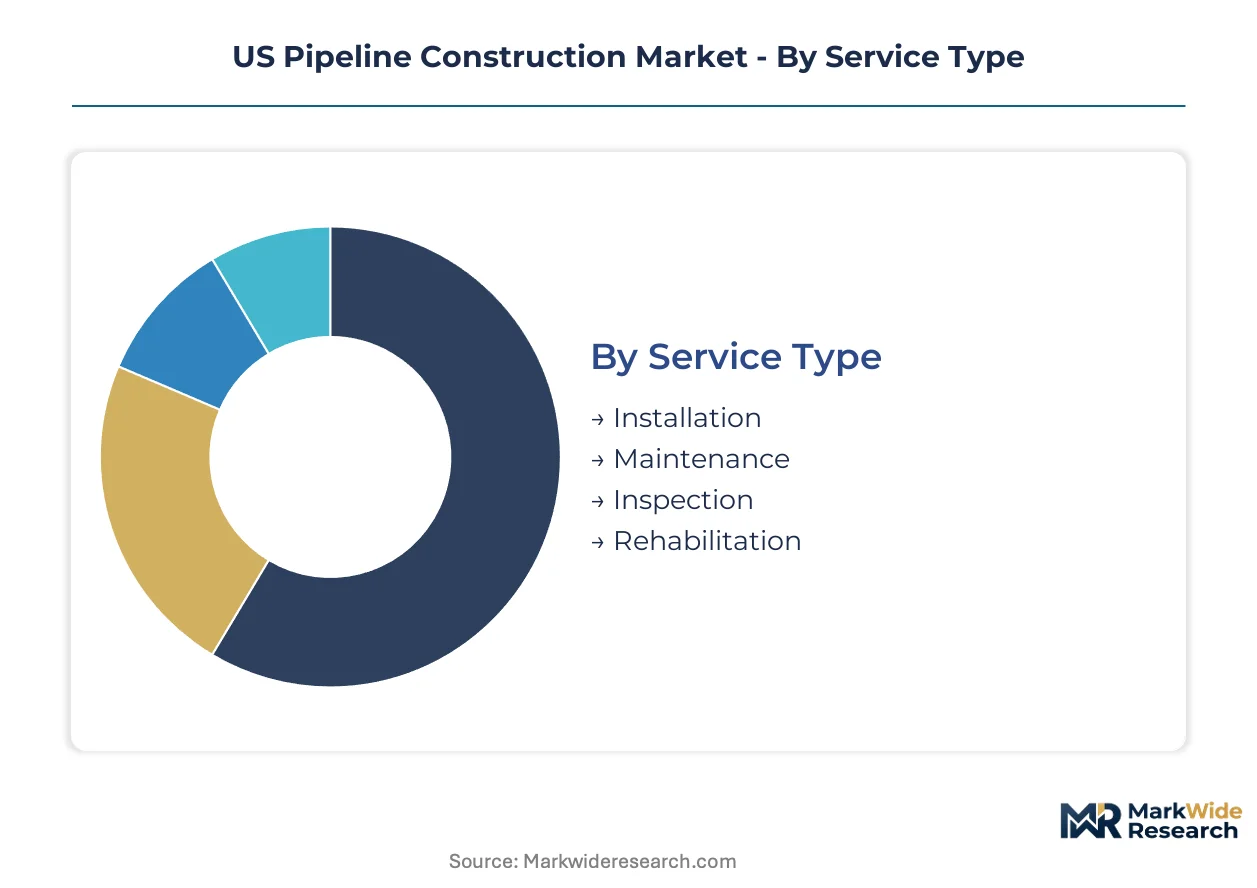
US pipeline construction segments diverge sharply in capital intensity and contract duration. Service type dictates crew specialization requirements, while product type determines material sourcing strategies and regulatory compliance protocols.
Service Type:
Installation contracts turn over fastest at 6-18 month cycles, while rehabilitation programs extend across multi-year utility master plans. Maintenance and inspection occupy intermediate positions with recurring annual scopes.
- Installation:Greenfield pipeline laying demands API 1104-certified welding crews and cathodic protection specialists. Texas and Pennsylvania shale zones concentrate demand as midstream operators expand gathering networks to connect well pads with processing infrastructure.
- Maintenance:Scheduled integrity digs and valve replacements follow PHMSA-mandated cycles. Appalachian operators accelerate maintenance spending ahead of federal deadline compression for legacy gathering line upgrades.
- Inspection:Inline smart pigging and direct assessment programs verify pipeline integrity without excavation disruption.
- Rehabilitation:Cast-iron main replacement and slip-lining projects address century-old municipal distribution infrastructure.
Installation anchors the volume base while rehabilitation gains share at the steepest rate.
Product Type:
Cost tiers separate commodity-driven gas transmission from specialized multi-utility corridor construction. Material specification complexity and permitting burden create distinct margin profiles across product categories.
- Gas Pipeline:Steel transmission lines and polyethylene distribution mains dominate capital allocation. Permian Basin takeaway expansion and Appalachian municipal replacement programs drive sustained demand for Class 3 and Class 4 location installations.
- Water Pipeline:Ductile iron and prestressed concrete cylinder lines serve municipal supply and wastewater conveyance. Western drought-response infrastructure and Great Lakes region lead service line replacement concentrate demand.
- Oil Pipeline:Crude gathering systems and refined product trunk lines require specialized corrosion-resistant coatings.
- Multi-Utility Pipeline:Shared corridor construction bundles gas, electric, and telecommunications infrastructure in dense urban corridors.
Gas pipeline construction commands the largest absolute spend while multi-utility corridor work expands most quickly.
End User:
Customer type determines procurement sophistication and contract structure preference. Volume concentration sits with integrated operators, while municipalities fragment demand across thousands of discrete projects.
- Oil & Gas Companies:Midstream operators and upstream producers deploy master service agreements with pre-qualified contractors. Bakken and Permian producers prioritize speed-to-market for gathering line connections.
- Municipalities:City gas utilities and water authorities bid projects through public procurement processes. Northeast and Midwest cities accelerate century-old cast-iron replacement programs.
- Industrial Plants:Refineries and petrochemical facilities require process piping and feedstock delivery infrastructure.
- Energy Providers:Electric-gas combination utilities coordinate joint trenching for distribution network modernization.
Oil and gas companies anchor the volume base while municipalities gain share at the steepest rate.
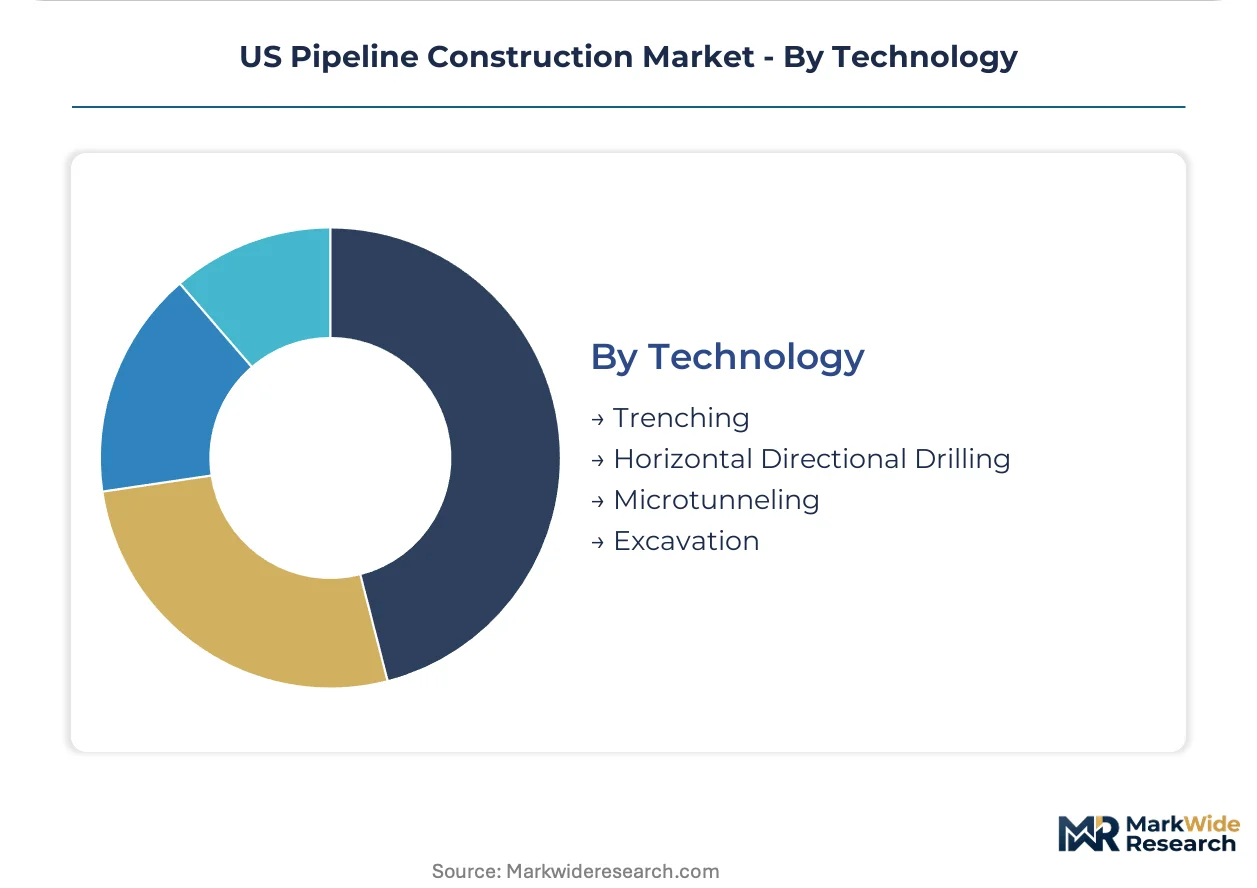
Technology:
Application context dictates technology selection, with environmental sensitivity and surface disruption tolerance as primary filters. Equipment specialization creates distinct contractor capability tiers.
- Trenching:Open-cut excavation remains the default for rural transmission corridors with minimal surface constraints. Standard trenching dominates Permian Basin gathering line construction where right-of-way access faces few restrictions.
- Horizontal Directional Drilling:Steerable underground boring installs pipelines beneath rivers, highways, and urban corridors without surface disruption. Marcellus Shale river crossings and Dallas-Fort Worth urban deployments command premium pricing.
- Microtunneling:Remote-controlled boring machines achieve precise alignment beneath rail corridors and deep river crossings.
- Excavation:Hydro excavation and vacuum excavation provide non-destructive exposure for utility verification and potholing.
Trenching anchors the volume base while horizontal directional drilling gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC certificate authority shapes interstate project viability across the dominant geography. State-level renewable natural gas mandates and municipal replacement programs create divergent demand profiles. Regional construction intensity clusters around shale production zones and aging urban distribution networks.
Texas
Permian Basin midstream operators expand gathering networks to connect well pads with processing infrastructure. Railroad Commission of Texas pipeline safety rules govern intrastate construction standards and operator qualification protocols. West Texas and the Eagle Ford Shale concentrate horizontal directional drilling deployments beneath sensitive riparian corridors.
Pennsylvania
Appalachian shale producers accelerate gathering line replacements ahead of PHMSA federal deadlines. Pennsylvania Public Utility Commission oversees municipal gas utility infrastructure modernization programs. Pittsburgh and Philadelphia metropolitan areas drive century-old cast-iron main replacement demand through trenchless installation methods.
North Dakota
Bakken formation operators prioritize speed-to-market for crude oil and associated gas gathering connections. North Dakota Industrial Commission regulates pipeline routing and environmental compliance across the Williston Basin. McKenzie and Williams counties anchor lateral construction between well pads and regional processing facilities.
California
Biogas injection mandates under California Public Utilities Commission directives create retrofit demand for corrosion-resistant infrastructure. South Coast Air Quality Management District rules accelerate pipeline compatibility upgrades for renewable natural gas. Central Valley agricultural waste digesters and Southern California utility corridors concentrate specialized metallurgy requirements.
Louisiana
Gulf Coast petrochemical complexes require extensive feedstock delivery and product export pipeline networks. Louisiana Department of Natural Resources governs coastal zone management and wetland crossing permits. The Mississippi River corridor and Lake Charles industrial zone drive multi-utility corridor construction bundling gas, electric, and chemical transport infrastructure.
US Pipeline Construction Market Competitive Landscape
Capability concentration sits with integrated engineering-procurement-construction firms; scale advantage sits with specialized directional drilling contractors. The market structures around three tiers: full-service interstate builders, niche trenchless technology providers, and regional distribution specialists. Dominant competitive moves include strategic partnerships for technology licensing and selective capacity expansion in Permian and Appalachian shale zones.
Within the integrated tier, Kiewit Corporation, Bechtel Corporation, and Fluor Corporation exemplify capitalized entities with regulatory endurance for multi-year FERC certificate cycles. These firms anchor large-diameter transmission project delivery through bundled risk assumption. Specialized capabilities concentrate with Michels Corporation and Mastec, Inc., representing horizontal directional drilling and last-mile distribution archetypes respectively.
| Leading Market Players |
|---|
| Mastec, Inc. |
| Michels Corporation |
| Kiewit Corporation |
| U.S. Pipeline |
| McDermott International |
| Bechtel Corporation |
| Fluor Corporation |
| Willbros Group |
| Northwest Pipe Company |
| Others |
Pricing and Supply Chain Analysis
Domestic steel mill concentration around the Great Lakes and Gulf Coast anchors pricing power for API 5L-grade plate and coil, pushing margin capture toward contractors with long-term offtake agreements and captive fabrication facilities. Pipeline operators in the Permian and Appalachian basins face divergent cost structures depending on their proximity to these supply nodes.
Pricing Analysis
Texas-to-Pennsylvania price spreads for large-diameter transmission pipe exceed fifteen percent due to freight differentials and regional demand intensity. Project-based contracting dominates, with fixed-bid structures for FERC-regulated interstate lines and cost-plus arrangements for municipal distribution work. Price differentiation rests on welding certification depth and directional drilling capability premiums. Cost compression in standard trenching tiers is intensifying because of equipment oversupply in the Permian Basin. Municipal utilities show highest price sensitivity, while midstream operators prioritize speed-to-market over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and trading partners for specialty alloy inputs dominates supply chain risk planning for corrosion-resistant coating systems. Domestic production draws from Ohio, Pennsylvania, and Indiana for steel plate, with polyethylene resin sourcing concentrated along the Gulf Coast petrochemical corridor. Raw material dependencies center on metallurgical coal, scrap steel, and high-density polyethylene. Single-source vulnerability exists for automated welding equipment controllers sourced from Germany and Japan. Distribution runs through mill-direct relationships for transmission-grade material and regional distributor networks for distribution-main fittings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across PHMSA, FERC, and state utility commissions is creating specialized contractor niches that favor focused capability investments over scale-based competition. Demand-side shifts toward renewable natural gas compatibility and hydrogen blending are fragmenting technical requirements.
For Market Incumbents: Build regulatory endurance as a moat by deepening in-house environmental permitting teams and PHMSA qualification infrastructure. Incumbents should secure master service agreements with Appalachian midstream operators ahead of federal gathering line deadlines. The threat of specialized labor scarcity compressing margins demands investment in automated welding training centers. Vertical integration into cathodic protection system installation provides channel control against regional specialists. For New Entrants and Emerging Players: Establish a beachhead in California biogas retrofit corridors where corrosion-resistant coating demand outstrips qualified contractor supply. New entrants should target municipal trenchless installation programs in Pittsburgh and Philadelphia, where century-old cast-iron replacement creates sustained project flow. The most penetrable segment is last-mile polyethylene distribution for municipal gas utilities lacking in-house construction capability. A go-to-market angle through equipment leasing partnerships reduces capital barriers for directional drilling entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed horizontal directional drilling specialists in the Marcellus Shale corridor. Long-term viability hinges on exposure to regulatory-mandated replacement cycles rather than commodity-sensitive new build activity. Acquisition targets should display concentrated PHMSA operator qualification depth and established relationships with state environmental agencies. The signal to watch is FERC certificate issuance velocity as an inflection indicator for interstate transmission investment appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Technology Deployment | PHMSA-mandated inspection protocols favor contractors with real-time defect detection capabilities. |
| Directional Drilling Capacity Expansion | Marcellus Shale river crossings and urban corridor restrictions command premium pricing tiers. |
| Renewable Natural Gas Infrastructure Certification | California and Oregon biogas mandates create first-mover advantage in corrosion-resistant coating. |
| Integrated Project Delivery Contracting | Dallas-Fort Worth and Pittsburgh utilities bundle engineering-permitting-construction risk with single-source accountability. |
| Operator Qualification Training Infrastructure | PHMSA three-year recertification cycles strain workforce availability and create captive training value. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and trade sources. Primary engagements included pipeline construction executives, PHMSA compliance officers, municipal utility procurement managers, and directional drilling equipment specialists. Secondary sources encompassed FERC certificate filings, PHMSA incident databases, Railroad Commission of Texas safety reports, and SEC 10-K disclosures from publicly traded contractors. Bottom-up project pipeline tracking was triangulated against top-down capital expenditure estimates from midstream operators.
Forecast inputs considered service type segmentation, product category material intensity, technology deployment rates, and end-user procurement sophistication across the projection horizon. The analytical framework modeled installation, maintenance, inspection, and rehabilitation cycles separately, with gas pipeline, water pipeline, oil pipeline, and multi-utility corridor work as distinct product streams. CAGRs were derived from project backlog analysis and utility master plan disclosures. Industry-specific inputs included PHMSA regulatory deadline schedules and FERC environmental review streamlining impacts.
Stress conditions across steel tariff volatility, specialized labor availability, and wetland permitting timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and shale production investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market