
 New Zealand Infrastructure Market | 2026-2036
New Zealand Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Infrastructure Market Insights
The Building for Climate Change programme is rebalancing material specifications and lifecycle accountability across public procurement. Fletcher Construction leverages its vertical integration into concrete and aggregate supply to sustain margin control on major transport contracts. Fulton Hogan Ltd anchors its position through geographic dominance in road maintenance networks across both islands. Downer Group competes on digital delivery platforms that integrate smart sensor data into asset management protocols.
New Zealand infrastructure encompasses the physical systems and engineered assets that enable transport, energy distribution, water management, and telecommunications across a seismically active, geographically dispersed archipelago. Structural designs must accommodate NZS 1170.5 seismic loadings and 100-year coastal inundation projections under updated climate guidance. Roads and bridges within the project type segment absorb the dominant share of public capital allocation due to state highway renewal obligations and local government rating capacity constraints. Concrete and steel within the material segment carry the deepest margin pools where prefabrication and low-carbon certification create pricing differentiation. Government end users channel the most predictable demand through the Infrastructure Commission's published pipeline, though utilities are expanding faster as water sector reform consolidates regional entities.
The Infrastructure Commission, MBIE, and Waka Kotahi NZ Transport Agency collectively shape market access through pipeline transparency rules, procurement preference for local content, and climate resilience design standards. These frameworks elevate BIM compliance and embodied carbon disclosure from optional to mandatory on projects above specified thresholds. Stakeholders must monitor how the National Adaptation Plan translates into enforceable design mandates and which contractors secure early positioning on resilience-rated frameworks.
Market Dynamics
The Infrastructure Commission's pipeline transparency rules and Waka Kotahi NZ Transport Agency climate resilience mandates are compressing procurement cycles while elevating technical pre-qualification thresholds for contractors.
Growth Catalysts
- Building for Climate Change programme:Mandatory embodied carbon disclosure on public projects above specified thresholds is accelerating low-carbon material substitution and lifecycle accountability integration.
- Auckland-Wellington corridor concentration:Transport resilience upgrades across these urban corridors are concentrating state highway renewal capital and creating bundled contract opportunities.
- Water sector reform consolidation:Regional entity mergers under Three Waters restructuring are aggregating procurement scale and standardizing asset management protocols.
Market Restraints
- Seismic steel supply concentration:NZS 1170.5-compliant structural steel fabrication capacity concentrates with limited domestic producers, creating import dependency for complex bridge components.
- Skilled engineering labor scarcity:Geotechnical and seismic design specialists face pipeline bottlenecks that extend project mobilization timelines.
- Local content preference friction:Procurement rules favoring domestic suppliers conflict with specialized equipment availability, particularly for tunnel boring and rail signaling systems.
Strategic Opportunities
- Upper North Island interconnection gap:Road-rail freight integration between Auckland, Hamilton, and Tauranga remains underdeveloped relative to container volume growth.
- Smart sensor convergence:Integration of IoT monitoring with predictive maintenance platforms is opening performance-based contracting models for state highway networks.
- Regional rating capacity expansion:Local government funding reforms may unlock council infrastructure bonds for water and transport assets previously constrained by ratepayer limits.
Industry Challenges
- BIM compliance talent shortage:Mandatory Building Information Modeling on Infrastructure Commission pipeline projects exceeds available certified technician supply.
- 100-year coastal inundation design uncertainty:Evolving climate guidance creates specification volatility for marine-adjacent structures requiring adaptive engineering approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Infrastructure Market |
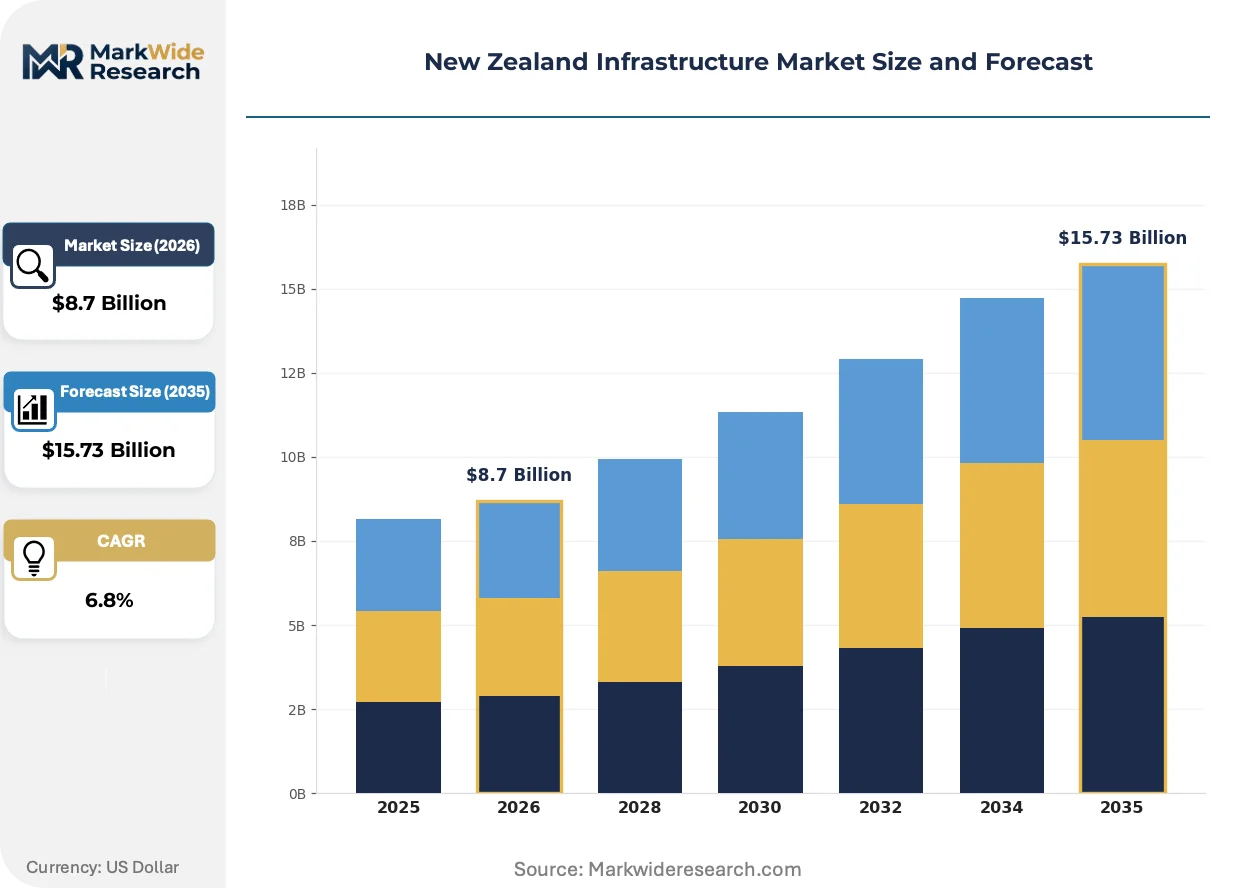
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material: Concrete, Steel, Asphalt, Timber End User: Government, Utilities, Contractors, Developers Technology: Smart Sensors, BIM, Drones, Robotics |
| Companies Covered | Fletcher Construction, Fulton Hogan Ltd, Downer Group, CPB Contractors Pty Ltd, Hawkins Limited, Citycare Ltd, Naylor Love Enterprises Ltd, Obayashi Corp, Infratil Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Infrastructure Market Trends and Innovations
Digital delivery platforms and prefabrication methods are compressing traditional construction timelines while MBIE procurement rules force earlier-stage contractor involvement in design development.
Cross-laminated timber and engineered wood products are penetrating bridge superstructure and mid-rise commercial applications as alternatives to carbon-intensive concrete and steel. Regional councils in Canterbury and Otago are specifying mass timber for administrative buildings and pedestrian infrastructure. This material transition is modularizing component fabrication off-site, reducing weather-dependent construction risk and enabling just-in-time delivery to geographically dispersed sites.
The Infrastructure Commission's pipeline transparency rules now mandate early contractor involvement and alliance contracting on projects exceeding specified capital thresholds. This procurement evolution compresses traditional design-bid-build sequences and transfers more design risk to construction consortia. Transport and water sector projects face the steepest adaptation requirements as Waka Kotahi NZ Transport Agency embeds these rules into state highway renewal frameworks.
Asset owners are unbundling long-term maintenance obligations from initial construction contracts, creating discrete performance-based service markets. Downer Group and Fulton Hogan Ltd are repositioning toward these recurring revenue streams. This procurement fragmentation is most visible in Auckland and Wellington road networks where smart sensor data enables outcome-based pavement management contracts.
New Zealand Infrastructure Market Segmentation
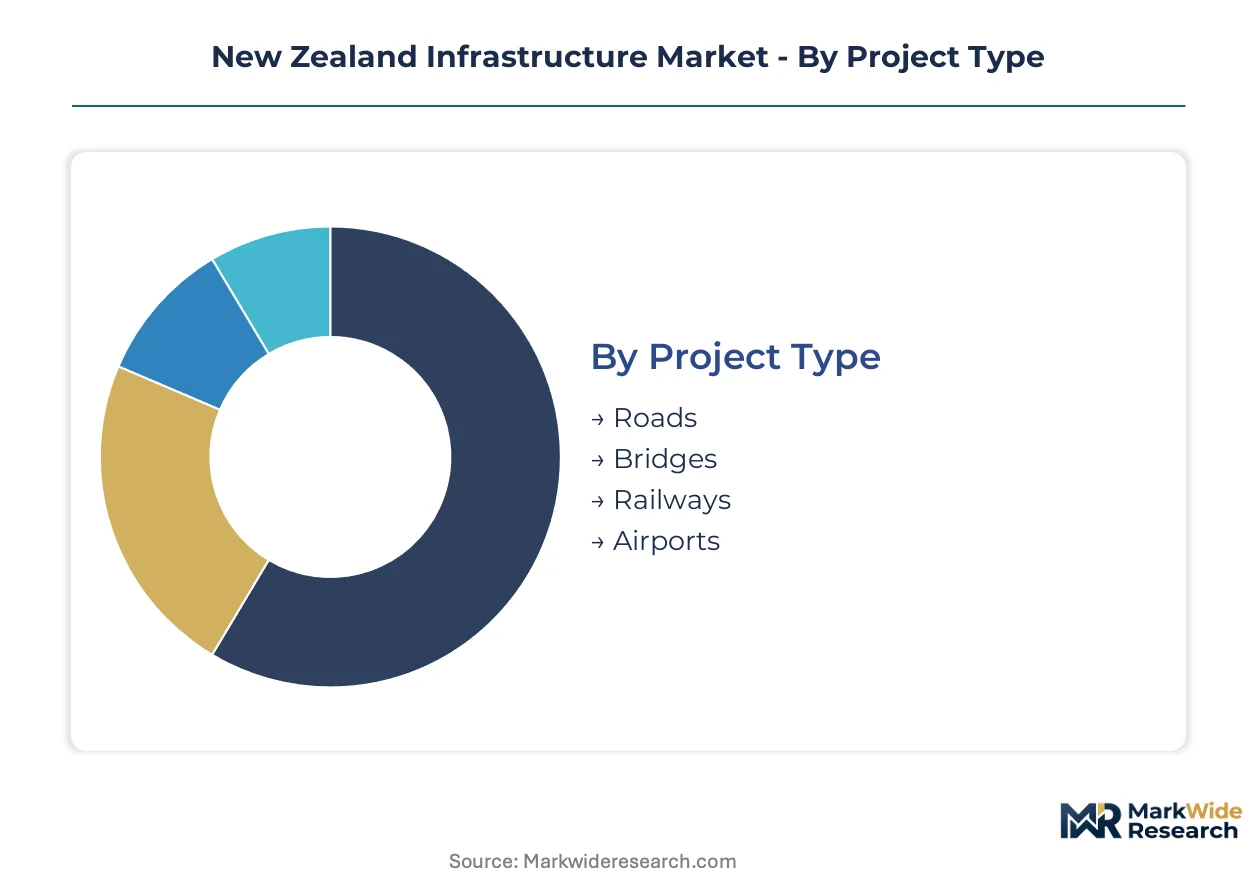
Segmentation reveals how procurement concentration, material specifications, and digital compliance requirements reshape contractor positioning across New Zealand's infrastructure pipeline. Each dimension carries distinct margin structures and regulatory thresholds that determine market access.
Project Type:
Capital allocation intensity drives buyer priorities, with resilience mandates and interconnection gaps determining contract scale.
- Roads:State highway renewal obligations absorb the dominant share of Waka Kotahi NZ Transport Agency capital, with Auckland-Wellington corridor upgrades bundling pavement, drainage, and smart sensor integration into single procurement packages. Volume concentrates in maintenance networks where performance-based contracts extend to 10-year terms.
- Bridges:NZS 1170.5 seismic loadings and 100-year coastal inundation projections demand specialized geotechnical and structural engineering, creating procurement bottlenecks where domestic fabrication capacity limits project mobilization timelines.
- Railways:Upper North Island freight integration between Auckland, Hamilton, and Tauranga lags container volume growth, opening bundled track-electrification-yard contracts.
- Airports:Regional terminal resilience upgrades face passenger traffic recovery uncertainty that compresses capital planning horizons.
Volume sits with Roads; growth tilts toward Railways.
Material:
Lifecycle accountability and embodied carbon disclosure are rebalancing specifications away from traditional carbon-intensive inputs.
- Concrete:Prefabrication and low-carbon certification create pricing differentiation, with Fletcher Construction's captive aggregate and cement supply sustaining margin control on major transport contracts. The Building for Climate Change programme mandates disclosure thresholds that favor suppliers with verified Environmental Product Declarations.
- Steel:NZS 1170.5-compliant structural fabrication concentrates with limited domestic producers, forcing import dependency for complex bridge components and extending lead times for seismic-grade sections.
- Asphalt:Road maintenance networks across both islands standardize warm-mix formulations that reduce production emissions and extend paving seasons.
- Timber:Cross-laminated timber and engineered wood products penetrate bridge superstructures and administrative buildings as Canterbury and Otago councils specify mass timber for carbon reduction.
Concrete commands procurement volume; timber climbs the fastest on climate mandates.
End User:
Funding predictability and procurement scale determine contractor relationship strategies.
- Government:The Infrastructure Commission's published pipeline channels the most predictable demand through transparency rules that mandate early contractor involvement on projects above specified capital thresholds.
- Utilities:Three Waters restructuring consolidates regional entities, aggregating procurement scale for water treatment and distribution assets.
- Contractors:Alliance contracting transfers design risk to construction consortia, compressing traditional design-bid-build sequences.
- Developers:Private commercial and industrial projects face tighter financing conditions that delay mobilization relative to public sector counterparts.
Government anchors current volume; utilities expand most quickly on reform consolidation.
Technology:
Digital compliance thresholds and predictive capability determine competitive differentiation.
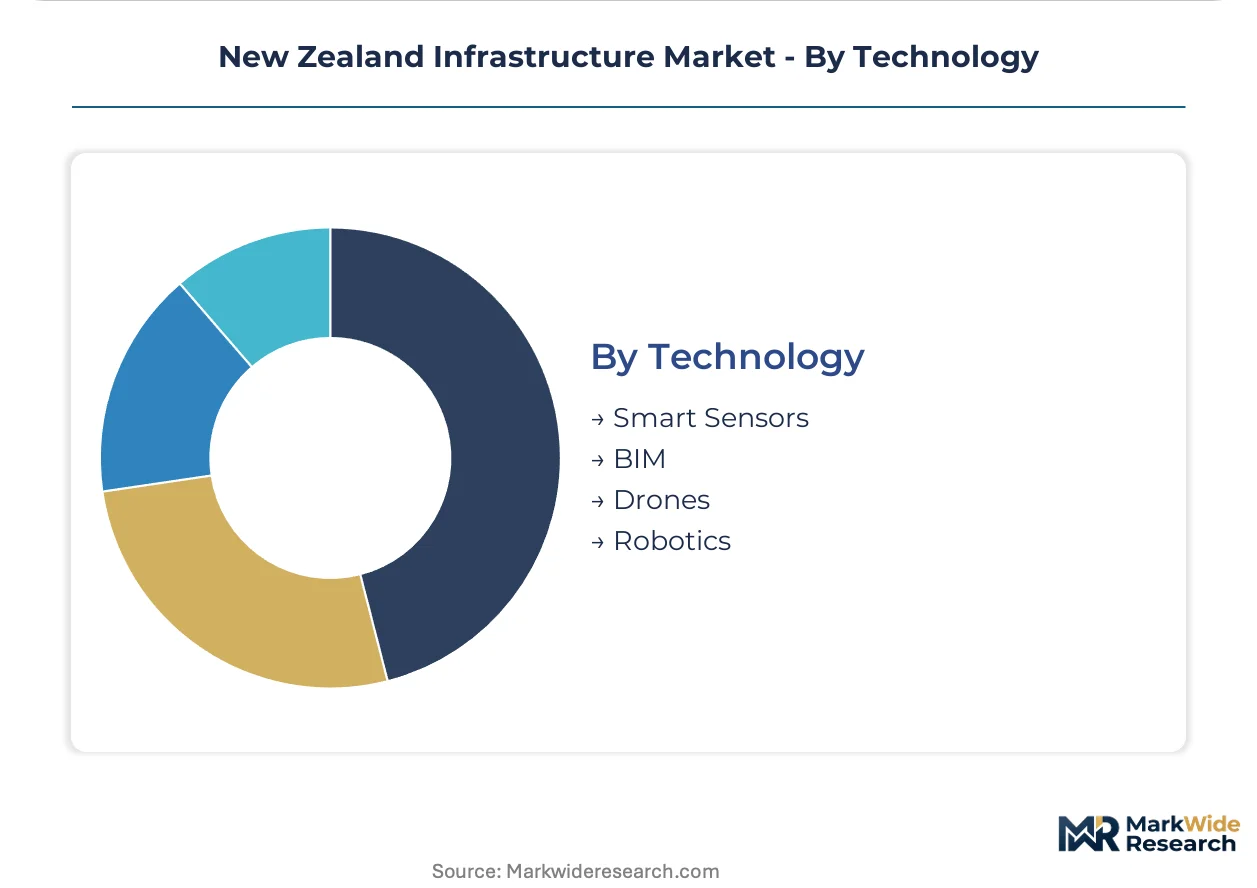
- Smart Sensors:IoT monitoring integration with predictive maintenance platforms enables outcome-based pavement management contracts across Auckland and Wellington road networks.
- BIM:Mandatory Building Information Modeling on Infrastructure Commission pipeline projects exceeds available certified technician supply, creating talent bottlenecks.
- Drones:Survey and inspection applications reduce weather-dependent site access risk across geographically dispersed terrain.
- Robotics:Tunnel boring and rail signaling systems face local content preference friction where procurement rules favoring domestic suppliers conflict with specialized equipment availability.
BIM dominates compliance requirements; smart sensors gain share fastest on performance contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland dominates procurement volume through state highway renewal corridors and port-rail interconnection projects. Wellington anchors climate resilience investment with transport network upgrades and coastal inundation defenses. Canterbury and Otago councils drive material innovation through mass timber specifications for administrative buildings.
Auckland
Auckland concentrates state highway renewal capital and bundled transport contracts across the upper North Island. Waka Kotahi NZ Transport Agency mandates climate resilience design standards for corridor upgrades. The Auckland-Hamilton-Tauranga freight triangle generates road-rail interconnection demand that outpaces current infrastructure capacity.
Wellington
Wellington channels Building for Climate Change programme investment into coastal transport resilience and seismic strengthening. The Infrastructure Commission's pipeline transparency rules accelerate procurement for marine-adjacent structures facing 100-year inundation projections. Greater Wellington Regional Council aggregates water sector reform procurement for treatment and distribution assets.
Canterbury
Canterbury councils specify cross-laminated timber for administrative buildings and pedestrian bridge superstructures. The region's geotechnical engineering capacity supports NZS 1170.5-compliant foundation design for seismically active terrain. Christchurch anchors prefabrication innovation through off-site component fabrication for dispersed rural delivery.
Otago
Otago regional councils adopt mass timber specifications for carbon reduction in public buildings. The area's engineering networks specialize in adaptive design for evolving climate guidance on alpine and coastal structures. Dunedin concentrates smart sensor pilot programmes for outcome-based road maintenance contracting.
Waikato
Waikato sits at the center of upper North Island freight integration gaps between Auckland and Tauranga. The region's rating capacity constraints limit local government infrastructure bond issuance for transport assets. Hamilton anchors road-rail yard development contracts that bundle track, electrification, and logistics infrastructure.
New Zealand Infrastructure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across digital compliance and material certification dimensions. The market structures around three tiers: vertically integrated conglomerates with captive supply chains, geographic specialists dominating maintenance networks, and technology-forward contractors competing on sensor-enabled asset management. Two competitive moves dominate: alliance contracting transfers design risk to construction consortia, while unbundling of long-term maintenance creates recurring revenue service markets.
Among New Zealand-based contractors, Fletcher Construction, Fulton Hogan Ltd, and Downer Group represent distinct strategic archetypes. Fletcher Construction exemplifies vertical integration through upstream control over concrete and aggregate supply. Fulton Hogan Ltd anchors geographic dominance across road maintenance networks on both islands. Downer Group occupies the technology-forward tier through digital delivery platforms integrating smart sensor data into predictive maintenance protocols.
| Leading Market Players |
|---|
| Fletcher Construction |
| Fulton Hogan Ltd |
| Downer Group |
| CPB Contractors Pty Ltd |
| Hawkins Limited |
| Citycare Ltd |
| Naylor Love Enterprises Ltd |
| Obayashi Corp |
| Infratil Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive supply of concrete and aggregate through Fletcher Construction's upstream operations anchors both procurement reliability and margin control across major transport contracts. This backward integration insulates pricing power from volatile cement imports while the Building for Climate Change programme forces lifecycle accountability premiums into public procurement.
Pricing Analysis
Outcome-based pavement management contracts across Auckland and Wellington road networks anchor value-based pricing to measurable uptime and maintenance intervals. Three-tier pricing structure across alliance contracting, traditional design-bid-build, and maintenance-only service tiers separates risk-bearing consortia from commodity pavement suppliers. Cost compression in standard concrete supply is intensifying because Environmental Product Declaration certification now gates public project eligibility. Local government end users exhibit highest price sensitivity due to rating capacity constraints, while Waka Kotahi NZ Transport Agency bundled contracts show lowest sensitivity through 10-year performance terms.
Supply Chain Analysis
Refurbishment flows for seismic steel bridge components create reverse-logistics complexity where NZS 1170.5-compliant fabrication capacity concentrates with limited domestic producers. Raw material sourcing draws from Australian iron ore, Chinese specialty steel sections, and domestic aggregate quarries. Single-source vulnerability concentrates in complex bridge component fabrication where import lead times extend project mobilization. Distribution runs through Waka Kotahi NZ Transport Agency's centralized procurement frameworks for state highway assets, with regional council networks handling local road maintenance sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around contractors with certified BIM capabilities and captive material supply, as the Infrastructure Commission's technical pre-qualification thresholds force smaller players into subcontractor roles.
For Market Incumbents: Cement dominance across road maintenance networks by securing 10-year performance-based contracts before alliance contracting mandates expand. Acquire certified BIM technician capacity to preempt talent bottlenecks on Infrastructure Commission pipeline projects. Threat substitution from cross-laminated timber in Canterbury and Otago administrative buildings demands early positioning on mass timber certification pathways. For New Entrants and Emerging Players: The mid-tier pricing gap between Fletcher Construction's vertically integrated premium positioning and regional maintenance contractors' economy-tier bidding opens white-space for digital-native entrants. Target smart sensor integration services for Downer Group's predictive maintenance platforms as the most penetrable technology wedge. Enter through performance-based contracting expertise rather than capital-heavy construction assets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Australian engineering conglomerates seeking New Zealand market footholds. Long-term viability favors contractors with alliance contracting experience and embodied carbon disclosure systems already operational. Monitor Infrastructure Commission pipeline transparency rule expansions as the signal for accelerated procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Alliance Contracting Capability Buildout | Transfers design risk to construction consortia under Infrastructure Commission mandates. |
| Environmental Product Declaration Certification | Gates public project eligibility under Building for Climate Change programme thresholds. |
| BIM Technician Workforce Expansion | Addresses certified supply shortage exceeding Infrastructure Commission pipeline demand. |
| Smart Sensor Platform Integration | Enables outcome-based pavement management contracts across Auckland and Wellington networks. |
| Cross-Laminated Timber Specification Development | Captures Canterbury and Otago council carbon reduction procurement preferences. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with infrastructure project directors, Waka Kotahi procurement officers, regional council asset managers, and geotechnical engineering consultants validated demand assumptions. Secondary sources encompassed Infrastructure Commission pipeline publications, MBIE procurement guidelines, NZS 1170.5 technical standards, and aggregate import statistics. Bottom-up project pipeline aggregation triangulated against top-down construction sector output estimates.
Segment-level modeling applied project type, material specification, end-user funding source, and technology compliance dimensions across the projection horizon. CAGRs derived from weighted infrastructure investment schedules and regional rating capacity trajectories. Forecast inputs incorporated Three Waters restructuring timelines, state highway renewal obligation schedules, and climate resilience design standard adoption curves.
Inputs from Infrastructure Commission pipeline disclosures and Waka Kotahi procurement frameworks were available through the study window; gaps in private developer financing condition data introduce uncertainty bands around commercial and industrial project mobilization assumptions. Forecasts reflect documented assumptions regarding alliance contracting mandate expansion and seismic steel import dependency persistence. Practitioners should monitor Building for Climate Change programme threshold adjustments and regional council bond issuance reforms for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Bahrain Construction Market