
 Philippines Data Center Construction Market | 2026-2036
Philippines Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Construction Market Insights
Metro Manila is narrowing its available power capacity as hyperscale commitments absorb grid allocations faster than utility expansion. AECOM Philippines Inc. leverages its engineering design portfolio to secure pre-construction contracts with international operators. Jacobs Project Philippines Inc. sustains competitive positioning through integrated project delivery models that compress build timelines. Turner & Townsend anchors cost consultancy services for foreign investors navigating local procurement complexity.
Data center construction encompasses the architectural, mechanical, electrical, and structural build-out of facilities housing server, storage, and networking equipment, typically requiring power densities exceeding 150 watts per square foot and redundant cooling architectures to maintain 99.999% uptime. The primary commercial purpose centers on creating controlled environments that protect compute infrastructure from thermal stress, particulate contamination, and power interruption. Hyperscale facilities command the largest capital allocation pools due to their single-tenant, high-redundancy specifications, while colocation builds compete on modular expandability and interconnection density. Edge deployments represent the fastest-growing type segment as latency-sensitive applications require distributed presence beyond Metro Manila's core.
The Department of Information and Communications Technology and the Department of Energy jointly shape market access through data center accreditation requirements and power service reliability standards that operators must satisfy before commercial launch. The National Building Code of the Philippines and local fire safety ordinances enforce structural and suppression specifications that elevate material and engineering costs above standard commercial construction. Stakeholders must monitor grid interconnection queue positions and renewable energy wheeling agreements as these determine site feasibility faster than land availability or fiber connectivity.
Market Dynamics
Hyperscale cloud commitments are absorbing Metro Manila's available power capacity faster than utility expansion can replenish it, forcing developers to queue for grid interconnection positions that determine project viability ahead of land or fiber considerations.
Growth Catalysts
- Streamlined Permitting:The Department of Information and Communications Technology has consolidated accreditation requirements for digital infrastructure, reducing bureaucratic friction for foreign operators seeking commercial launch authorization.
- Provincial Cost Arbitrage:Cavite and Laguna provinces offer land and power cost structures that favor hyperscale campus development versus Metro Manila's constrained utility environment.
- Latency-Sensitive Applications:Edge computing deployments for real-time gaming, autonomous systems, and industrial IoT are pulling compute infrastructure beyond the capital region into distributed secondary markets.
Market Restraints
- Grid Interconnection Bottlenecks:National Grid Corporation of the Philippines queues for transmission access extend 24-36 months in high-demand zones, freezing site feasibility timelines.
- Fire Safety Material Costs:Local fire safety ordinances mandate suppression specifications and structural ratings that elevate construction costs above standard commercial build-outs.
- Renewable Energy Wheeling Complexity:Retail electricity supplier agreements for green power require navigating regulatory layers that delay offtake certainty for sustainability-committed operators.
Strategic Opportunities
- Secondary City Edge Expansion:Cebu and Davao metropolitan areas remain underpenetrated for latency-optimized infrastructure serving Visayas and Mindanao digital economies.
- Liquid Cooling Technology Convergence:Direct-to-chip and immersion cooling systems are converging with tropical climate engineering to enable higher rack densities without mechanical refrigeration penalties.
- Department of Energy Reliability Standards:New power service reliability mandates create competitive differentiation for operators achieving Tier III or Tier IV design certifications ahead of compliance deadlines.
Industry Challenges
- Specialized MEP Workforce Scarcity:Mechanical, electrical, and plumbing engineers with data center-specific mission-critical experience command premium compensation and extended recruitment cycles.
- Legacy Building Code Interpretation:National Building Code of the Philippines provisions written for conventional commercial structures require case-by-case variance applications for high-redundancy power architectures.
- Capex Intensity of Redundant Substations:Dual-fed utility infrastructure with automatic transfer switching requires capital allocation pools that strain project finance structures for sub-10 megawatt developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Construction Market |
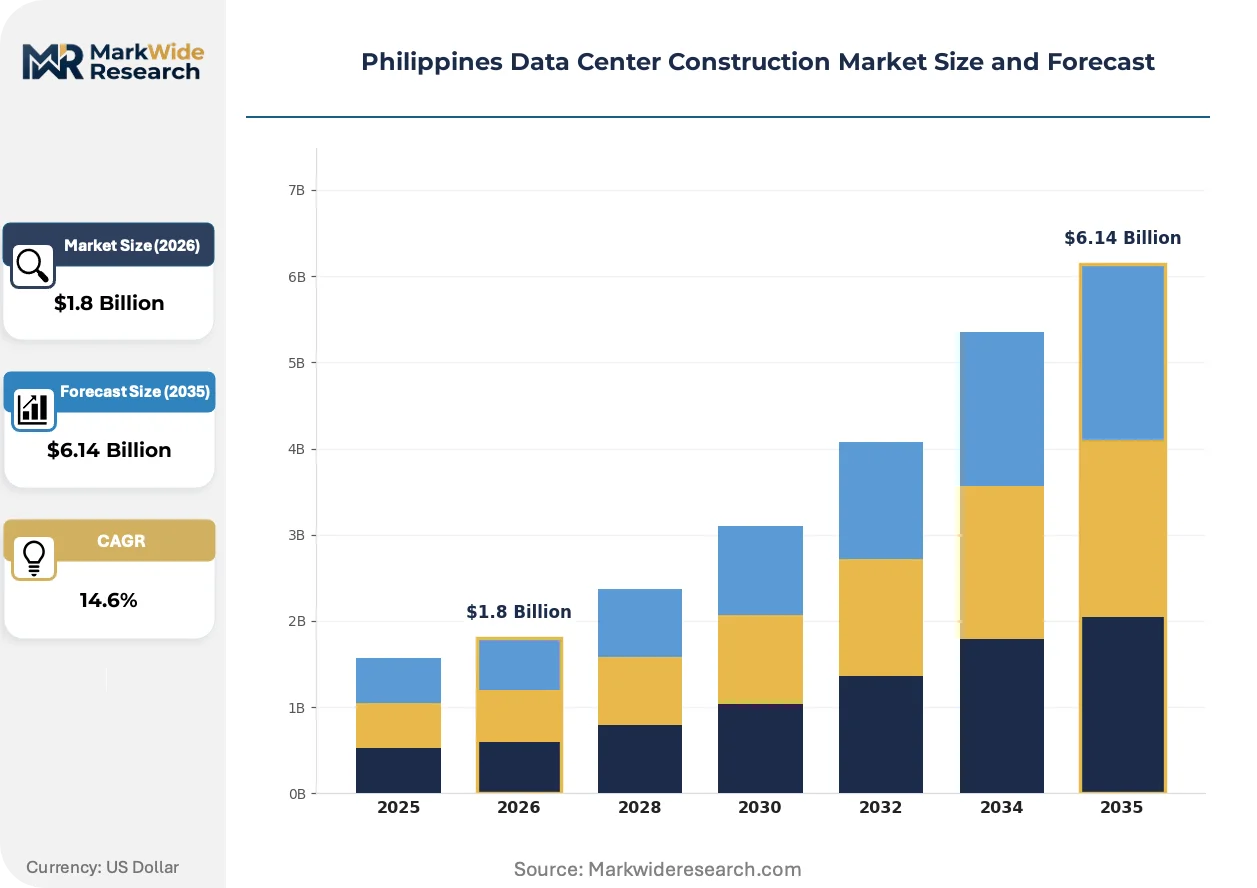
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Maintenance, Operations Type: Hyperscale, Colocation, Enterprise, Edge Building Material: Steel, Concrete, Prefabricated Components, Insulation Infrastructure: Cooling Systems, Power Supply, Network Connectivity, Fire Safety |
| Companies Covered | AECOM Philippines Inc., Jacobs Project Philippines Inc., Turner & Townsend, Arup, Aurecon Group Pty. Ltd., Endec Group, Rider Levett Bucknall Philippines Inc., First Balfour Inc., MDBI Construction Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Construction Market Trends and Innovations
Digital infrastructure build-out in the Philippines is accelerating toward higher power densities and sustainability certifications as hyperscale operators impose specifications that reshape local contractor capabilities and material supply chains.
Modular prefabrication is digitizing construction workflows for electrical and mechanical plant. International operators are specifying factory-built power modules and cooling skids to compress on-site integration timelines. This approach is digitizing project delivery schedules that previously relied on stick-built sequential trades, enabling parallel workstreams that reduce commissioning windows by 30-40 percent.
The Department of Information and Communications Technology's data center accreditation framework now mandates cybersecurity and physical security standards that exceed prior voluntary industry guidelines. Operators must demonstrate compliance with multi-layer access controls and environmental monitoring before commercial authorization. Foreign cloud providers are most affected, deploying dedicated compliance teams to navigate documentation requirements that extend pre-operational phases.
Buyers are consolidating procurement authority under hyperscale direct contracts rather than distributed colocation leases. Enterprise IT departments are bypassing traditional carrier-neutral facilities to negotiate directly with cloud regions or dedicated builds. This concentration is most visible in Metro Manila's southern corridor, where single-tenant commitments now dominate new supply absorption versus multi-tenant speculative development.
Philippines Data Center Construction Market Segmentation
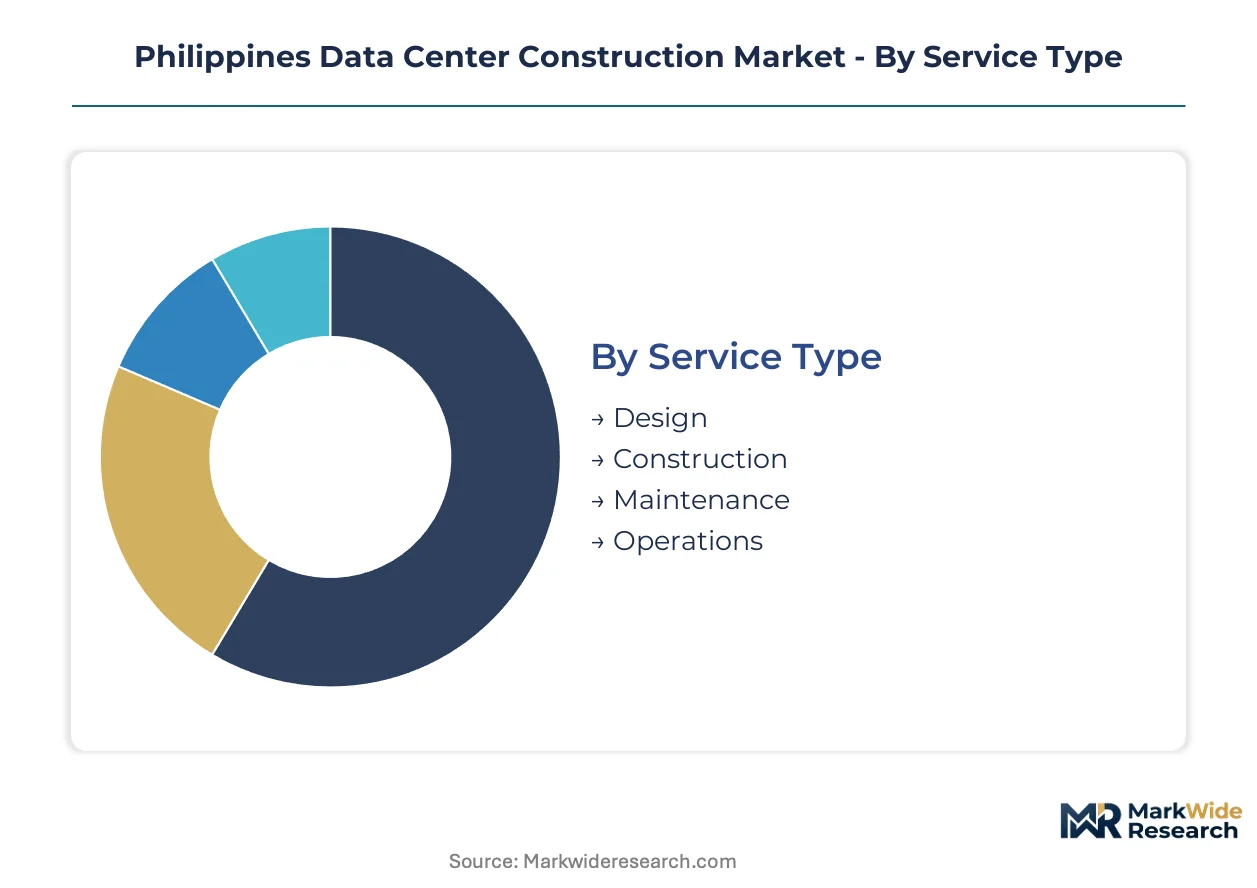
Service intensity varies dramatically across construction phases in the Philippines data center market. Design and construction phases command premium margins due to specialized mission-critical engineering requirements. Post-commissioning maintenance and operations contracts generate recurring revenue streams that stabilize contractor cash flows across multi-year facility lifecycles.
Service Type:
After-sales service intensity peaks during operations and maintenance phases where uptime guarantees create contractual penalties and incentive structures.
- Design:Architectural and engineering specifications define power density targets, redundancy tiers, and cooling architectures that constrain all downstream construction decisions. Philippine-based engineering firms like AECOM Philippines Inc. and Jacobs Project Philippines Inc. compete for pre-construction contracts by demonstrating tropical climate adaptation expertise and familiarity with DICT accreditation requirements.
- Construction:Physical build-out encompasses structural, mechanical, electrical, and plumbing systems requiring coordination between international standards and local National Building Code compliance. Demand concentrates in Cavite and Laguna provinces where land availability and lower power costs attract hyperscale campus developments versus Metro Manila's grid-constrained environment.
- Maintenance:Preventive and corrective servicing of critical infrastructure including UPS systems, cooling plant, and fire suppression networks. Meralco and NGCP interconnection reliability standards drive service contract specifications.
- Operations:Continuous facility management including environmental monitoring, security operations, and energy optimization. DICT cybersecurity mandates now require dedicated compliance personnel within operational teams.
By volume, Construction leads. By growth pace, Operations is ahead.
Type:
Capital allocation patterns diverge sharply based on tenant commitment certainty and redundancy specifications.
- Hyperscale:Single-tenant facilities exceeding 10 megawatts with N+1 or 2N redundancy architectures commissioned by cloud service providers. Microsoft, Google, and Amazon Web Services anchor demand in Metro Manila's southern corridor despite power capacity constraints forcing queue positions with National Grid Corporation of the Philippines.
- Colocation:Multi-tenant facilities offering modular space and interconnection services to enterprise customers. Demand is shifting toward wholesale commitments from cloud providers rather than retail enterprise leases, compressing speculative development margins.
- Enterprise:Dedicated facilities built for single corporate owners typically in banking, telecommunications, or government verticals. Bangko Sentral ng Pilipinas and major Philippine banks drive compliance-focused specifications.
- Edge:Distributed small-footprint deployments under 1 megawatt positioned for latency-sensitive applications. Cebu and Davao metropolitan areas represent underpenetrated expansion corridors for Visayas and Mindanao digital economies.
Hyperscale claims the largest capital pools. Edge deployments are expanding most quickly.
Building Material:
Material selection trade-offs center on seismic resilience, thermal performance, and speed-to-market compression.
- Steel:Structural framing systems enabling rapid erection and future expansion flexibility. Philippine seismic zone requirements elevate engineering specifications above standard commercial construction.
- Concrete:Reinforced shell construction providing thermal mass and blast resistance for critical infrastructure protection. Higher embodied carbon profiles face scrutiny from sustainability-committed operators.
- Prefabricated Components:Factory-built power modules, cooling skids, and containment systems reducing on-site integration timelines by 30-40 percent. International operators specify these for parallel workstream execution.
- Insulation:Thermal envelope materials managing tropical heat gain and humidity intrusion. Local fire safety ordinances mandate specific ratings that elevate material costs.
Concrete dominates structural mass. Prefabricated Components are gaining share fastest.
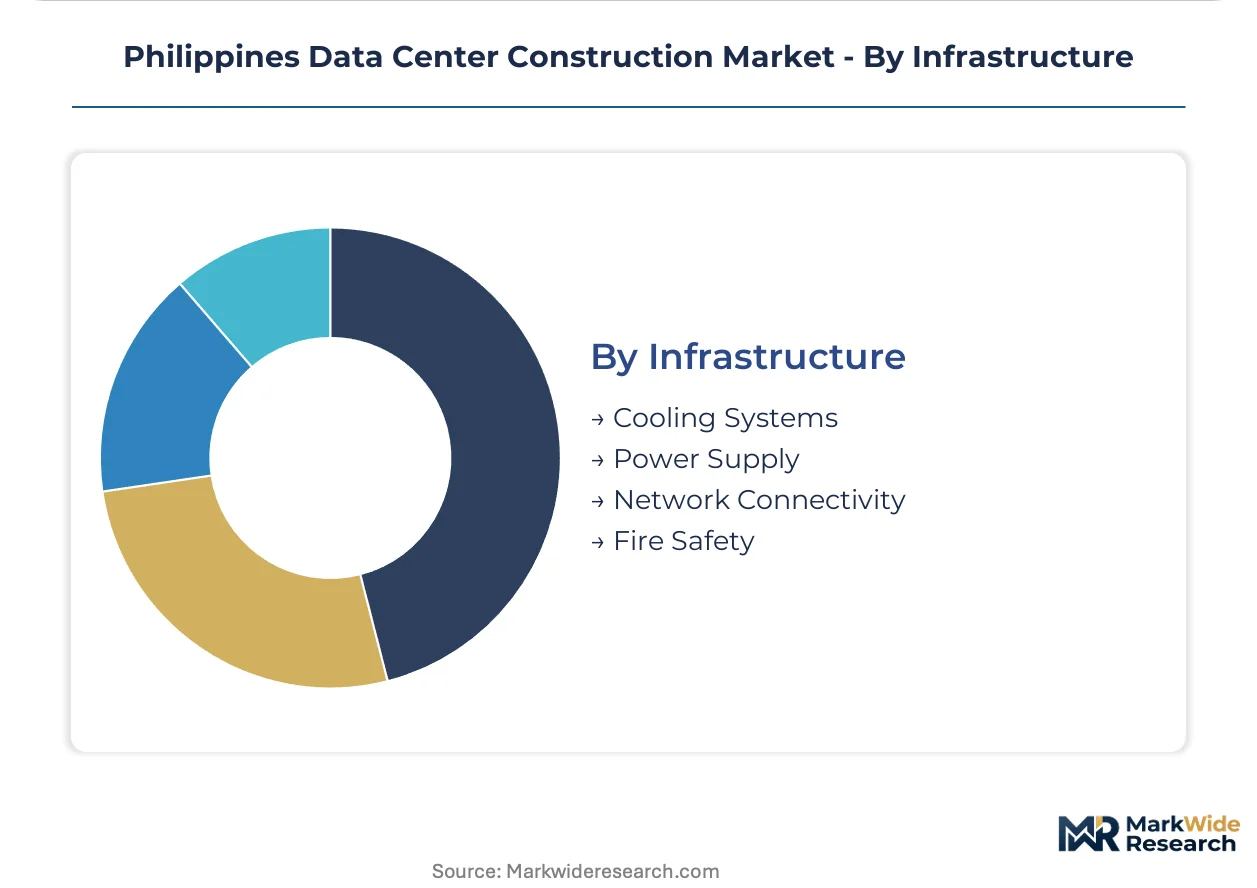
Infrastructure:
System interdependencies create bottleneck risks where any subsystem failure cascades to facility-wide uptime violations.
- Cooling Systems:Mechanical and liquid-based thermal management maintaining N+1 redundancy for 99.999% uptime targets. Direct-to-chip and immersion cooling convergence with tropical engineering enables higher rack densities without refrigeration penalties.
- Power Supply:Dual-fed utility infrastructure with automatic transfer switching, UPS banks, and diesel generator backup. NGCP interconnection queues extending 24-36 months freeze site feasibility timelines ahead of construction mobilization.
- Network Connectivity:Fiber diversity and carrier-neutral interconnection enabling multi-homed internet and private cloud access. PLDT and Globe Telecom infrastructure density influences site selection.
- Fire Safety:Suppression systems and structural ratings mandated by local ordinances exceeding standard commercial build-out costs. Bureau of Fire Protection inspections create pre-operational approval gates.
Power Supply absorbs the largest capital share. Cooling Systems show the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Information and Communications Technology anchors development patterns across Philippine sub-regions through accreditation requirements and permitting streamlines that determine where hyperscale operators commit capital.
Metro Manila
Power capacity constraints now dominate site selection as National Grid Corporation of the Philippines queues extend 24-36 months for transmission access. The DICT accreditation framework mandates cybersecurity and physical security standards that extend pre-operational phases. Makati and Taguig central business districts concentrate legacy carrier-neutral facilities while southern corridor townships absorb new hyperscale commitments.
Cavite Province
Land availability and lower industrial power tariffs attract hyperscale campus developments escaping Metro Manila's grid constraints. The Department of Energy's reliability standards for power service create compliance benchmarks that developers must satisfy before commercial launch. General Trias and Silang municipalities host emerging data center clusters where international operators queue for substation interconnection.
Laguna Province
Provincial cost structures favor wholesale builds over Metro Manila's constrained utility environment. Local fire safety ordinances enforce suppression specifications that elevate construction costs above standard commercial build-outs. Calamba and Santa Rosa industrial zones concentrate prefabricated module integration facilities serving tropical climate engineering requirements.
Cebu Metropolitan Area
Latency-sensitive applications for Visayas digital economies drive edge deployment demand in an underpenetrated corridor. The National Building Code of the Philippines requires case-by-case variance applications for high-redundancy power architectures that delay permitting. Mandaue and Lapu-Lapu cities host emerging fiber diversity nodes enabling multi-homed connectivity for distributed infrastructure.
Davao Metropolitan Area
Mindanao's digital economy expansion creates pull factors for compute infrastructure beyond the capital region. Bureau of Fire Protection inspections create pre-operational approval gates that extend commissioning timelines. Davao City and adjacent industrial zones represent greenfield development opportunities where renewable energy wheeling agreements determine site feasibility.
Philippines Data Center Construction Market Competitive Landscape
Capability concentration sits with engineering design specialists; scale advantage sits with integrated project delivery platforms. The Philippine market structures around three tiers: international engineering consultancies with tropical climate expertise, domestic contractors with National Building Code navigation experience, and cost consultancies specializing in local procurement complexity. Competitive moves center on pre-construction contract capture and modular prefabrication partnerships that compress build timelines.
Among international engineering consultancies, AECOM Philippines Inc., Jacobs Project Philippines Inc., and Turner & Townsend occupy positions that exemplify distinct competitive archetypes. AECOM Philippines Inc. represents the engineering design portfolio specialist securing early-stage contracts through tropical adaptation expertise. Jacobs Project Philippines Inc. exemplifies integrated project delivery models that compress sequential trades into parallel workstreams. Turner & Townsend anchors cost consultancy services for foreign investors navigating procurement complexity without direct construction risk. These three entities collectively illustrate how international operators fragment their vendor relationships across design, construction management, and cost control functions rather than consolidating under single-source arrangements.
| Leading Market Players |
|---|
| AECOM Philippines Inc. |
| Jacobs Project Philippines Inc. |
| Turner & Townsend |
| Arup |
| Aurecon Group Pty. Ltd. |
| Endec Group |
| Rider Levett Bucknall Philippines Inc. |
| First Balfour Inc. |
| MDBI Construction Corporation |
| Others |
Pricing and Supply Chain Analysis
Metro Manila's 24-36 month NGCP interconnection queues signal acute undercapacity that compresses supplier margins in the capital while inflating cost premiums for expedited provincial development. This utilization asymmetry forces contractors to absorb risk in Cavite and Laguna where land arbitrage attracts hyperscale commitments, while buyers in the constrained core face scarcity-driven pricing power erosion.
Pricing Analysis
Cavite and Laguna provinces trade at 15-25 percent construction cost discounts versus Metro Manila's grid-constrained sites, with price differentiation centering on power availability premiums and fire safety material compliance tiers. Project-based contracting dominates, with hyperscale direct awards commanding fixed-price certainty while colocation builds face cost-plus volatility from steel and copper commodity exposure. Pricing pressure stems from specialized MEP workforce scarcity that extends recruitment cycles and elevates labor premiums. Enterprise banking verticals show least price sensitivity due to Bangko Sentral ng Pilipinas compliance mandates, while speculative colocation developers face acute margin compression from buyer consolidation under hyperscale direct contracts.
Supply Chain Analysis
Upstream feedstock for critical infrastructure draws from China for electrical switchgear and prefabricated power modules, South Korea for precision cooling components, and domestic sources for reinforced concrete and structural steel. Copper busbar, diesel generator sets, and lithium-ion UPS batteries constitute the highest-value input dependencies. Single-source vulnerability concentrates in liquid cooling skids where tropical climate engineering specifications limit qualified suppliers. Distribution runs through international EPC contractors with Philippine-based integration facilities in Laguna's industrial zones, bypassing traditional building materials wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippine data center construction market rewards engineering firms with pre-positioned tropical climate expertise and DICT accreditation navigation capabilities, while penalizing generalist contractors lacking mission-critical MEP credentials. This capability scarcity concentrates contract capture among AECOM Philippines Inc., Jacobs Project Philippines Inc., and Turner & Townsend archetypes.
For Market Incumbents: Pre-empt provincial land aggregation in Cavite and Laguna before NGCP substation queues lengthen further, securing interconnection positions that freeze competitor site feasibility. Acquire or partner with liquid cooling specialists as direct-to-chip and immersion specifications displace traditional mechanical refrigeration. Vertical integration into prefabricated module fabrication compresses 30-40 percent timeline advantages that generalist stick-build contractors cannot replicate. For New Entrants and Emerging Players: Mid-market edge deployments in Cebu and Davao metropolitan areas represent the most penetrable entry point, with latency-sensitive applications for Visayas and Mindanao digital economies underserved by capital-region infrastructure. Target municipal government and provincial utility relationships as the critical go-to-market angle, as local permitting velocity determines project viability ahead of technical specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hyperscale campus developments as dual-fed substation requirements and renewable energy wheeling agreements strain project finance structures. Acquisition candidates include domestic contractors with National Building Code variance track records and established Bureau of Fire Protection inspection relationships. Watch NGCP interconnection queue position announcements as the signal for site feasibility inflection and development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Module Integration | Factory-built power and cooling skids compress commissioning windows by 30-40 percent versus stick-built alternatives. |
| Liquid Cooling Technology Convergence | Direct-to-chip and immersion systems enable higher rack densities without tropical climate mechanical refrigeration penalties. |
| Provincial Land Aggregation | Cavite and Laguna site acquisition ahead of NGCP queue saturation secures interconnection priority for hyperscale commitments. |
| DICT Accreditation Compliance | Cybersecurity and physical security mandates now exceed voluntary guidelines, extending pre-operational phases for foreign operators. |
| Renewable Energy Wheeling Agreements | Retail electricity supplier contracts for green power determine site feasibility for sustainability-committed hyperscale tenants. |
Research Methodology
Desk research of DICT regulatory filings, NGCP interconnection queue databases, and Bureau of Fire Protection ordinance compendiums preceded structured interviews with data center engineering directors, EPC project managers, Meralco utility planning officers, and hyperscale cloud provider real estate leads. Secondary validation drew from Department of Energy reliability standard circulars, National Building Code variance application records, and provincial investment promotion agency land availability disclosures. Bottom-up project pipeline aggregation triangulated against top-down contractor revenue segmentation.
Assumptions held fixed include DICT accreditation framework continuity and NGCP transmission expansion timelines, while variables included hyperscale commitment velocity, renewable energy wheeling regulatory evolution, and liquid cooling technology adoption curves. Segmentation dimensions encompassed service type, facility type, building material, and infrastructure subsystem across the analysis window. CAGRs derived from facility completion forecasts weighted by power density specifications and redundancy tier capital intensity, with hyperscale direct contract absorption rates and provincial migration patterns as primary demand-side inputs.
Stress conditions across NGCP queue extension scenarios, fire safety material cost inflation bands, and specialized MEP workforce availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and utility infrastructure delivery. Cross-checking against Department of Energy power service reliability standard enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Market