
 Qatar Transportation Infrastructure Construction Market | 2026-2036
Qatar Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Transportation Infrastructure Construction Market Analytics
Aftermarket service revenue from completed transport assets is narrowing the margin gap between pure construction and long-term asset management. Redco Construction AL Mana leverages its diversified project portfolio to capture recurring maintenance contracts. Gulf Contracting Company anchors its position through heavy civil capabilities in bridge and highway segments. HBK Contracting Company W.L.L competes aggressively on government tenders tied to rail corridor development.
Qatar transportation infrastructure construction encompasses the planning, engineering, and physical assembly of road networks, bridge systems, railway lines, and airport facilities using concrete, asphalt, steel, and composite materials. These assets function as load-bearing, traffic-distributing systems engineered to withstand desert thermal cycling, saline groundwater exposure, and seismic zone requirements while enabling passenger and freight mobility. Roads and bridges currently occupy the largest share of awarded contract value due to Lusail City connectivity demands and industrial zone expansion. Railways represent the fastest-growing project type as the Doha Metro Phase extensions and freight rail links to Saudi Arabia advance through procurement. Sustainable construction methods are gaining traction among end users seeking compliance with green building certifications and reduced embodied carbon in concrete pours.
Qatar's Public Works Authority (Ashghal) and the Ministry of Municipality enforce building codes and material standards that mandate sulfate-resistant cement and corrosion-protected steel reinforcement in coastal zones. The Qatar Central Bank's project finance guidelines and sovereign wealth fund capital allocations shape contractor liquidity and bonding capacity requirements. Ashghal's updated pavement design specifications now incorporate warm-mix asphalt and recycled aggregate thresholds. Stakeholders must monitor how procurement rule changes around local content quotas and joint-venture structuring affect foreign contractor market access.
Market Dynamics
Qatar's National Vision 2030 infrastructure mandates are compressing project timelines and forcing procurement toward integrated design-build contracts that bundle construction with decades-long maintenance obligations. This structural shift favors contractors with captive engineering capabilities and sovereign wealth fund backing.
Growth Catalysts
- Lusail City Connectivity Mandates:Ashghal's arterial road specifications require dual-carriage highways linking the new city to Hamad International Airport, generating sustained civil works demand through 2030.
- Doha Metro Phase Extensions:Qatar Rail's procurement of Red Line North and Green Line expansions is accelerating steel and concrete orders for underground stations and elevated viaducts.
- Sulfate-Resistant Cement Standards:Coastal zone building codes mandate corrosion-protected reinforcement, creating premium material substitution opportunities for domestic suppliers.
Market Restraints
- Steel Price Volatility:Rebar and structural steel input costs fluctuate with Gulf Cooperation Council import tariffs, compressing fixed-price contract margins for highway builders.
- Labor Camp Capacity Limits:Ministry of Municipality enforcement of worker housing standards restricts peak workforce deployment during summer construction windows.
- Desalinated Water Dependency:Concrete curing and dust suppression operations rely on energy-intensive desalination, exposing contractors to Qatar General Electricity and Water Corporation tariff revisions.
Strategic Opportunities
- Freight Rail Links to Saudi Arabia:The GCC Rail interconnection agreement creates cross-border civil works scope for bridge and track contractors with Saudi joint-venture credentials.
- Warm-Mix Asphalt Adoption:Ashghal's updated pavement specifications permit reduced-temperature paving, opening technology licensing partnerships for European equipment suppliers.
- Industrial Zone Expansion:Ras Laffan and Mesaieed petrochemical corridor growth is generating dedicated heavy-haul road and port access contracts outside Doha's competitive core.
Industry Challenges
- Geotechnical Survey Gaps:Karst limestone formations beneath Doha create unexpected foundation conditions, forcing design changes that delay piling and tunnel boring machine deployment.
- Local Content Quota Compliance:Procurement rules requiring minimum Qatari workforce ratios and domestic material sourcing complicate foreign contractor joint-venture structuring and bid pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Transportation Infrastructure Construction Market |
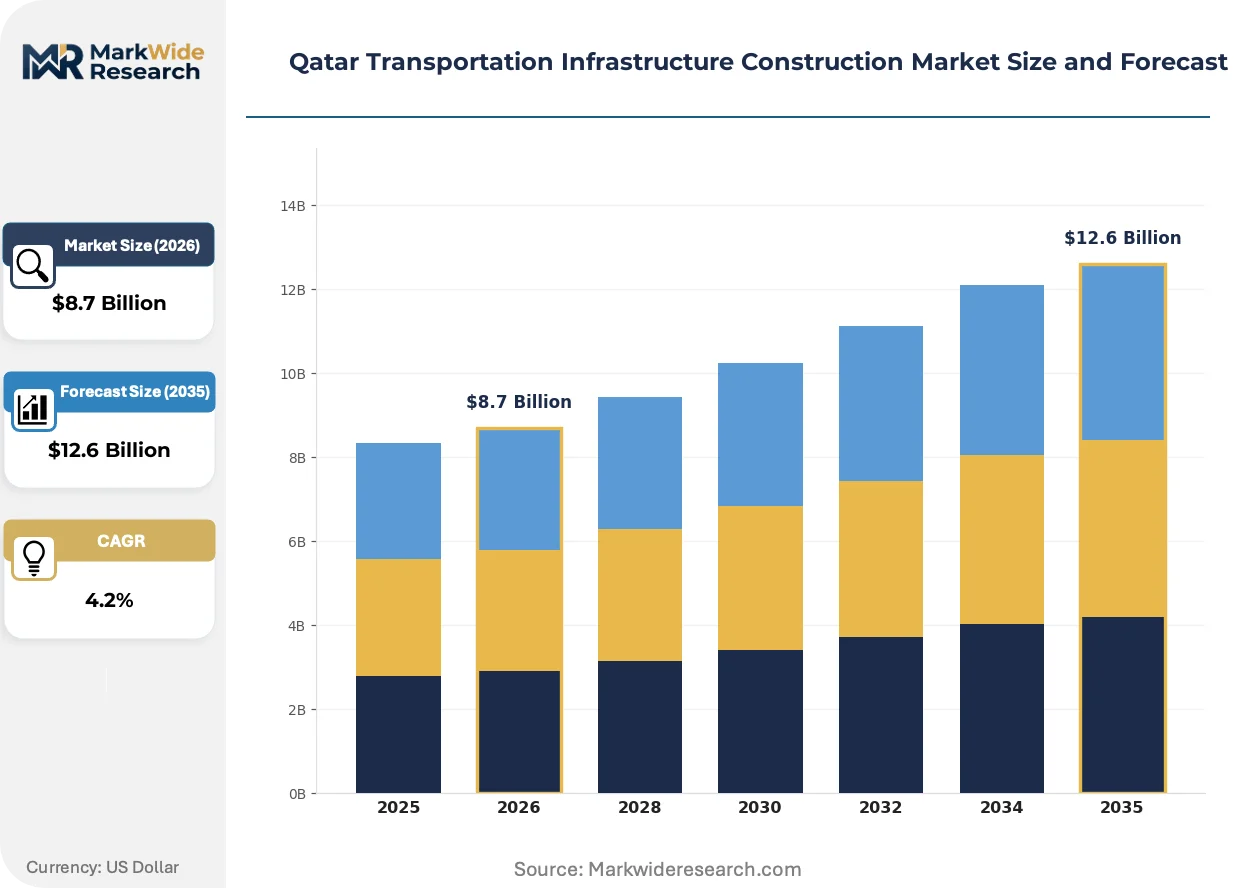
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material Type: Concrete, Asphalt, Steel, Composites Construction Method: Traditional, Modular, Prefabricated, Sustainable End User: Government, Private Sector, Contractors, Consultants |
| Companies Covered | Redco Construction AL Mana, Gulf Contracting Company, AIJaber Engineering WLL, MIDMAC Contracting Co WLL, HBK Contracting Company W.L.L, Boom Construction Co., Medgulf Construction Company WLL, Besix Group, PORR AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Transportation Infrastructure Construction Market Evolving Landscape
Digital twin platforms and sustainable material specifications are converging to reshape how transport assets get designed, built, and handed over to operators. Contractors now compete on data deliverables as much as physical construction quality.
Building Information Modeling integrated with geospatial survey drones is digitizing earthworks quantity verification and as-built documentation for Ashghal highway projects. Major contractors deploy laser-scanned terrain models to eliminate rework on interchange earthmoving. This capability is compressing final account settlement timelines from months to weeks.
Ashghal's updated pavement design specifications now mandate warm-mix asphalt thresholds and recycled aggregate incorporation for arterial road contracts. The Public Works Authority enforces compliance through third-party laboratory testing of mix designs. Contractors lacking in-house materials testing capability face disqualification from tier-one bid lists.
Long-term service agreements are displacing traditional construction-only contracts as Qatar Rail and Hamad International Airport seek single-point accountability for asset lifecycle performance. Design-build-maintain procurement bundles twenty-year maintenance obligations with initial civil works. European and Korean contractors with rail operations experience capture premium pricing for these integrated scopes.
Qatar Transportation Infrastructure Construction Market Segmentation
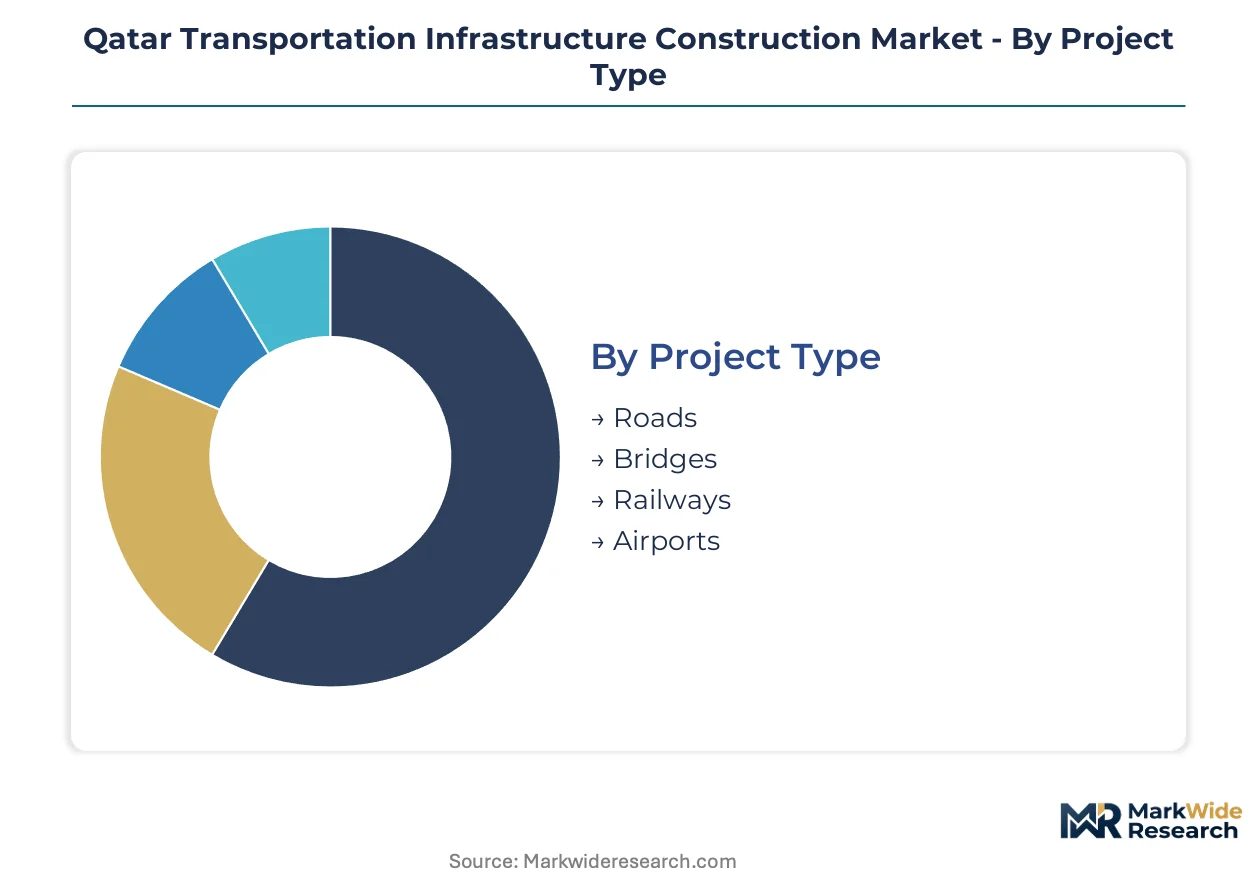
Project type, material selection, construction methodology, and end-user procurement patterns each govern distinct bidding strategies and margin profiles for contractors operating under Qatar's National Vision 2030 framework. Segment boundaries blur where design-build-maintain contracts bundle multiple categories into single-source accountability.
Project Type:
Application focus determines contract scale, technical complexity, and maintenance obligation length across Qatar's transport portfolio.
- Roads:Dual-carriage arterial highways and urban distributor roads form the largest awarded contract volume. Ashghal's Lusail City connectivity mandates sustain demand for grade-separated interchanges linking Hamad International Airport to new urban cores.
- Bridges:Elevated viaducts and marine crossings concentrate in industrial corridor extensions. Sulfate-resistant foundation specifications and seismic zone compliance elevate engineering costs above standard highway construction.
- Railways:Underground stations and elevated trackwork for Doha Metro Phase extensions absorb premium steel and concrete volumes. Qatar Rail's procurement bundles twenty-year maintenance obligations with initial civil works.
- Airports:Runway pavements, taxiway systems, and terminal access roads serve Hamad International Airport expansion and new general aviation facilities. Specialized asphalt specifications for aircraft loading govern material selection.
Roads command the established base. The steepest expansion runs through Railways.
Material Type:
Cost tier positioning reflects raw material sourcing constraints, thermal performance requirements, and Ashghal specification mandates for coastal zone durability.
- Concrete:Sulfate-resistant cement formulations dominate coastal and subterranean applications. Domestic suppliers capture premium substitution opportunities where building codes mandate corrosion-protected reinforcement in marine environments.
- Asphalt:Warm-mix thresholds and recycled aggregate incorporation now feature in arterial road contracts. Third-party laboratory testing of mix designs disqualifies contractors lacking in-house materials capability.
- Steel:Rebar and structural sections face Gulf Cooperation Council import tariff volatility. Fixed-price highway contracts expose builders to margin compression when regional steel prices spike.
- Composites:Fiber-reinforced polymers and advanced polymer concrete gain traction in bridge deck overlays and corrosion-critical applications. Higher upfront costs trade against reduced lifecycle maintenance.
Concrete commands the established base. Composite adoption is climbing the fastest.
Construction Method:
Maturity gradients separate legacy procurement from emerging delivery models reshaping contractor capability requirements.
- Traditional:Cast-in-place concrete and conventional steel erection retain dominance in government tenders. Established Qatari contractors anchor market position through heavy civil execution speed.
- Modular:Pre-cast segmental bridge construction and standardized station modules compress on-site labor exposure. Factory-controlled quality reduces rework in desert thermal cycling conditions.
- Prefabricated:Off-site manufactured bridge girders and tunnel lining segments minimize summer construction window constraints. Logistics complexity rises with component scale and site access limitations.
- Sustainable:Reduced-temperature paving, recycled aggregate incorporation, and embodied carbon tracking align with green building certification demands. European equipment suppliers license warm-mix technology to local contractors.
Traditional methods command the established base. Sustainable construction is gaining share fastest.
End User:
Customer type dictates procurement rule exposure, payment security, and joint-venture structuring complexity.
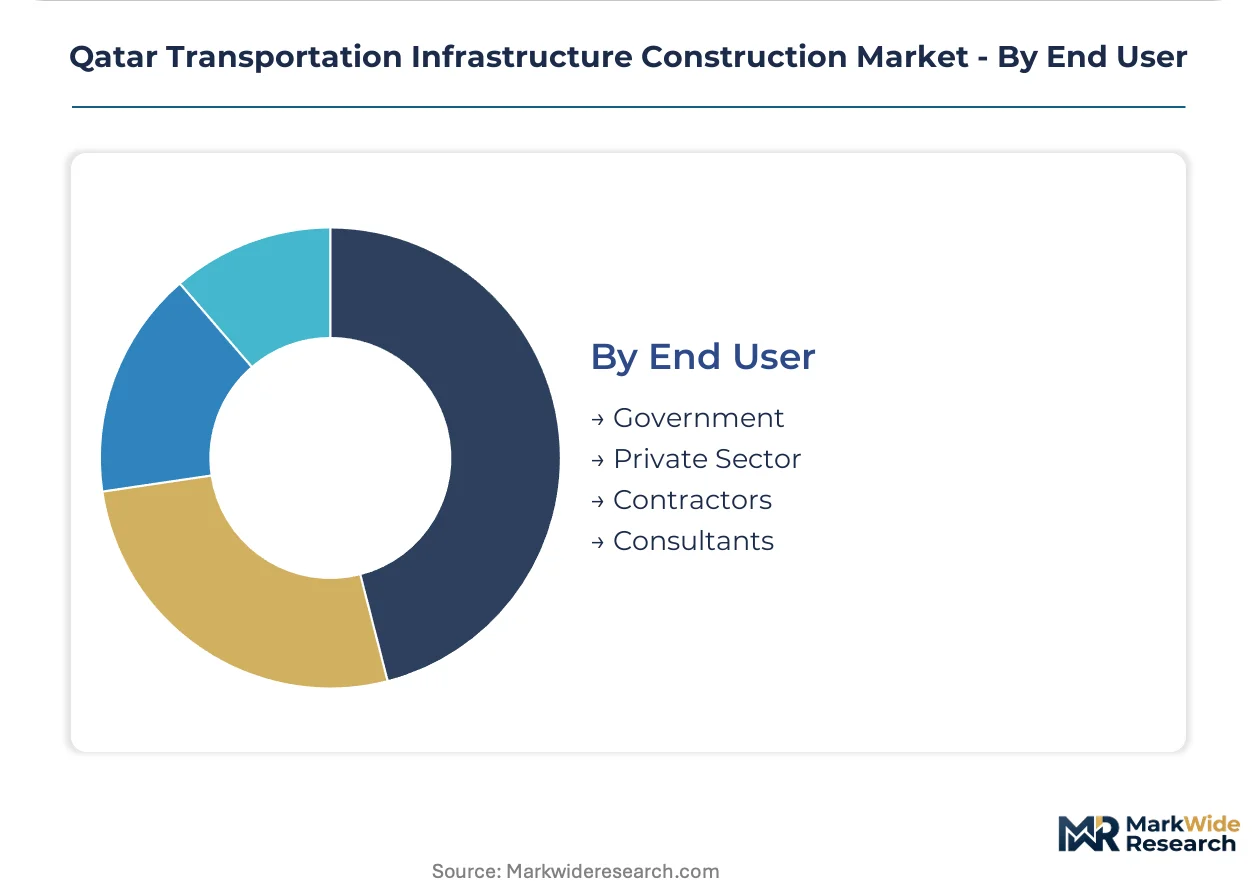
- Government:Ashghal and Qatar Rail tenders absorb the bulk of contract value. Local content quotas and Qatari workforce ratio mandates complicate foreign contractor market access.
- Private Sector:Industrial zone developers in Ras Laffan and Mesaieed generate dedicated heavy-haul road and port access contracts. Payment terms typically outpace government settlement timelines.
- Contractors:Design-build-maintain procurement bundles long-term service agreements with initial construction. Sovereign wealth fund backing and captive engineering capabilities favor integrated bidders.
- Consultants:Engineering advisory roles concentrate in geotechnical survey gaps and digital twin platform deployment. Laser-scanned terrain modeling contracts compress final account settlement timelines.
Government procurement commands the established base. Private sector engagement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor concentration clusters around Doha and its industrial corridors, with Ashghal procurement mandates directing award flows toward specific municipal zones. Five sub-regional markets absorb distinct project typologies under Qatar National Vision 2030 implementation schedules.
Doha Metropolitan Core
Underground station excavation and elevated viaduct construction for Doha Metro Phase extensions dominate steel and concrete procurement. Qatar Rail mandates twenty-year maintenance obligations bundled with civil works awards. Lusail City arterial highways linking Hamad International Airport concentrate interchange construction in the northern corridor.
Al Wakrah Industrial Corridor
Mesaieed petrochemical expansion drives heavy-haul road and port access contracts outside Doha's competitive core. Ashghal specifications for dual-carriage highways accommodate abnormal load configurations for refinery equipment transport. Sulfate-resistant foundation standards elevate engineering costs above standard municipal construction.
Al Khor Northern Zone
Ras Laffan liquefied natural gas infrastructure sustains dedicated marine crossing and pipeline corridor contracts. Coastal zone building codes mandate corrosion-protected reinforcement in bridge foundations exposed to saline groundwater. Modular pre-cast segmental construction minimizes summer construction window exposure.
Al Rayyan Western Suburbs
Educational City and Qatar Foundation campus extensions generate campus distributor road networks with specialized pavement specifications. Warm-mix asphalt thresholds and recycled aggregate incorporation feature in Ashghal arterial road contracts. Third-party laboratory testing of mix designs filters contractor qualification lists.
Umm Salal Central Belt
Logistics hub development and freight rail staging yards advance through procurement under GCC Rail interconnection timelines. Geotechnical survey gaps in karst limestone formations force design modifications during piling operations. Sovereign wealth fund capital allocations shape contractor bonding capacity for cross-border civil works scope.
Qatar Transportation Infrastructure Construction Market Competitive Landscape
Diversified construction groups and specialized heavy civil contractors split the market between integrated design-build-maintain awards and traditional procurement. Market structure tilts toward consolidation around sovereign wealth fund-backed entities with captive engineering capabilities. Three archetypes dominate: diversified conglomerates with maintenance service arms, heavy civil specialists with bridge and highway execution speed, and European-Korean joint ventures with rail operations experience. Competitive intensity centers on technology licensing partnerships for warm-mix asphalt and pre-qualification for bundled long-term service agreements.
Within the diversified conglomerate tier, Redco Construction AL Mana and Gulf Contracting Company anchor positions through project portfolio breadth and heavy civil execution capabilities respectively. HBK Contracting Company W.L.L occupies a position among contractors competing aggressively on government tenders tied to rail corridor development. These three entities exemplify how captive engineering resources and established Ashghal relationships determine bid list placement for integrated procurement formats.
| Leading Market Players |
|---|
| Redco Construction AL Mana |
| Gulf Contracting Company |
| AIJaber Engineering WLL |
| MIDMAC Contracting Co WLL |
| HBK Contracting Company W.L.L |
| Boom Construction Co. |
| Medgulf Construction Company WLL |
| Besix Group |
| PORR AG |
| Others |
Value Network & Pricing Analysis
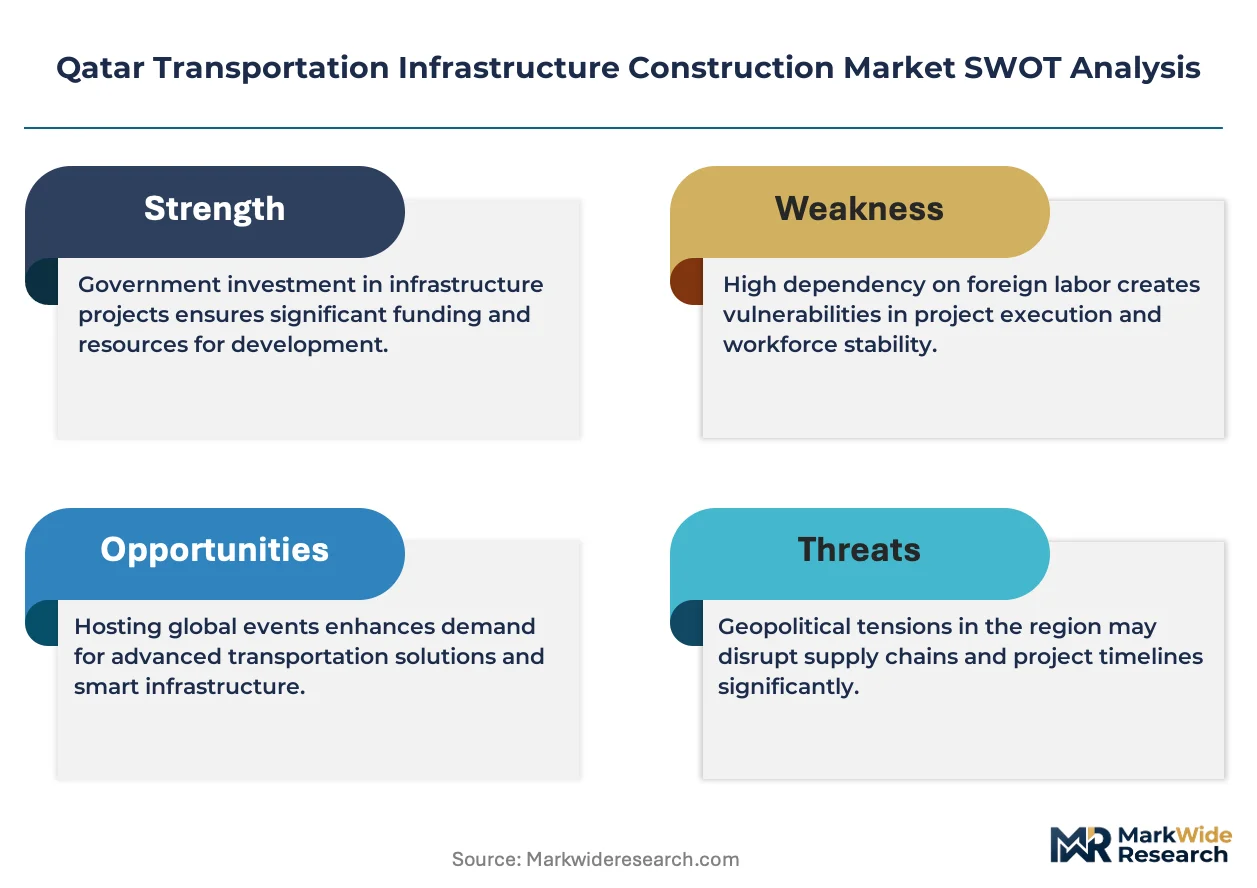
Undercapacity in European steel rebar production is tightening supply availability for Gulf contractors, forcing Qatar's Public Works Authority procurement to absorb premium import costs while domestic suppliers leverage scarcity to extract favorable payment terms from project developers.
Pricing Analysis
Ashghal's updated pavement design specifications dictate the pricing tier structure across Qatar's transportation infrastructure construction market. Three-tier pricing separates premium sulfate-resistant concrete formulations from standard-grade asphalt mixes and economy-tier recycled aggregate blends. Cost compression in steel-intensive rail corridor contracts is intensifying because Gulf Cooperation Council import tariffs expose fixed-price highway builders to margin erosion. Industrial zone developers in Ras Laffan exhibit the lowest price sensitivity due to petrochemical project contingency buffers, while municipal road contractors face acute pressure from compressed government settlement timelines.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities are anchoring contractor liquidity as Qatar Central Bank project finance guidelines reshape bonding capacity requirements. Steel rebar draws from Turkey, China, and India; sulfate-resistant cement feeds from Saudi Arabia and UAE; warm-mix asphalt technology sources from European equipment licensors. Single-source vulnerability concentrates around specialized tunnel boring machine components and corrosion-protected reinforcement coatings. Distribution runs through Ashghal-certified material yards and Qatar Rail consolidated procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's transportation infrastructure construction market is cycling through a post-mega-project recovery phase as National Vision 2030 implementation schedules compress procurement timelines and favor integrated design-build-maintain awards.
For Market Incumbents: Insulate margin position through captive engineering capabilities that capture bundled long-term maintenance obligations from Qatar Rail and Hamad International Airport procurement. Deepen backward integration into warm-mix asphalt technology licensing to reduce European supplier dependency. Local content quota compliance offers defensive moat construction against foreign joint-venture competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in Ras Laffan and Mesaieed industrial corridor heavy-haul road contracts outside Doha's saturated competitive core. The freight rail staging yards in Umm Salal Central Belt represent the most penetrable geography given GCC Rail interconnection procurement timelines. A Saudi joint-venture credential unlocks cross-border civil works scope. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contractors with design-build-maintain capabilities and sovereign wealth fund backing. Long-term viability hinges on twenty-year service agreement pricing power rather than construction-only margin capture. Target acquisition archetype: heavy civil specialists with bridge execution speed and Ashghal pre-qualification status. The signal to monitor is warm-mix asphalt specification adoption velocity as green certification compliance tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build-Maintain Contract Conversion | Qatar Rail's bundled procurement creates single-point accountability premiums for integrated bidders. |
| Warm-Mix Asphalt Technology Licensing | European equipment partnerships unlock Ashghal specification compliance and recycled aggregate incorporation. |
| Saudi Joint-Venture Structuring | GCC Rail interconnection credentials open cross-border freight rail civil works procurement. |
| Modular Pre-Cast Segmental Capacity | Factory-controlled quality reduces summer construction window exposure in coastal zone projects. |
| Digital Twin Platform Deployment | Laser-scanned terrain modeling compresses final account settlement timelines from months to weeks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Ashghal procurement officers, Qatar Rail project directors, heavy civil contractor estimating managers, and materials testing laboratory supervisors. Secondary validation drew from Qatar Central Bank project finance guidelines, Ashghal pavement design specifications, Qatar Rail procurement disclosures, and GCC Rail interconnection agreements. Bottom-up contract award aggregation and top-down National Vision 2030 capital allocation triangulation anchored market sizing.
Calibration against historical contract award flows and announced procurement schedules shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include project type, material selection, construction methodology, and end-user procurement pattern. CAGRs were derived from disclosed contract values and pipeline visibility. Industry-specific forecast inputs encompass karst limestone geotechnical risk factors and local content quota compliance trajectories.
Sensitivities concentrate around steel price volatility, Ministry of Municipality labor camp enforcement intensity, and Qatar General Electricity and Water Corporation tariff revision schedules. Forecasts reflect documented assumptions around sovereign wealth fund capital allocation continuity and Ashghal specification stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market