
 Mining Locomotive Market | 2026-2036
Mining Locomotive Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Locomotive Market Analysis
Direct procurement channels between original equipment manufacturers and tier-one mining houses is reshaping how locomotive contracts are negotiated and fulfilled. Siemens AG leverages its electric drive expertise to anchor long-term service agreements with major ore producers. Alstom SA competes through specialized narrow-gauge systems for constrained tunnel environments. Hitachi Ltd. differentiates by integrating automation-ready platforms that reduce operator exposure in hazardous headings.
A mining locomotive is a rail-mounted traction vehicle engineered to haul ore cars, personnel carriers, and material wagons through subterranean galleries or open-pit tracks, typically operating on 600V to 3000V DC overhead lines, battery banks, or diesel-electric powertrains rated between 50 kW and 500 kW depending on gradient and payload. Its primary purpose is to move bulk mineral output from extraction faces to processing plants or surface loading points with minimal ventilation burden and track wear. Battery-powered units now capture the fastest expansion as mines pursue zero-emission targets and reduce underground ventilation infrastructure. Diesel-powered fleets retain dominance in surface applications and remote sites lacking grid connectivity, though their margin pools are compressing under emissions compliance costs. Electric-powered systems with trolley-assist or continuous overhead supply sustain the highest utilization rates in deep, high-volume operations.
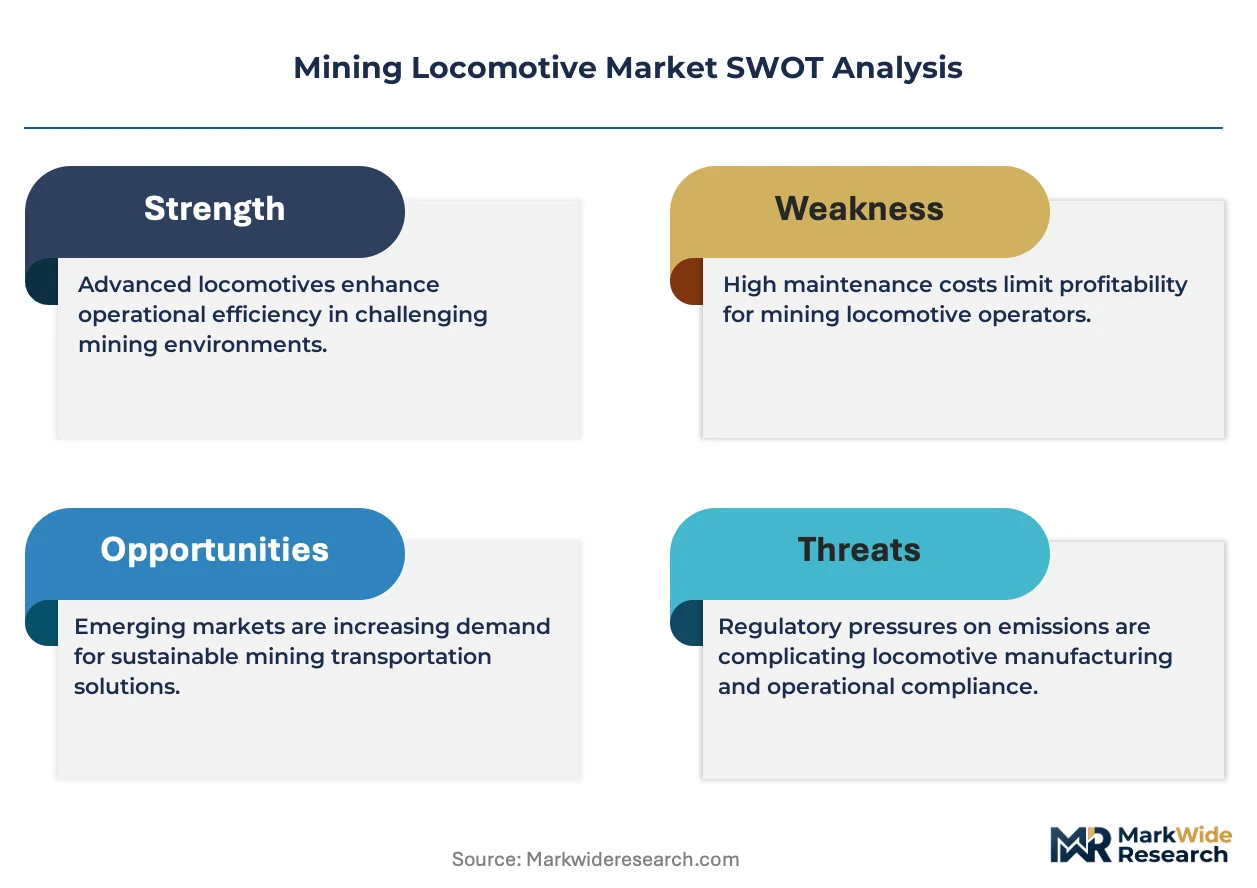
The US Mine Safety and Health Administration enforces ventilation and fire suppression standards that directly elevate capital costs for diesel locomotives while creating regulatory preference for battery-electric alternatives. Australia's state-based mining regulators, alongside ISO 19296 for underground mining machinery safety, mandate collision avoidance and operator proximity systems that reshape technology procurement specifications. Stakeholders must monitor how automation certification pathways evolve and whether battery energy density improvements can displace diesel in the heaviest payload categories without sacrificing shift endurance.
Market Dynamics
Underground ventilation economics are compressing the total cost of ownership for diesel fleets while battery energy density improvements above 200 Wh/kg now enable single-shift endurance in 150-tonne payload operations previously reserved for combustion powertrains.
Growth Catalysts
- Canada's diesel particulate regulations:Federal limits on elemental carbon exposure in underground mines are forcing fleet turnover toward battery-electric alternatives before asset depreciation cycles complete.
- Copper extraction depths:Chilean and Peruvian operations below 1,000 meters require trolley-assist electric systems to manage heat load and ventilation costs that scale exponentially with diesel combustion.
- Lithium iron phosphate cell chemistry:Thermal stability improvements in LFP batteries are eliminating the fire suppression infrastructure previously required for underground lithium-ion deployment.
Market Restraints
- Cobalt and lithium price volatility:Battery pack costs remain exposed to Democratic Republic of Congo cobalt concentrate and Chilean lithium carbonate spot markets.
- Grid infrastructure gaps:Remote Pilbara and Mongolian Gobi sites lack the 11kV distribution networks required for continuous overhead trolley systems.
- ISO 19296 certification timelines:Collision avoidance system validation for autonomous retrofits extends delivery schedules by 8-14 months.
Strategic Opportunities
- Kazakhstan's untapped coal basins:Karaganda and Ekibastuz deposits lack rail haulage infrastructure, creating greenfield demand for modular battery-electric fleets.
- Autonomous haulage convergence:Integration of LiDAR-based positioning with existing trolley wire infrastructure enables mixed-fleet automation without full infrastructure replacement.
- Australia's Safeguard Mechanism reforms:Baseline emission reduction requirements for large mining facilities create compliance-driven procurement preference for zero-emission traction.
Industry Challenges
- Electrical trades shortage:Maintenance of 1,500V DC traction systems requires certified high-voltage technicians scarce in Western Australia's mining labor pool.
- Legacy diesel fleet interoperability:Battery-electric locomotives must maintain coupling and braking compatibility with 30-year-old ore car fleets without full rolling stock replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Locomotive Market |
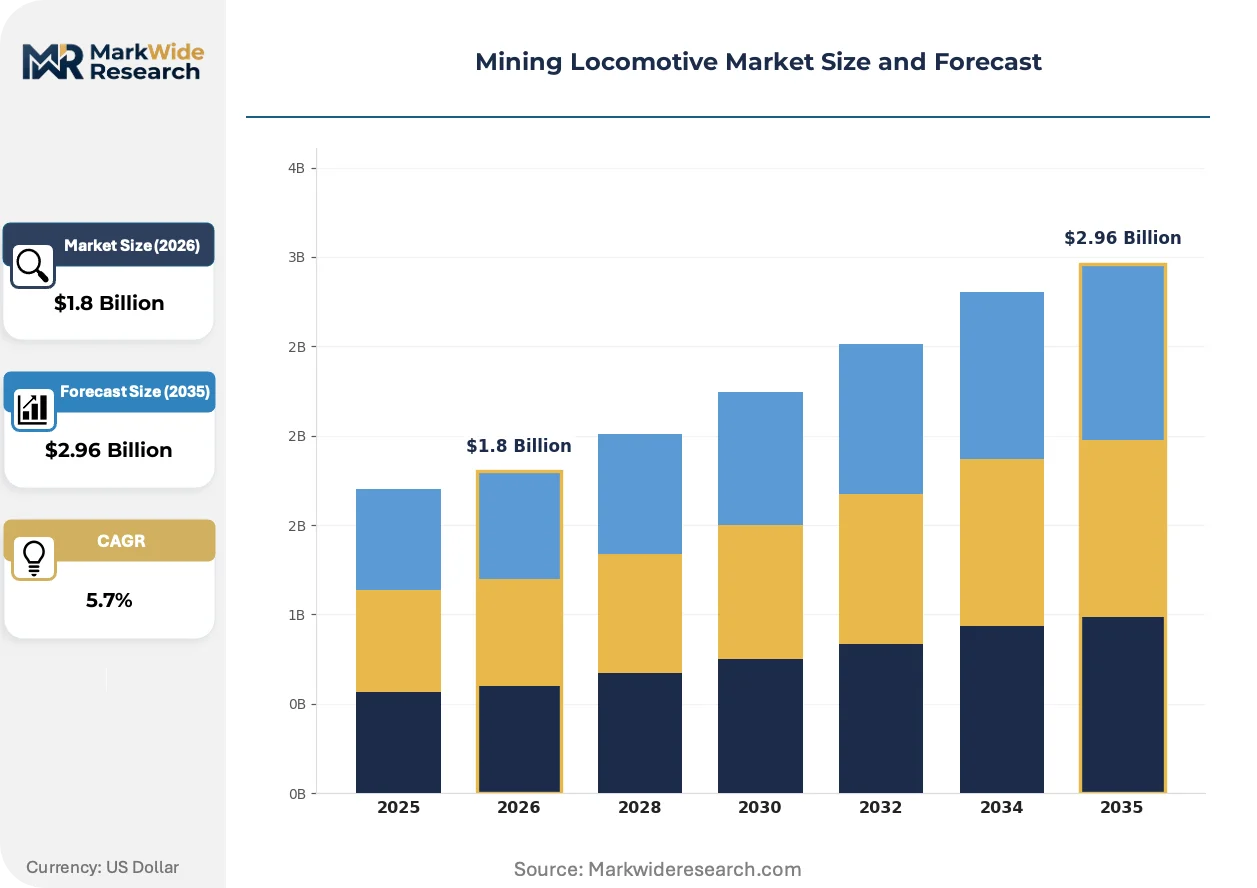
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Diesel-Powered, Electric-Powered, Hybrid Application: Underground Mining, Surface Mining, Material Handling, Transportation Technology: Electric Drive, Diesel Engine, Hybrid System, Automation End User: Mining Companies, Contractors, Equipment Manufacturers, Service Providers |
| Companies Covered | CSR Corporation Brookville, Trident, Mining Equipment Ltd., Bombardier Transportation, Irwin Car and Equipment, Alstom SA, AEG Power Solutions, Siemens AG, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Locomotive Market Emerging Trajectories
Powertrain architecture decisions now precede mine development planning, with ventilation shaft sizing and grid connection capacity engineered around traction technology choice rather than retrofitted afterward.
Permanent magnet synchronous motors are displacing DC traction motors in underground haulage. Anglo American's Chilean copper divisions specify IPM motor packages for 35% efficiency gains in regenerative braking recovery. The technology is migrating from premium greenfield projects to mid-life fleet renewals as rewind costs for aging DC armatures exceed motor replacement economics.
Australia's state mining regulators are harmonizing autonomous vehicle certification with ISO 17757 earth-moving machinery safety standards. This convergence accelerates approval timelines for collision avoidance systems but forces suppliers to maintain dual certification pathways for jurisdictions retaining legacy MSHA-equivalent frameworks. Deep South African gold mines face the steepest compliance cost escalation.
Service contract unbundling is separating locomotive supply from maintenance provision. BHP and Rio Tinto now tender power-by-the-hour agreements distinct from capital procurement, with specialist electrical contractors assuming battery lifecycle risk. This restructuring concentrates in Western Australia's iron ore district where fleet utilization exceeds 6,000 hours annually.
Mining Locomotive Market Segmentation
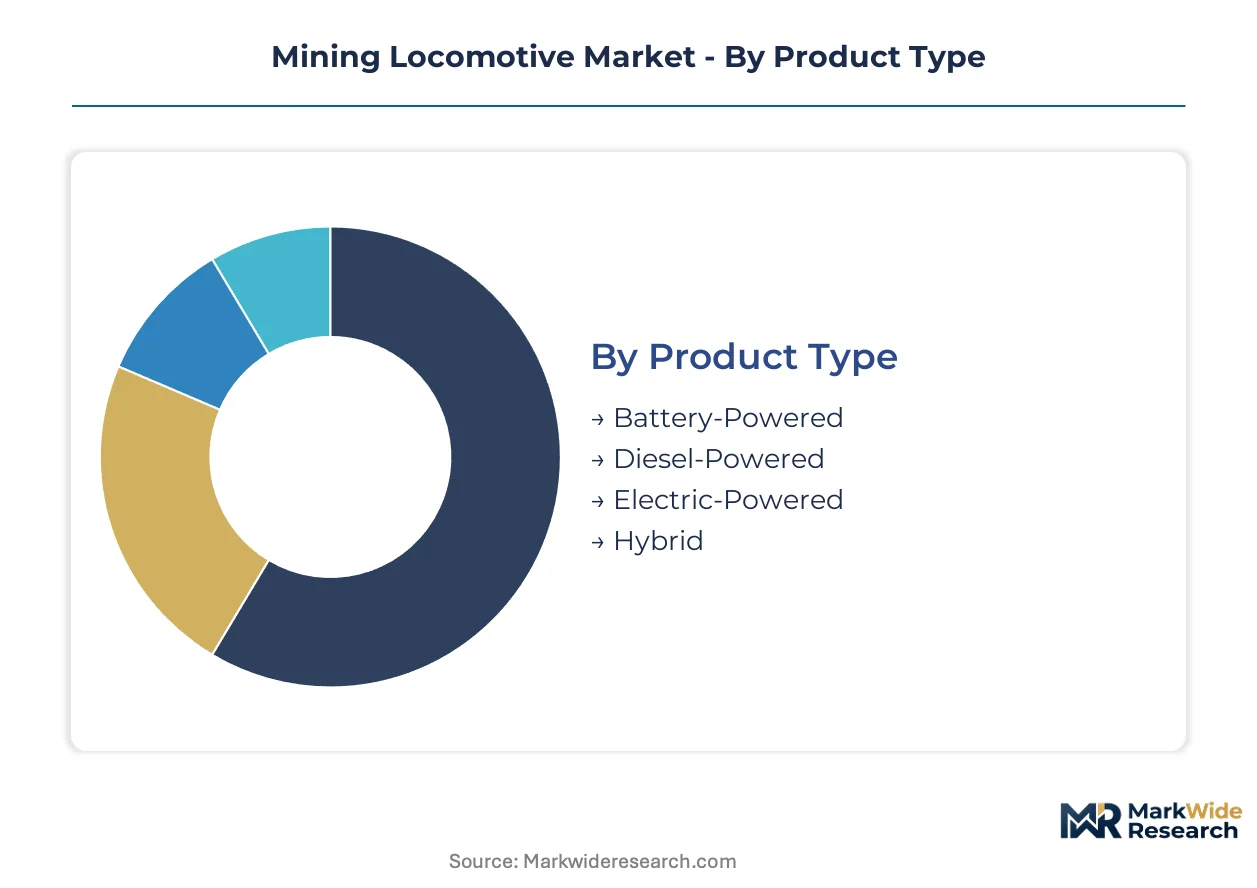
Mining locomotive procurement cycles vary dramatically by powertrain technology, with battery-electric fleets turning over in 8-12 years versus 15-20 years for diesel assets. Fleet managers align replacement schedules with ventilation infrastructure investments and automation retrofit windows.
Product Type:
Battery-powered units exhibit the shortest replacement cycles as energy density improvements render three-year-old packs obsolete, while diesel locomotives linger longest in remote surface operations.
- Battery-Powered:Lithium iron phosphate cell packs rated 200-400 kWh now deliver single-shift endurance in 150-tonne payload operations. Western Australia's Pilbara iron ore district concentrates demand as BHP and Rio Tinto pursue zero-emission targets under Australia's Safeguard Mechanism reforms.
- Diesel-Powered:Cummins and MTU engines rated 300-500 kW retain dominance in surface applications and Mongolian Gobi sites lacking grid connectivity. Canada's federal elemental carbon limits are forcing premature retirement of underground diesel fleets before depreciation cycles complete.
- Electric-Powered:Trolley-assist systems operating on 1,500V DC overhead lines sustain highest utilization rates in Chilean copper operations below 1,000 meters depth.
- Hybrid:Diesel-battery configurations bridge infrastructure gaps in Kazakhstan's Karaganda coal basin where grid extensions remain uneconomical.
Diesel-powered locomotives dominate installed base. Battery-powered units are where expansion concentrates.
Application:
Underground operations command premium pricing due to ventilation cost burdens and fire suppression requirements, while surface mining favors standardized configurations with lower technical complexity.
- Underground Mining:Narrow-gauge systems operating on 600mm-900mm track gauge haul ore cars through constrained tunnel environments. Chilean and Peruvian copper-gold operations below 1,000 meters require trolley-assist electric traction to manage heat loads.
- Surface Mining:Standard-gauge locomotives on 1,435mm track move bulk ore across open-pit perimeters and processing plant spurs. Pilbara iron ore district fleets exceed 6,000 annual operating hours.
- Material Handling:Shunting locomotives rated 50-150 kW position rail cars at loading points and maintenance facilities.
- Transportation:Personnel carriers and man-riding vehicles operate on dedicated safety-rated tracks with ISO 19296 collision avoidance systems.
Surface mining dominates installed base. Underground mining is climbing the fastest.
Technology:
Permanent magnet synchronous motors are displacing DC traction motors across all power classes, with efficiency gains of 35% in regenerative braking recovery justifying premium capital outlays.
- Electric Drive:IPM motor packages with silicon carbide inverters enable trolley-assist and battery-electric architectures. Anglo American's Chilean copper divisions specify these systems for deep-level haulage.
- Diesel Engine:Tier 4 Final and Stage V compliant engines with diesel particulate filters face escalating maintenance costs in high-altitude Andean operations.
- Hybrid System:Battery-diesel series configurations reduce fuel consumption by 25-30% in intermittent duty cycles.
- Automation:LiDAR-based positioning integrated with existing trolley wire infrastructure enables mixed-fleet autonomous operation without full infrastructure replacement.
Diesel engine technology dominates installed base. Electric drive is gaining share fastest.
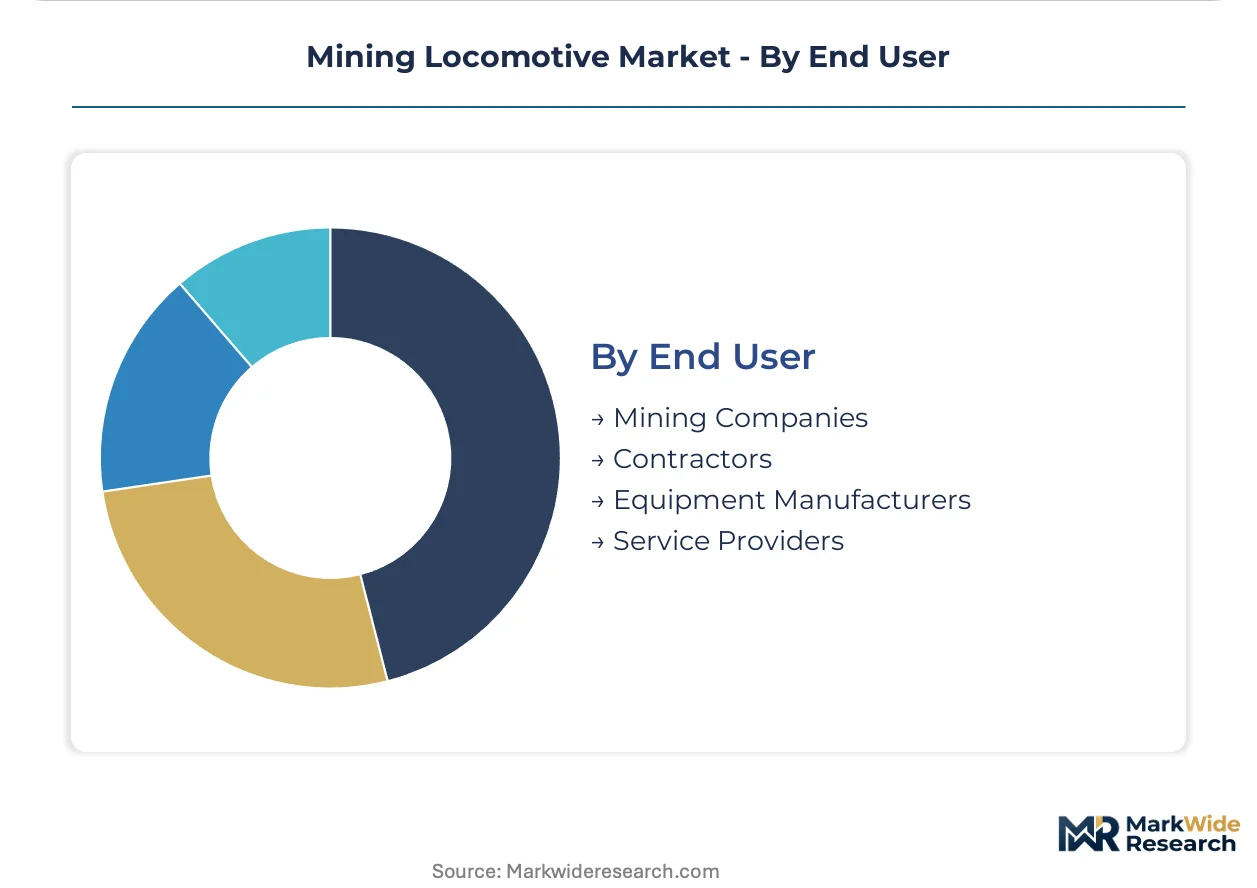
End User:
Tier-one mining houses with captive maintenance capabilities prefer power-by-the-hour service agreements, while contractors prioritize acquisition cost minimization and financing flexibility.
- Mining Companies:BHP, Rio Tinto, and Anglo American negotiate direct procurement with OEMs, unbundling locomotive supply from maintenance provision. Western Australia's iron ore district concentrates this purchasing pattern.
- Contractors:Specialist underground mining contractors in South Africa's deep gold operations favor leased diesel fleets with operator-inclusive contracts.
- Equipment Manufacturers:Siemens AG and Alstom SA anchor long-term service agreements through vertical integration into electrical infrastructure.
- Service Providers:Specialist electrical contractors assume battery lifecycle risk under emerging power-by-the-hour structures.
Mining companies dominate installed base. Service providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Safeguard Mechanism reforms are accelerating zero-emission procurement mandates across major iron ore basins. Canada's federal elemental carbon limits force premature diesel fleet retirement. Chile's deep copper operations below 1,000 meters drive trolley-assist electric adoption.
Australia
Western Australia's Pilbara iron ore district concentrates the world's highest-utilization mining locomotive fleets, exceeding 6,000 annual operating hours. The country's Safeguard Mechanism reforms impose baseline emission reduction requirements that redirect capital toward battery-electric traction. BHP and Rio Tinto negotiate direct procurement contracts with OEMs, unbundling locomotive supply from maintenance provision.
Canada
Underground hard-rock mining in Ontario and Quebec faces accelerated fleet turnover as federal diesel particulate regulations compress asset depreciation cycles. Health Canada enforces elemental carbon exposure limits that elevate capital costs for combustion powertrains. The Sudbury Basin nickel operations are converting to battery-electric haulage ahead of regulatory deadlines.
Chile
Copper extraction depths below 1,000 meters in the Atacama Desert require trolley-assist electric systems to manage exponential ventilation cost scaling. The country's mining regulator aligns collision avoidance certification with ISO 17757 standards. Anglo American's Los Bronces division specifies permanent magnet synchronous motor packages for regenerative braking recovery.
Kazakhstan
Karaganda and Ekibastuz coal basins lack established rail haulage infrastructure, creating greenfield demand for modular battery-electric fleets. The central government's mining modernization programs subsidize grid extension to remote extraction sites. Domestic procurement preferences favor locally assembled hybrid configurations bridging diesel-battery gaps.
United States
Appalachian coal operations and Western hard-rock mining confront MSHA ventilation and fire suppression standards that elevate diesel locomotive capital costs. The Mine Safety and Health Administration's regulatory preference channels underground procurement toward battery-electric alternatives. Arizona's copper porphyry deposits are piloting autonomous trolley-assist integration with existing infrastructure.
Mining Locomotive Market Vendor Landscape
On the supply side, the industry is consolidating around electrical infrastructure specialists with captive maintenance capabilities. Tier-one mining houses negotiate direct procurement contracts that separate capital acquisition from lifecycle service provision. Two strategic archetypes dominate: integrated electrical conglomerates with traction motor expertise, and narrow-gauge specialists engineering constrained tunnel environments. Competitive moves concentrate on long-term service agreement anchoring and automation-ready platform development.
Within the integrated electrical tier, Siemens AG and Hitachi Ltd. occupy positions defined by electric drive heritage and automation integration respectively. Alstom SA exemplifies the narrow-gauge specialization archetype for constrained underground environments. Among diversified industrial conglomerates, AEG Power Solutions represents the power electronics vector. These anchors illustrate how competitive positioning separates infrastructure-integrated suppliers from standalone equipment fabricators.
| Leading Market Players |
|---|
| CSR Corporation Brookville |
| Trident |
| Mining Equipment Ltd. |
| Bombardier Transportation |
| Irwin Car and Equipment |
| Alstom SA |
| AEG Power Solutions |
| Siemens AG |
| Hitachi Ltd. |
| Others |
Supply Flow & Price Mechanics
The Pilbara iron ore corridor's freight density compresses logistics premiums for Australian suppliers while amplifying price spreads between certified and uncertified equipment across procurement channels. Battery cell chemistry grade and ISO 19296 collision avoidance certification tier create the primary price differentiation vectors, with OEMs commanding premiums for automation-ready platforms that reduce operator exposure in hazardous headings.
Pricing Analysis
Certification level creates the primary spread between premium and standard equipment tiers, with ISO 19296-compliant collision avoidance systems and MSHA ventilation-rated configurations commanding substantial premiums over baseline offerings. Pricing stratifies across automation-ready, certified-manual, and economy-tier locomotives based on regenerative braking efficiency and battery energy density ratings. Cost compression in diesel-powered segments is intensifying because Canada's federal elemental carbon limits force premature fleet retirement before depreciation cycles complete. Contractor-operated leased fleets exhibit highest price sensitivity, while tier-one mining houses with captive maintenance capabilities prioritize lifecycle cost over acquisition price.
Supply Chain Analysis
Export control restrictions on permanent magnet synchronous motor technology and silicon carbide power electronics limit component flows from China and Japan to Western assembly plants. Manufacturing capacity concentrates in Germany, China, and Japan, with traction motor production anchored in industrial clusters near automotive electrification supply bases. The supply chain draws from Chilean lithium carbonate, DRC cobalt concentrate, and Australian rare earth processing for battery pack assembly. Single-source vulnerability in high-voltage DC inverter modules poses structural risk given limited qualified suppliers. Distribution runs through direct OEM-to-mine procurement channels that bypass traditional equipment dealers, with service provision unbundled from capital acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage electrical technicians capable of maintaining 1,500V DC traction systems represent the critical capability gap constraining fleet expansion in Western Australia's mining labor pool.
For Market Incumbents: Build captive maintenance moats through power-by-the-hour service agreements that assume battery lifecycle risk, locking in multi-year revenue streams with BHP and Rio Tinto. Defend against specialist electrical contractors by securing exclusive high-voltage technician training pipelines. Add rewind and remanufacturing capacity in Perth to capture mid-life fleet renewal demand from Pilbara operations. For New Entrants and Emerging Players: Kazakhstan's Karaganda and Ekibastuz coal basins offer greenfield penetration opportunity where rail haulage infrastructure remains undeveloped and domestic procurement preferences favor local assembly. Target modular battery-electric configurations that bridge diesel-battery gaps in grid-constrained sites. Enter through hybrid system partnerships with regional distributors holding government modernization contracts. For Investors and Strategic Acquirers: Narrow-gauge specialists with ISO 17757 autonomous certification capabilities and established Chilean copper mine relationships present the most defensible acquisition profile. Frame long-term viability around trolley-assist infrastructure expansion in deep extraction operations below 1,000 meters. Watch for inflection in Australia's Safeguard Mechanism baseline stringency, which would accelerate zero-emission procurement mandates beyond current compliance schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Service Contracting | Unbundles locomotive supply from maintenance, concentrating revenue with Siemens and Hitachi in Pilbara operations. |
| Permanent Magnet Motor Manufacturing Scale-Up | Captures 35% efficiency gains in regenerative braking, displacing DC traction in Chilean copper divisions. |
| Autonomous Certification Dual-Tracking | Maintains ISO 17757 and MSHA-equivalent pathways to accelerate approval timelines across jurisdictions. |
| Lithium Iron Phosphate Cell Integration | Eliminates fire suppression infrastructure requirements, unlocking underground deployment previously reserved for diesel. |
| High-Voltage Technician Training Pipeline | Addresses electrical trades shortage constraining 1,500V DC maintenance capacity in Western Australia. |
Methodological Framework
The analysis maps battery-electric, diesel-powered, trolley-assist, and hybrid powertrain segments, each validated through fleet managers at tier-one mining houses, procurement directors at Anglo American and BHP, maintenance heads at specialist electrical contractors, and regulatory affairs leads at OEMs. Primary interview intelligence triangulates against MSHA enforcement records, Australia's Safeguard Mechanism compliance filings, Chilean mining regulator collision avoidance certifications, and customs data on traction motor trade flows. Bottom-up unit deployment estimates reconcile with top-down capital expenditure projections across the analysis window.
Assumptions hold battery energy density improvements above 200 Wh/kg, Canada's elemental carbon limits enforcement timeline, and Chilean copper extraction depth expansion patterns fixed throughout the projection horizon. The analytical framework models powertrain technology, application environment, motor architecture, and end-user procurement archetype as core segmentation dimensions. CAGRs derive from installed base turnover rates aligned with ventilation infrastructure investment cycles and automation retrofit windows. Forecast inputs incorporate lithium carbonate spot price volatility and electrical trades availability in Western Australia's mining labor pool.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese battery cell manufacturers or accelerated trolley-assist infrastructure buildouts by Chilean state mining enterprises would shift outcomes. Material shifts in ISO 19296 certification timeline stringency or Australia's Safeguard Mechanism baseline reduction requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Surface Mining Equipment Market