
 South Africa Rigid Plastic Packaging Market | 2026-2036
South Africa Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Rigid Plastic Packaging Market Insights
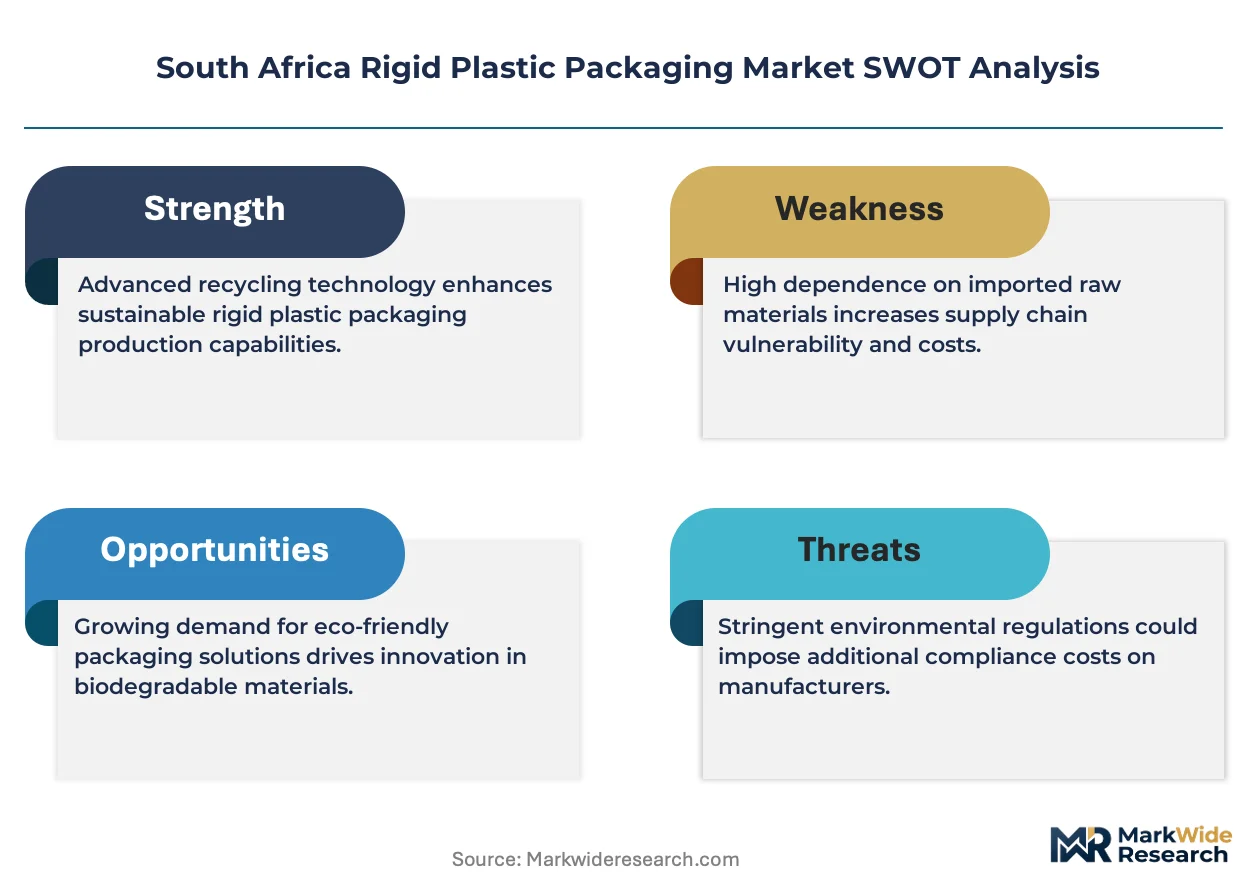
Polymer compounding expertise is unwinding a bottleneck that previously constrained high-performance rigid packaging output in South Africa. Mpact Group leverages integrated recycling and extrusion assets to secure feedstock continuity across bottle and container lines. Polyoak Packaging Group Pty Ltd anchors its position through specialized closure and jar manufacturing for food and pharmaceutical clients. Nampak Rigid Plastics competes via scale advantages in polyethylene terephthalate preform production serving beverage multinationals.
South Africa rigid plastic packaging comprises thermoformed and injection-molded structures engineered from polyethylene, polypropylene, polyethylene terephthalate, and polystyrene, typically manufactured through extrusion blow molding, injection stretch blow molding, or thermoforming processes to achieve dimensional stability, barrier performance, and stack strength for filled goods protection. The primary commercial purpose centers on extending shelf life, enabling retail display, and ensuring safe distribution of food, beverages, pharmaceuticals, and household products through the domestic supply chain. Bottles and containers dominate volume throughput given beverage and food application pull, while trays represent a faster-growing format as fresh protein and prepared meal segments expand modern retail penetration. Polypropylene exhibits structural momentum due to its heat resistance enabling hot-fill applications and growing mechanical recycling compatibility under extended producer responsibility frameworks.
South Africa's National Environmental Management Waste Act and Department of Forestry, Fisheries and Environment regulations mandate extended producer responsibility schemes that reshape material choices toward recyclable mono-polymer constructions. BIS-equivalent technical standards and industry association protocols govern food-contact migration limits and pharmaceutical packaging integrity requirements. SEDA and DTI industrial policy incentives influence capital allocation decisions for localization and recycling infrastructure. Stakeholders must monitor EPR fee structures and recyclate content thresholds as these mechanisms will determine competitive cost positioning and product qualification access across the value chain.
Market Dynamics
Extended producer responsibility schemes under South Africa's National Environmental Management Waste Act are restructuring material specifications across rigid plastic packaging formats, forcing converters toward mono-polymer designs and verified recyclate content.
Growth Catalysts
- EPR regulatory mandates:The Department of Forestry, Fisheries and Environment's extended producer responsibility framework compels brand owners to fund collection infrastructure, creating guaranteed offtake for post-consumer recyclate streams.
- Hot-fill application expansion:Polypropylene's heat resistance properties are capturing share in ready-to-drink beverage and prepared food segments where thermal stability extends shelf life without barrier coatings.
- Gauteng converter concentration:The province's clustering of extrusion and thermoforming capacity reduces logistics costs for beverage and pharmaceutical clients distributing through Johannesburg and Pretoria logistics corridors.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices track international oil and naphtha benchmarks, compressing converter margins during upstream commodity spikes.
- Mechanical recycling yield limits:Multi-layer barrier films and metallized decorations contaminate post-consumer waste streams, reducing usable recyclate volumes below EPR compliance thresholds.
- Import parity pricing pressure:Asian PET preform and closure imports undercut domestic blow molding operations on large-volume beverage contracts.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments can process contaminated flexible and rigid waste streams currently rejected by mechanical sorting facilities.
- Pharmaceutical serialization compliance:Track-and-trace mandates for secondary packaging create demand for molded containers with integrated RFID or QR code authentication features.
- Western Cape aquaculture logistics:Insulated fish boxes and live-harvest containers for abalone and trout exports represent an underdeveloped application segment with premium pricing tolerance.
Industry Challenges
- Polymer compounding technical deficit:Formulation expertise for high-performance recycled-content resins remains concentrated at Mpact Group and select multinational compounders.
- EPR scheme administration complexity:Producers must navigate fee structures, reporting protocols, and third-party auditor verification timelines that vary across packaging format categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Rigid Plastic Packaging Market |
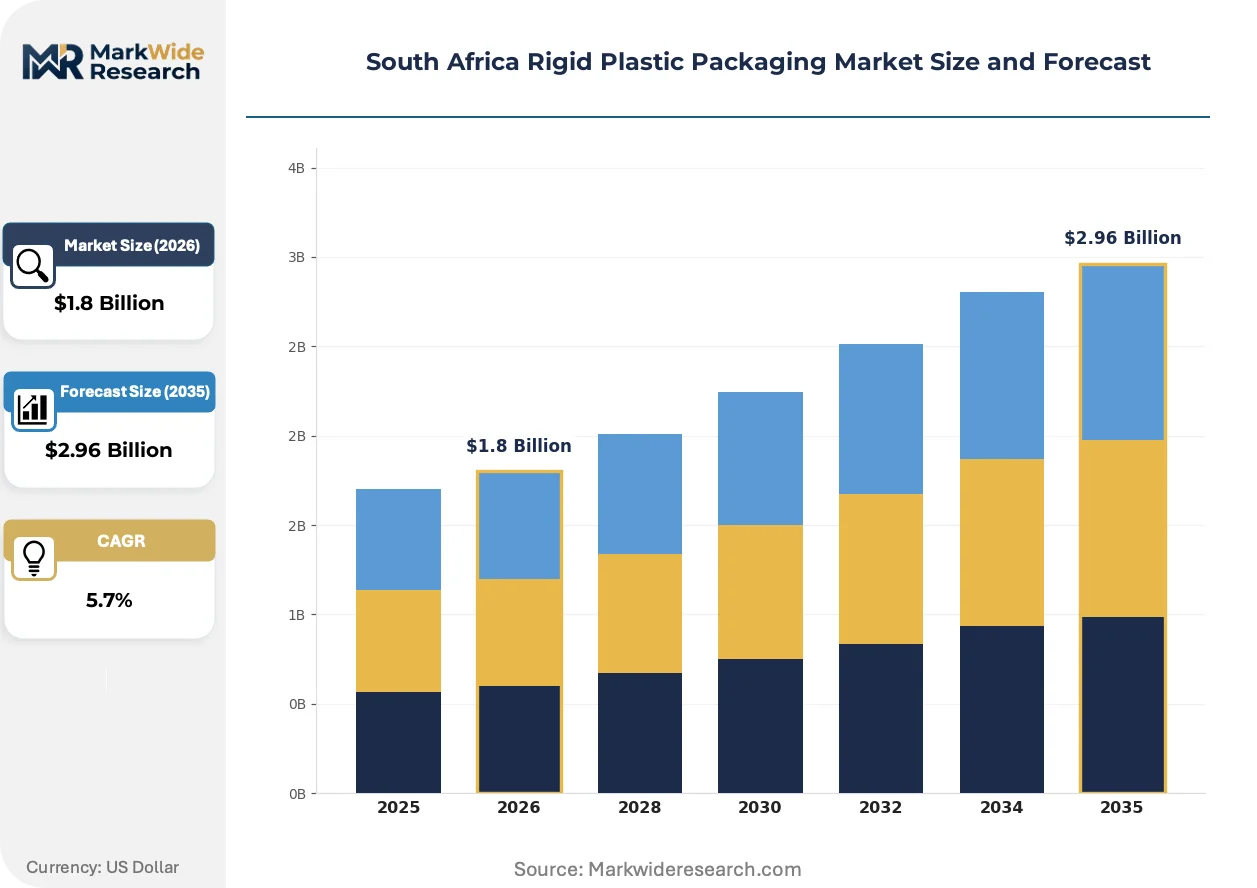
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Application: Food, Beverages, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, Polyethylene Terephthalate, Polystyrene End User: Food & Beverage Industry, Healthcare Sector, Consumer Goods, Electronics |
| Companies Covered | Mpact Group, Polyoak Packaging Group Pty Ltd, Alpla Group, Amcor GmbH, Berry Global Inc., Nampak Rigid Plastics, Bowler Packaging, Silafrica, PXD Plastics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Rigid Plastic Packaging Market Trends and Innovations
Digital printing and smart packaging integration are redefining brand-consumer interaction points, while regulatory pressure on single-use formats accelerates material science investment across the South African converter base.
Mono-material polyethylene terephthalate structures are decomposing multi-layer barrier constructions previously standard in condiment and sauce bottles. Retail brand owners in the prepared foods segment are specifying these simplified formats to meet recyclability claims. The shift is decomposing legacy co-extrusion equipment valuations and redirecting capital toward injection stretch blow molding lines with in-house recycled flake processing.
South Africa's National Environmental Management Waste Act amendments tighten design-for-recycling standards and mandate minimum post-consumer recycled content thresholds. The regulations force reformulation of colored and opaque containers that previously relied on virgin pigment systems. Food and beverage multinationals operating in the Western Cape and KwaZulu-Natal are accelerating supplier qualification audits to secure compliant packaging ahead of enforcement deadlines.
Direct-to-retailer procurement contracts are displacing traditional distributor networks for standard bottle and jar formats. Large supermarket chains in Gauteng and the Western Cape are consolidating supplier panels and negotiating volume commitments with tier-one converters. This concentration is most visible in private-label beverage and household chemical segments where specification standardization reduces SKU complexity across distribution centers.
South Africa Rigid Plastic Packaging Market Segmentation
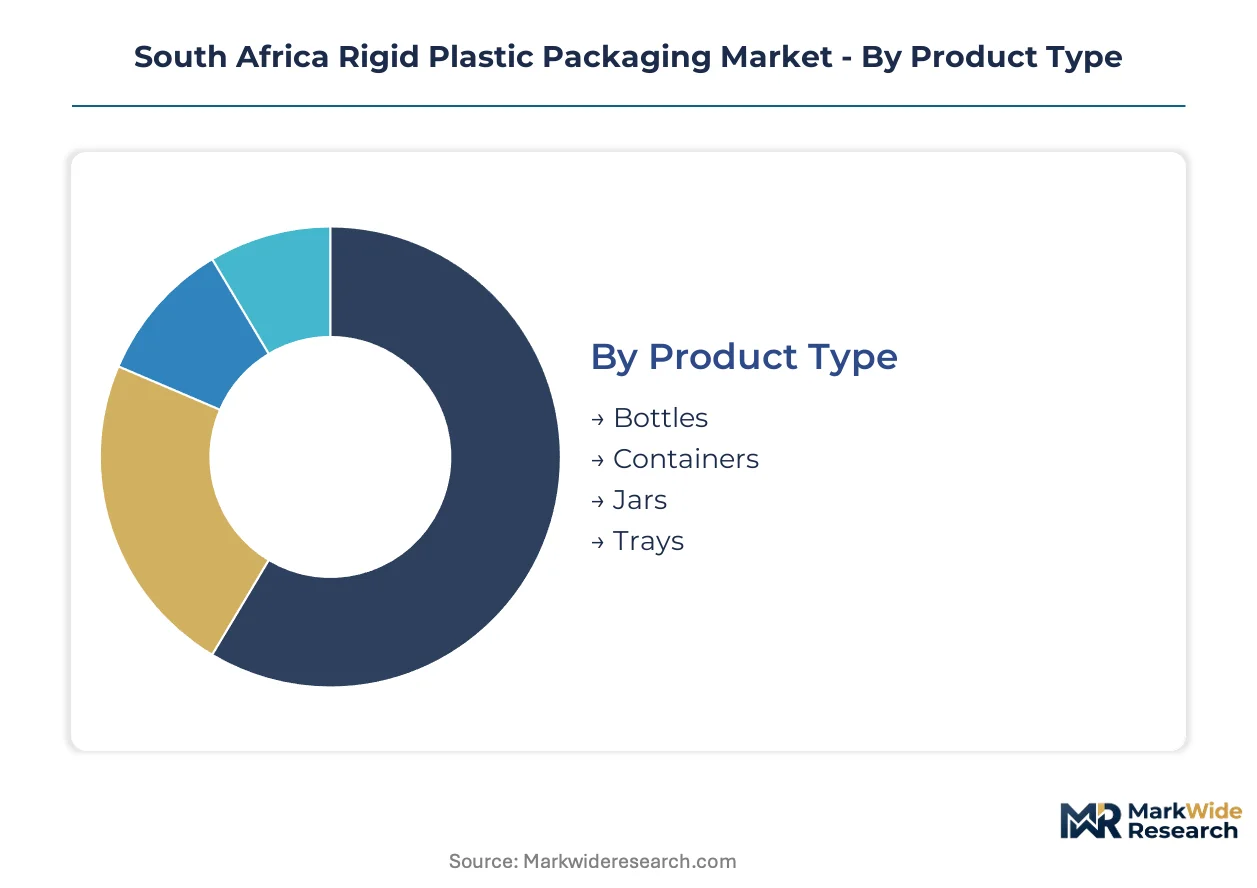
Rigid plastic packaging segmentation in South Africa reflects divergent demand drivers across domestic consumption and export-oriented supply chains. Material specifications and format choices vary sharply between food-contact applications governed by local EPR mandates and pharmaceutical segments serving regional export markets.
Product Type:
Domestic beverage and food manufacturers drive volume concentration in Gauteng and the Western Cape, while specialized container formats serve niche export applications in aquaculture and horticulture.
- Bottles:Injection stretch blow-molded PET structures dominate carbonated soft drink and water applications. Mpact Group and Nampak Rigid Plastics anchor supply to Coca-Cola Beverages South Africa and PepsiCo bottling operations in Johannesburg and Durban corridors.
- Containers:Extrusion blow-molded HDPE vessels serve household chemical and lubricant segments. Demand clusters around Pretoria industrial zones where Unilever and Reckitt Benckiser operate formulation and filling plants.
- Jars:Wide-mouth polypropylene containers target prepared foods and condiments. Polyoak Packaging Group supplies heat-resistant formats for hot-fill sauce applications meeting extended shelf life requirements.
- Trays:Thermoformed PET and PP structures capture fresh protein and ready-meal segments. Modern retail expansion in Cape Town and Port Elizabeth drives specification for modified atmosphere packaging.
Bottles hold the largest share; momentum sits with trays as fresh food retail penetration deepens.
Application:
Cost tier differentiation separates commodity food packaging from premium pharmaceutical formats requiring compliance investments.
- Food:Mono-polymer PP and PET constructions replace multi-layer barriers under National Environmental Management Waste Act design-for-recycling mandates. Margins compress as EPR fees and recyclate content thresholds raise input costs.
- Beverages:PET preform and closure systems face import parity pressure from Asian suppliers. Domestic blow molders defend position through proximity logistics and customized neck finish specifications.
- Pharmaceuticals:Child-resistant and senior-friendly closure systems command premium pricing. Compliance with the South African Health Products Regulatory Authority serialization requirements drives molded-in authentication features.
- Household Products:HDPE bottles and trigger sprayers for cleaning chemicals compete on volume scale. Private-label concentration among Massmart and Shoprite Holdings squeezes converter margins.
Food commands volume leadership; pharmaceuticals deliver the steepest expansion trajectory as serialization mandates take effect.
Material:
Supply concentration in Secunda petrochemical complexes shapes converter procurement economics and polymer availability.
- Polyethylene:HDPE and LDPE grades serve blow-molded containers and flexible lid applications. Sasol's Secunda operations provide domestic feedstock, though naphtha-linked pricing tracks volatile international benchmarks.
- Polypropylene:Homopolymer and random copolymer resins enable hot-fill and microwaveable applications. Mechanical recycling compatibility under extended producer responsibility frameworks accelerates specification for food-contact grades.
- Polyethylene Terephthalate:Bottle-grade PET serves beverage preform and thermoformed tray segments. Import dependency for purified terephthalic acid exposes converters to currency and shipping cost fluctuations.
- Polystyrene:General purpose and high-impact grades retreat in food-contact applications due to recyclability concerns. Residual demand concentrates in electronics protective packaging and pharmaceutical secondary containers.
Polyethylene Terephthalate dominates by tonnage; polypropylene gains share fastest through heat-resistant application expansion.
End User:
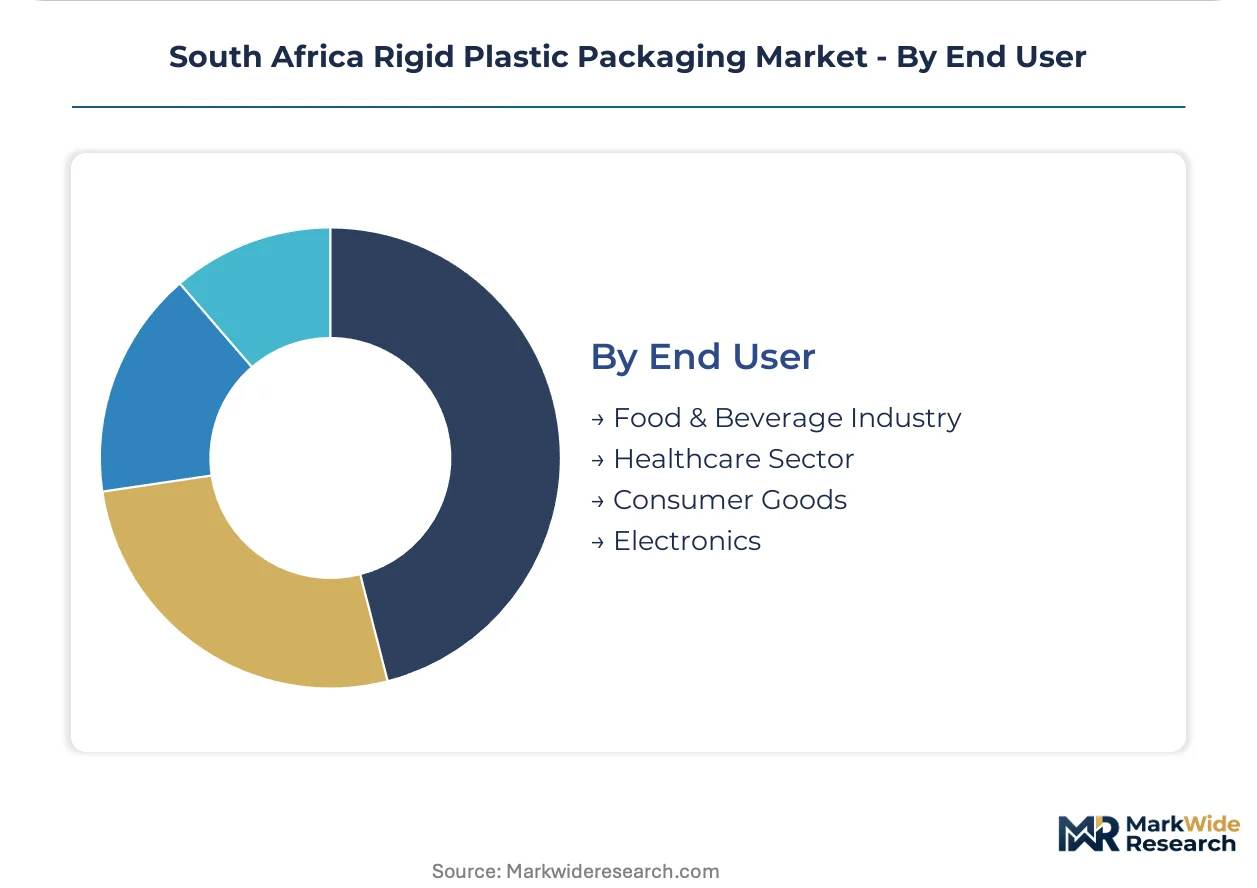
Customer type fragmentation separates multinational procurement standardization from mid-tier domestic manufacturer flexibility requirements.
- Food & Beverage Industry:Integrated converters with captive recycling operations secure preferred supplier status. Direct-to-retailer contracting displaces distributor networks for high-volume beverage and private-label formats.
- Healthcare Sector:Pharmaceutical manufacturers demand batch traceability and tamper-evidence certification. Compliance audits intensify as the South African Health Products Regulatory Authority tightens secondary packaging integrity standards.
- Consumer Goods:Personal care and home care brands balance shelf differentiation against EPR cost recovery. Digital printing enables short-run customization for promotional and seasonal variants.
- Electronics:Anti-static and cushioning applications for mobile device distribution represent a contracting segment. Polystyrene foam replacement by molded pulp and corrugated alternatives accelerates format decline.
Food & Beverage Industry anchors demand volume; healthcare sector offers the strongest pricing power as regulatory barriers limit supplier mobility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province consumes rigid plastic packaging differently from coastal regions, prioritizing beverage preforms and household chemical containers over export-oriented fish boxes and horticultural trays that dominate Western Cape demand patterns.
Gauteng
Johannesburg and Pretoria logistics corridors concentrate converter capacity for carbonated soft drinks and cleaning chemicals. The National Environmental Management Waste Act mandates extended producer responsibility fees that reshape procurement decisions by Coca-Cola Beverages South Africa and PepsiCo bottling operations. The East Rand industrial zone hosts extrusion blow molding clusters serving Unilever and Reckitt Benckiser formulation plants.
Western Cape
Cape Town's modern retail expansion drives thermoformed tray demand for fresh protein and prepared meals. Provincial environmental regulations align with national EPR frameworks but impose stricter design-for-recycling timelines on food-contact packaging. The Paarl-Stellenbosch corridor anchors wine industry bottle supply chains alongside emerging aquaculture logistics for abalone exports.
KwaZulu-Natal
Durban's port infrastructure positions the province as import gateway for purified terephthalic acid and Asian PET preform competition. The Department of Forestry, Fisheries and Environment enforces coastal pollution controls that accelerate mono-polymer adoption in beverage packaging. The Pinetown-New Germany industrial belt concentrates injection stretch blow molding for regional beverage distribution.
Eastern Cape
Port Elizabeth retail modernization lags Gauteng and Western Cape, constraining tray format penetration in fresh food segments. National waste act compliance deadlines pressure mid-tier converters to upgrade mechanical recycling compatibility. The Coega Special Economic Zone attracts packaging investment targeting automotive and agro-processing export corridors.
South Africa Rigid Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling captive recycling and extrusion assets while downstream players compete on format specialization and regional logistics proximity. The market structure rewards backward integration into post-consumer waste collection and flake processing, as EPR mandates guarantee offtake volumes for recyclate streams. Three archetypes dominate: integrated resin-to-package converters with circular economy platforms, format-specific specialists in closures and jars, and multinational preform suppliers defending position through scale economies. Competitive moves center on M&A to secure recycling capacity and strategic partnerships with beverage brand owners for long-term volume commitments.
Among South Africa-based integrated groups, Mpact Group and Nampak Rigid Plastics exemplify the circular-economy archetype through combined recycling and manufacturing operations. Polyoak Packaging Group Pty Ltd occupies a position within the format-specialist tier. International players including Alpla Group and Amcor GmbH represent the multinational scale-driven segment, leveraging global resin procurement and technology transfer to serve beverage multinationals operating across Southern Africa.
| Leading Market Players |
|---|
| Mpact Group |
| Polyoak Packaging Group Pty Ltd |
| Alpla Group |
| Amcor GmbH |
| Berry Global Inc. |
| Nampak Rigid Plastics |
| Bowler Packaging |
| Silafrica |
| PXD Plastics |
| Others |
Pricing and Supply Chain Analysis
Polypropylene's displacement of multi-layer PET constructions in hot-fill sauce applications redraws converter procurement maps from Secunda petrochemical complexes toward mechanical recycling hubs in Gauteng, simultaneously compressing virgin resin premiums and elevating recyclate-linked contract values. The Department of Forestry, Fisheries and Environment's extended producer responsibility fees now embed directly into converter pricing models, forcing brand owners to absorb or pass through recyclate content premiums.
Pricing Analysis
Long-term offtake agreements dominate converter-brand relationships, with beverage multinationals locking in polyethylene terephthalate preform volumes across 24-36 month horizons to hedge Sasol naphtha-linked resin volatility. Price differentiation hinges on recyclate certification grade and volume scale tiers, with EPR-compliant mono-polymer formats commanding modest premiums over legacy multi-layer alternatives. Cost compression in standard HDPE household chemical containers intensifies as private-label concentration at Massmart and Shoprite Holdings squeezes converter margins. Mid-tier domestic manufacturers exhibit highest price sensitivity, while pharmaceutical serialization-compliant formats demonstrate inelastic demand.
Supply Chain Analysis
Strategic resin stockpiling prevails among integrated converters, with Mpact Group and Nampak Rigid Plastics maintaining 6-8 week polypropylene and polyethylene inventories to buffer Secunda supply disruptions and currency-driven import parity swings. Raw material sourcing draws from domestic Sasol production and imported purified terephthalic acid via Durban port corridors, with mechanical recycling flake increasingly substituting virgin feedstock. Single-source vulnerability concentrates in bottle-grade PET resin dependent on Asian PTA shipments. Distribution runs through Johannesburg-Pretoria logistics clusters for Gauteng beverage and chemical clients, with Cape Town and Durban serving coastal retail and export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise for high-performance recycled-content resins remains bottlenecked at a handful of integrated compounders, creating asymmetric returns for players that solve polymer compounding technical deficits ahead of National Environmental Management Waste Act enforcement deadlines.
For Market Incumbents: Secure mechanical recycling capacity acquisitions in Gauteng and Western Cape corridors to guarantee EPR-compliant feedstock volumes ahead of compliance threshold escalations. Deepen backward integration into post-consumer waste collection partnerships with metropolitan municipalities, defending position against Asian PET preform import parity pressure through proximity logistics and customized neck finish specifications. For New Entrants and Emerging Players: South African Health Products Regulatory Authority serialization fast-tracks offer the most penetrable regulatory pathway, enabling qualification for pharmaceutical secondary packaging with integrated authentication features. Target Western Cape aquaculture logistics for insulated fish boxes and live-harvest containers, where abalone and trout export growth outpaces established converter attention. Pursue direct-to-retailer procurement bypass of traditional distributor networks for private-label beverage formats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier blow molders lacking captive recycling infrastructure, presenting consolidation targets for platforms seeking EPR scheme administrative capabilities. Five-to-ten year viability favors converters with demonstrated mono-polymer reformulation track records and verified recyclate content supply agreements. Monitor Department of Forestry, Fisheries and Environment EPR fee structure announcements as the critical inflection signal for competitive cost positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis investments process contaminated waste streams rejected by mechanical sorting facilities. |
| Backward Integration into Flake Processing | In-house recyclate processing secures feedstock continuity under extended producer responsibility mandates. |
| Pharmaceutical Serialization Compliance | Track-and-trace mandates create demand for molded containers with integrated RFID authentication features. |
| Direct-to-Retailer Contracting | Supermarket chain consolidation reduces SKU complexity across Gauteng and Western Cape distribution centers. |
| Mono-Polymer Format Transition | Simplified PET constructions replace multi-layer barriers to meet National Environmental Management Waste Act recyclability claims. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations directors, brand owner procurement leads, recycling facility managers, and Department of Forestry, Fisheries and Environment regulatory officers, and refined through secondary validation against customs trade records, industry association technical protocols, SEC filings of listed packaging groups, and SEDA industrial policy incentive disclosures. Bottom-up volume modeling from individual converter capacity and utilization rates was triangulated against top-down demand estimates from beverage and food manufacturer fill volumes.
Variance decomposition across material, format, and end-use dimensions structured the analytical framework, with growth trajectories derived from elasticity-adjusted demand projections and substitution dynamics between virgin and recycled resin grades over the projection horizon. Segmentation modeling captured product type, application, material composition, and end-user industry verticals. Forecast inputs incorporated EPR fee structure scenarios, petrochemical feedstock price bands, and import parity threshold triggers.
The analysis sits within stated boundaries; outcomes outside sustained EPR enforcement, stable mechanical recycling yield improvements, or continued modern retail expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and resin technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Cast Films Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
North America Plastic Bottles Market