
 France Plastic Bottles Market | 2026-2036
France Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
France Plastic Bottles Market Insights
Personal care end-use demand is shifting toward lightweight, recyclable bottle formats as French cosmetics houses reformulate packaging roadmaps. Alpla France SAS leverages its blow-molding expertise to serve regional beauty brands with rPET solutions. Berry Global Inc. anchors substantial capacity in personal care and household segments through specialized barrier technologies. Amcor Group GmbH competes on pharmaceutical-grade compliance and controlled-atmosphere designs for sensitive formulations.
France plastic bottles are hollow thermoplastic containers typically extrusion- or injection-blow-molded from polyethylene terephthalate, high-density polyethylene, or polypropylene resins, with wall thicknesses calibrated for carbonation retention, chemical resistance, or collapsible dispensing. PET dominates beverage applications due to its clarity, barrier performance, and established recycling stream via France's sélectif collection infrastructure. High-density polyethylene sustains growth in household and industrial segments where chemical compatibility and cost efficiency outweigh optical requirements. The 250ml to 500ml capacity band captures premium personal care volumes, while above-1L formats serve bulk household and institutional buyers.
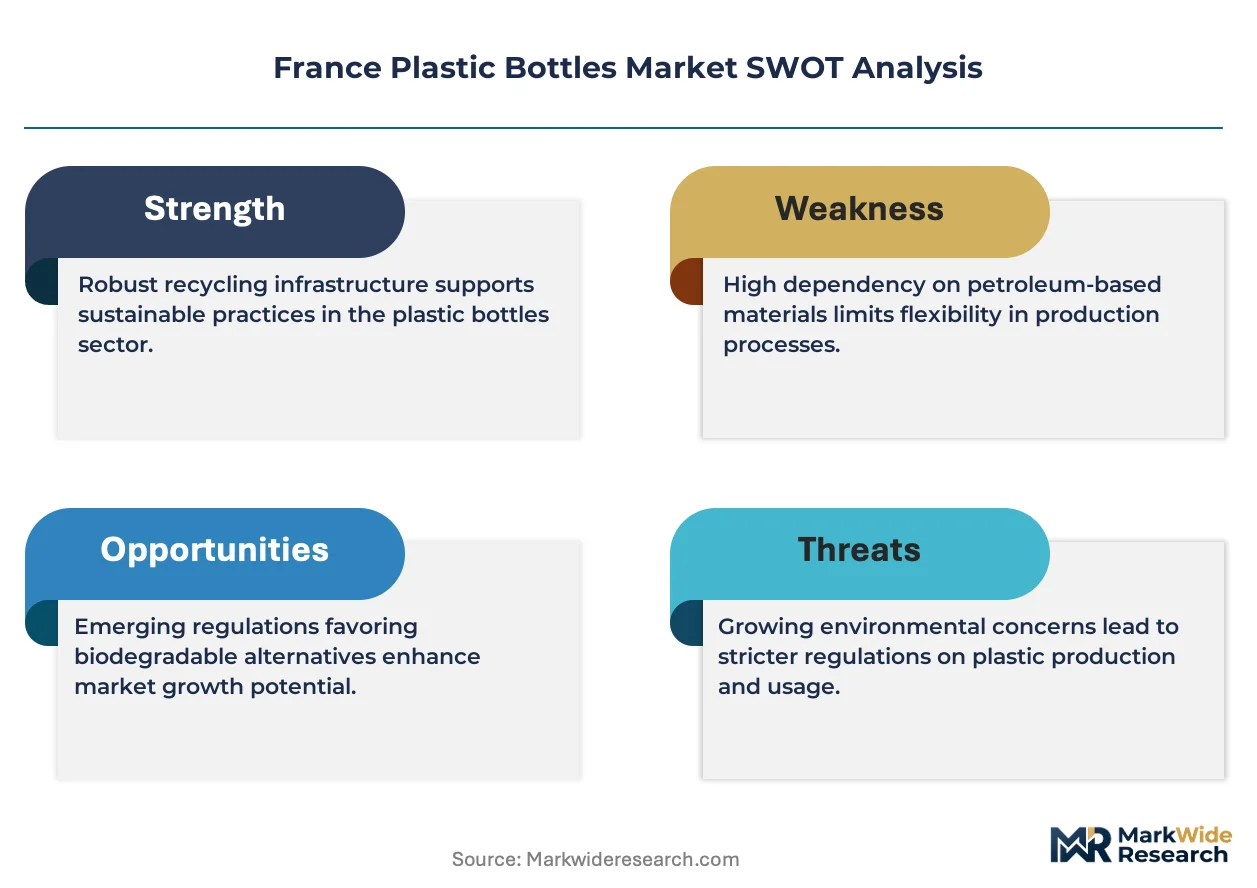
France's AGEC law and extended producer responsibility frameworks enforced by ADEME reshape material choices and minimum recycled content thresholds. ECHA REACH compliance and EU Single-Use Plastics Directive restrictions on certain formats further constrain design freedom and accelerate substitution toward reusable or highly recyclable structures. Stakeholders must monitor forthcoming French packaging deposit scheme expansions and EU PPWR implementation timelines to align capital allocation with compliance-driven demand migration.
Market Dynamics
France's AGEC anti-waste law and extended producer responsibility frameworks enforced by ADEME are compressing design cycles and forcing material substitutions across personal care, beverage, and pharmaceutical packaging tiers.
Growth Catalysts
- rPET infrastructure maturation:France's sélectif collection stream now delivers food-grade recycled flake at scale, enabling cosmetic houses to meet AGEC-mandated recycled content floors without supply disruption.
- Lightweighting protocols:Blow-molding equipment advances allow wall-thickness reduction of 15-20% in standard PET formats, cutting resin consumption per unit while maintaining carbonation barrier performance.
- Île-de-France concentration:Paris-region headquarters of L'Oréal, Clarins, and Sanofi generate dense demand clusters that justify dedicated production lines and shorten logistics loops for just-in-time beauty launches.
Market Restraints
- rPET price volatility:Baled bottle scrap trades at premiums to virgin PET during collection shortfalls, squeezing converters who cannot pass through cost spikes to locked-in personal care contracts.
- Barrier technology limitations:Monolayer HDPE bottles fail oxygen and CO2 retention tests required for sensitive nutraceuticals, forcing reliance on costlier multilayer or coated alternatives.
- EU Single-Use Plastics Directive friction:Restrictions on certain single-use formats eliminate design options for travel-size and sample bottles, compressing SKU diversity in the 50-100ml band.
Strategic Opportunities
- Deposit scheme expansion:France's forthcoming packaging deposit system will capture post-consumer PET at higher purity grades than curbside collection, creating captive feedstock pools for bottle-to-bottle recycling.
- Refill station infrastructure:Bulk dispensing formats for household cleaners and personal care are penetrating Carrefour and Monoprix locations, opening demand for durable 1-5L returnable bottles.
- Pharmaceutical compliance specialization:ANSM serialization requirements and EMA Annex 1 sterile packaging rules favor converters with validated cleanroom blow-molding capacity for parenteral and ophthalmic applications.
Industry Challenges
- Blow-molding technician scarcity:Regional vocational programs have not kept pace with servo-electric machine complexity, lengthening commissioning timelines for new high-speed lines in Normandy and Rhône-Alpes.
- Legacy mold asset stranding:Converters face write-downs on aluminum and steel tooling optimized for virgin-only resins that cannot process rPET's viscosity variations without retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Plastic Bottles Market |
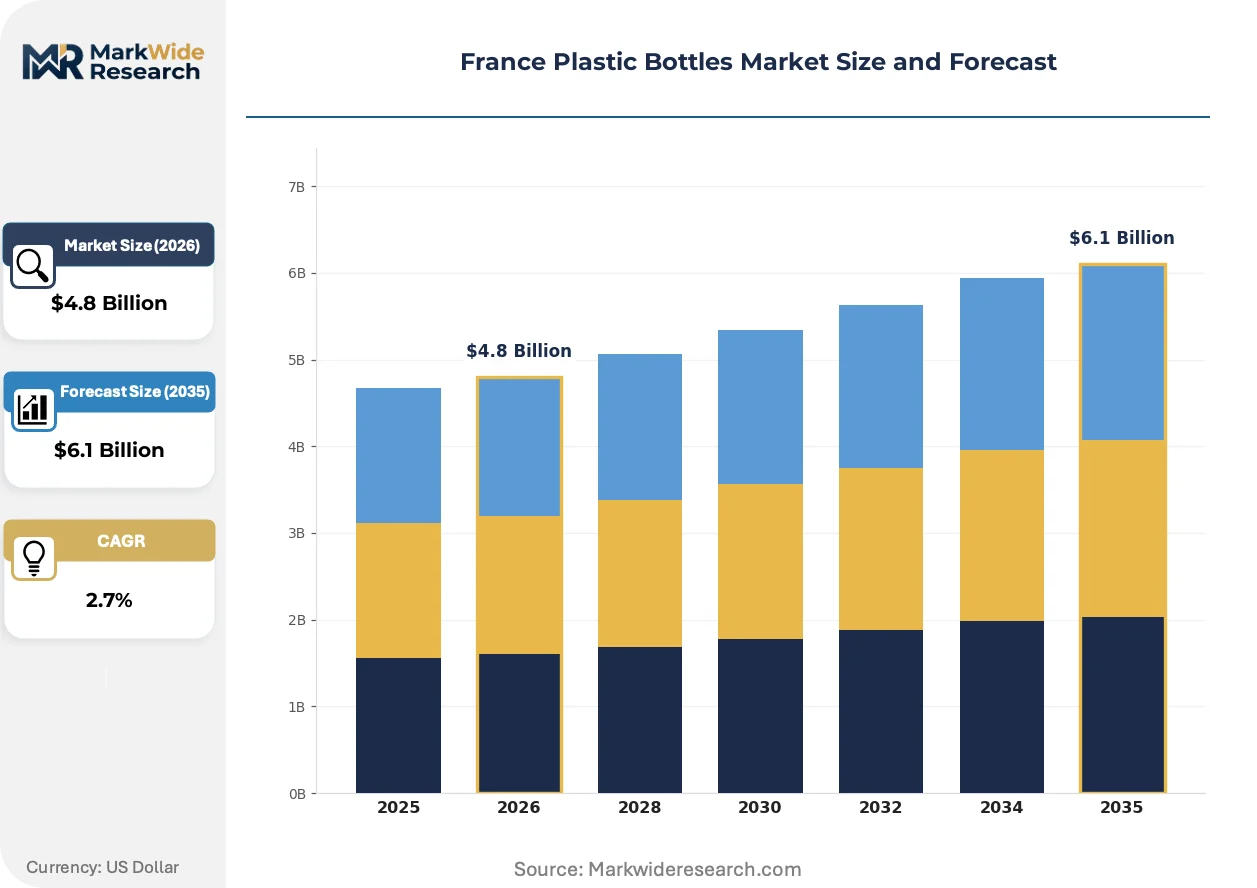
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Others End User: Food & Beverage, Personal Care, Household Products, Industrial Capacity: Less than 250ml, 250ml to 500ml, 500ml to 1L, Above 1L Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Bulk Suppliers |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Aptar Group Inc., Alpla France SAS, PDG Plastiques, Frapak Packaging, Axium Packaging, Retal Group, ActiPack SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Plastic Bottles Market Trends and Innovations
Material science advances and compliance automation are reconfiguring competitive advantage in French plastic bottle manufacturing, with sustainability verification and production flexibility emerging as decisive capabilities.
rPET is consolidating its position as the default material for premium personal care bottles. L'Oréal and Clarins have mandated post-consumer content minimums across their Paris-developed skincare lines. This consolidation is compressing virgin PET demand in the 250-500ml decorative segment and forcing resin suppliers to secure long-term bale contracts.
ADEME's enforcement of AGEC recycled content thresholds is accelerating validation investments. Converters must document mass-balance chains from collection through reprocessing to claim regulatory compliance. Personal care brands with September product launch cycles face the tightest certification timelines as third-party auditors queue for facility inspections.
Beauty houses are unbundling their packaging procurement from traditional full-service converters. Direct relationships with specialized blow-molders in Normandy and the Rhône-Alpes plastics corridor are displacing tier-one distributor intermediaries. This pattern is most pronounced among mid-sized French cosmeceutical brands seeking faster mold modification cycles for limited-edition releases.
France Plastic Bottles Market Segmentation
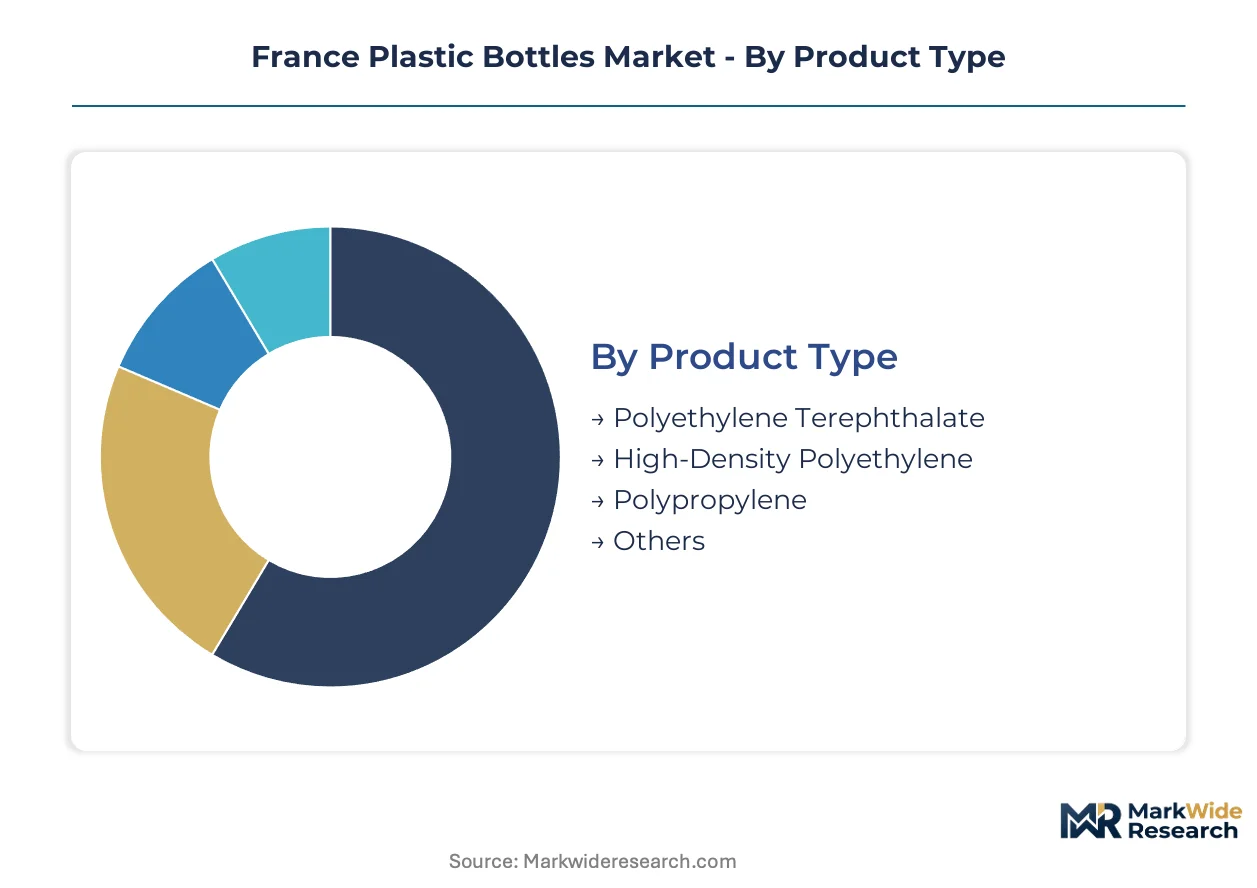
France plastic bottle demand fragments across material chemistry, end-use specifications, and capacity formats that each carry distinct compliance obligations under AGEC law. Converters must align production assets with the customization intensity each segment requires.
Product Type:
Standardization dominates commodity resin grades while specialty polymers demand formulation partnerships with brand technical teams.
- Polyethylene Terephthalate:Clear, biaxially oriented bottles deliver carbonation barrier performance and optical clarity for premium personal care. L'Oréal and Clarins procurement concentrates in Île-de-France for 250-500ml skincare formats where recycled content mandates bite hardest.
- High-Density Polyethylene:Opaque, chemically resistant containers serve household cleaners and industrial concentrates. Rhône-Alpes converters supply institutional buyers with cost-calibrated wall thicknesses that prioritize chemical compatibility over aesthetics.
- Polypropylene:Heat-resistant bottles withstand hot-fill and retort applications for specialized food segments. Normandy blow-molders target dairy and prepared meal distributors with clarified random copolymer grades.
- Others:Bioplastics and barrier-enhanced multilayer structures address niche pharmaceutical and organic food certifications. Limited volume runs through pilot lines in Brittany and Pays de la Loire.
Most installed capacity flows through Polyethylene Terephthalate. Expansion is steepest in High-Density Polyethylene.
End User:
Regulatory pressure intensity varies sharply across buyer categories, with personal care facing the strictest recycled content floors.
- Food & Beverage:EFSA-compliant rPET bottles for mineral water and soft drinks dominate volume. Sélectif collection infrastructure in Provence-Alpes-Côte d'Azur feeds food-grade reprocessing for this segment's safety requirements.
- Personal Care:Decorative bottles with metallized finishes and custom shoulder designs command premium positioning. Paris-region headquarters of major beauty houses drive just-in-time procurement with compressed certification timelines.
- Household Products:Functional HDPE containers for bleach, detergents, and surface cleaners prioritize cost efficiency over visual differentiation. Carrefour and Monoprix private-label volumes concentrate demand.
- Industrial:Heavy-wall drums and intermediate bulk containers serve chemical distributors and agricultural formulators. Lower regulatory scrutiny permits higher recycled content inclusion without aesthetic penalty.
Food & Beverage absorbs the largest production share. Personal Care is climbing the fastest as AGEC thresholds tighten.
Capacity:
Volume economics favor mid-range formats while miniatures and bulk containers occupy opposite ends of the automation spectrum.
- Less than 250ml:Travel-size and sample bottles face EU Single-Use Plastics Directive restrictions that compress SKU diversity. Clarins and smaller cosmeceutical brands still demand limited runs for promotional campaigns.
- 250ml to 500ml:Premium personal care standard format where decorative finishing and shoulder customization justify dedicated mold investments. Île-de-France converters maintain shortest logistics loops for beauty house launches.
- 500ml to 1L:Mid-tier household and beverage applications balance material efficiency with handling ergonomics. Supermarket private-label volumes concentrate here.
- Above 1L:Bulk institutional formats and refill station containers for Carrefour's expanding dispensing infrastructure. Returnable designs require durability specifications that extend reuse cycles.
250ml to 500ml commands the densest mold utilization. Above 1L is gaining share fastest through refill station expansion.
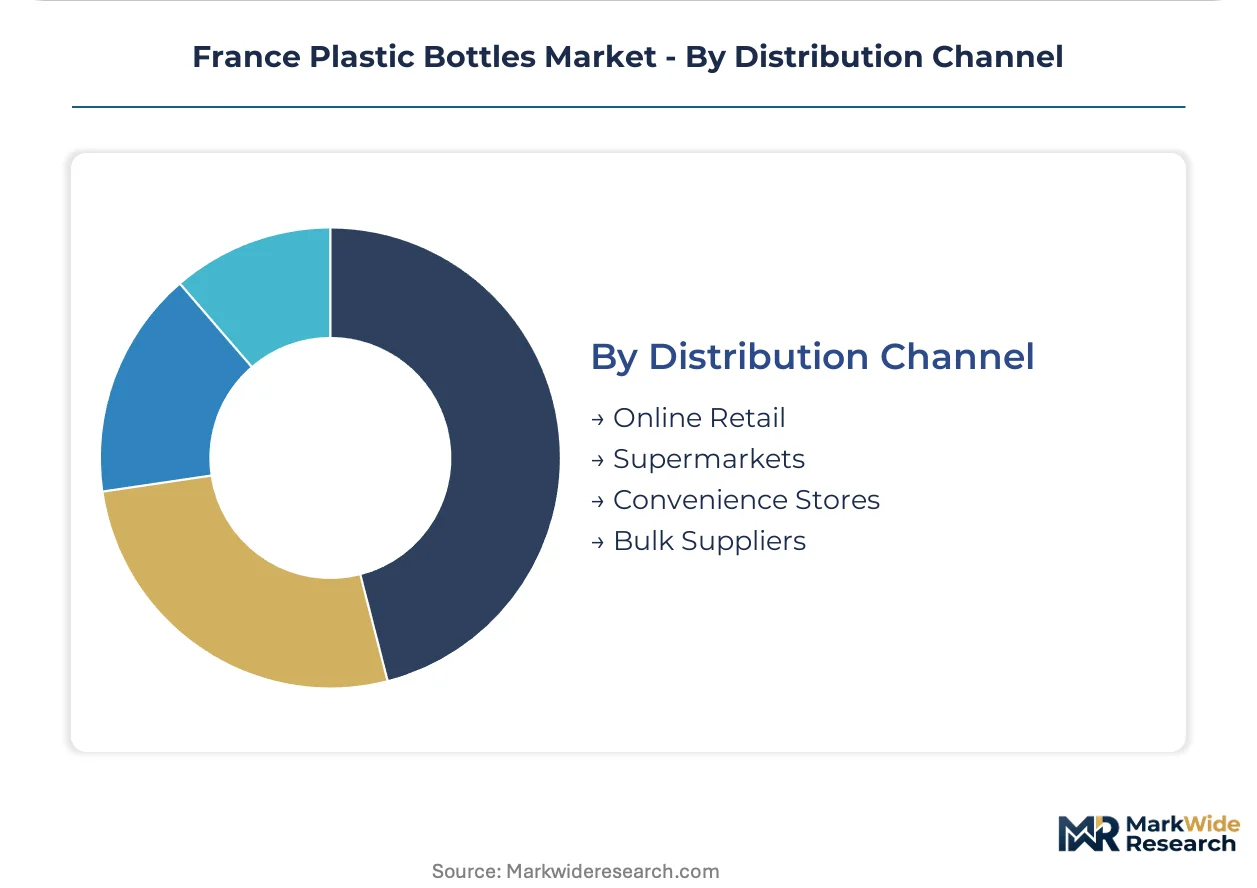
Distribution Channel:
Channel selection determines packaging specification complexity, with direct-to-consumer formats demanding higher customization than bulk supply.
- Online Retail:E-commerce-optimized bottles with leak-proof closures and crush-resistant wall designs. Amazon France and Cdiscount sellers prioritize dimensional efficiency for last-mile logistics.
- Supermarkets:High-visibility shelf presence drives decorative investment for Carrefour, E.Leclerc, and Intermarché listings. Seasonal promotional cycles require rapid mold changeover capability.
- Convenience Stores:Impulse-oriented formats with grab-and-go ergonomics and single-serve positioning. Urban Monoprix and Franprix locations favor compact 250ml configurations.
- Bulk Suppliers:Undecorated, palletized volumes for industrial and institutional buyers with minimal branding requirements. Rhône-Alpes and Normandy producers serve this channel through distributor intermediaries.
Supermarkets channel the most finished goods volume. Online Retail is expanding most quickly as fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France concentrates France's highest plastic bottle packaging demand through the Paris-region headquarters of L'Oréal, Clarins, and Sanofi. AGEC law enforcement by ADEME varies in intensity across French regions, creating differentiated compliance timelines for converters.
Île-de-France
Premium personal care brands drive dense demand for 250-500ml decorative bottles with metallized finishes. ADEME's strictest recycled content audits target beauty houses headquartered here. Dedicated production lines in Seine-et-Marne and Val-d'Oise serve just-in-time launch cycles for seasonal skincare collections.
Auvergne-Rhône-Alpes
Rhône-Alpes converters supply institutional buyers with cost-calibrated HDPE containers for household and industrial chemicals. The region's plastics corridor hosts blow-molding capacity optimized for chemical compatibility over aesthetics. Lyon-based distributors connect Normandy producers with bulk supply contracts.
Provence-Alpes-Côte d'Azur
Sélectif collection infrastructure here feeds food-grade rPET reprocessing for EFSA-compliant beverage bottles. Mineral water bottlers in the region source recycled flake at scale for AGEC-mandated content floors. Marseille logistics hubs distribute finished goods to southern European markets.
Normandy
Normandy blow-molders target dairy and prepared meal distributors with clarified random copolymer polypropylene grades. The region's vocational training gaps lengthen commissioning timelines for servo-electric machine installations. Pilot lines here test bioplastics for niche organic food certifications.
Hauts-de-France
Industrial plastic bottle demand concentrates in Hauts-de-France for agricultural formulators and chemical distributors. Lower regulatory scrutiny permits higher recycled content inclusion without aesthetic penalty. Lille-area converters serve bulk institutional buyers through distributor intermediaries.
France Plastic Bottles Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit virgin-only lines for rPET viscosity variations. The vendor base splits between integrated multinationals with barrier technology portfolios and regional specialists with agile mold modification capabilities. Three archetypes define competitive positioning: compliance-focused pharmaceutical-grade suppliers, sustainability-verified beauty packaging specialists, and cost-driven commodity converters. M&A activity and strategic partnerships for recycled feedstock security represent the dominant competitive moves reshaping market structure.
Within the integrated multinational tier, Amcor Group GmbH and Berry Global Inc. exemplify scale-driven positions anchored by specialized barrier technologies and pharmaceutical-grade compliance capabilities. Alpla France SAS represents the regional specialist archetype with blow-molding expertise concentrated in the Île-de-France beauty corridor. These three entities occupy distinct competitive vectors: Amcor on controlled-atmosphere pharmaceutical designs, Berry on personal care and household segment capacity, and Alpla on rPET solutions for regional beauty brands.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Aptar Group Inc. |
| Alpla France SAS |
| PDG Plastiques |
| Frapak Packaging |
| Axium Packaging |
| Retal Group |
| ActiPack SAS |
| Others |
Pricing and Supply Chain Analysis
AGEC-mandated recycled content floors for personal care brands are forcing converters to absorb rPET scrap premiums or retrofit virgin-only lines, compressing margins and reshaping procurement toward long-term bale contracts. This demand-side specification shift feeds directly into supply chain restructuring as converters seek captive feedstock security.
Pricing Analysis
Input-cost pass-through from volatile baled bottle scrap drives contract renegotiation cycles between converters and locked-in beauty houses. Pricing stratifies across pharmaceutical-grade barrier bottles, AGEC-compliant rPET personal care formats, and undecorated HDPE commodity containers. Cost compression in the standard PET tier intensifies because lightweighting advances cut resin consumption per unit. Private-label household buyers at Carrefour and Intermarché exhibit highest price sensitivity, while ANSM-validated pharmaceutical converters maintain lowest sensitivity due to compliance switching costs.
Supply Chain Analysis
Reverse-logistics flows through France's sélectif collection infrastructure and forthcoming deposit scheme expansion are creating captive rPET feedstock pools that reduce quality variance in bottle-to-bottle recycling. Raw material supply draws from Germany, Belgium, and domestic Provence-Alpes-Côte d'Azur reprocessing hubs for food-grade flake. Single-source vulnerability concentrates in specialized barrier resin additives sourced from limited European compounders. Distribution runs through Île-de-France just-in-time logistics loops for beauty launches and Rhône-Alpes bulk supply corridors for institutional chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in French plastic bottles rests on rPET processing efficiency gains and premium-tier pharmaceutical compliance specialization that commands price premiums over commodity converters.
For Market Incumbents: Cement feedstock security through backward integration into baled scrap collection or long-term reprocessing partnerships before ADEME tightens audit timelines. Retrofit legacy blow-molding lines for rPET viscosity tolerance to avoid asset stranding as AGEC thresholds escalate. Barrier technology R&D investment defends position against multilayer substitute entrants in sensitive nutraceutical applications. For New Entrants and Emerging Players: Enter via refill station infrastructure partnerships with Carrefour and Monoprix for durable 1-5L returnable formats where incumbent asset bases lack adaptation speed. Target Hauts-de-France industrial chemical distributors with cost-calibrated HDPE volumes where regulatory scrutiny permits higher recycled content inclusion. Direct-to-brand relationships with mid-sized cosmeceutical houses bypass entrenched distributor intermediaries. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing validated cleanroom capacity and agile mold modification capabilities for limited-edition beauty launches. The five-to-ten year viability window favors converters with documented mass-balance chains and third-party certification relationships. Monitor ADEME enforcement intensity and EU PPWR implementation pace as inflection indicators for compliance-driven demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Captive baled scrap supply secures AGEC compliance without spot market volatility exposure. |
| Cleanroom Blow-Molding Capacity Expansion | ANSM-validated production lines capture pharmaceutical-grade premium pricing from Sanofi and biologics formulators. |
| Refill Station Format Development | Durable returnable designs align with Carrefour's bulk dispensing infrastructure expansion. |
| Mass-Balance Certification Investment | Third-party audit readiness compresses procurement cycles for September beauty launch timelines. |
| Servo-Electric Line Modernization | Advanced blow-molding equipment enables 15-20% wall-thickness reduction while maintaining carbonation barriers. |
Research Methodology
Bottom-up personal care and pharmaceutical demand modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with blow-molding plant managers, procurement leads at L'Oréal and Clarins, ADEME compliance officers, and distributor channel partners combined with secondary validation from ADEME enforcement reports, ECHA REACH filings, and EU Single-Use Plastics Directive implementation tracking. Customs data on resin imports and sélectif collection throughput statistics anchored supply-side calibration.
Historical trendline analysis across material chemistry shifts, end-use specification tightening, and regional production concentration patterns informed the projection framework. Segmentation dimensions modeled include resin type, end-use vertical, capacity format, and distribution channel complexity. CAGRs derived from elasticity-adjusted demand curves and capacity utilization trajectories throughout the forecast period. Industry-specific inputs encompass rPET flake pricing volatility indices and AGEC audit timeline compression effects.
Inputs from ADEME enforcement disclosures and converter certification databases were available through the study window; gaps in forthcoming deposit scheme implementation timelines introduce uncertainty bands around refill station demand projections. Practitioners should monitor baled scrap price spreads and third-party auditor queue lengths for early signals of margin compression or compliance bottleneck formation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market