
 Poland Plastic Caps and Closures Market | 2026-2036
Poland Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Plastic Caps and Closures Market Insights
Multi-source procurement for resin and tooling is decoupling from the single-supplier legacy common among Polish converters. BERICAP Holding GmbH leverages its European mold network to sustain short-lead production for beverage clients. ALPLA Group anchors regional supply through its Polish manufacturing footprint, while Politech Sp. z o.o. competes on customized closure designs for local dairy and cosmetics brands.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polypropylene or polyethylene, designed to seal containers against contamination, leakage, and tampering across consumer and industrial packaging. Screw cap configurations retain dominant share in Polish food and beverage applications due to proven reseal reliability and line compatibility with existing filling equipment. Dispensing cap demand is expanding fastest in personal care and household products as brands prioritize controlled-dose convenience and reduced product waste.
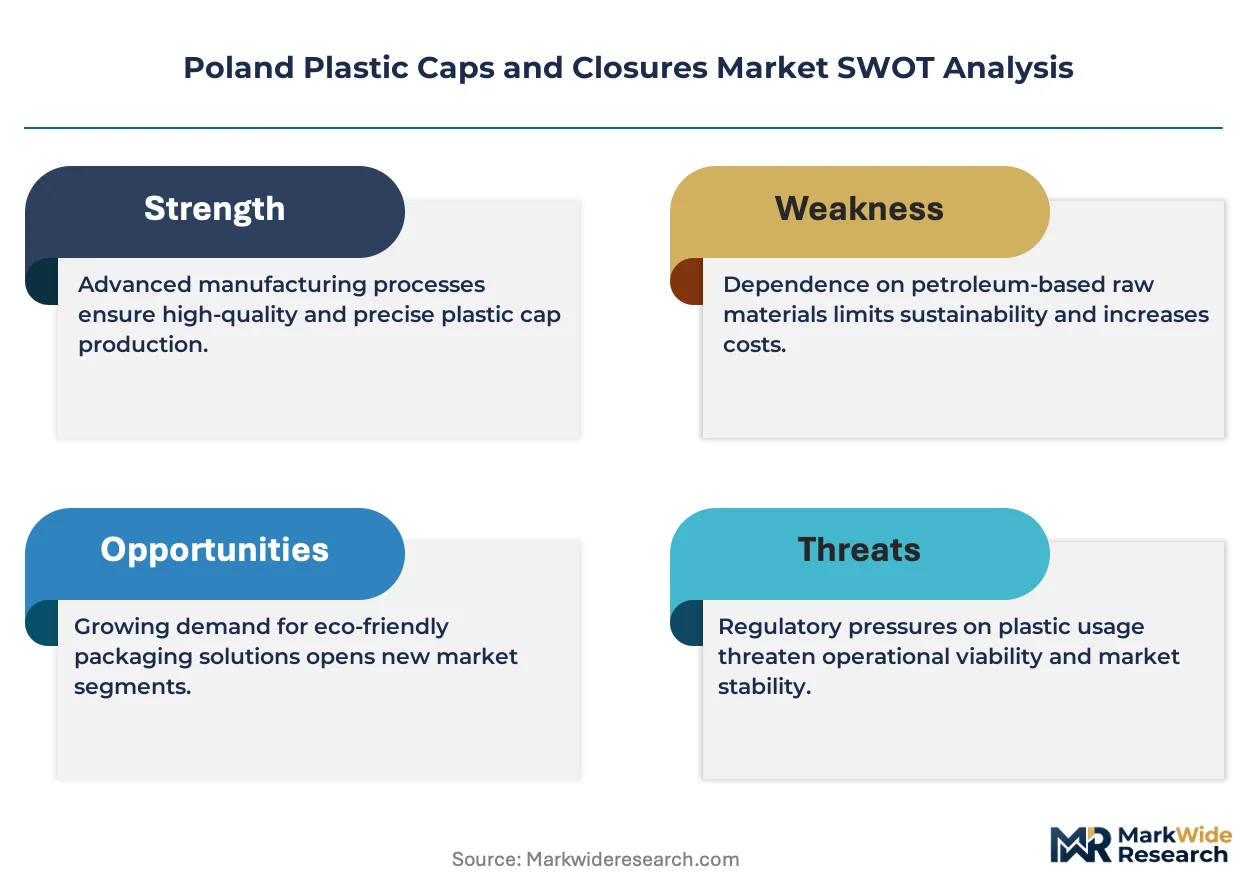
Poland's packaging sector operates under the EU Single-Use Plastics Directive, the REACH chemicals framework, and national extended producer responsibility regulations administered by the Chief Inspectorate of Environmental Protection, all of which elevate compliance costs for non-recyclable or additive-heavy formulations. The Polish Committee for Standardization and ECHA jointly influence material approvals, testing protocols, and circularity claims that determine market access for both domestic molders and imported closure systems. Stakeholders must monitor forthcoming revisions to Poland's packaging recovery targets and the EU Packaging and Packaging Waste Regulation's implementation timeline to anticipate resin specification shifts and capital allocation priorities.
Market Dynamics
Poland's plastic caps and closures sector is reconfiguring around the EU Single-Use Plastics Directive's material mandates, which are forcing converters to abandon legacy polystyrene formulations and revalidate entire production lines for recyclable polypropylene alternatives before compliance deadlines tighten.
Growth Catalysts
- REACH chemical restrictions:Poland's alignment with ECHA substance restrictions is eliminating non-compliant imported closures, creating protected demand for domestic molders who have preemptively reformulated resin blends.
- Masovia beverage corridor expansion:Bottling capacity concentration around Warsaw is generating captive demand for lightweight screw caps and dispensing closures with integrated tamper-evident bands.
- Compression molding technology:Lower energy intensity per unit versus injection molding is allowing Polish converters to absorb electricity cost volatility while maintaining margin structures.
Market Restraints
- Propylene feedstock volatility:Poland's reliance on imported polymer-grade propylene from German and Dutch crackers exposes converters to naphtha-linked price swings without captive steam cracker capacity.
- Tooling supply concentration:High-precision mold fabrication concentrates in southern German and northern Italian equipment builders, extending lead times for Polish converters seeking multi-cavity hot-runner systems.
- Mechanical recycling contamination limits:Poland's sorting infrastructure struggles to separate polypropylene closures from polyethylene bottles, depressing post-consumer recyclate quality and circularity claims.
Strategic Opportunities
- Silesia cosmetics manufacturing:Underpenetrated premium dispensing pump demand from Katowice-area skincare formulators offers margin expansion for closures with airless pump integration.
- EU Packaging and Packaging Waste Regulation:Pending recycled content mandates will create first-mover advantage for Polish molders with validated food-contact recyclate streams.
- Digital watermark traceability:Convergence of polymer marking technology with blockchain verification is enabling premium pricing for closures with embedded circularity credentials.
Industry Challenges
- Hot-runner maintenance specialization:Shortage of technicians qualified for valve-gate troubleshooting and thermal balancing is extending unplanned downtime at Polish molding facilities.
- Food-contact migration testing backlog:Certification delays at Poland's national reference laboratory for overall migration and specific migration testing are freezing new product launches for dairy and edible oil clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Plastic Caps and Closures Market |
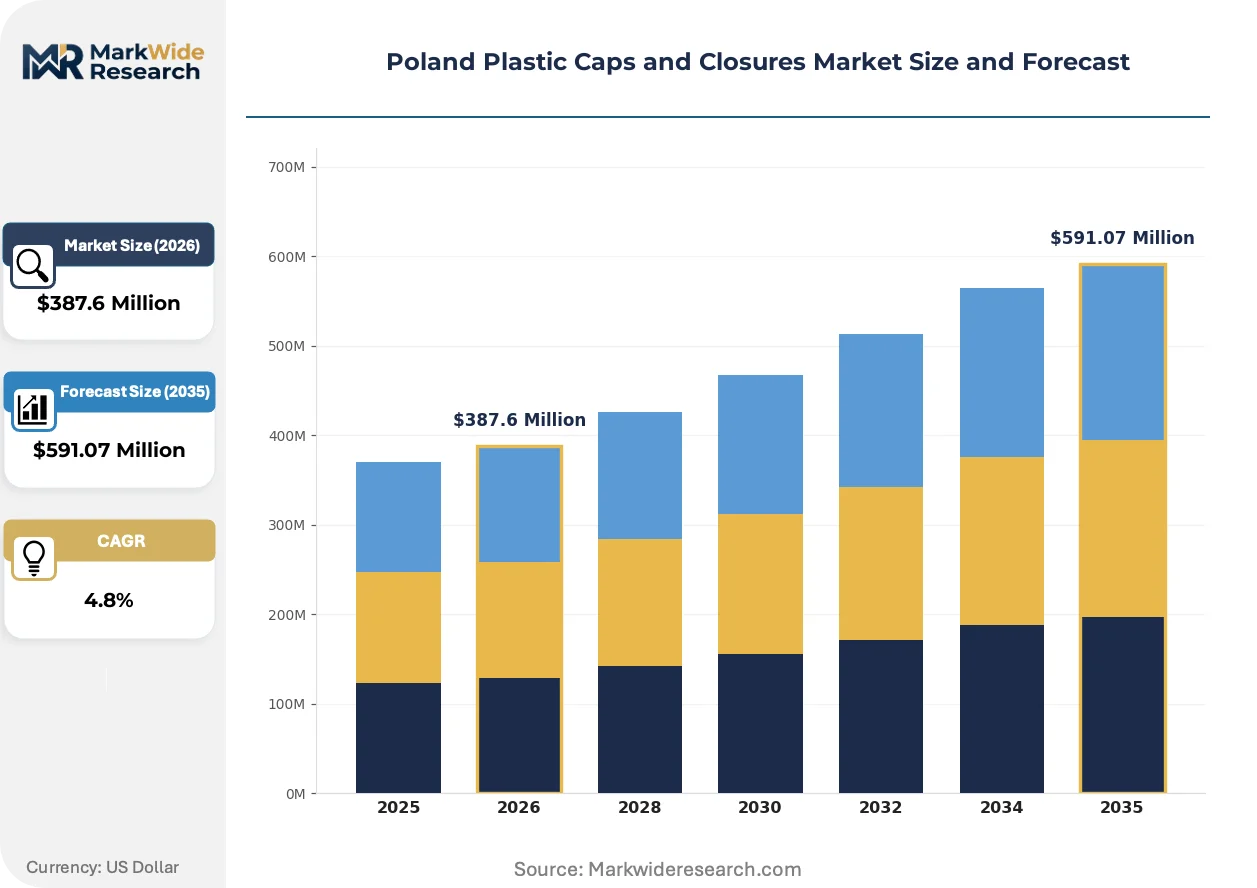
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Screw Cap, Snap-On, Dispensing Cap Material: Polypropylene, Polyethylene, PVC, PET End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Size: Child-Resistant, Large, Small, Standard |
| Companies Covered | Berry Global Inc., BERICAP Holding GmbH, UNITED CAPS LUXEMBOURG SA, Amcor Group GmbH, Guala Closures S.p.A., ALPLA Group, Tecnocap Group, Politech Sp. z o.o., Multicaps Sp. z o.o., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Plastic Caps and Closures Market Trends and Innovations
Poland's closure market is pivoting toward material-lightweighting and mono-material designs that simplify end-of-life sorting, with technology investments clustering around process efficiency and regulatory pre-compliance rather than breakthrough functionality.
All-polyethylene dispensing closures are decentralizing traditional multi-material pump assemblies by eliminating metal springs and glass balls through engineered flexural hinge designs. Personal care brands in the Masovia corridor are specifying these units for shampoo and conditioner lines. The simplification is compressing assembly steps and enabling direct-to-brand procurement without component integrators.
REACH Annex XVII restrictions on intentional microplastic additives are compelling Polish converters to eliminate slip agents and anti-static coatings from closure formulations. The regulatory pressure is elevating compliance costs for legacy additive packages. Dairy and edible oil segments are responding fastest by qualifying additive-free polypropylene grades with modified surface finishes.
Beverage bottlers are consolidating supplier panels and mandating closed-loop resin certification for all procurement lots. The concentration is displacing spot-market resin purchasing with contracted recycled-content supply agreements. Polish mineral water and soft drink producers are driving this transition most aggressively to preempt extended producer responsibility fee structures.
Poland Plastic Caps and Closures Market Segmentation
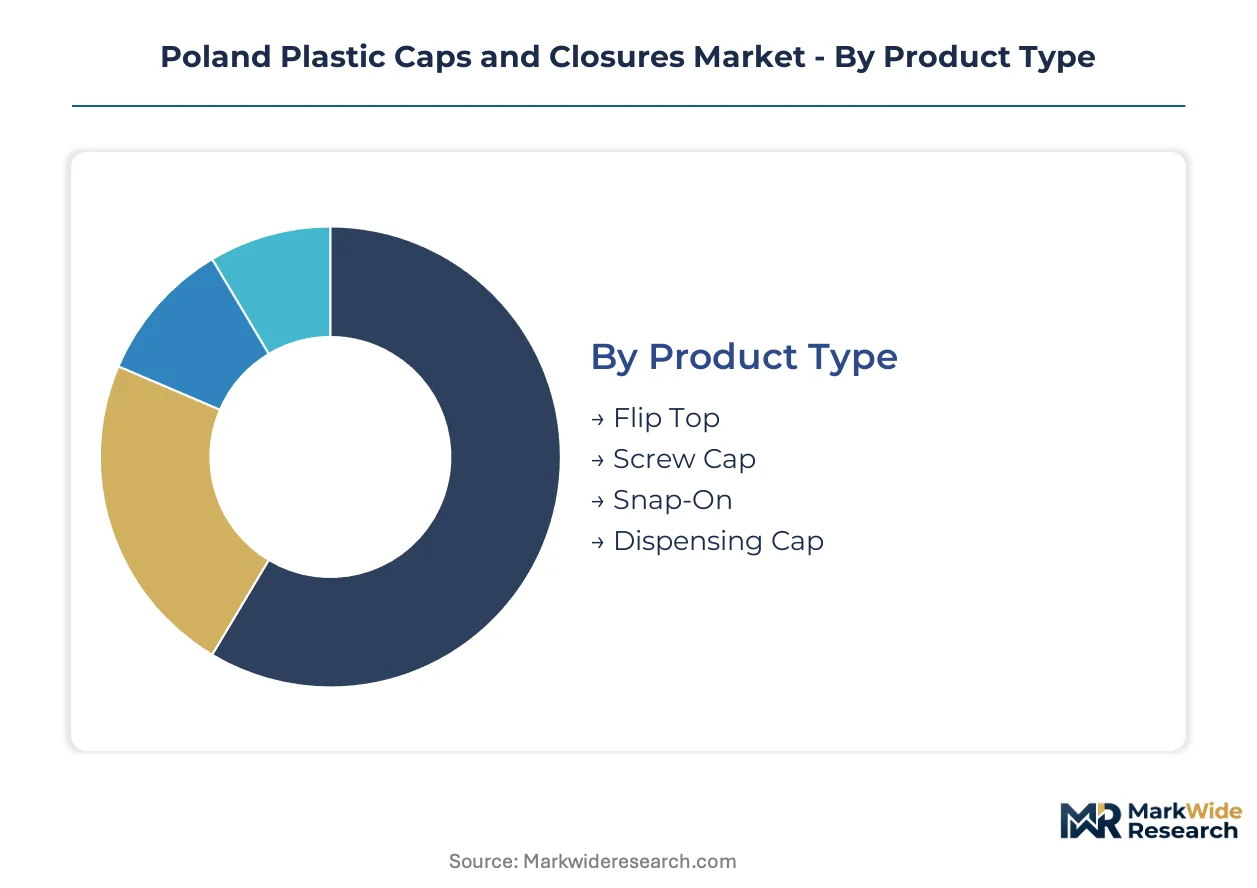
Polish converters configure production lines around closure specifications that determine filling equipment compatibility, regulatory compliance burden, and recyclate recovery economics. Segment boundaries are hardening as EU Single-Use Plastics Directive deadlines force material standardization and as Masovia beverage bottlers consolidate supplier panels around validated formats.
Product Type:
Beverage bottlers in the Masovia corridor prioritize reseal reliability and line speed compatibility when specifying closure formats for carbonated and still water applications.
- Screw Cap:Injection-molded polypropylene with continuous thread profiles and integrated tamper-evident bands. Demand concentrates among Warsaw-area mineral water and soft drink producers seeking proven compatibility with existing rotary capping equipment and minimal changeover downtime.
- Dispensing Cap:Compression-molded designs with flip-top or push-pull actuation mechanisms. Personal care formulators in Łódź and household chemical producers specify these units for controlled-dose functionality that reduces product waste and supports premium positioning.
- Flip Top:Hinged single-piece constructions common in condiment and sauce applications where one-handed operation drives consumer preference.
- Snap-On:Press-fit closures for dairy tubs and ready-meal trays where reseal is secondary to initial seal integrity and cost minimization.
Volume sits with Screw Cap; growth tilts toward Dispensing Cap.
Material:
Resin selection determines compliance pathways under REACH Annex XVII and Poland's extended producer responsibility fee structures.
- Polypropylene:Homopolymer and random copolymer grades dominate beverage and food applications due to favorable stress-crack resistance and established mechanical recycling streams. Masovia bottlers are mandating post-industrial recyclate inclusion in procurement specifications.
- Polyethylene:HDPE and LDPE formulations serve personal care and household segments where flexibility and impact resistance outweigh stiffness requirements. Silesia cosmetics manufacturers favor these grades for airless pump compatibility.
- PVC:Specialized applications in pharmaceutical blister packaging and certain chemical-resistant closures where barrier properties justify handling complexity.
- PET:Crystalline grades for hot-fill applications and compatibility with PET bottle streams in sorting infrastructure.
Polypropylene captures the largest share; polyethylene is climbing the fastest as mono-material dispensing designs displace multi-material alternatives.
End User:
Customer procurement patterns diverge sharply between high-volume beverage contracts and specification-intensive pharmaceutical validation cycles.
- Food & Beverage:The anchor segment spanning mineral water, soft drinks, dairy, edible oils, and sauces. Polish bottlers specify lightweight screw caps with tamper-evident features and are accelerating shifts toward recyclable mono-material formats ahead of regulatory deadlines.
- Personal Care:Shampoo, conditioner, and skincare formulators in the Masovia and Silesia corridors drive demand for dispensing pumps and flip-top closures with premium tactile finishes and airless functionality.
- Pharmaceuticals:Child-resistant and senior-friendly closure designs for OTC and prescription packaging with stringent migration testing requirements enforced by Poland's national reference laboratory.
- Household Products:Bleach, detergent, and cleaning chemical containers requiring chemical-resistant formulations and trigger-spray or disc-top dispensing configurations.
Food & Beverage dominates absolute volume; Personal Care shows the steepest expansion trajectory as dispensing convenience commands premium positioning.
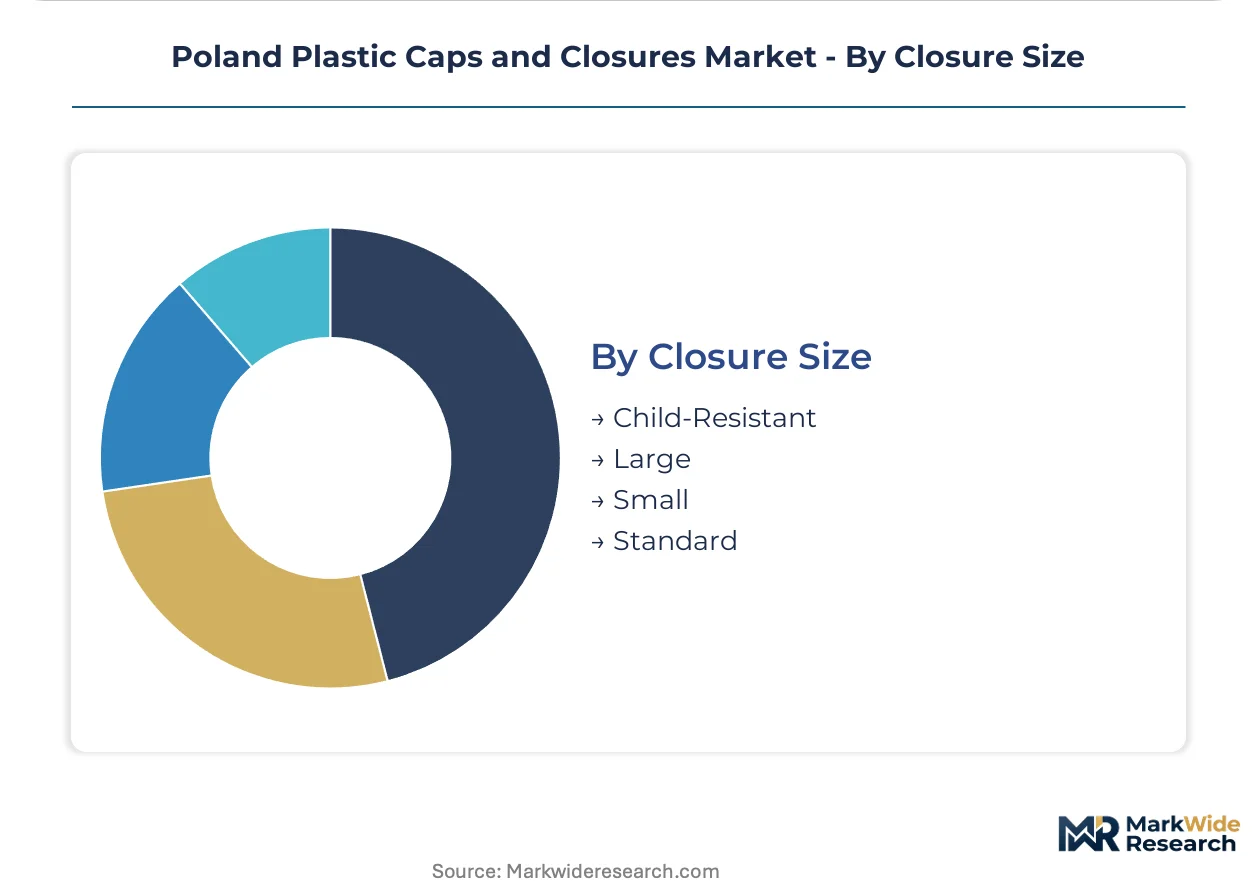
Closure Size:
Format dimensions correlate with container neck finish standards and end-user safety requirements rather than commodity cost tiers.
- Standard:28mm and 38mm PCO and BPF neck finishes for mainstream beverage bottles. Polish converters maintain dedicated production cells for these high-rotation formats serving Masovia bottling clusters.
- Child-Resistant:Push-and-turn or squeeze-and-turn mechanisms for pharmaceutical and household chemical applications. Certification requirements under Poland's pharmaceutical regulator and EU safety directives extend product development timelines.
- Small:20mm and 22mm finishes for single-serve beverage bottles and sample-size personal care products.
- Large:48mm and 53mm formats for wide-mouth jars, industrial containers, and bulk household chemical packaging.
Standard size generates the highest unit volumes; Child-Resistant formats are gaining share fastest as safety regulations tighten across pharmaceutical and chemical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer-grade propylene supply from German and Dutch crackers anchors Poland's closure manufacturing base, with feedstock logistics shaping converter location decisions across the country's industrial corridors.
Masovia
Warsaw-area bottling clusters drive captive demand for lightweight screw caps with tamper-evident bands. The Chief Inspectorate of Environmental Protection enforces extended producer responsibility fee structures that elevate compliance costs for non-recyclable formulations. Łódź personal care formulators specify compression-molded dispensing caps for controlled-dose functionality.
Silesia
Katowice-area skincare manufacturers generate underpenetrated demand for premium dispensing pumps with airless functionality. Poland's packaging waste regulations administered at voivodeship level mandate recyclability documentation for all closure imports. Gliwice industrial zones host converters serving household chemical producers with chemical-resistant flip-top designs.
Greater Poland
Poznań food processors anchor demand for dairy tub snap-on closures where initial seal integrity outweighs reseal requirements. The Polish Committee for Standardization influences material approval protocols that determine market access for imported closure systems. Konin packaging converters supply edible oil clients with additive-free polypropylene grades.
Pomerania
Gdańsk port logistics facilitate resin import flows from Rotterdam and Antwerp crackers, reducing inventory carrying costs for regional molders. EU Single-Use Plastics Directive implementation timelines drive qualification of mono-material formats ahead of compliance deadlines. Gdynia beverage bottlers consolidate supplier panels around validated 28mm PCO neck finishes.
Lower Silesia
Wrocław pharmaceutical packaging demand requires child-resistant closure certification under Poland's national reference laboratory protocols. REACH Annex XVII restrictions on intentional microplastic additives compel reformulation of legacy slip agent packages. Wałbrzych industrial parks accommodate converters serving OTC and prescription drug segments.
Poland Plastic Caps and Closures Market Competitive Landscape
Capacity expansion dominates the current landscape as converters revalidate production lines for recyclable polypropylene alternatives ahead of regulatory deadlines. The vendor base clusters around three tiers: pan-European specialists with multi-country mold networks, domestic Polish converters with regional customization capabilities, and integrated packaging groups with captive resin supply agreements. Strategic archetypes include technology licensors leveraging compression molding energy advantages, design specialists capturing premium dispensing pump margins, and scale operators serving high-volume beverage contracts. M&A activity and strategic partnerships represent the dominant competitive moves, with players acquiring tooling capabilities and forming resin supply alliances to secure feedstock access.
Among German-origin specialists, BERICAP Holding GmbH and ALPLA Group occupy positions anchored by European manufacturing footprints and beverage sector relationships. BERICAP exemplifies the technology-licensing archetype through its mold network leverage for short-lead production. ALPLA represents integrated packaging group positioning with regional supply anchoring. Domestic Polish specialists Politech Sp. z o.o. and Multicaps Sp. z o.o. sit within the customization tier, serving local dairy and cosmetics brands with specification-intensive closure designs. These two exemplify the regional design-specialist archetype competing on tailored formats rather than scale economics.
| Leading Market Players |
|---|
| Berry Global Inc. |
| BERICAP Holding GmbH |
| UNITED CAPS LUXEMBOURG SA |
| Amcor Group GmbH |
| Guala Closures S.p.A. |
| ALPLA Group |
| Tecnocap Group |
| Politech Sp. z o.o. |
| Multicaps Sp. z o.o. |
| Others |
Pricing and Supply Chain Analysis
Polymer-grade propylene feedstock costs cascade through Polish closure manufacturing into three distinct pricing tiers, with resin-linked contract structures dominating high-volume beverage procurement while spot-market exposure concentrates in small-batch cosmetics converters serving Silesia formulators.
Pricing Analysis
Warranty and mold-maintenance bundling separates premium converter relationships from transactional spot purchasing, with BERICCAP Holding GmbH and ALPLA Group embedding multi-year tooling service agreements into their beverage contracts. Pricing stratifies across premium, standard, and economy tiers based on recyclate certification grade and compression-molding energy efficiency. Cost compression in the standard tier is intensifying because REACH Annex XVII compliance is forcing additive reformulation. Beverage bottlers in Masovia show the least price sensitivity due to line revalidation costs, while dairy processors in Greater Poland prioritize unit cost minimization above technical service.
Supply Chain Analysis
Road freight rates from Rotterdam and Antwerp crackers to Poznań and Warsaw molding facilities absorb 8-12% of landed resin costs, with rail alternatives limited by last-mile trucking requirements. Polish converters draw polymer-grade propylene from German and Dutch steam crackers, with homopolymer and random copolymer grades forming the core input basket. Single-source vulnerability concentrates in high-precision mold fabrication, where southern German and northern Italian equipment builders control multi-cavity hot-runner supply. Distribution runs through converter-direct relationships with Masovia bottling clusters, bypassing traditional distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's plastic caps and closures market operates under supply-constrained conditions where hot-runner mold fabrication bottlenecks prop pricing power for converters with validated European equipment partnerships.
For Market Incumbents: Hedge against propylene feedstock volatility through captive resin supply agreements with Rotterdam and Antwerp crackers, while accelerating compression-molding capacity additions in Masovia to capture beverage bottler consolidation. Defend margin structures by embedding digital watermark traceability into premium dispensing closures before EU Packaging and Packaging Waste Regulation mandates tighten.
For New Entrants and Emerging Players: Capture underpenetrated premium dispensing pump demand from Katowice-area skincare formulators in Silesia, where airless functionality specifications outpace local converter capabilities. Target pharmaceutical child-resistant closure certification as the most penetrable segment, leveraging Poland's national reference laboratory backlog to justify extended development timelines while building technical credibility.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation implementation timelines are the leading indicator that first-mover recyclate validation will separate viable acquisition targets from stranded capacity. The 5-10 year viability window favors Polish domestic converters with established relationships to the Chief Inspectorate of Environmental Protection and documented circularity claims. Watch for compression-molding technology licensing agreements as signals of operational efficiency differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recyclate Sourcing | Secures food-contact approved post-industrial polypropylene streams ahead of EU recycled content mandates. |
| Compression Molding Capacity Expansion | Reduces unit energy costs for Masovia beverage contracts exposed to Polish electricity price volatility. |
| Digital Watermark Traceability Program | Enables premium pricing through blockchain-verified circularity credentials for personal care brands. |
| Hot-Runner Mold Fabrication Partnership | Shortens lead times for multi-cavity systems currently concentrated in German and Italian equipment builders. |
| REACH Annex XVII Pre-Compliance Reformulation | Eliminates slip agent packages before enforcement eliminates non-compliant imported closures from Polish market access. |
Research Methodology
Document review covered customs and trade flow databases, EU regulatory filings including ECHA substance restriction updates, and Polish packaging waste administration records, complemented by interviews with plant managers at injection and compression molding facilities, procurement leads at Masovia beverage bottlers, distribution channel partners serving Silesia cosmetics manufacturers, and technical R&D directors at resin compounders. Bottom-up capacity and utilization estimates triangulated against top-down demand aggregation from end-use sector consumption patterns.
Output modeling generated segment-level volume and value trajectories across the projection horizon, with analytical frameworks disaggregating by closure type, material grade, end-use industry, and regional production cluster. CAGRs derived from elasticity-adjusted demand curves incorporating propylene price sensitivity and regulatory compliance cost pass-through assumptions. Industry-specific inputs included REACH Annex XVII implementation schedules and Poland's extended producer responsibility fee structure revisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation recycled content mandate timing and mechanical recycling infrastructure deployment rates. Forecasts reflect assumptions around resin specification stability and converter capacity expansion execution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Brush Caps Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Bag Closures Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Overcaps Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Sleeve Rubber Stoppers Market