
 Thermoformed Plastic Trays Market | 2026-2036
Thermoformed Plastic Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Plastic Trays Market Analytics
Capital-intensity divergence between thin-gauge commodity producers and heavy-gauge precision thermoformers is collapsing as medical-grade certification costs rise. Pactiv Evergreen leverages its integrated resin-to-tray footprint to sustain margin stability across food service volumes. Sonoco Products Company anchors its position through specialized pharmaceutical blister formats that compete on barrier performance rather than price. Huhtamaki Group differentiates by controlling European healthcare packaging channels with cleanroom-certified production assets.
Thermoformed plastic trays are rigid packaging structures produced by heating polymer sheets—typically PET, polypropylene, polystyrene, or polyethylene—and vacuum- or pressure-forming them over molds to create precise cavity geometries for product containment, display, or protection. Wall thickness ranges from thin-gauge disposable formats to heavy-gauge reusable industrial designs, with forming temperatures varying by resin crystallinity and molecular weight. Clamshell trays dominate retail fresh-produce applications where visibility and tamper evidence drive specification, while blister trays command premium positioning in pharmaceutical compliance packaging where moisture and oxygen barrier properties determine selection. Custom trays represent the fastest-expanding category as medical device original equipment manufacturers seek tray-and-lid systems validated for ethylene oxide and gamma sterilization cycles.
The US FDA enforces sterile barrier system validation under ISO 11607 for medical trays, compelling manufacturers to maintain process capability indices that exclude non-specialized thermoformers from healthcare procurement pools. Europe's MDR and REACH frameworks restrict phthalate plasticizers and mandate recyclability disclosures, redirecting formulation investment toward mono-material PET streams that satisfy EFSA food-contact approvals. Stakeholders must monitor evolving extended producer responsibility schemes and sterilization modality shifts to position tray specifications ahead of buyer qualification timelines.
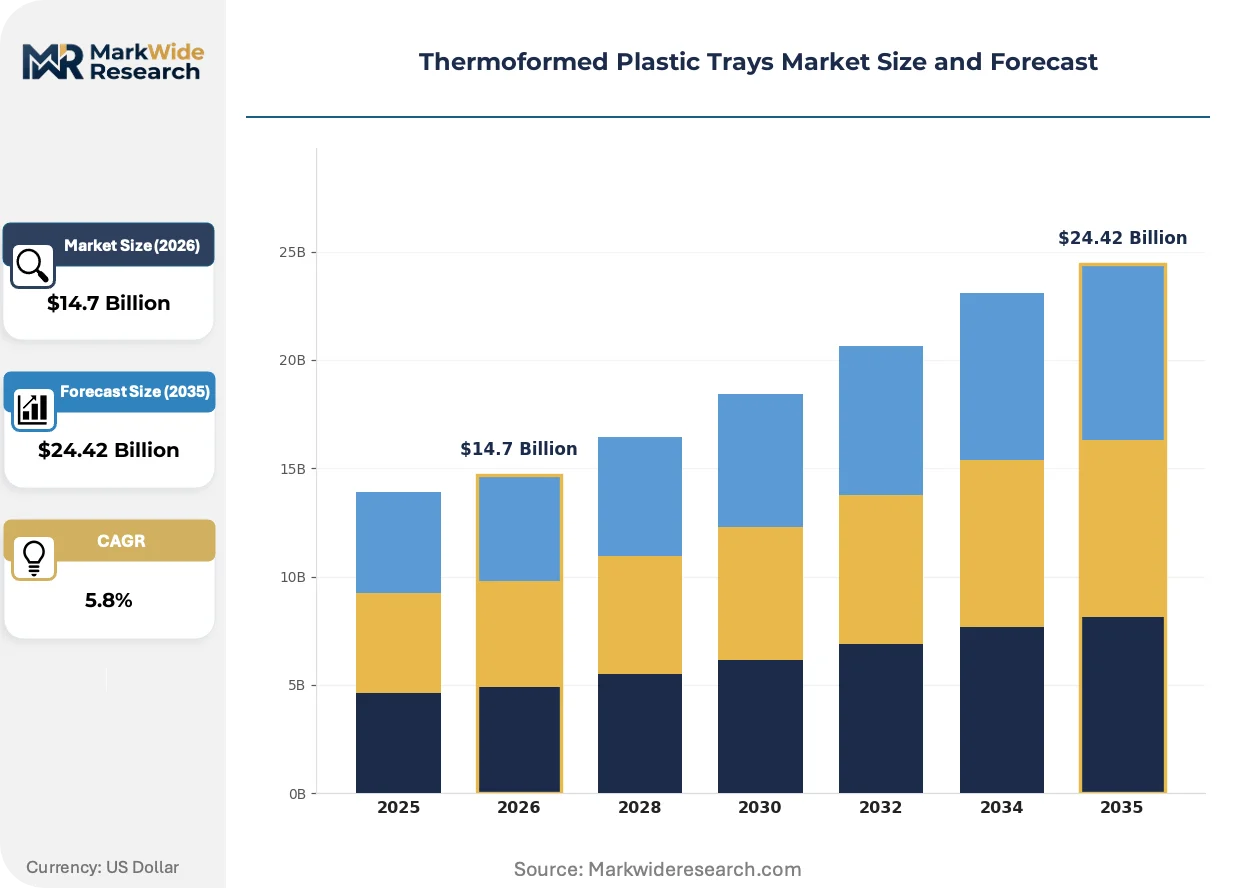
Market Dynamics
Sterilization validation requirements for medical-grade trays are consolidating production capability among thermoformers with cleanroom assets and ISO 11607 certification, squeezing commodity converters from healthcare procurement pools.
Growth Catalysts
- MDR sterilization mandates:Europe's Medical Device Regulation requires validated sterile barrier systems, pulling tray demand toward certified manufacturers in Germany's Stuttgart-Tuttlingen corridor.
- Gamma-compatible PET formulations:Advanced copolymer grades withstand radiation sterilization without yellowing, opening surgical kit applications previously served by glass.
- Hospital supply chain consolidation:Integrated delivery networks in the US are standardizing tray specifications across multi-facility systems, favoring suppliers with national distribution footprints.
Market Restraints
- Resin price volatility:Polypropylene and PET feedstock costs fluctuate with crude oil and PTA spot markets, compressing margins for thin-gauge food service converters without backward integration.
- Cleanroom capacity scarcity:Certified medical-grade production space concentrates in Switzerland, southern Germany, and Massachusetts, creating geographic bottlenecks for healthcare tray supply.
- Aluminum tray substitution:Reusable metal formats regain traction in pharmaceutical cold chain logistics where temperature stability outweighs disposability preferences.
Strategic Opportunities
- India's hospital infrastructure buildout:Central government health schemes are expanding tertiary care capacity, creating first-mover openings for sterilization-validated tray suppliers.
- Mono-material recyclability:EFSA-compliant PET streams satisfy both food-contact and healthcare requirements, enabling cross-sector asset utilization and simplified recycling claims.
- E-commerce pharmaceutical fulfillment:Direct-to-patient dispensing models require unit-dose blister trays with tamper-evident features, displacing bulk bottle packaging in chronic care segments.
Industry Challenges
- ISO 11607 validation timelines:Sterile barrier system qualification cycles extend 18-24 months, locking working capital in development programs before revenue recognition.
- Multi-modal sterilization compatibility:Trays must perform across ethylene oxide, gamma, and emerging vaporized hydrogen peroxide protocols without material degradation or dimensional drift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Plastic Trays Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshell Trays, Skin Packaging, Blister Trays, Custom Trays End User: Food Service, Retail Packaging, Industrial, Medical Material: Polypropylene, Polyethylene, Polystyrene, PET Shape: Rectangular, Square, Round, Specialty Shapes |
| Companies Covered | Pactiv Evergreen Inc., Sonoco Products Company, Huhtamaki Group, Winpak Ltd., Placon Corporation, Amcor Plc, Berry Global Inc., Greiner Packaging, Anchor Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Plastic Trays Market Evolving Landscape
Material science advances and regulatory stringency are splitting the thermoformed tray market into divergent technical specifications, with medical and food service applications demanding incompatible performance profiles.
Copolyester formulations with enhanced radiation stability are bifurcating the pharmaceutical blister segment from commodity PET applications. Surgical device OEMs in the US and Germany are specifying these grades for gamma-sterilized implant kits, while food service buyers remain anchored to standard PET price points. The technical gap is compressing shared resin purchasing and forcing converters to choose specialization lanes.
REACH restrictions on phthalate plasticizers and the EU Green Deal's packaging waste targets are redirecting formulation investment toward bio-based and chemically recycled feedstocks. Thermoformers serving European healthcare channels must now document mass balance certifications and recyclability percentages in tender submissions. Mono-material PET structures are displacing multi-layer laminates in diagnostic test kit packaging to satisfy EFSA and MDR dual compliance.
Hospital procurement departments are consolidating vendor panels around full-service tray-and-lid system suppliers capable of sterile barrier validation. This consolidation is squeezing standalone thermoformers without in-house lidding film or sterile packaging expertise. The shift is most pronounced in US integrated delivery networks and German university hospital systems, where total cost of ownership models now include sterilization cycle validation and supply chain risk assessments.
Thermoformed Plastic Trays Market Segmentation
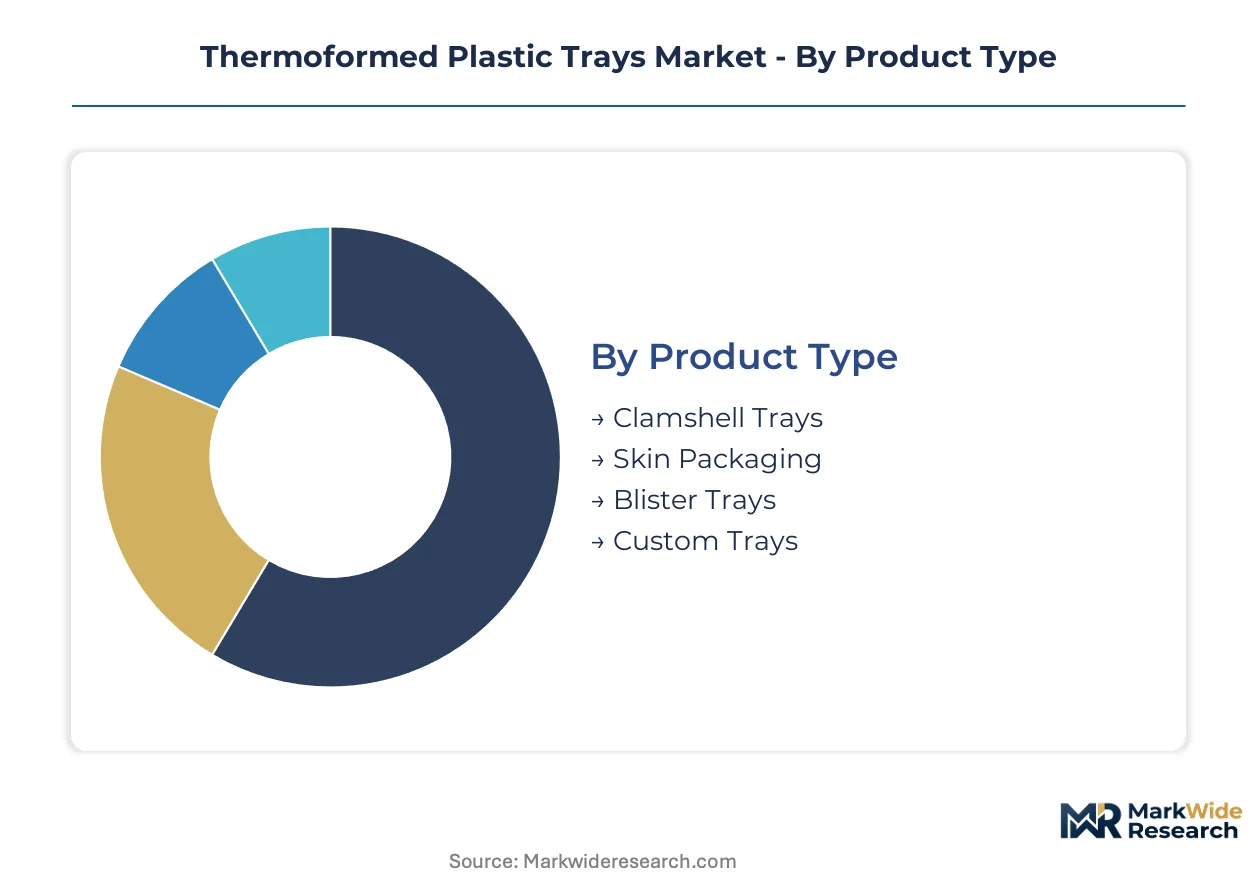
Thermoformed tray specifications diverge sharply between commodity food service formats and validated medical barrier systems. Segmentation reveals where resin chemistry, cleanroom certification, and sterilization compatibility create defensible margin tiers.
Product Type:
Margin pools concentrate in custom medical formats where ISO 11607 validation creates procurement moats, while commodity clamshells compete on resin throughput efficiency.
- Clamshell Trays:Hinged-lid structures formed from thin-gauge PET or polystyrene dominate fresh produce retail where visibility drives purchase decisions. US supermarket chains specify tamper-evident designs with snap-lock closures that withstand distribution vibration without cracking.
- Custom Trays:Precision-engineered cavity geometries accommodate surgical instruments, implants, and diagnostic devices with validated sterile barrier performance. Germany's Stuttgart-Tuttlingen medical device corridor sources these formats for gamma and ethylene oxide sterilization cycles.
- Skin Packaging:Film laminated directly to product surfaces creates zero-headspace containment for protein and seafood applications.
- Blister Trays:Thermoformed cavities paired with lidding films deliver unit-dose pharmaceutical compliance packaging.
Custom trays hold installed capacity. Clamshell trays are rotating up the share rankings.
End User:
Volume concentration sits with food service converters running continuous-roll thermoforming lines, though medical qualification timelines protect pricing power.
- Medical:Sterile barrier systems for surgical kits, implant packaging, and diagnostic devices require cleanroom manufacturing and ISO 11607 process validation. FDA 510(k) clearance pathways and Europe's MDR compliance documentation extend procurement cycles but lock in multi-year supply agreements.
- Food Service:Disposable takeaway containers, deli trays, and catering formats consume high-volume resin streams with thin-gauge forming efficiency. Quick-service restaurant chains in the US standardize specifications across franchise networks to simplify sourcing.
- Retail Packaging:Produce, bakery, and meat case displays prioritize optical clarity and shelf appeal.
- Industrial:Heavy-gauge reusable trays protect automotive and electronics components through assembly line logistics.
Food service dominates unit volume. Medical is expanding most quickly.
Material:
Specialty copolyester grades for gamma sterilization command premium spreads over commodity polypropylene food service formulations.
- PET:Amorphous and crystalline grades span food contact, pharmaceutical blister, and medical barrier applications with EFSA and FDA dual approvals. Mono-material PET structures satisfy EU packaging waste targets while maintaining clarity and barrier performance.
- Polypropylene:High-impact copolymers dominate microwaveable food containers and industrial dunnage trays where temperature resistance and chemical inertness outweigh optical requirements. Resin price volatility tracks propylene monomer spot markets.
- Polystyrene:Crystal and high-impact grades serve cost-sensitive disposable applications.
- Polyethylene:LDPE and HDPE formulations provide flexibility and moisture resistance for industrial and produce applications.
PET holds installed capacity. Polypropylene is climbing the fastest.
Shape:
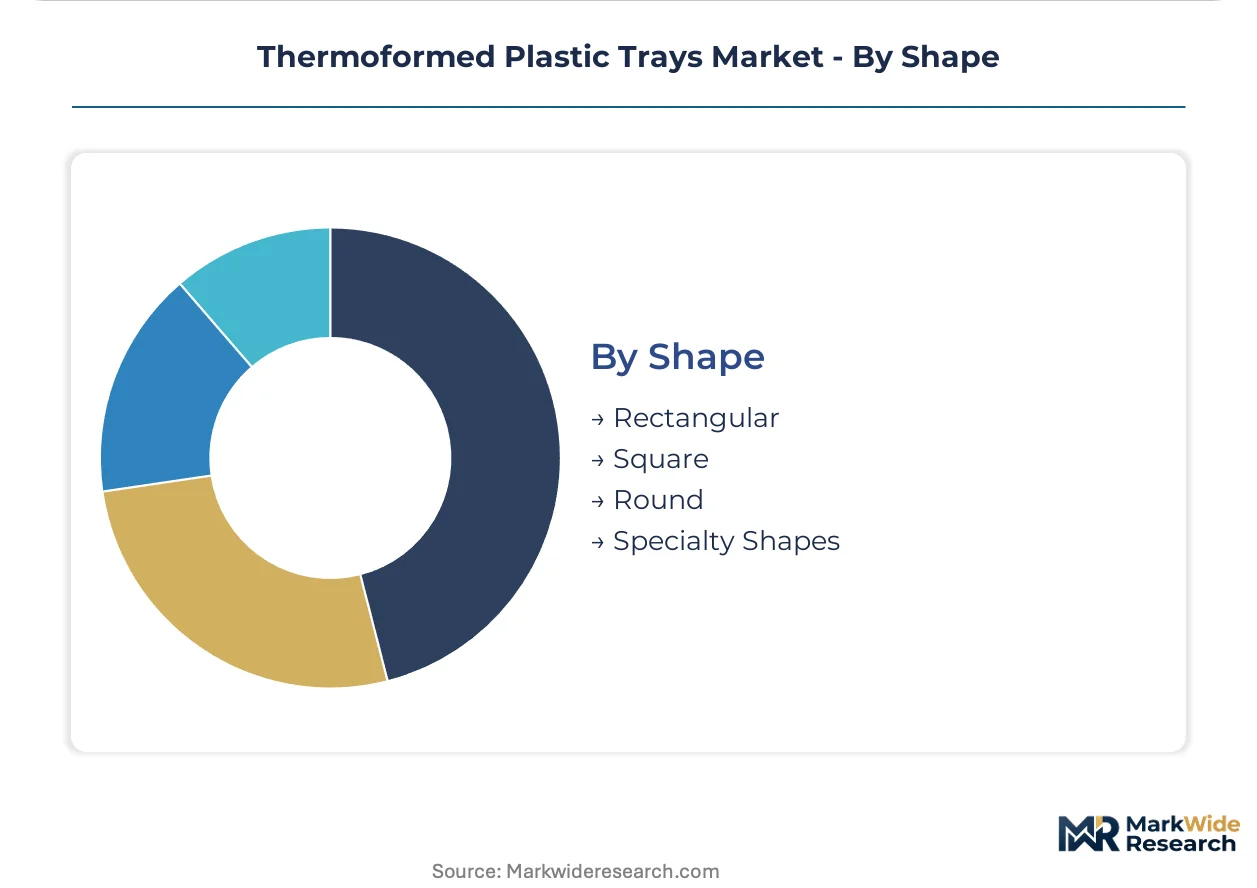
Standardized rectangular formats maximize forming yield per resin sheet, while specialty geometries capture design-intensive medical and retail premium positioning.
- Rectangular:Optimized cavity packing density minimizes trim waste in high-speed roll-fed thermoforming operations. Food service and industrial logistics networks standardize on modular rectangular footprints for palletization efficiency.
- Specialty Shapes:Contoured designs accommodate irregular medical devices, cosmetic presentations, and gift packaging where differentiation justifies higher per-unit conversion costs. Tooling complexity limits supplier pools.
- Square:Balanced dimensional stability for retail display and portion-controlled food applications.
- Round:Radial symmetry suits produce punnets and catering platters with rotational nesting.
Rectangular formats hold installed capacity. Specialty shapes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service buyers in India and Southeast Asia exhibit acute price elasticity, squeezing margins on commodity clamshell formats, while German and US hospital procurement teams absorb premium spreads for ISO 11607-validated sterile barrier systems without volume attrition.
United States
FDA 510(k) clearance pathways for sterile barrier systems extend procurement cycles but lock in multi-year supply agreements for validated tray-and-lid formats. Integrated delivery networks spanning multi-state hospital systems are consolidating vendor panels around full-service suppliers with national distribution footprints. Massachusetts hosts concentrated cleanroom-certified production assets serving surgical kit OEMs.
Germany
Europe's MDR mandates validated sterile barrier documentation, redirecting tray demand toward certified manufacturers with cleanroom assets. REACH restrictions on phthalate plasticizers accelerate formulation shifts toward mono-material PET streams. The Stuttgart-Tuttlingen corridor anchors medical device manufacturing, sourcing precision thermoformed formats for gamma and ethylene oxide sterilization cycles.
China
NMPA regulatory harmonization with ISO 11607 standards is elevating certification requirements for domestic tray suppliers serving multinational device OEMs. SAMR enforcement of food-contact material safety standards constrains resin sourcing flexibility for food service converters. Yangtze River Delta manufacturing clusters concentrate both medical-grade cleanroom capacity and high-volume food service thermoforming operations.
India
Central government health schemes expanding tertiary care infrastructure are creating first-mover openings for sterilization-validated tray suppliers. CDSCO medical device rules increasingly align with international quality management standards, raising barriers for uncertified converters. Maharashtra and Gujarat industrial corridors concentrate domestic thermoforming capacity serving both pharmaceutical blister and food service segments.
Japan
METI industrial policy supports domestic production of high-barrier pharmaceutical packaging materials, insulating local thermoformers from commodity price cycles. PMDA quality regulations for sterile medical devices maintain stringent validation requirements that favor established suppliers with documented process capability. Kanto and Kansai manufacturing regions concentrate precision packaging assets serving domestic pharma OEMs.
Thermoformed Plastic Trays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in thermoformed plastic trays, with scale advantages in resin purchasing and sterilization certification creating durable procurement moats. The market structure separates thin-gauge commodity food service converters from heavy-gauge precision thermoformers with cleanroom assets. Three archetypes dominate: integrated resin-to-tray producers, specialized pharmaceutical barrier specialists, and regional food service volume players. Competitive dynamics center on backward integration into resin compounding and geographic expansion of cleanroom-certified production networks.
Within the integrated tier, Pactiv Evergreen Inc. exemplifies scale-driven positioning through captive resin supply chains, while Sonoco Products Company occupies a specialist position in barrier-performance formats. Huhtamaki Group represents European healthcare channel control through cleanroom-certified asset networks. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Sonoco Products Company |
| Huhtamaki Group |
| Winpak Ltd. |
| Placon Corporation |
| Amcor Plc |
| Berry Global Inc. |
| Greiner Packaging |
| Anchor Packaging |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month ISO 11607 validation cycles lock working capital in development programs before revenue recognition, concentrating pricing power among thermoformers with cleanroom assets while commodity converters absorb resin volatility without recourse. This lead-time asymmetry stratifies the market into certified medical-grade suppliers commanding premium spreads and thin-gauge food service players competing on resin throughput efficiency.
Pricing Analysis
After-sales sterile barrier validation services and multi-year supply agreements drive lifetime value for medical-grade tray suppliers. Three-tier pricing structure across premium ISO 11607-certified, standard food-contact compliant, and economy commodity clamshell levels dominates the market. Price differentiation rests on certification grade and cleanroom manufacturing capability. Cost compression in commodity clamshells is intensifying because food service buyers in India and Southeast Asia exhibit acute price elasticity. Quick-service restaurant chains absorb premium spreads for validated sterile barrier systems without volume attrition.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Rotterdam and Hamburg elevate inbound logistics costs for resin imports serving European thermoforming operations. Geographic supply concentrates in Germany, the United States, and China. Raw material dependencies draw from PET resin streams, polypropylene feedstock, and specialty copolyester grades for gamma sterilization. Single-source vulnerability in cleanroom-certified production space creates structural risk. Distribution runs through integrated delivery networks in US hospital systems and Germany's Stuttgart-Tuttlingen medical device corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoformed plastic trays market sits in early-cycle expansion as MDR sterilization mandates and hospital supply chain consolidation accelerate validated tray adoption ahead of commodity format penetration.
For Market Incumbents: Fortify sterile barrier validation capabilities and captive resin compounding operations to defend against aluminum tray substitution in pharmaceutical cold chain logistics. Prioritize backward integration into PET resin streams to stabilize margin exposure to PTA spot market volatility. Expand cleanroom-certified production footprints in Massachusetts and southern Germany to capture integrated delivery network vendor consolidation. For New Entrants and Emerging Players: Anchor in India's tertiary care infrastructure buildout where CDSCO regulatory alignment creates first-mover openings for ISO 11607-certified suppliers. Target Maharashtra and Gujarat industrial corridors for pharmaceutical blister and sterilization-validated tray manufacturing. Pursue hospital system partnerships through gamma-compatible PET formulation expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because sterile barrier validation timelines and cleanroom asset scarcity create durable procurement barriers that compound over multi-year supply agreements. Acquisition candidates include regional thermoformers with latent cleanroom capacity and documented process capability indices. Monitor NMPA regulatory harmonization progress in China as the signal for accelerated multinational OEM sourcing shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 11607 validation unlocks multi-year supply agreements with German surgical kit OEMs. |
| Backward Integration into Resin Compounding | Captive PET supply chains insulate margin stability from crude oil and PTA volatility. |
| Mono-Material PET Formulation Development | EFSA-compliant streams satisfy EU packaging waste targets and MDR dual compliance. |
| Hospital System Partnership Expansion | Integrated delivery networks in the US consolidate vendor panels around full-service suppliers. |
| Gamma-Compatible Copolyester Scale-Up | Radiation-stable grades open surgical kit applications previously served by glass formats. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR submissions, resin trade data, and hospital procurement databases preceded structured interviews with thermoforming plant managers, medical device OEM procurement leads, GPO contracts managers, and sterile packaging engineers. Bottom-up volume modeling across product type, end user, material, and shape segments was cross-validated against top-down industry association data and customs records.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in medical versus food service applications. Segmentation dimensions modeled include tray format, sterilization compatibility, cleanroom certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to validated sterile barrier adoption curves and hospital infrastructure buildout timelines. Industry-specific inputs incorporate REACH restriction implementation schedules and extended producer responsibility scheme rollouts.
Decision-makers should treat outputs as directional under assumptions of continued MDR enforcement and resin price volatility within historical bands; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding sterilization modality shifts and recycling infrastructure development. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Japan Plastic Bottles Market