
 United Arab Emirates Plastic Packaging Market | 2026-2036
United Arab Emirates Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Plastic Packaging Market Analytics
Food service buyer concentration is expanding across UAE hotel chains and quick-service restaurant groups, consolidating procurement volumes toward fewer but larger contracts. Integrated Plastics Packaging LLC leverages its domestic manufacturing footprint to anchor supply relationships with these consolidated buyers. Huhtamaki Flexibles UAE competes through technology leadership in barrier film formulations for hot-climate distribution. Hotpack Packaging Industries LLC dominates the disposable food service segment through extensive channel control across Gulf Cooperation Council retail and food service distribution networks.
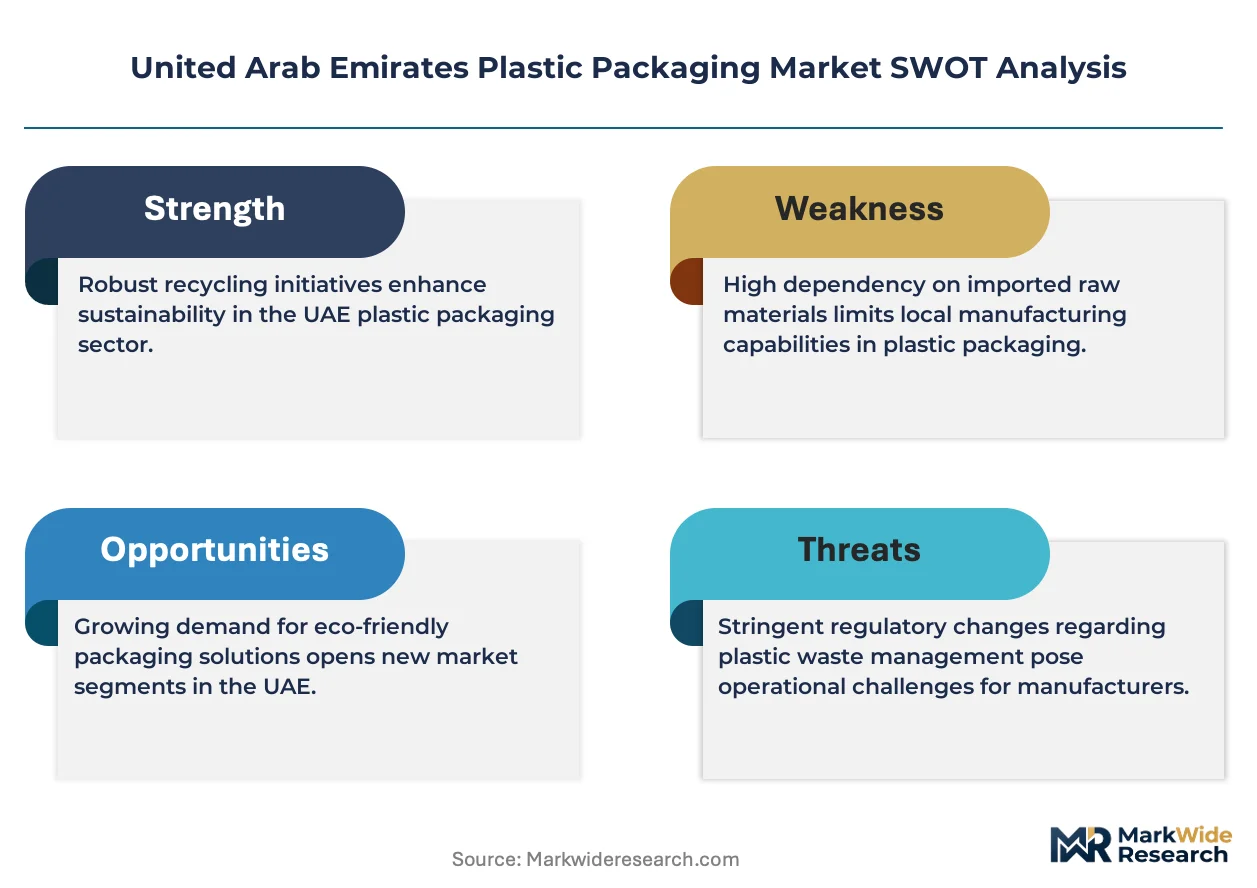
Plastic packaging in the United Arab Emirates encompasses thermoformed, extruded, and molded polymer structures engineered for containment, protection, and shelf-life extension of consumer and industrial goods. Polyethylene films constitute the largest material segment by tonnage, while polypropylene containers capture premium margin pools in temperature-resistant food packaging applications. The food and beverage end-user segment leads absolute consumption, though healthcare packaging exhibits the fastest structural expansion driven by pharmaceutical import growth and local manufacturing incentives. Industrial packaging retains mature, price-sensitive characteristics tied to construction and petrochemical logistics demand.
MOHAP oversees pharmaceutical packaging standards, while the UAE Ministry of Climate Change and Environment administers extended producer responsibility and single-use plastic reduction mandates. ESMA conformity requirements and Gulf Standards Organization technical regulations shape import access and local production specifications for food-contact materials. Stakeholders must monitor evolving biodegradable content thresholds and free-zone regulatory harmonization as these frameworks determine competitive positioning and capital allocation across emirate-level manufacturing zones.
Market Dynamics
The UAE Ministry of Climate Change and Environment's extended producer responsibility mandates are compressing material specification timelines, forcing converters to requalify polymer grades ahead of single-use plastic phase-out deadlines while food and beverage buyers consolidate procurement volumes.
Growth Catalysts
- Free-zone manufacturing incentives:Dubai Industrial City and KIZAD are attracting extrusion and thermoforming capacity with customs exemptions and utility subsidies, anchoring downstream packaging demand within bonded logistics corridors.
- MOHAP pharmaceutical packaging standards:Tightening barrier requirements for imported drug stability in hot-climate distribution are pulling high-performance multilayer film demand from healthcare logistics providers.
- Quick-service restaurant expansion:Gulf Cooperation Council food service chains are standardizing disposable packaging specifications across UAE outlets, creating volume pull for rigid polypropylene containers and barrier-coated paper laminates.
Market Restraints
- Polymer feedstock import dependence:The UAE lacks domestic ethylene cracker capacity for packaging-grade polyethylene, exposing converters to Saudi Aramco and Qatari supplier pricing volatility and freight cost swings.
- Biodegradable content threshold uncertainty:ESMA has not finalized mandatory renewable content percentages for food-contact plastics, freezing converter capex commitments on compostable line investments.
- Aluminum can substitution in beverages:Emirates-based beverage bottlers are expanding canning lines for premium water and soft drinks, displacing polyethylene terephthalate bottle demand in temperature-sensitive distribution.
Strategic Opportunities
- Abu Dhabi healthcare corridor:Khalifa Industrial Zone's pharmaceutical manufacturing incentives are creating demand for high-barrier blister packs and cold-chain shippers that local converters have not fully captured.
- Reverse vending integration:The UAE's deposit-return scheme pilot for plastic bottles is opening service-contract opportunities for sorting and reprocessing equipment providers alongside packaging converters.
- Barrier film and paper hybridization:Convergence of aqueous coating technology and fiber-based substrates is enabling heat-sealable paper packaging for quick-service restaurant chains seeking plastic reduction without shelf-life sacrifice.
Industry Challenges
- Polymer requalification timelines:Converters face 12-18 month validation cycles with food and beverage brand owners when switching to post-consumer recycled or bio-based resin grades, compressing margin recovery windows.
- ESMA conformity assessment bottlenecks:Testing laboratory capacity constraints in Dubai are extending food-contact material approval timelines, delaying new product launches for export-oriented free-zone manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Plastic Packaging Market |
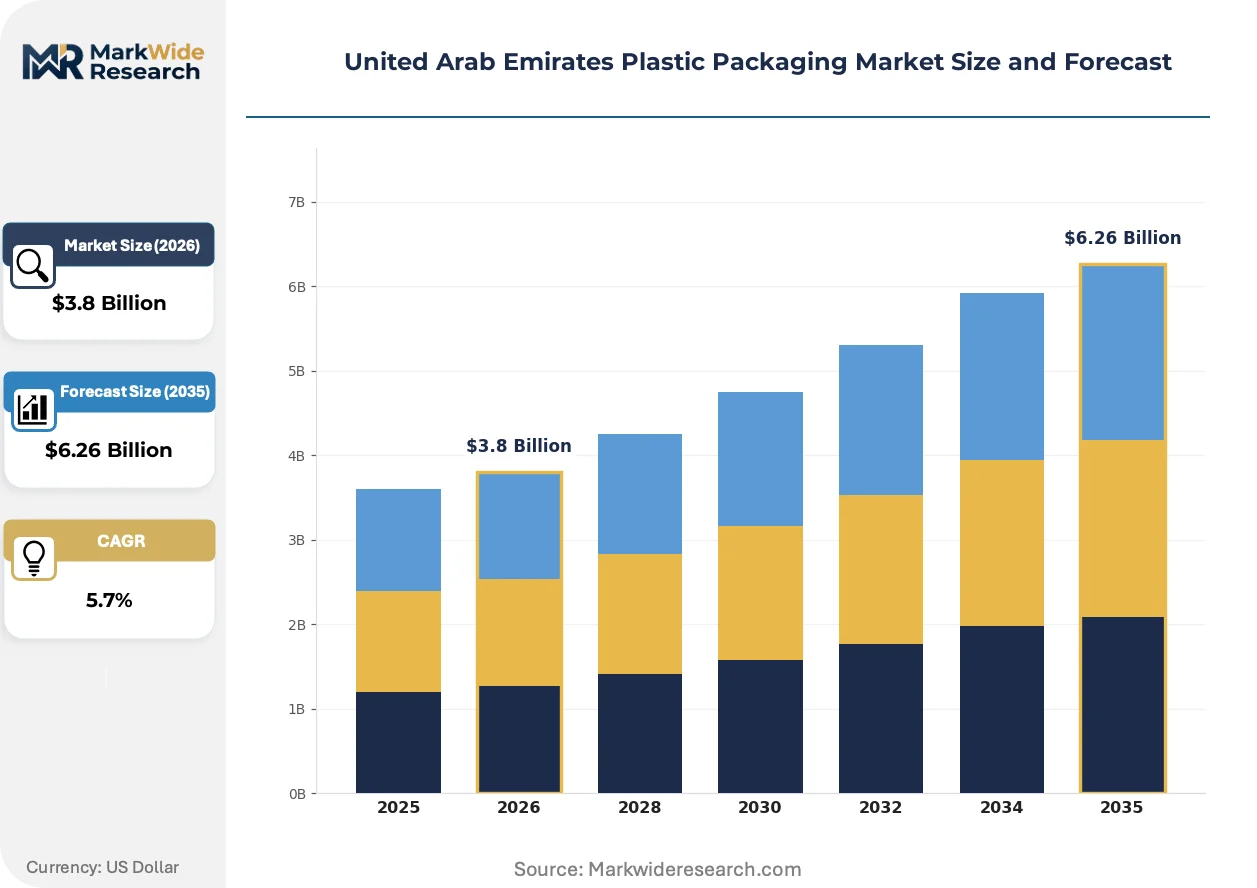
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Films, Bottles Material: Polyethylene, Polypropylene, PVC, Polystyrene End User: Food & Beverage, Healthcare, Consumer Goods, Industrial Application: Retail Packaging, Industrial Packaging, Food Packaging, Medical Packaging |
| Companies Covered | Integrated Plastics Packaging LLC, Swiss Pac UAE, Amber Packaging Industries LLC, Arabian Flexible Packaging LLC, Falcon Pack, Huhtamaki Flexibles UAE, ENPI Group, Hotpack Packaging Industries LLC, Mondi plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Plastic Packaging Market Evolving Landscape
Material hybridization and regulatory compliance automation are reshaping converter R&D priorities, with digital printing and track-and-trace integration emerging as competitive differentiators in premium food and pharmaceutical segments.
High-barrier polyethylene terephthalate glycol-modified films with enhanced oxygen scavenging are expanding into fresh meat and dairy packaging for UAE supermarket private labels. Retailers in Dubai and Abu Dhabi are specifying these structures for modified-atmosphere applications previously dominated by ethylene vinyl alcohol laminates. The technology is expanding into mid-tier price positions as Gulf Cooperation Council distribution networks extend shelf-life requirements.
MOHAP's 2024 guidance on pharmaceutical serialization and aggregation is mandating two-dimensional barcode integration at primary, secondary, and tertiary packaging levels. Contract packaging organizations serving multinational drug importers are retrofitting thermoforming and cartoning lines with vision systems and aggregation software. The regulation is compressing equipment upgrade timelines for free-zone converters supplying Ministry of Health and Prevention-regulated facilities.
Centralized procurement desks at UAE hospitality groups are consolidating specifications across hotel portfolios, replacing property-level purchasing with category-managed contracts. Procurement teams at Dubai-based international chains are mandating standardized disposable food service specifications with sustainability scorecards. The shift is visible in Abu Dhabi's Yas Island and Saadiyat Island developments, where master developers pre-qualify packaging suppliers for entire destination ecosystems.
United Arab Emirates Plastic Packaging Market Segmentation
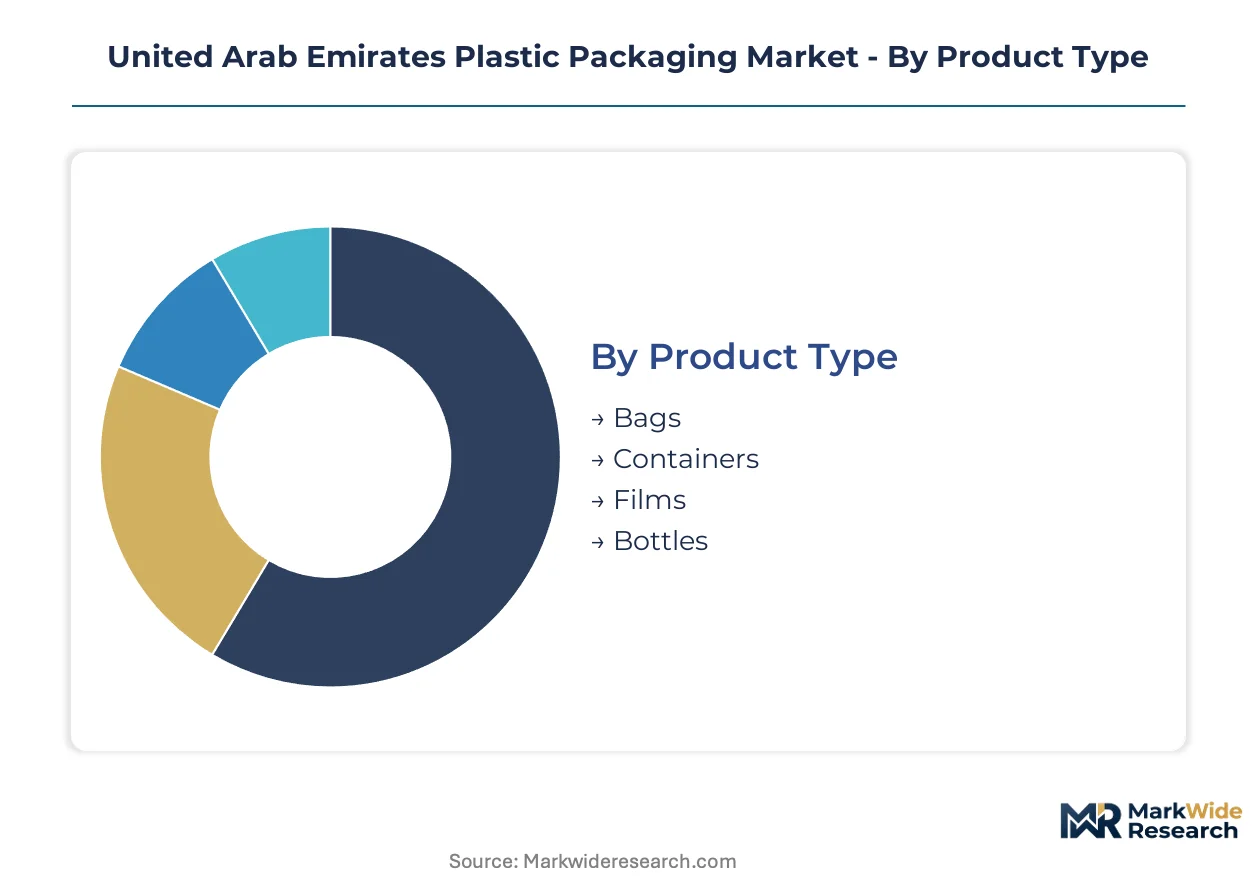
Segmentation in the UAE plastic packaging market reveals distinct capital requirements and margin profiles across product categories. Material specifications and end-use compliance standards determine converter investment priorities and free-zone location decisions.
Product Type:
Extrusion and thermoforming equipment intensity varies sharply across these categories, with blown film lines demanding the largest upfront capital commitments.
- Films:Blown and cast polyethylene films constitute the tonnage base for flexible food packaging. Dubai Industrial City hosts the densest concentration of multi-layer extrusion capacity serving quick-service restaurant chains and supermarket private labels.
- Containers:Injection-molded and thermoformed rigid structures capture premium margins in temperature-resistant applications. Abu Dhabi's Khalifa Industrial Zone is attracting dedicated polypropylene container lines for pharmaceutical and food service demand.
- Bags:T-shirt and gusseted polyethylene bags serve retail and waste management applications with lower barrier specifications.
- Bottles:Stretch blow-molded PET and HDPE bottles face substitution pressure from aluminum cans in beverage applications.
Films absorb the bulk of installed capacity; containers are expanding most quickly.
Material:
Polymer selection dictates processing equipment, regulatory qualification timelines, and exposure to feedstock import volatility.
- Polyethylene:Linear low-density and high-density grades dominate flexible packaging tonnage. Converters in Jebel Ali Free Zone rely on Saudi Aramco and Qatari resin supply, exposing margins to GCC feedstock pricing swings.
- Polypropylene:Homopolymer and random copolymer grades command premium positioning in hot-fill and retort applications. KIZAD-based converters are expanding biaxially oriented polypropylene capacity for snack and confectionery barrier requirements.
- Polystyrene:Crystal and high-impact grades serve disposable food service and electronics protective packaging with thinner margin profiles.
- PVC:Rigid and plasticized formulations retain niche positions in pharmaceutical blister packs and construction shrink film despite regulatory scrutiny.
Polyethylene commands the largest volume share; polypropylene offers the steepest expansion trajectory.
End User:
Customer consolidation patterns and compliance stringency separate high-investment healthcare segments from price-sensitive industrial applications.
- Food & Beverage:Flexible films and rigid containers for fresh, processed, and food service applications drive absolute demand. Dubai-based hospitality procurement desks are consolidating specifications across hotel portfolios toward standardized disposable packaging.
- Healthcare:High-barrier blister packs, cold-chain shippers, and sterile barrier systems exhibit the fastest structural expansion. MOHAP serialization mandates are forcing equipment upgrades at contract packaging organizations serving multinational drug importers.
- Consumer Goods:Personal care and household product packaging demands aesthetic differentiation through digital printing and specialty finishes.
- Industrial:Stretch film, drums, and intermediate bulk containers serve construction and petrochemical logistics with mature, price-sensitive characteristics.
Food & Beverage anchors volume consumption; Healthcare is gaining share fastest.
Application:
Distribution channel requirements and shelf-life specifications determine barrier complexity and printing investment levels.
- Food Packaging:Modified-atmosphere and vacuum structures for fresh meat, dairy, and ready meals demand oxygen scavenging and ethylene vinyl alcohol barrier layers. Retailers in Dubai and Abu Dhabi are specifying high-barrier PETG films for private label programs.
- Medical Packaging:Sterile barrier validation and MOHAP aggregation requirements demand cleanroom conversion environments and vision system integration. Free-zone converters near Dubai Logistics City are retrofitting lines for two-dimensional barcode compliance.
- Retail Packaging:Point-of-sale display and consumer convenience features prioritize digital printing and easy-open functionality.
- Industrial Packaging:Unitization and protection for palletized goods emphasizes tensile strength and UV stabilization over aesthetic properties.
Food Packaging concentrates converter capacity; Medical Packaging shows the steepest growth slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin supply from Saudi Aramco and Qatari producers anchors plastic packaging demand across Gulf Cooperation Council manufacturing zones. Dubai and Abu Dhabi free zones concentrate extrusion and thermoforming capacity serving food service and pharmaceutical logistics.
Dubai
Hotel chain procurement desks and quick-service restaurant groups are consolidating disposable packaging specifications across hospitality portfolios. Dubai Industrial City hosts the densest concentration of multi-layer blown film lines serving supermarket private labels. Jebel Ali Free Zone converters rely on bonded logistics corridors for GCC export distribution.
Abu Dhabi
Khalifa Industrial Zone pharmaceutical manufacturing incentives are pulling high-barrier blister pack and cold-chain shipper demand from healthcare logistics providers. MOHAP serialization mandates are forcing equipment upgrades at contract packaging organizations serving multinational drug importers. KIZAD-based converters are expanding biaxially oriented polypropylene capacity for snack barrier requirements.
Sharjah
Mid-tier extrusion capacity serves price-sensitive retail bag and industrial stretch film applications with thinner margin profiles. Sharjah's Hamriyah Free Zone offers utility subsidies attracting secondary processing operations from Dubai cost pressures. Local converters supply construction logistics packaging for Northern Emirates infrastructure projects.
Northern Emirates
Ras Al Khaimah and Fujairah manufacturing zones are capturing overflow thermoforming capacity from Dubai land cost escalation. Fujairah's port proximity offers freight advantages for resin import-dependent operations serving Omani and Saudi border markets. These emirates concentrate lower-specification food service disposables with reduced barrier requirements.
United Arab Emirates Plastic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty barrier and pharmaceutical-grade certifications. The vendor base clusters around three archetypes: integrated free-zone manufacturers with captive logistics advantages, multinational technology licensors leveraging formulation expertise, and regional specialists dominating disposable food service distribution. Competitive moves center on capacity expansion in KIZAD and Dubai Industrial City zones alongside strategic partnerships for post-consumer recycled resin supply security.
Among UAE-based integrated manufacturers, Integrated Plastics Packaging LLC exemplifies the domestic manufacturing archetype anchoring supply relationships with consolidated hospitality buyers. Huhtamaki Flexibles UAE represents multinational technology leadership in barrier film formulations. Hotpack Packaging Industries LLC occupies a position within the regional distribution-controlled segment spanning GCC retail networks.
| Leading Market Players |
|---|
| Integrated Plastics Packaging LLC |
| Swiss Pac UAE |
| Amber Packaging Industries LLC |
| Arabian Flexible Packaging LLC |
| Falcon Pack |
| Huhtamaki Flexibles UAE |
| ENPI Group |
| Hotpack Packaging Industries LLC |
| Mondi plc |
| Others |
Value Network & Pricing Analysis
Captive resin sourcing through Saudi Aramco and Qatari petrochemical producers anchors converter pricing power while exposing margins to GCC feedstock volatility and freight cost swings from Jebel Ali port operations.
Pricing Analysis
Service bundling separates converter tiers in the UAE market, with premium suppliers packaging ESMA conformity testing and MOHAP serialization validation into long-term contracts while economy players strip these to bare per-kilogram resin rates. Three-tier pricing structure across premium, standard, and economy levels tracks barrier complexity and regulatory certification depth. Cost compression in the standard tier is intensifying because hospitality procurement desks are consolidating volumes toward fewer suppliers with sustainability scorecard requirements. Quick-service restaurant chains exhibit the sharpest price sensitivity, while pharmaceutical contract packaging organizations show the least due to serialization compliance mandates.
Supply Chain Analysis
Polyethylene resin supply rests on Saudi Arabian and Qatari petrochemical producers, with specialty polypropylene additives drawing from German and Japanese chemical suppliers. Blown film converters depend on linear low-density polyethylene, high-density polyethylene, and ethylene vinyl alcohol copolymers as core inputs. Single-source vulnerability concentrates in Saudi Aramco's dominance of LLDPE supply to Jebel Ali Free Zone extruders. Distribution runs through bonded logistics corridors at Dubai Industrial City and KIZAD, with final-mile delivery via GCC retail and food service distribution networks controlled by regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE plastic packaging market is becoming a vertical-integration race, with players pursuing backward integration into post-consumer recycled resin supply to secure ESMA-compliant feedstock ahead of biodegradable content mandates.
For Market Incumbents: Hedge against aluminum can substitution in beverage applications by expanding barrier-coated paper laminate capacity for quick-service restaurant chains. Secure long-term offtake agreements with Saudi Aramco for virgin resin while building captive mechanical recycling lines to meet emerging renewable content thresholds. Channel control through GCC retail distribution partnerships remains essential as hospitality procurement desks consolidate supplier panels.
For New Entrants and Emerging Players: E-commerce-enabled direct sourcing platforms offer the most penetrable route into mid-tier supermarket private label programs that incumbent converters underserve with legacy minimum order quantities. Target pharmaceutical contract packaging organizations in Khalifa Industrial Zone that lack local high-barrier blister pack capacity. Lead with digital printing and short-run customization capabilities to bypass incumbent tooling cost advantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational packaging conglomerates seeking GCC manufacturing footholds. The five-to-ten year viability window favors converters with MOHAP-certified pharmaceutical lines and established free-zone logistics access. Acquisition target archetypes are mid-scale extruders with underutilized thermoforming assets and ESMA testing laboratory relationships. Watch ESMA's finalization of mandatory renewable content percentages as the critical inflection trigger for compostable line investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Recycled Resin | Captive supply of ESMA-compliant feedstock secures converter positioning ahead of biodegradable mandates from the UAE Ministry of Climate Change and Environment. |
| Pharmaceutical Serialization Line Retrofit | MOHAP aggregation requirements for two-dimensional barcodes pull equipment upgrade demand at Dubai Logistics City contract packaging organizations. |
| Barrier Film and Paper Hybridization Capacity | Aqueous coating technology convergence enables heat-sealable fiber-based packaging for quick-service restaurant chains seeking plastic reduction pathways. |
| KIZAD Free-Zone Manufacturing Expansion | Customs exemptions and utility subsidies at Khalifa Industrial Zone anchor polypropylene container lines for pharmaceutical and food service demand. |
| Reverse Vending Service Contract Integration | The UAE deposit-return scheme pilot for plastic bottles opens sorting and reprocessing equipment opportunities alongside core converter operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, combining structured interviews with extrusion plant managers, procurement leads at hospitality groups, ESMA conformity assessment officers, and distribution channel partners with validation against Gulf Standards Organization technical regulations, MOHAP pharmaceutical packaging guidelines, and UAE Ministry of Climate Change and Environment policy documents. Bottom-up capacity modeling at individual free-zone facilities triangulated against top-down consumption estimates derived from food and beverage production statistics.
Segment-level granularity modeled product type splits across films, containers, bags, and bottles; material grades spanning polyethylene, polypropylene, polystyrene, and PVC; and end-use applications in food service, healthcare, consumer goods, and industrial logistics. CAGRs across the analysis window derived from elasticity-adjusted demand projections incorporating polymer price scenarios and regulatory compliance cost trajectories. Forecast inputs included quick-service restaurant outlet expansion rates, pharmaceutical import growth patterns, and hospitality procurement desk consolidation timelines.
The model holds under stable GCC resin supply relationships and gradual ESMA threshold implementation; deviation in Saudi Aramco pricing volatility or sudden biodegradable mandate acceleration would shift converter margin recovery windows. Forecasts reflect assumptions on free-zone incentive continuity and MOHAP serialization enforcement intensity. A small set of named triggers—ESMA renewable content finalization, aluminum can substitution velocity, and KIZAD utility subsidy duration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market