
 Global Plastic Container Market | 2026-2036
Global Plastic Container Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Container Market Foresight
Multi-source resin procurement is realigning how converters manage polyethylene terephthalate and polypropylene cost volatility. Amcor Plc leverages its global manufacturing footprint to sustain supply continuity across multiple geographies. Berry Global anchors North American food packaging demand through specialized jar and tub production lines. Graham Packaging Company differentiates via blow-molding expertise for complex bottle geometries in beverage applications.
A plastic container is a formed polymer vessel typically manufactured through injection blow molding, extrusion blow molding, or thermoforming, with wall thicknesses engineered for specific barrier, stackability, and drop-resistance requirements; these containers store, transport, and dispense solids, liquids, and semi-solids across industrial and consumer supply chains. Bottles command the largest volume share within product type segmentation due to pervasive use in carbonated soft drinks, personal care, and pharmaceutical liquids. Polyethylene terephthalate leads material selection for its clarity, recyclability infrastructure, and compatibility with existing filling equipment, while polypropylene gains ground in hot-fill and retort applications requiring higher thermal tolerance.
The US FDA regulates food-contact substances under 21 CFR, while the EPA oversees resin manufacturing emissions and chemical safety assessments that affect polymer cost structures. Europe's ECHA administers REACH restrictions on substances of very high concern, directly limiting certain plasticizers and stabilizers in container formulations. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates to determine capital allocation between virgin resin conversion lines and post-consumer recycling integration.
Market Dynamics
Recycled content mandates under the EU Green Deal are forcing converters to reconfigure resin procurement and retrofit extrusion lines, compressing margins while creating first-mover advantages for integrated recyclers.
Growth Catalysts
- Lightweighting in beverage packaging:Polyethylene terephthalate bottle weights have dropped 30% since 2000, cutting transport costs and resin consumption for carbonated soft drink bottlers.
- EU packaging waste directives:Mandatory recycled content minimums are accelerating post-consumer recycling infrastructure buildout across member states.
- India:Dairy and edible oil processors are replacing metal and glass with polymer pails and jars, expanding addressable volume for blow-molded containers.
Market Restraints
- Resin price volatility:Crude oil and natural gas feedstock swings compress converter margins unpredictably, especially for small-batch polypropylene tub manufacturers.
- China concentration:Virgin polyethylene terephthalate resin supply clusters with state-controlled petrochemical complexes, creating geographic single-source risk.
- Barrier limitations:Standard polyethylene terephthalate oxygen transmission rates restrict shelf life for sensitive nutraceuticals, capping penetration in high-value pharmaceutical liquids.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization technologies promise food-grade recycled content beyond mechanical recycling quality ceilings.
- Hot-fill polypropylene:Retort-ready jars are displacing glass in ready-meal applications where thermal tolerance exceeds polyethylene terephthalate limits.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz and similar laws in France and Italy create compliance-service revenue streams for integrated packaging groups.
Industry Challenges
- Recycling contamination control:Sorting facility operators struggle to meet brand-owner specifications for food-contact post-consumer resin, raising rejection rates.
- Legacy equipment retrofit costs:Converters face capital intensity for extrusion line modifications to process higher recycled content without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Container Market |
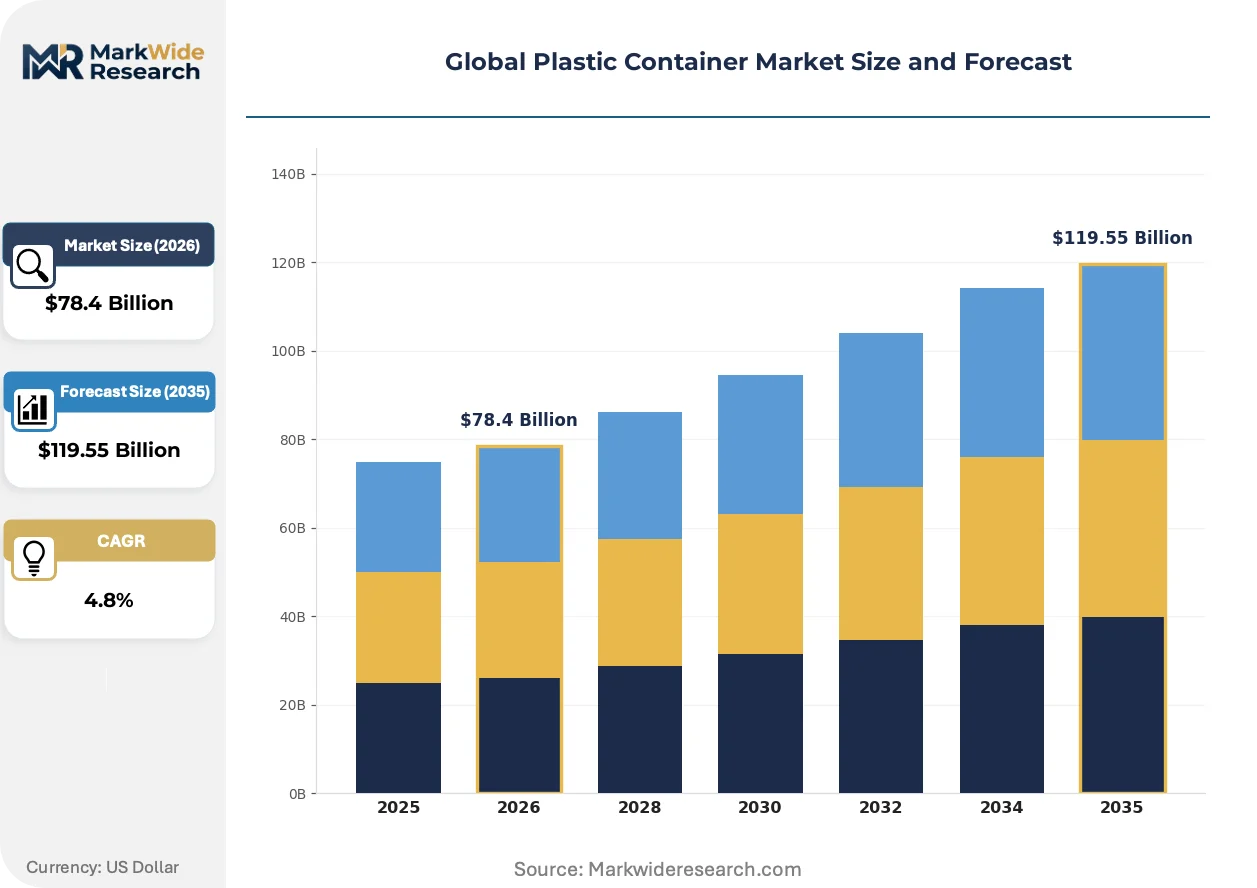
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tubs, Pails Material: Polyethylene Terephthalate, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Healthcare, Household, Industrial Sales Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Plastipak Holdings, Pretium Packaging, Amcor Plc, Time Technoplast, Altium Packaging, Berry Global, Graham Packaging Company, Shanghai Zijiang Enterprise Group, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Container Market Shifts & Advancements
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability, reshaping how converters compete on customization speed versus unit economics.
Mono-material polyethylene terephthalate structures with detachable labels and compatible closures are modularizing the recycling stream, simplifying sortation at materials recovery facilities. Food brands in Germany and the Netherlands are piloting these designs for private-label water and juice lines. The structural consequence is collapsing the cost premium for circular-design packaging to near-parity with conventional multi-layer alternatives.
REACH restrictions administered by ECHA on substances of very high concern are eliminating certain phthalate plasticizers and heavy-metal stabilizers from container formulations. Compounders must reformulate color concentrates and impact modifiers to maintain clarity and drop resistance. Personal care and cosmetics segments face the steepest compliance timelines, with some brands accelerating transitions to non-phthalate alternatives ahead of 2025 authorization deadlines.
Brand-owner buying committees are consolidating resin procurement across multiple bottle SKUs, compressing supplier rosters and demanding volume commitments in exchange for specification influence. This concentration is displacing spot-market purchasing for polyethylene terephthalate in North American beverage applications. The shift is most visible among multinational CPG groups with centralized sustainability targets requiring supply chain transparency documentation.
Global Plastic Container Market Segmentation
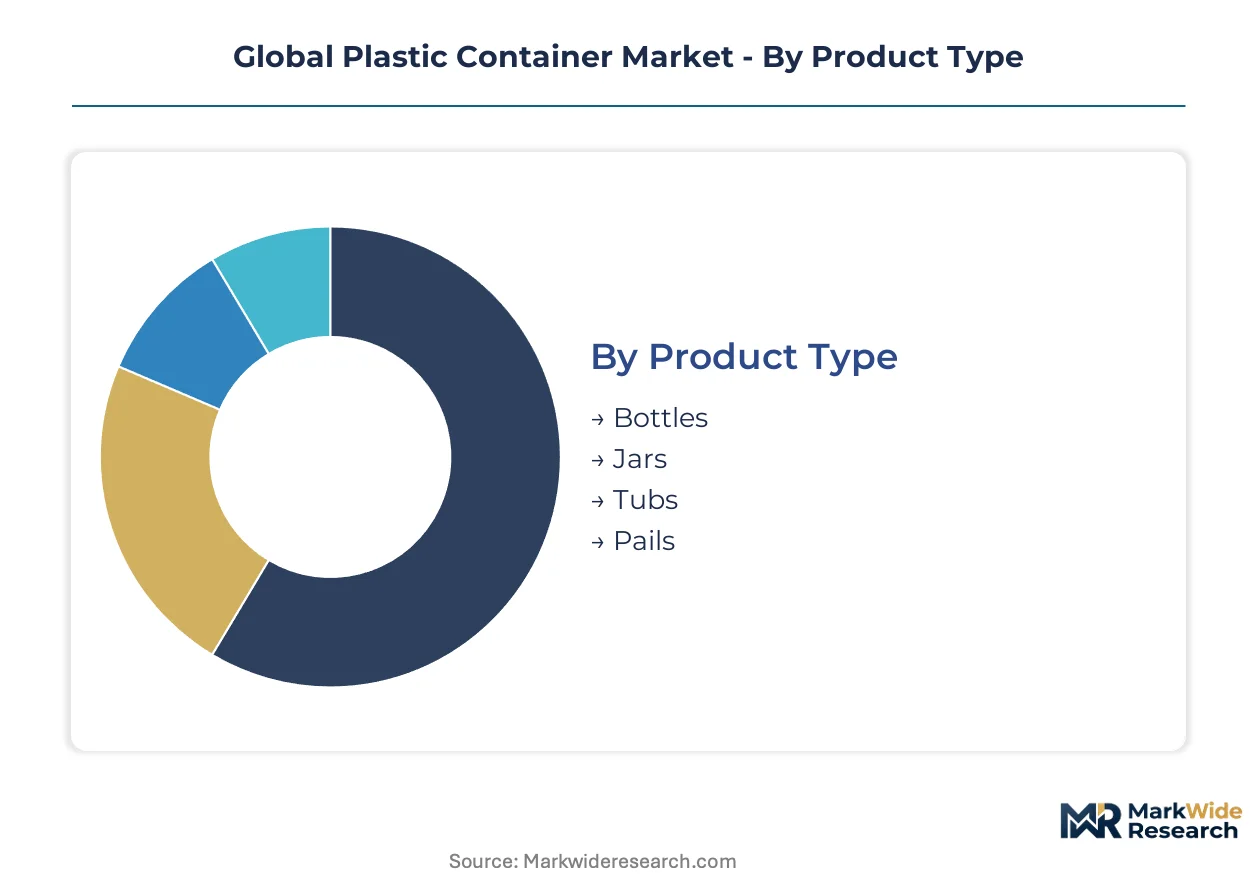
Converters configure production assets around distinct demand profiles. Product geometry, resin selection, and end-use specifications determine line investments and margin structures. Segment boundaries are blurring as multi-functional containers displace single-purpose formats.
Product Type:
Buyers prioritize dimensional precision, stack density, and filling-line compatibility when selecting formats.
- Bottles:Thin-walled cylindrical vessels engineered for carbonated soft drinks, personal care liquids, and pharmaceutical solutions. Demand concentrates in India's ready-to-drink beverage sector where lightweight polyethylene terephthalate formats displace glass. Filling-line speed requirements favor standardized neck finishes.
- Jars:Wide-mouth cylindrical containers with threaded or lug closures for viscous products and solid contents. Germany's private-label food brands are piloting mono-material designs with detachable labels to satisfy ECHA sorting requirements. Thermal tolerance specifications separate hot-fill from ambient applications.
- Tubs:Short cylindrical vessels with snap-fit or threaded lids for dairy, spreads, and ready-meals. Margins compress in polypropylene retort applications where barrier additives raise material costs.
- Pails:Industrial-grade containers with integrated handles for chemicals, coatings, and edible oils. India's dairy processors are shifting from metal to polymer pails for transport efficiency.
Bottles lead volumes today; jars are gaining share fastest through food-sector specification changes.
Material:
Resin selection hinges on clarity requirements, thermal tolerance, and recycling infrastructure compatibility.
- Polyethylene Terephthalate:Transparent polyester with established mechanical recycling streams and food-contact regulatory clearance. EU Green Deal mandates are forcing converters toward post-consumer content minimums. Bottled water and carbonated soft drink brands specify this resin for optical clarity and drop resistance.
- Polypropylene:Semi-crystalline olefin with superior hot-fill and retort tolerance. India's edible oil processors specify polypropylene pails where thermal stability exceeds polyethylene terephthalate limits. Random copolymer grades enable transparency in premium cosmetic jars.
- Polyvinyl Chloride:Rigid polymer with excellent barrier properties for pharmaceutical blister packs and chemical containment. REACH restrictions on plasticizer migration limit food-contact applications.
- Polystyrene:Amorphous resin valued for dimensional stability in dairy tubs and laboratory ware. Virgin resin demand is contracting as brand-owners eliminate non-recyclable formats from sustainability commitments.
Polyethylene terephthalate dominates current procurement; polypropylene is climbing the fastest on hot-fill specification expansion.
End User:
Regulatory exposure and volume predictability separate attractive customer segments.
- Food & Beverage:The largest demand pool spanning carbonated drinks, dairy, edible oils, and ready-meals. FDA 21 CFR compliance requirements and EU packaging waste directives shape converter qualification processes. India's dairy sector is replacing metal and glass with polymer alternatives.
- Healthcare:Pharmaceutical liquids, nutraceuticals, and medical devices requiring barrier precision and extractables documentation. Oxygen transmission rate limitations in standard polyethylene terephthalate restrict shelf-life for sensitive formulations.
- Household:Cleaning products, personal care, and cosmetics with diverse closure and dispensing requirements. ECHA phthalate restrictions are accelerating transitions to non-phthalate plasticizers ahead of authorization deadlines.
- Industrial:Chemicals, lubricants, and agricultural inputs prioritizing stack strength and UN certification. Volume concentration with large-format pail specifications.
Food & Beverage anchors procurement volumes; Healthcare shows the steepest expansion trajectory on barrier technology investments.
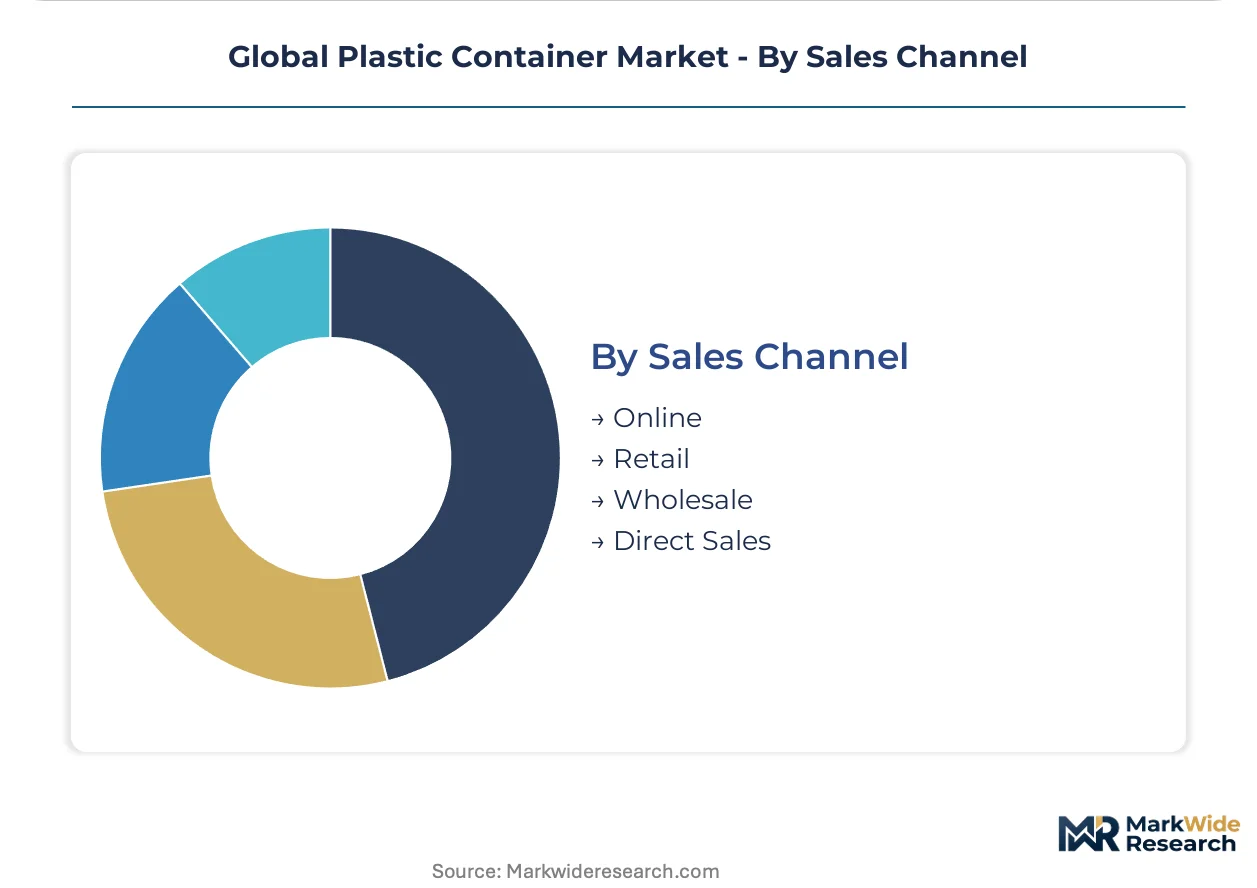
Sales Channel:
Order scale and customization requirements determine channel economics.
- Online:Digital procurement platforms enabling spot purchasing for standardized SKUs. Minimum order quantities compress as digital printing reduces setup costs.
- Retail:Big-box and specialty store distribution for consumer-facing container sales. Shelf-ready packaging requirements influence secondary containment specifications.
- Wholesale:Distributor networks aggregating demand from mid-size converters and regional brand-owners. Inventory pooling reduces resin price volatility exposure.
- Direct Sales:Long-term contracts with multinational CPG groups requiring supply chain transparency documentation. Centralized sustainability targets consolidate supplier rosters.
Direct Sales commands the largest contract values; Online is expanding most quickly on digital infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's petrochemical corridor supplies virgin polyethylene terephthalate resin to converters across South Asia. National regulators are tightening packaging waste rules. City-level industrial clusters are retrofitting extrusion lines for post-consumer recycled content.
United States
Carbonated soft drink bottlers in Georgia and Texas drive lightweight polyethylene terephthalate bottle procurement. The FDA's 21 CFR food-contact substance regulations govern resin selection and additive clearance. Chicago-area converters are expanding blow-molding capacity for dairy and ready-to-drink beverage brands.
Germany
Private-label food brands specify mono-material jar designs with detachable labels for simplified recycling streams. The Verpackungsgesetz mandates extended producer responsibility compliance and minimum recycled content thresholds. The Rhine-Ruhr industrial belt hosts integrated packaging groups retrofitting lines for post-consumer resin processing.
India
Dairy processors in Maharashtra and Gujarat are replacing metal pails with polymer alternatives for edible oil and milk transport. The FSSAI enforces food-contact safety standards for polymer migration limits. Ahmedabad's converter cluster is scaling blow-molded container output for regional edible oil brands.
China
State-controlled petrochemical complexes in Jiangsu and Zhejiang concentrate virgin polyethylene terephthalate resin supply. The MIIT oversees industrial standards for packaging materials and recycling infrastructure development. The Yangtze River Delta converter base is expanding thermoforming capacity for food-grade applications.
Brazil
Edible oil and beverage processors in São Paulo state specify high-clarity polyethylene terephthalate bottles for retail shelf presence. ANVISA regulates pharmaceutical and food-contact polymer safety assessments. The ABC Paulista industrial zone hosts blow-molding specialists serving multinational CPG groups.
Global Plastic Container Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling integration and mono-material design patents. The vendor base organizes around three archetypes: integrated resin-to-container conglomerates with global manufacturing footprints, regional blow-molding specialists serving single-country beverage markets, and technology-focused compounders developing barrier-enhanced formulations. Dominant competitive moves include backward integration into post-consumer recycling streams and strategic partnerships with brand-owners for co-developed sustainable packaging specifications.
Among diversified packaging conglomerates, Amcor Plc and Berry Global exemplify the scale-driven archetype with multi-continent production networks. ALPLA Group represents the family-owned specialist model with concentrated blow-molding expertise. Time Technoplast anchors the emerging-market regional champion position, while Shanghai Zijiang Enterprise Group occupies a position within Asia-Pacific resin-to-container supply chains. These named entities serve as reference points for understanding how competitive positioning stratifies across geographic and capability dimensions.
| Leading Market Players |
|---|
| Plastipak Holdings |
| Pretium Packaging |
| Amcor Plc |
| Time Technoplast |
| Altium Packaging |
| Berry Global |
| Graham Packaging Company |
| Shanghai Zijiang Enterprise Group |
| ALPLA Group |
| Others |
Supply & Pricing Matrix
Virgin polyethylene terephthalate resin costs cascade through converter pricing tiers, with feedstock volatility from Jiangsu and Zhejiang petrochemical complexes compressing margins for spot-market buyers while contract-heavy beverage bottlers lock in stability. The pass-through mechanics separate integrated recyclers with captive post-consumer resin supply from converters exposed to virgin resin spot markets.
Pricing Analysis
Input-cost pass-through dominates converter pricing, with crude oil and natural gas feedstock swings transmitting directly to polyethylene terephthalate and polypropylene contract negotiations. Three-tier pricing structure across premium, standard, and economy levels separates brand-owners with volume commitments and specification influence from spot purchasers facing margin compression. Pricing pressure stems from EU Green Deal recycled content mandates forcing extrusion line retrofits. Small-batch polypropylene tub manufacturers exhibit highest price sensitivity; multinational CPG groups with centralized procurement show lowest.
Supply Chain Analysis
Reverse-logistics flows for post-consumer container collection and mechanical recycling are consolidating around Germany's Verpackungsgesetz compliance infrastructure and EU extended producer responsibility frameworks. Virgin resin supply concentrates in China, India, and the United States, with Gujarat's petrochemical corridor feeding South Asian converter demand. Raw material dependencies rest on paraxylene and ethylene feedstocks, plus imported catalyst systems for barrier additive formulations. Single-source vulnerability runs through state-controlled Chinese petrochemical complexes. Distribution runs through direct sales contracts with multinational CPG groups and wholesale distributor networks aggregating regional brand-owner demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Plastic Container Market functions as a stable compounder, with regulatory mandates for recycled content minimums generating predictable retrofit demand and infrastructure investment cycles.
For Market Incumbents: To counter margin compression from resin price volatility, Amcor Plc and Berry Global should deepen backward integration into post-consumer recycling streams and secure long-term offtake agreements with brand-owners requiring supply chain transparency documentation. Capacity additions in India's Ahmedabad converter cluster capture dairy and edible oil processor demand shifting from metal and glass. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting mid-size converters with standardized SKU spot purchasing, where minimum order quantity compression from digital printing reduces setup cost barriers. India's regional edible oil brands represent the most penetrable segment, underserved by multinational infrastructure. Chemical recycling scale-up partnerships with pyrolysis technology developers offer differentiation beyond mechanical recycling quality ceilings. For Investors and Strategic Acquirers: Consolidation pressure builds where converters lack integrated recycling capabilities and face EU Green Deal compliance deadlines without capital for extrusion line retrofits. The 5-10 year viability window favors integrated resin-to-container conglomerates with multi-continent production networks. Acquisition targets include regional blow-molding specialists in single-country beverage markets lacking post-consumer recycling integration. Monitor Germany's Verpackungsgesetz enforcement intensity and India's FSSAI packaging waste rule tightening as inflection indicators for compliance-service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captures EU Green Deal compliance revenue streams and insulates against virgin resin volatility. |
| Mono-Material Design Patenting | Secures first-mover positioning for ECHA-compliant detachable-label jar specifications in Germany. |
| Hot-Fill Polypropylene Capacity Expansion | Displaces glass in retort-ready ready-meal applications where thermal tolerance exceeds polyethylene terephthalate limits. |
| Digital Printing Infrastructure Deployment | Compresses minimum order quantities and enables batch-level traceability for customization-speed competition. |
| Chemical Recycling Joint Venture | Unlocks food-grade recycled content beyond mechanical recycling quality ceilings for sensitive pharmaceutical liquids. |
Research Methodology
Direct dialogue with blow-molding plant managers, resin procurement leads at beverage converters, distribution channel partners, and technical R&D directors at compounder facilities grounded qualitative insights. Secondary validation drew from customs and trade data, SEC 10-K filings of listed packaging conglomerates, EU ECHA REACH restriction updates, and FDA 21 CFR food-contact substance registrations. Bottom-up and top-down triangulation cross-checked converter capacity announcements against brand-owner volume commitments.
Bottom-up modeling aggregated individual converter line investments and resin procurement patterns across the projection horizon, while top-down analysis tracked EU packaging waste directive implementation timelines and India's dairy sector polymer substitution rates. Segmentation dimensions included product geometry, resin selection, end-use regulatory exposure, and regional recycling infrastructure maturity. CAGRs were derived from weighted average of historical volume trajectories and policy-mandated substitution elasticities, with specific inputs from FSSAI enforcement intensity in Maharashtra and Gujarat and Verpackungsgesetz compliance cost pass-through rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude oil price volatility spikes or accelerated EU recycled content threshold escalations. Practitioners should monitor ECHA authorization deadline enforcement for phthalate alternatives and China's MIIT industrial standard revisions for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Vacuum Forming Plastic Market