
 Africa BOPP Films Market | 2026-2036
Africa BOPP Films Market Size, Share, and Industry Trends Forecast 2026-2036
Africa BOPP Films Market Outlook
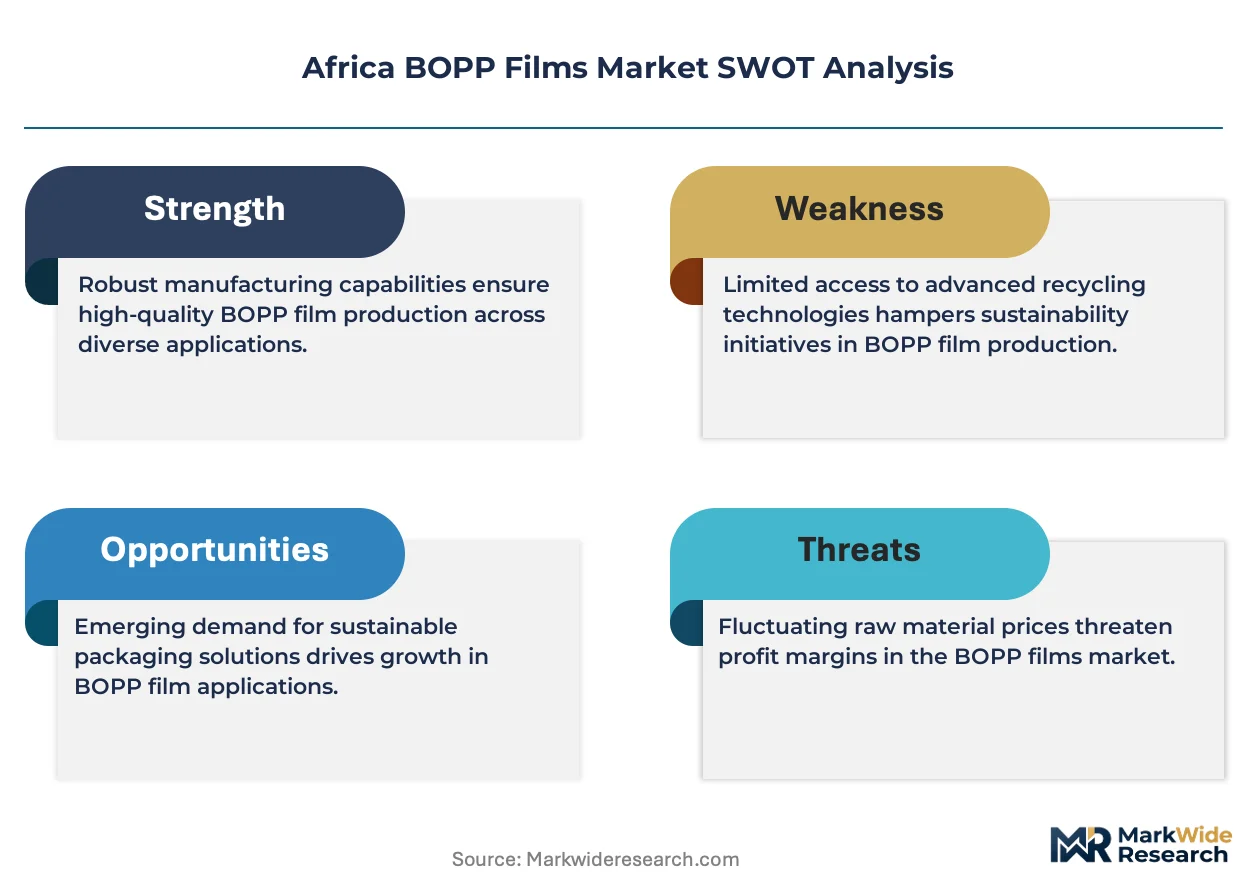
Buyer consolidation among pan-African fast-moving consumer goods groups is repositioning contract structures toward volume-commitment frameworks with regional film converters. Taghleef Industries S.A.E. leverages its Egyptian production base to supply North African packaging houses with metallized grades. Flex Films anchors its competitive stance through backward integration into resin sourcing, while Cosmo Films Ltd differentiates via specialized thermal lamination films for premium label applications.
Biaxially oriented polypropylene film is a thermoplastic polymer sheet stretched in both machine and transverse directions to achieve uniform thickness, high tensile strength, and moisture barrier properties typically ranging from eight to fifty microns. The manufacturing process creates a crystalline structure that delivers optical clarity and printability for flexible packaging substrates. Packaging Films dominates current volume flows across the continent, though Labels captures expanding margin pools as pharmaceutical serialization requirements spread. Cast Film manufacturing leads in installed capacity, while Extrusion Coating lines are attracting fresh capital for barrier-enhanced food pouch structures.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that compel converters to certify recyclability pathways for multilayer flexible packaging. Egypt's Egyptian Organization for Standardization and Quality aligns BOPP film imports with harmonized African standards for food-contact materials. Nigeria's National Agency for Food and Drug Administration and Control monitors migration limits in printed films for edible oil sachets. Stakeholders must track how evolving national standards on recyclability and food-contact compliance reshape supplier qualification criteria across the continent's fragmented regulatory landscape.
Market Dynamics
Extended producer responsibility frameworks across South Africa and Egypt are forcing converters to redesign multilayer structures into recyclable mono-material formats, redirecting capital flows toward metallization and coating line upgrades.
Growth Catalysts
- Snack food packaging upgrade cycle:Nigerian processors in the Lagos-Ibadan corridor are replacing polyethylene with BOPP laminate solutions for moisture-sensitive products.
- Extended Producer Responsibility regulations:South Africa's Department of Forestry, Fisheries and the Environment mandates certified recyclability pathways for flexible packaging, accelerating converter investment in compatible film grades.
- Pharmaceutical serialization compliance:Egypt's pharmaceutical sector is adopting high-clarity thermal lamination films to meet track-and-trace labeling requirements.
Market Restraints
- Propylene feedstock volatility:Regional polymer supply depends on imported monomer, exposing converters to currency-driven margin compression.
- Multilayer incompatibility with recycling infrastructure:Existing collection and reprocessing systems cannot handle barrier-enhanced pouch structures, creating stranded asset risk for legacy equipment.
- Harmonization gaps in food-contact standards:Misalignment between Egypt's EOSQ requirements and Nigeria's NAFDAC migration limits complicates cross-border product qualification.
Strategic Opportunities
- East African high-clarity film penetration:Kenyan and Tanzanian food packaging processors remain undersupplied relative to West African counterparts, creating first-mover positioning for regional converters.
- Metallized barrier film adoption:Extended shelf-life requirements for edible oil sachets in humid climates are driving specification shifts toward vapor-deposited aluminum coatings.
- Mono-material structure incentives:South African EPR frameworks reward certified recyclable packaging with reduced compliance fees, tilting procurement toward compatible substrate suppliers.
Industry Challenges
- Coextrusion technician scarcity:The specialized skill set for controlling transverse-direction stretching ratios remains concentrated among veteran operators at established Egyptian and South African facilities.
- Barrier coating capex intensity:Vacuum metallization and extrusion coating lines require significant capital deployment, limiting mid-scale converter participation in premium-grade segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa BOPP Films Market |
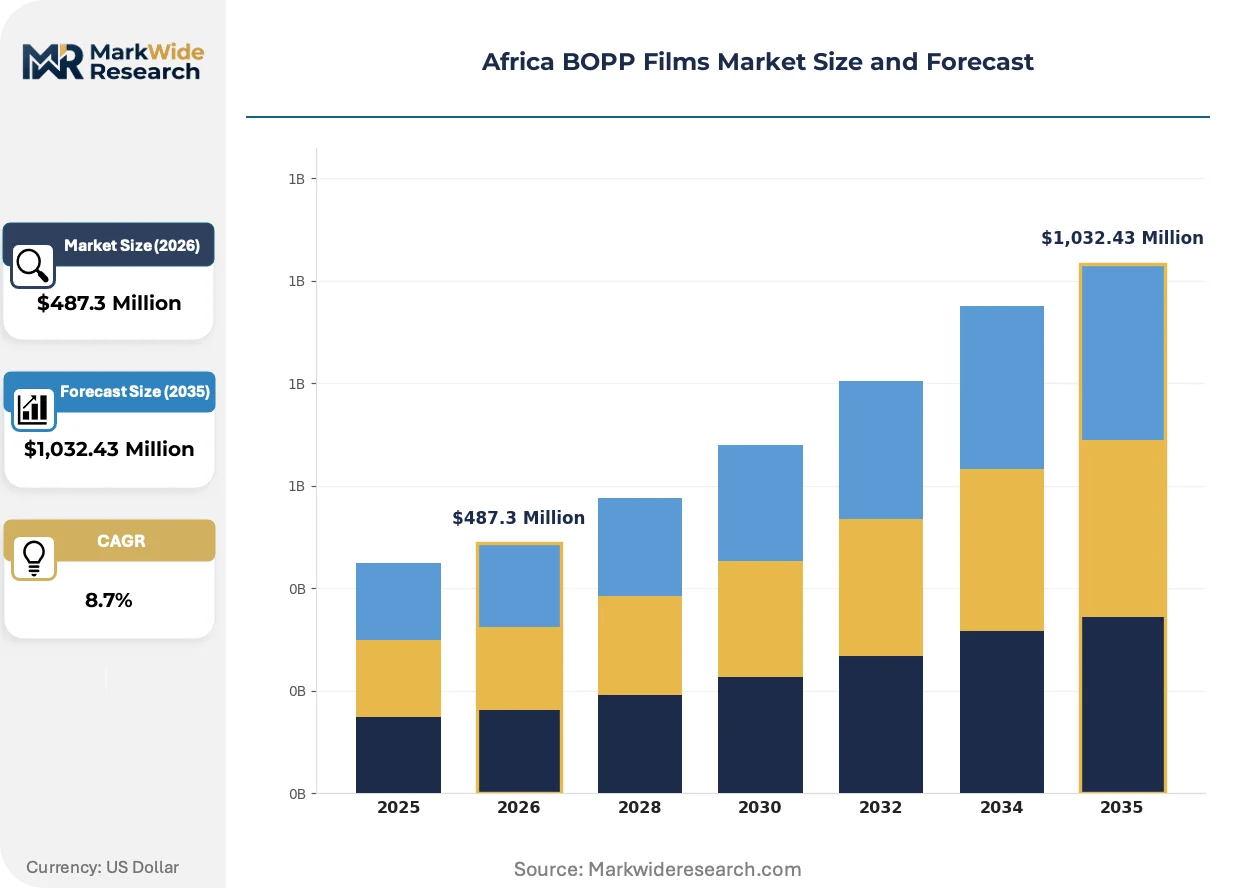
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaging Films, Labels, Adhesive Tapes, Thermal Films End Use Industry: Food Packaging, Consumer Goods, Electronics, Medical Applications Manufacturing Process: Cast Film, Blow Film, Extrusion Coating, Lamination Thickness: Low Gauge, Medium Gauge, High Gauge, Ultra-Thin |
| Companies Covered | Taghleef Industries S.A.E., Flex Films, Cosmo Films Ltd, SABIC, Jindal Films, UFlex Ltd., COPACK Company, elm films, Innovia Films, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa BOPP Films Market Strategic Shifts
Equipment modularity and regulatory compliance automation are compressing product development cycles while enabling smaller batch production of certified food-contact grades.
Digital printing integration with BOPP substrates is modularizing converter operations by allowing rapid job changeovers without plate costs. Pan-African fast-moving consumer goods groups are piloting this capability for seasonal promotional packaging. The technology is compressing minimum viable order quantities and enabling regional distributed production models.
South Africa's EPR regulations now require documented recyclability pathways for all flexible packaging placed on market. Converters must certify mono-material structures or face escalating compliance fees. The pharmaceutical and edible oil segments are responding fastest, with Lagos-based sachet producers already qualifying alternative substrate specifications.
Buyer consolidation among multinational consumer goods groups is compressing contract renewal cycles and unbundling technical service from material supply agreements. Regional converters now compete on qualification speed rather than sole-source relationships. This pattern is most visible in Nigeria's snack food sector, where procurement teams rotate suppliers annually to benchmark total cost of ownership.
Africa BOPP Films Market Segmentation
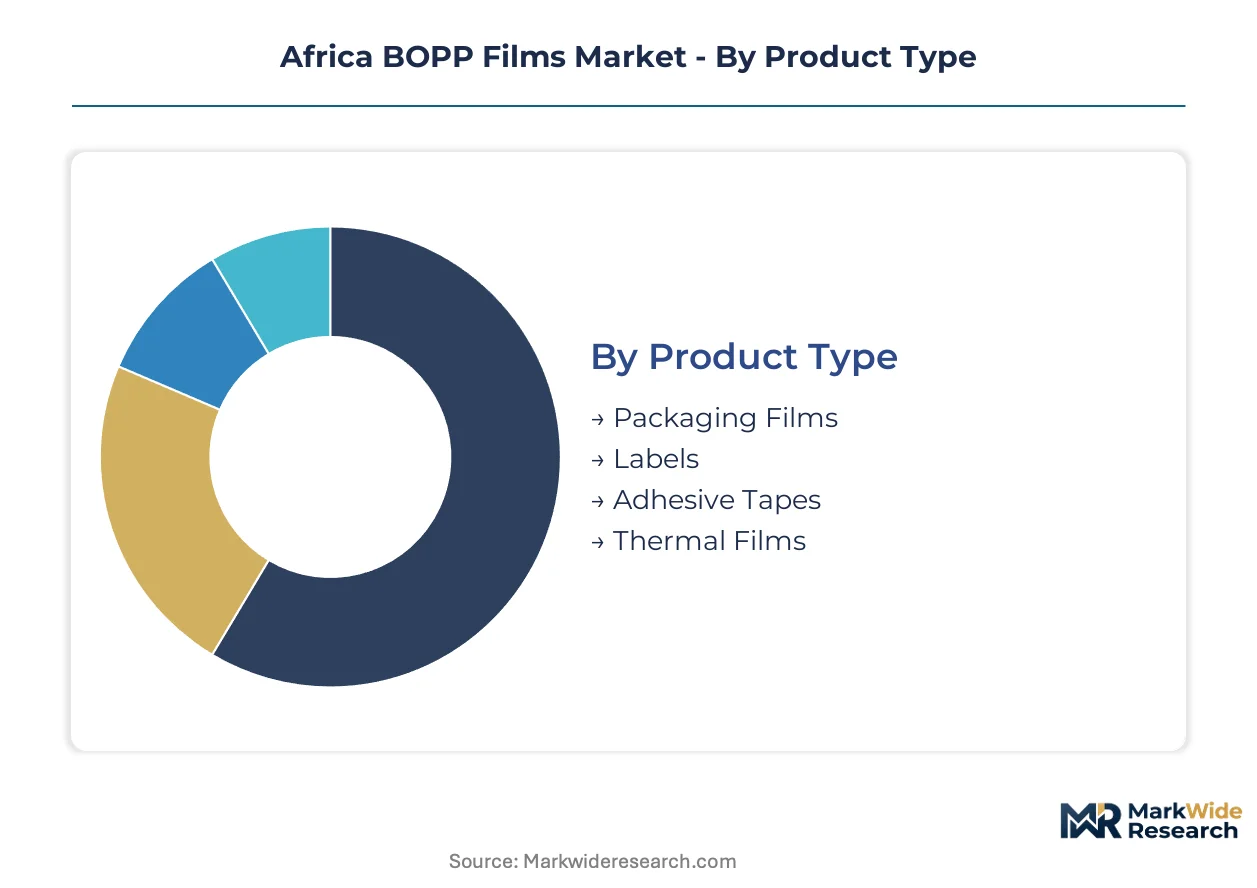
Segmentation in the Africa BOPP Films Market reveals how substrate specifications align with distinct value chain positions. Product type and manufacturing process determine whether films serve as standalone packaging or embedded barrier layers, while end-use and thickness dimensions capture margin differentiation across application tiers.
Product Type:
Packaging Films operate as standalone primary substrates, while Labels and Adhesive Tapes embed into downstream converting systems; Thermal Films bridge both integration modes through lamination applications.
- Packaging Films:These biaxially oriented sheets deliver moisture barriers and optical clarity for flexible food pouches. Nigerian snack producers in the Lagos-Ibadan corridor specify these grades for moisture-sensitive products, driving volume commitments toward high-clarity variants.
- Labels:Specialized facestocks enable pharmaceutical serialization compliance through thermal transfer printability. Egypt's pharmaceutical sector is adopting these grades to meet track-and-trace requirements, expanding margin pools faster than commodity packaging segments.
- Adhesive Tapes:Pressure-sensitive constructions serve carton sealing and industrial bonding applications.
- Thermal Films:Heat-activated adhesive layers bond to printed substrates for premium label protection.
Volume placements concentrate in Packaging Films; the faster expansion belongs to Labels.
End Use Industry:
Food Packaging commands the largest substrate throughput, while Medical Applications and Electronics represent premium specification tiers with tighter compliance requirements.
- Food Packaging:Edible oil sachets and snack pouches absorb the majority of regional BOPP film output. Kenya's processors are scaling purchases of high-clarity grades as they upgrade from polyethylene, though capacity lags West African counterparts.
- Consumer Goods:Personal care and household product wrappers require print-ready surfaces with consistent gauge control.
- Electronics:Anti-static and moisture-barrier specifications protect sensitive components during regional distribution.
- Medical Applications:Sterile barrier properties and migration-compliant formulations serve pharmaceutical blister packs and device packaging. South Africa's EPR frameworks are accelerating qualification of mono-material structures in this segment to avoid escalating compliance fees.
Food Packaging absorbs the highest tonnage; Medical Applications are climbing the fastest as serialization mandates spread.
Manufacturing Process:
Cast Film and Blow Film represent mature installed bases with distinct cost structures, while Extrusion Coating and Lamination lines attract fresh capital for barrier-enhanced configurations.
- Cast Film:Chilled roll quenching produces uniform gauges with high optical clarity at scale. Egyptian facilities anchor regional supply through this process, serving North African packaging houses with metallized grades.
- Blow Film:Tubular orientation creates balanced mechanical properties for heavy-duty applications. South African converters leverage this method for industrial tape backings where tensile strength outweighs clarity requirements.
- Extrusion Coating:Molten polymer deposition onto substrates builds barrier layers for pouch structures. Vacuum metallization compatibility is redirecting converter investment toward this capability as EPR regulations tighten.
- Lamination:Adhesive bonding of multiple webs enables complex barrier structures, though recyclability certification challenges are forcing redesign toward mono-material alternatives.
Cast Film maintains the deepest installed base; Extrusion Coating is gaining share fastest on barrier upgrade demand.
Thickness:
Gauge selection maps directly to application economics, with Low and Medium grades dominating commodity throughput while High and Ultra-Thin specifications capture specialty premiums.
- Low Gauge:Eight-to-fifteen micron specifications reduce material cost for high-volume snack wrappers. Tanzanian food packaging processors remain undersupplied relative to Nigerian counterparts, creating first-mover positioning for regional converters.
- Medium Gauge:Fifteen-to-thirty micron range balances stiffness and conformability for standard label applications.
- High Gauge:Thirty-to-fifty micron construction delivers puncture resistance for industrial and medical packaging.
- Ultra-Thin:Sub-eight micron development targets downgauging incentives in South African EPR frameworks, where reduced material intensity earns compliance fee reductions.
Medium Gauge captures the broadest application base; Ultra-Thin is expanding most quickly on regulatory optimization incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Nigeria's Lagos-Ibadan manufacturing corridor, where snack food producers are upgrading from polyethylene to BOPP laminate solutions. South Africa's extended producer responsibility frameworks are redirecting converter investment toward recyclable mono-material structures. Egypt anchors North African supply through metallized grade production.
Nigeria
Snack food packaging processors in the Lagos-Ibadan corridor are scaling purchases of high-clarity BOPP laminate solutions for moisture-sensitive products. The National Agency for Food and Drug Administration and Control monitors migration limits in printed films for edible oil sachets. Lagos-based sachet producers are already qualifying alternative substrate specifications to meet evolving compliance requirements.
South Africa
Converters are redesigning multilayer structures into recyclable mono-material formats to meet extended producer responsibility mandates. The Department of Forestry, Fisheries and the Environment enforces certified recyclability pathways for flexible packaging. Industrial clusters in Gauteng and the Western Cape are attracting capital toward metallization and coating line upgrades.
Egypt
Pharmaceutical serialization compliance is driving adoption of high-clarity thermal lamination films for track-and-trace labeling. The Egyptian Organization for Standardization and Quality aligns BOPP film imports with harmonized African standards for food-contact materials. Cairo-based packaging houses receive metallized grades from regional production facilities serving North African markets.
Kenya
Food packaging processors are scaling purchases of high-clarity films as they upgrade from polyethylene substrates. The country's national standards body is developing food-contact material guidelines to align with broader African harmonization efforts. Nairobi and Mombasa industrial zones remain undersupplied relative to West African counterparts, creating positioning opportunities for regional converters.
Tanzania
Low-gauge film demand is expanding as snack food producers seek material cost reductions for high-volume wrappers. The central food safety authority is implementing migration limit testing protocols for imported flexible packaging. Dar es Salaam's manufacturing corridor is attracting first-mover converters targeting East African supply gaps.
Africa BOPP Films Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue barrier-enhanced specialty grades. The market structures around three maturity tiers: integrated resin-to-film operators, regional converters with coating capabilities, and import-dependent distributors serving fragmented end-use segments. Two strategic archetypes dominate—backward-integrated resin controllers and coating-specialized converters. Competitive moves concentrate on metallization line upgrades and EPR-compliant mono-material portfolio diversification.
Within the integrated producer tier, Taghleef Industries S.A.E. and Flex Films exemplify geographic anchoring strategies—Egyptian and Indian origins respectively—while Cosmo Films Ltd occupies a specialization position in thermal lamination films. These three entities represent distinct competitive vectors: regional production base leverage, captive resin supply control, and premium label application focus. Their positioning illustrates how market participants are aligning capability investments with regulatory-driven demand shifts across the continent.
| Leading Market Players |
|---|
| Taghleef Industries S.A.E. |
| Flex Films |
| Cosmo Films Ltd |
| SABIC |
| Jindal Films |
| UFlex Ltd. |
| COPACK Company |
| elm films |
| Innovia Films |
| Others |
Value Chain & Pricing Dynamics
Coextrusion technician scarcity in Egyptian and South African facilities widens labor-cost differentials between established producers and new entrants, stretching pricing-tier spreads from commodity snack-film grades to premium pharmaceutical lamination specifications.
Pricing Analysis
Volume placements concentrate in Packaging Films; Labels captures expanding margin pools. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Cost compression in standard-grade segments intensifies as Nigerian snack producers rotate suppliers annually to benchmark total cost of ownership. Small-scale converters in Tanzania and Kenya exhibit highest price sensitivity; integrated resin-to-film operators command lowest.
Supply Chain Analysis
Reverse-logistics flows for recyclable mono-material structures remain underdeveloped, limiting converter ability to document closed-loop pathways for South African EPR compliance. Raw material supply draws from Saudi propylene monomer, Egyptian resin production, and imported additives from India and China. Single-source vulnerability concentrates in metallized coating equipment sourced from European suppliers. Distribution runs through regional converter hubs in Lagos, Cairo, and Johannesburg serving fragmented end-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates across South Africa and Egypt are consolidating procurement power among converters with certified recyclability capabilities, forcing import-dependent distributors toward exit or acquisition.
For Market Incumbents: Anticipate annual supplier rotation protocols from Nigerian snack food processors by accelerating qualification speed for alternative substrate specifications. Prioritize metallization line upgrades to capture barrier-enhanced edible oil sachet demand. Defend against emerging entrants through captive resin supply control and EPR-compliant mono-material portfolio diversification. For New Entrants and Emerging Players: E-commerce platform procurement channels offer direct access to mid-scale Kenyan and Tanzanian food packaging processors undersupplied relative to West African counterparts. Target low-gauge film specifications for high-volume snack wrappers in Dar es Salaam's manufacturing corridor. Pursue distributed production models enabled by digital printing integration for seasonal promotional packaging contracts. For Investors and Strategic Acquirers: Re-rating potential sits with coating-specialized converters given South African EPR framework acceleration toward certified recyclability pathways. Long-term viability favors regional converters with backward integration into resin sourcing and barrier coating capabilities. Monitor harmonization progress between Egypt's EOSQ requirements and Nigeria's NAFDAC migration limits as cross-border qualification inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Metallization Line Upgrade | Vacuum-deposited aluminum coatings capture edible oil sachet demand in humid Lagos-Ibadan corridor. |
| Backward Integration into Resin | Captive polypropylene supply insulates Egyptian and South African converters from currency-driven margin compression. |
| Mono-Material Structure Certification | Documented recyclability pathways reduce South African EPR compliance fees for pharmaceutical packaging suppliers. |
| Digital Printing Integration | Rapid job changeovers without plate costs compress minimum viable order quantities for seasonal Nigerian snack promotions. |
| East African Capacity Addition | High-clarity film production in Nairobi and Mombasa addresses undersupplied Kenyan and Tanzanian processor demand. |
Study Parameters
Multi-period observation of converter capacity utilization, resin import flows, and EPR compliance certification rates anchored the trend analysis, supplemented by interviews with plant managers at Egyptian and South African film facilities, procurement leads at Nigerian snack food processors, regulatory affairs specialists at Egypt's EOSQ, and distribution channel partners across East Africa. Secondary validation drew from customs trade data, National Agency for Food and Drug Administration and Control migration limit filings, Department of Forestry, Fisheries and the Environment EPR registry disclosures, and SEC filings of integrated resin producers. Bottom-up volume estimates triangulated against top-down demand projections from end-use industry consumption patterns.
Input-output matrices mapped polypropylene resin availability through extrusion, orientation, and coating stages to finished film output across thickness tiers and application specifications. Segmentation dimensions modeled include product type, manufacturing process, end-use industry, and thickness gauge. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated propylene feedstock price volatility indices and regulatory compliance cost schedules.
The model holds under stable EPR enforcement intensity and continued resin import dependence; deviation in harmonization of food-contact standards or metallization equipment supply disruptions would shift converter investment timelines. Practitioners should monitor South African EPR fee structure revisions and Egyptian-EOSQ standard alignment progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Asia Pacific Plastic Bottles Market