
 Europe PET Packaging Market | 2026-2036
Europe PET Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe PET Packaging Market Intelligence
Modular bottle formats with detachable components and customizable label zones is realigning procurement patterns among mid-sized beverage brands. Amcor Limited leverages its European thermoforming footprint to supply nested tray configurations for fresh-protein retail. Huhtamaki Oyj anchors its position through high-barrier PET laminates designed for oxygen-sensitive food categories. ALPLA Werke specializes in integrated preform-to-bottle systems that reduce converter complexity for carbonated soft drink bottlers.
Europe PET Packaging comprises polyethylene terephthalate containers, films, and formed articles typically manufactured through blow molding, injection molding, or thermoforming processes, with intrinsic viscosity ranging from 0.70 to 0.84 dL/g depending on end-use performance requirements. The material delivers clarity, gas barrier performance, and mechanical strength for carbonated beverages, pharmaceuticals, and perishable food distribution. Bottles retain the dominant value share across product types, though trays are gaining share in modified-atmosphere protein packaging where oxygen scavenger integration commands premium positioning. Rigid packaging formats lead volume throughput, while flexible PET pouches with metallized or coextruded barrier layers represent the fastest-expanding margin pool in cosmetics and single-serve condiment segments.
The EU Green Deal and REACH frameworks mandate minimum recycled content thresholds and restrict certain additive chemistries in food-contact materials, compelling converters to certify rPET streams through EFSA-compliant recycling processes. Germany's national packaging regulator enforces strict extended producer responsibility quotas that shape collection infrastructure investment and recycling yield economics. France's AGEC law imposes additional labeling and recyclability disclosure requirements that influence brand-owner specification decisions. Stakeholders must monitor evolving ECHA substance evaluations and national deposit-return scheme expansions to anticipate feedstock cost shifts and compliance timeline adjustments.
Market Dynamics
EU Green Deal recycled-content mandates are compressing converter timelines and forcing rapid rPET infrastructure buildout across Western European bottling corridors. This regulatory pressure is restructuring feedstock procurement relationships and certifier dependencies.
Growth Catalysts
- EFSA-compliant recycling certification:Food-contact rPET approval pathways are unlocking circular material flows for beverage and dairy converters seeking closed-loop supply security.
- Deposit-return scheme expansion:Germany's DRS infrastructure investments are yielding higher-purity bale streams that reduce mechanical recycling yield losses.
- Lightweighting blow-molding advances:Stretch-blow process refinements are enabling gram-weight reductions in carbonated bottles without pressure-performance degradation.
Market Restraints
- rPET feedstock cost volatility:Bottle bale spot markets exhibit price swings that compress converter margins during collection-season troughs.
- Preform molding equipment concentration:Blow-molding machinery supply concentrates among German and Italian OEMs, creating lead-time vulnerability for capacity expansions.
- Polypropylene substitution in hot-fill:Crystallized PP bottles are displacing heat-set PET in ambient-juice segments above 85°C fill temperatures.
Strategic Opportunities
- Poland and Romania collection infrastructure:Underdeveloped DRS networks in these markets present first-mover advantages for integrated recycler-converter joint ventures.
- Pharmaceutical blister-to-bottle conversion:Unit-dose PET bottles with child-resistant closures are capturing share from PVC blisters in OTC analgesics.
- France AGEC labeling mandates:Recyclability disclosure requirements are creating specification-switching windows for converters with EPR-compliant design certifications.
Industry Challenges
- Food-contact process engineer scarcity:EFSA dossier preparation and challenge-test execution require specialized toxicology and migration-modeling expertise that outpaces vocational pipeline output.
- Legacy injection-molding asset stranding:Converters with sunk capital in non-rPET-compatible preform tooling face accelerated obsolescence timelines under 2025 recycled-content thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe PET Packaging Market |
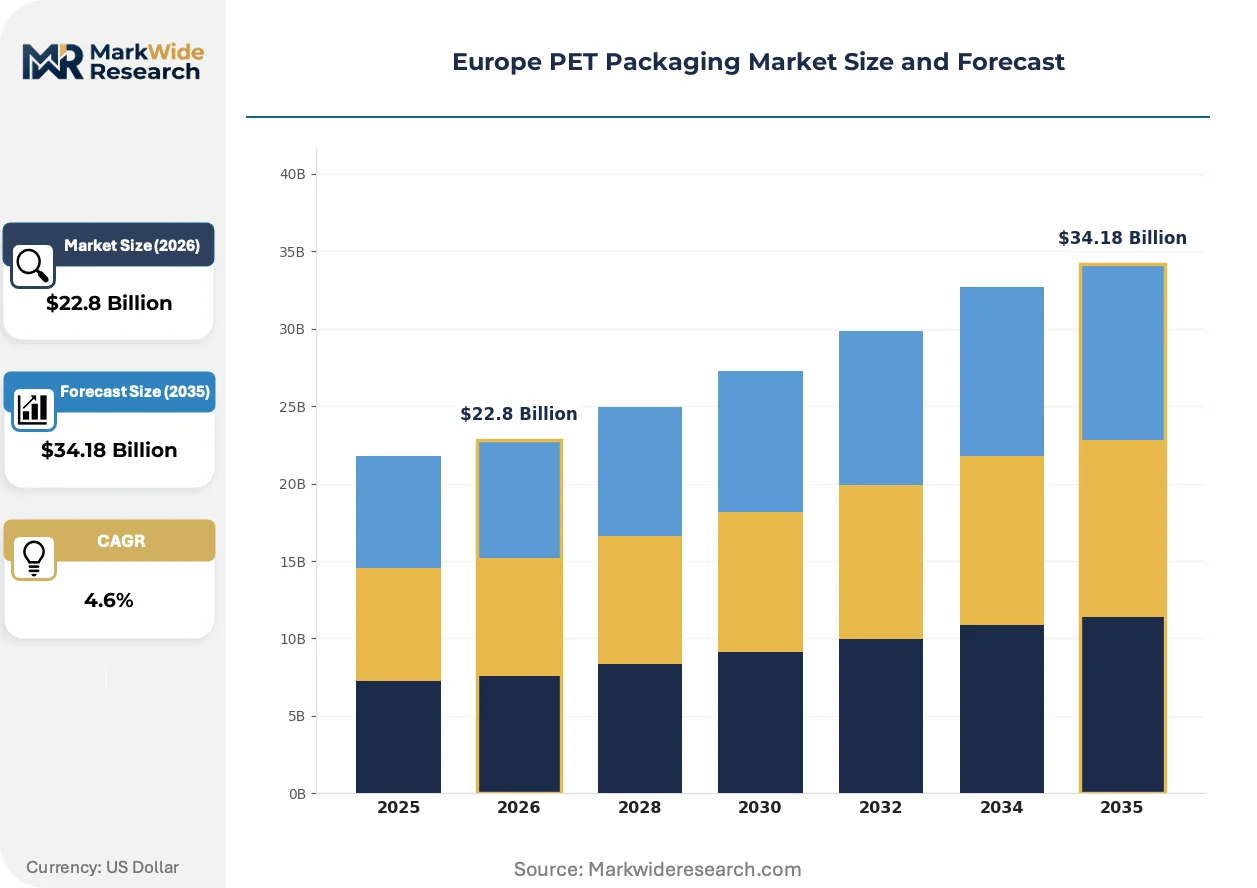
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Trays, Pouches End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Packaging Type: Rigid, Flexible, Blister, Shrink Sleeve Manufacturing Stage: Blow Molding, Injection Molding, Extrusion, Thermoforming |
| Companies Covered | Huhtamaki Oyj, Mondi Group, Amcor Limited, Gerresheimer AG, ALPLA Werke, Berry Global Group Inc., Constantia Flexibles, Resilux NV, Klöckner Pentaplast, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe PET Packaging Market Strategic Shifts & Innovations
Active packaging functionality and circular design protocols are converging to redefine specification standards across beverage, food, and pharmaceutical end-uses. These developments are compressing traditional converter development cycles.
Mono-material PET barrier structures with plasma-enhanced chemical vapor deposition coatings are displacing multilayer laminates in oxygen-sensitive meat and cheese packaging. Retailers in France and the Netherlands are specifying these formats for private-label modified-atmosphere protein lines. The technology is modularizing converter equipment footprints by eliminating coextrusion complexity and enabling single-platform flexibility across product categories.
REACH restriction proposals on intentionally added microplastics are compelling additive reformulation in masterbatch colorants and slip agents. Compounders serving the European market are accelerating migration to polymer-bound pigment systems that eliminate free-particle release. Food-contact tray manufacturers face the steepest compliance timelines given direct handling exposure in ready-meal applications.
Direct-store-delivery beverage bottlers are consolidating SKU portfolios around nested bottle families with shared preform bases and interchangeable label panels. This specification discipline reduces mold inventory and enables rapid brand-variant rotation. German mid-market mineral water producers are most advanced in adopting these platform architectures to service fragmented retail channel requirements.
Europe PET Packaging Market Segmentation
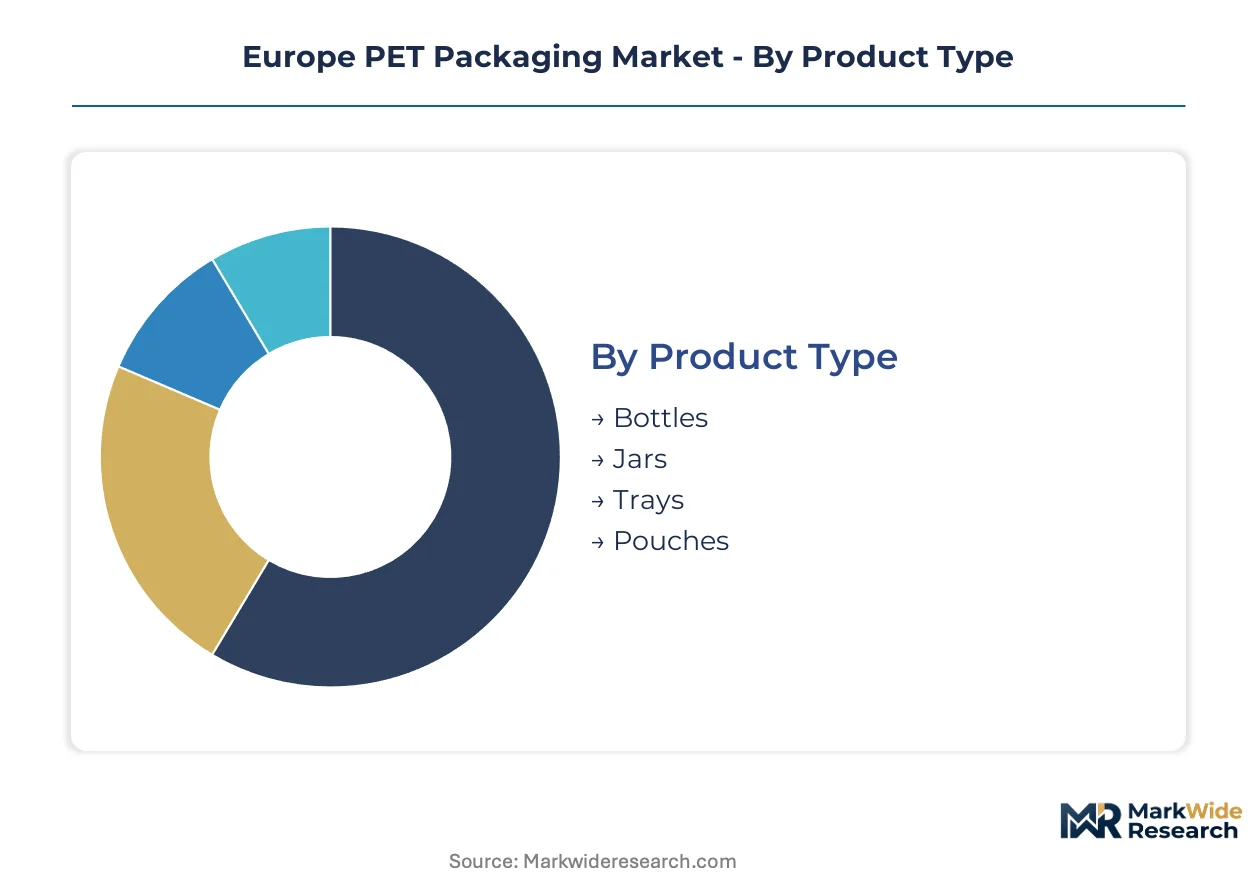
PET packaging specifications diverge sharply across end-use applications, with oxygen barrier requirements and thermal stability thresholds dictating material grade selection. Converters segment their production assets around these technical boundaries to optimize cycle times and minimize changeover losses.
Product Type:
Buyers differentiate primarily by fill-volume ranges and shelf-visibility requirements, with carbonated beverage bottlers prioritizing pressure resistance and dairy processors emphasizing hermetic seal integrity.
- Bottles:Stretch-blow molded containers with intrinsic viscosity above 0.78 dL/g withstand internal pressures exceeding 4 bar for carbonated soft drinks. German mineral water bottlers and French cider producers drive specification refinement around lightweight gram-weight targets without creep deformation.
- Trays:Thermoformed structures with oxygen scavenger integration dominate modified-atmosphere protein packaging. Netherlands retailers specify these for private-label fresh meat lines where shelf-life extension commands premium positioning.
- Jars:Wide-mouth injection-stretch blow formats serve ambient sauces and condiments requiring thermal stability above 65°C.
- Pouches:Flexible metallized or coextruded barrier laminates expand fastest in single-serve cosmetics and condiment segments.
Bottles lead volumes today; pouches are gaining share fastest.
End User:
Regulatory exposure and contamination risk tolerance separate procurement patterns, with pharmaceutical buyers demanding migration-test documentation that food-contact converters rarely encounter.
- Food & Beverage:EFSA-compliant rPET certification requirements now govern specification sheets for beverage bottlers across Germany, France, and Italy. Deposit-return scheme purity standards in these markets determine acceptable contamination thresholds for recycled feedstock integration.
- Pharmaceuticals:Unit-dose PET bottles with child-resistant closures displace PVC blister packs in OTC analgesics. Migration modeling and extractables testing protocols exceed food-contact stringency by an order of magnitude.
- Cosmetics:Premium fragrance and skincare brands specify ultra-clear PET with zero color-masterbatch addition.
- Household Products:Industrial chemical resistance drives copolymer selection for bleach and solvent containers.
Food & Beverage dominates absolute tonnage; Pharmaceuticals exhibits the steepest margin expansion trajectory.
Packaging Type:
Mechanical handling compatibility and retail-display geometry shape converter equipment investment, with automated palletizing systems favoring rigid formats over flexible alternatives.
- Rigid:Blow-molded and thermoformed structures handle stacking loads above 500 kg in warehouse distribution. France's AGEC labeling mandates accelerate specification shifts toward mono-material rigid formats with EPR-compliant design certifications.
- Flexible:Pouch and film formats reduce transport cube utilization by 40-60% versus equivalent rigid containers. Cosmetics sampling and single-serve condiment segments drive barrier-laminate development.
- Blister:Thermoformed cavity-lid combinations serve unit-dose pharmaceutical and confectionery applications.
- Shrink Sleeve:Full-body label formats enable 360-degree brand communication on contoured bottle geometries.
Rigid packaging commands volume leadership; flexible formats climb the fastest in value terms.
Manufacturing Stage:
Capital intensity and cycle-speed economics determine converter specialization, with high-volume beverage producers integrating blow-molding operations that smaller food brands outsource.
- Blow Molding:Stretch-blow and injection-stretch-blow processes produce biaxially oriented bottles with enhanced tensile strength. Equipment supply concentrates among German and Italian OEMs, creating lead-time vulnerability for capacity expansions.
- Thermoforming:Sheet extrusion and vacuum forming generate trays and blisters with rapid tool-change capability. Fresh-protein retail specifications in France and the Netherlands drive oxygen-barrier coating integration.
- Injection Molding:Preform production and wide-mouth jar manufacture require precise temperature control for crystallinity management.
- Extrusion:Cast and oriented film production supplies flexible pouch substrates and sheet stock for downstream thermoforming.
Blow molding anchors volume throughput; thermoforming expands most quickly in food-contact barrier applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale PET bottle production in Europe during the 1970s, establishing blow-molding expertise that spread across Rhine-Ruhr manufacturing corridors before the format displaced glass in beverage distribution.
Germany
Beverage bottlers in the Rhine-Main region are expanding lightweight PET adoption to cut transport emissions. The national packaging regulator enforces strict extended producer responsibility quotas that shape collection infrastructure investment. Munich-based converters supply nested tray configurations to fresh-protein retail chains operating across Bavaria.
France
Cider producers in Brittany drive specification refinement around gram-weight targets without creep deformation. France's AGEC law imposes additional labeling and recyclability disclosure requirements that influence brand-owner specification decisions. The Paris basin hosts pharmaceutical blister-to-bottle conversion activity where unit-dose PET bottles capture share from PVC alternatives.
Italy
Carbonated soft drink bottlers in Lombardy source integrated preform-to-bottle systems that reduce converter complexity. EFSA-compliant rPET certification requirements now govern specification sheets for beverage converters across the Po Valley. Turin-area thermoformers supply oxygen-barrier trays to Netherlands retailers for private-label meat lines.
Netherlands
Retailers specify mono-material PET barrier structures with plasma-enhanced coatings for modified-atmosphere protein packaging. Rotterdam's port infrastructure enables rPET feedstock import flows that supplement domestic collection yields. Eindhoven-region compounders accelerate migration to polymer-bound pigment systems that eliminate free-particle release under REACH proposals.
Poland
Underdeveloped deposit-return scheme networks present first-mover advantages for integrated recycler-converter joint ventures. The Warsaw-Łódź corridor attracts blow-molding capacity expansions serving Central European beverage distribution. Poznań-area converters leverage lower labor costs to produce standard-grade bottles for price-sensitive private-label brands.
Europe PET Packaging Market Key Industry Players
The competitive structure tilts toward integrated packaging conglomerates with multi-format production capabilities. Tiered specialization separates beverage-dedicated blow molders from diversified food-contact converters. Three archetypes dominate: pan-European rigid packaging specialists with thermoforming footprints, integrated preform-to-bottle system providers, and high-barrier laminate developers for oxygen-sensitive categories. Capacity expansion and EPR-compliant design certification represent the dominant competitive moves.
Among Nordic-based rigid packaging specialists, Huhtamaki Oyj exemplifies the high-barrier laminate archetype for food-contact applications. Amcor Limited and ALPLA Werke occupy positions on opposite ends of the integration spectrum—Amcor representing diversified geographic coverage across European thermoforming, ALPLA embodying dedicated preform-to-bottle system concentration for carbonated beverage bottlers. These three anchors illustrate how competitive positioning fragments across technical specialization rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Mondi Group |
| Amcor Limited |
| Gerresheimer AG |
| ALPLA Werke |
| Berry Global Group Inc. |
| Constantia Flexibles |
| Resilux NV |
| Klöckner Pentaplast |
| Others |
Cost & Logistics Intelligence
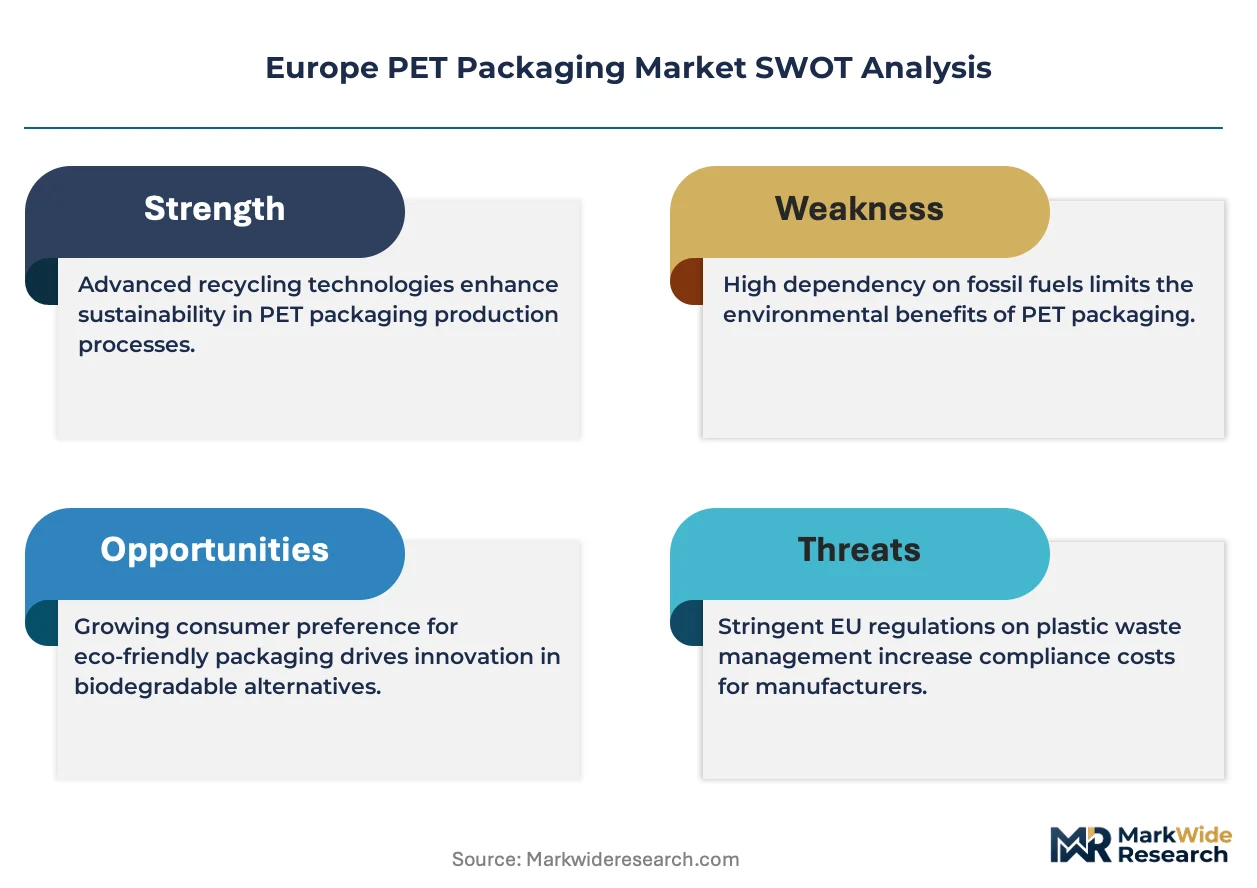
EFSA-compliant rPET certification tiers create a sharp bifurcation between premium food-contact grades and standard industrial applications, with this quality ladder manifesting in both converter procurement premiums and the geographic clustering of mechanical recycling infrastructure around Germany's deposit-return scheme corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter procurement, with EFSA-certified food-contact rPET commanding substantial premiums over non-certified industrial bales. Price differentiation rests on contamination thresholds and challenge-test documentation completeness. Pricing pressure stems from bottle bale spot market seasonality, with collection troughs compressing converter margins. Small beverage brands exhibit highest price sensitivity, while pharmaceutical buyers prioritize migration-test compliance over unit cost.
Supply Chain Analysis
Skilled process engineers for EFSA dossier preparation concentrate in Germany's Rhine-Ruhr and Italy's Po Valley manufacturing belts, creating recruitment competition that elevates labor costs for converter expansions. Raw material flows draw from post-consumer bale networks across Germany, France, and the Netherlands, with virgin PET resin anchored in Northwest European petrochemical corridors. Single-source vulnerability concentrates in blow-molding machinery supply from German and Italian OEMs. Distribution runs through palletized bulk shipments to beverage bottling facilities and roll-stock delivery to thermoforming converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through lightweighting technology adoption that reduces gram-weight resin consumption per bottle while maintaining pressure performance for carbonated applications.
For Market Incumbents: Hedge against crystallized polypropylene substitution in hot-fill juice segments by accelerating heat-set PET thermal stability improvements. Secure backward integration into rPET collection infrastructure before 2025 recycled-content thresholds strand legacy preform tooling. Prioritize EFSA-compliant certification investment to defend specification positions with German and French beverage bottlers. For New Entrants and Emerging Players: Plasma-enhanced chemical vapor deposition coating technology offers a technology-first wedge into oxygen-sensitive modified-atmosphere protein packaging currently served by multilayer laminates. Target Netherlands and French private-label retail specifications where mono-material PET barrier structures face specification-switching windows under AGEC labeling mandates. Pursue joint-venture structures with established thermoformers to bypass capital-intensive equipment lead times. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated recycler-converter joint ventures in Poland and Romania where underdeveloped deposit-return scheme networks present first-mover collection infrastructure advantages. Five-to-ten-year viability hinges on EU Green Deal recycled-content mandate enforcement consistency. Watch ECHA substance evaluation timelines for intentionally added microplastics restrictions as inflection indicators for additive reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Compliant rPET Certification Investment | Unlocks food-contact specification access for beverage bottlers across Germany and France under EU Green Deal mandates. |
| Lightweighting Blow-Molding Process Refinement | Reduces transport emissions and resin costs for carbonated soft drink bottlers in Rhine-Main and Lombardy corridors. |
| Plasma-Enhanced Barrier Coating Adoption | Displaces multilayer laminates in Netherlands and French modified-atmosphere protein packaging specifications. |
| Deposit-Return Scheme Infrastructure Partnership | Captures higher-purity bale streams in Poland and Romania before competitor recycler-converter joint ventures consolidate. |
| Polymer-Bound Pigment Masterbatch Migration | Ensures REACH compliance for intentionally added microplastics restrictions in French ready-meal tray applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blow-molding equipment operators, rPET procurement managers at beverage converters, EFSA certification specialists, and retail private-label specification directors with secondary validation from EU Green Deal regulatory filings, ECHA substance evaluation databases, national packaging regulator enforcement notices, and extended producer responsibility quota disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-regulatory-shift trajectories, with CAGR derivation reflecting segment-specific growth elasticities across product type, end-use application, packaging format, and manufacturing stage dimensions. Industry-specific inputs incorporated rPET bale spot price volatility patterns, blow-molding equipment capacity utilization rates, and EFSA challenge-test approval timelines.
The model holds under sustained EU Green Deal enforcement and stable rPET collection infrastructure investment; deviation in ECHA restriction timelines or deposit-return scheme adoption delays would shift converter margin trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market