
 Plasticizers Market | 2026-2036
Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Plasticizers Market Analysis
Bio-based feedstock integration is fragmenting traditional petrochemical supply chains for plasticizer production. BASF SE leverages its proprietary biomass-balanced portfolio to secure preferential access to European automotive OEMs seeking lower-carbon vinyl compounds. Eastman Chemical Company anchors its position through backward integration into 2-ethylhexanol and proprietary non-phthalate ester technology. ExxonMobil Chemical dominates North American supply through its Baton Rouge manufacturing complex and captive hydrocarbon feedstock position.
Plasticizers are high-boiling-point organic compounds, typically phthalate or non-phthalate esters with molecular weights between 300 and 600 g/mol, added to polymers—principally polyvinyl chloride—to increase flexibility, workability, and distensibility by reducing intermolecular forces between polymer chains. Phthalate product lines retain volume leadership in developing markets where cost sensitivity persists, though margin pools are migrating toward bio-based plasticizers as certification premiums expand. Adipate formulations sustain growth in low-temperature automotive and construction applications where plastisol viscosity stability and cold-flex performance command technical specification premiums. Water-based technology segments are displacing solvent-based coating applications under tightening volatile organic compound regimes across multiple jurisdictions.
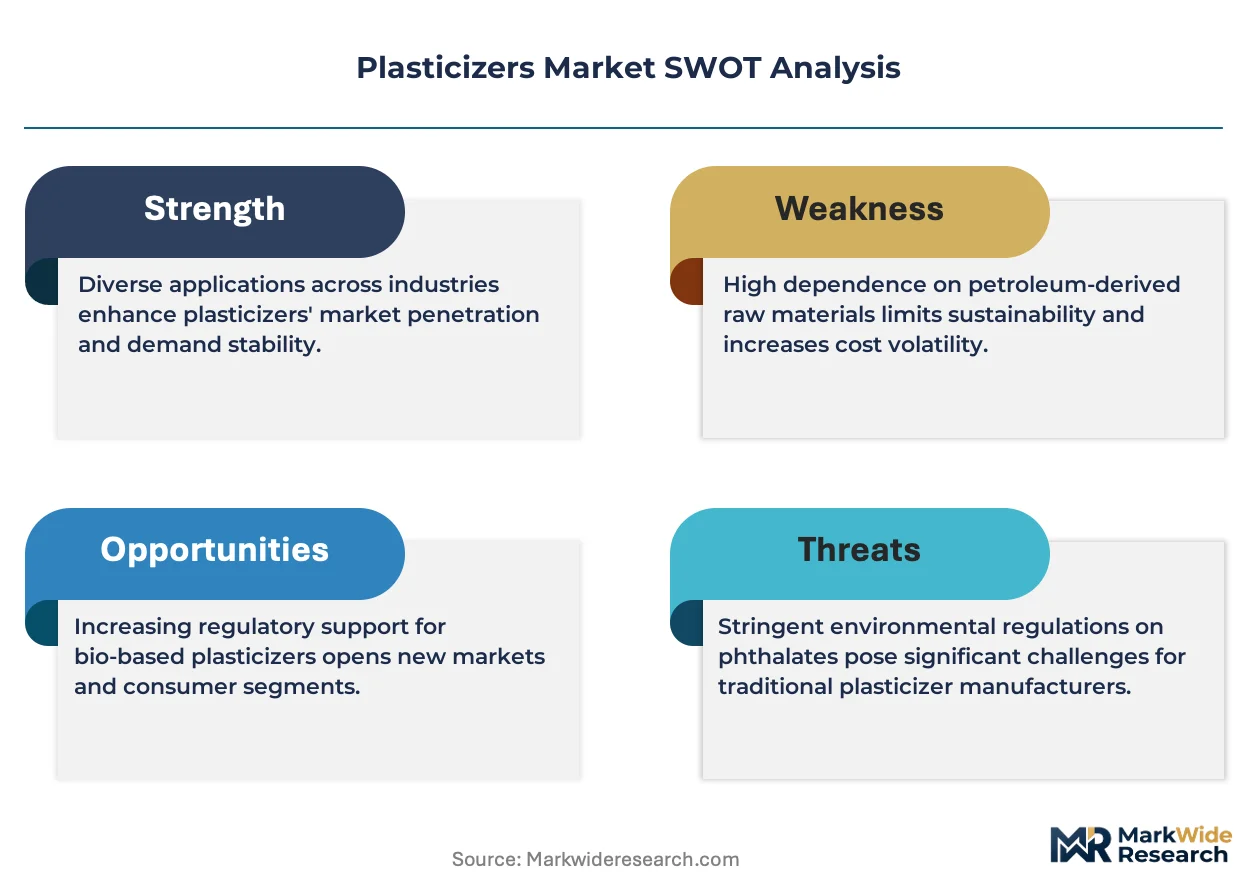
REACH restrictions on ortho-phthalates and the EU Green Deal's chemical sustainability targets are reshaping product registration requirements and import compliance costs for suppliers serving European end users. The EPA's Toxic Substances Control Act Section 6 authority and state-level Proposition 65 litigation in California are accelerating reformulation timelines for U.S.-bound plasticizer shipments. China's GB standards and dual carbon goals from MEE are tightening domestic production permits for conventional phthalate capacity. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capital allocation across product lines and manufacturing assets.
Market Dynamics
REACH ortho-phthalate restrictions and China's GB standards are fragmenting legacy supply chains, forcing producers to reconfigure product portfolios across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Automotive OEM specification tightening:Cold-flex performance requirements in underbody coatings and interior vinyl are accelerating adipate plasticizer qualification timelines for Tier 1 suppliers.
- REACH Annex XVII expansion:ECHA's progressive restriction of DEHP, DBP, and BBP is redirecting formulation R&D budgets toward non-phthalate ester platforms.
- Infrastructure investment cycles:Residential and commercial construction across China and India is sustaining high-volume flexible PVC consumption for flooring, roofing membranes, and cable insulation.
Market Restraints
- 2-ethylhexanol feedstock concentration:Oxo-alcohol supply is geographically concentrated, exposing plasticizer producers to naphtha-cracker output volatility and regional refinery maintenance cycles.
- Technical performance gaps in bio-based grades:Current biomass-derived plasticizers exhibit inferior UV stability and migration resistance versus petrochemical analogs, limiting adoption in medical device and food-contact applications.
- Regulatory friction from divergent compliance:The absence of harmonized testing protocols between REACH, EPA TSCA Section 6, and China's MEE permitting creates redundant certification costs for multi-territory suppliers.
Strategic Opportunities
- Underpenetrated medical device segments:India's CDSCO is expanding its medical plastics regulatory framework, creating first-mover positioning for DEHP-free IV bag and tubing formulations.
- Water-based coating conversion:VOC emission limits under EPA NESHAP and EU Solvent Emissions Directive are displacing solvent-based plastisols in automotive sealant and textile coating applications.
- Recyclable vinyl compound design:Mechanical recycling infrastructure for flexible PVC is maturing in Germany and the Netherlands, enabling closed-loop service models for construction and automotive waste streams.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in esterification kinetics and polymer compatibility testing is concentrated among retiring cohorts in European and North American R&D centers.
- Multi-jurisdiction registration timelines:REACH SVHC notification, EPA PMN review, and China's new chemical substance notification (MEE Order 12) require parallel track management stretching 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasticizers Market |
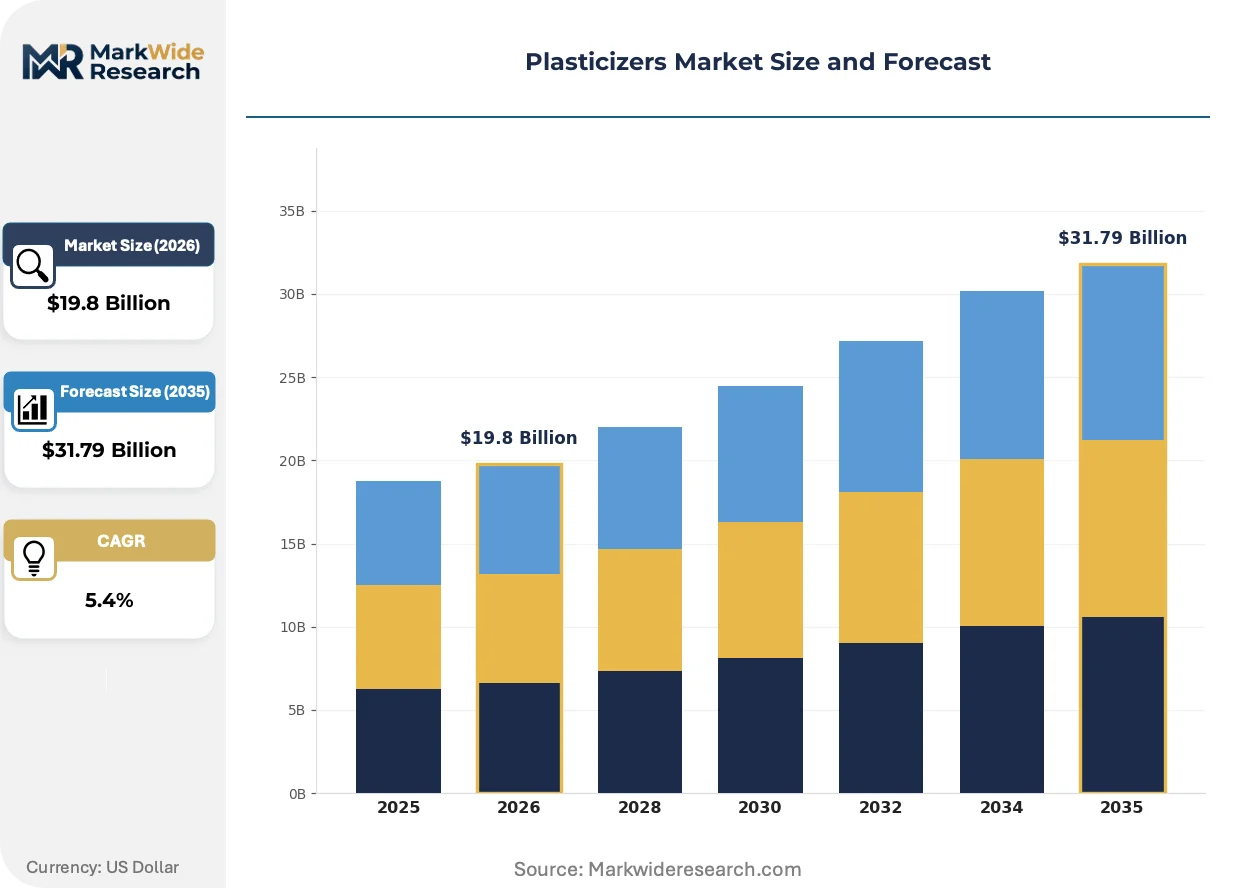
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalates, Adipates, Trimellitates, Bio-based Plasticizers End User: Automotive, Construction, Packaging, Consumer Goods Application: Wiring, Flooring, Coatings, Adhesives Technology: Solvent-based, Water-based, 3D Printing, Extrusion |
| Companies Covered | BASF SE, Eastman Chemical Company, ExxonMobil Chemical, Evonik Industries, LG Chem, Lanxess AG, DIC Corporation, Arkema S.A., UPC Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasticizers Market Emerging Trajectories
Formulation science is converging with carbon accounting methodologies, redefining how plasticizer producers demonstrate product-level environmental performance to specification-driven buyers.
Polymeric plasticizer technology is hybridizing low-migration permanence with bio-content claims. Automotive seating and interior trim suppliers at BMW and Volvo are qualifying these materials for 10-year durability warranties. The technology is compressing the addressable market for monomeric phthalates in premium vehicle segments.
ECHA's 2025 restriction proposal for DINP in consumer articles is accelerating substitution timelines. Compounders serving toy, childcare, and food-contact applications are reformulating ahead of enforcement dates. The household goods segment is responding fastest, with Nordic and German retailers demanding pre-certified non-phthalate supply chains.
Specification-driven procurement is consolidating vendor relationships among construction and automotive buyers. Long-term offtake agreements with embedded carbon reporting are displacing spot-market purchasing in Germany and California. This concentration is most visible in commercial flooring, where Tarkett and Interface are requiring supplier-specific EPD documentation.
Plasticizers Market Segmentation
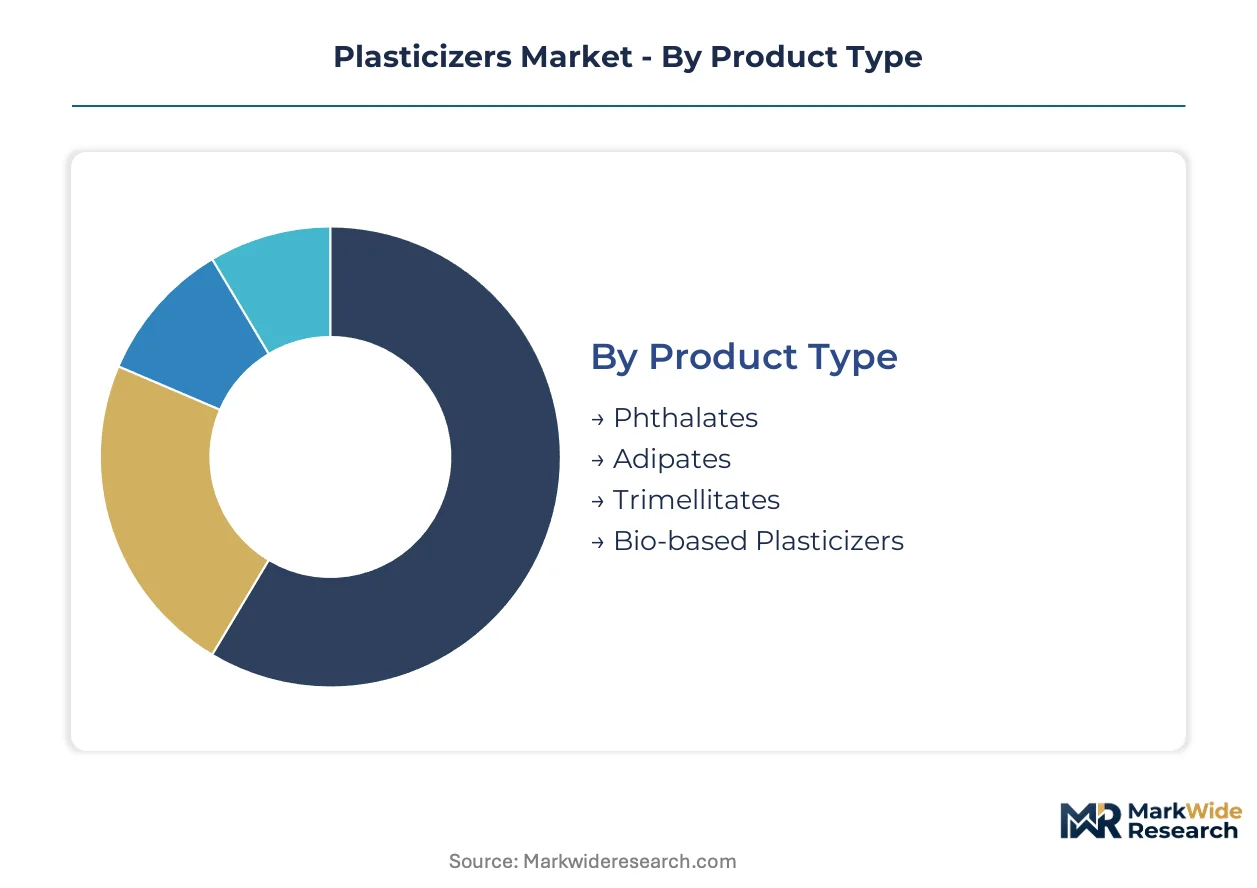
Plasticizer procurement decisions diverge sharply across product chemistry, end-use durability requirements, and processing technology. Specification engineers, compounders, and OEM buyers each weight segments differently when qualifying formulations for regulatory compliance and performance targets.
Product Type:
Cost tier stratification separates commodity phthalate volumes from premium-certified alternatives where regulatory pressure has compressed margins and redirected R&D investment.
- Phthalates:Ortho-phthalate esters including DEHP, DINP, and DIDP remain the lowest-cost flexible PVC modifiers, with formulation concentration highest in developing markets where REACH-equivalent restrictions have not yet taken full effect. Infrastructure projects in India and Southeast Asia sustain volume demand despite accelerating substitution in European automotive and medical applications.
- Adipates:Adipate esters deliver superior low-temperature flexibility and plastisol viscosity stability, commanding specification premiums in automotive underbody coatings and construction membranes where cold-flex performance determines warranty compliance. German and Swedish automotive OEMs have accelerated adipate qualification timelines ahead of ECHA's progressive ortho-phthalate restrictions.
- Trimellitates:High-molecular-weight trimellitate esters target elevated-temperature wire insulation and specialty cable jacketing where low volatility and extraction resistance justify cost premiums.
- Bio-based Plasticizers:Epoxidized soybean oil and citrate derivatives from biomass feedstocks carry certification premiums under EU Green Deal carbon accounting frameworks, though technical gaps in UV stability and migration resistance constrain medical and food-contact adoption.
Phthalates command the established base. The steepest expansion runs through bio-based formulations.
End User:
Application maturity varies by sector, with construction and automotive driving specification tightening while packaging and consumer goods respond fastest to retailer-driven certification requirements.
- Automotive:Interior vinyl, underbody coatings, and wire harnesses face OEM specification tightening on cold-flex durability and VOC emissions, with BMW and Volvo requiring 10-year warranty compliance for seating and trim compounds. REACH Annex XVII expansion is redirecting Tier 1 supplier formulation portfolios toward non-phthalate esters.
- Construction:Residential and commercial building across China sustains high-volume flexible PVC consumption for flooring, roofing membranes, and cable insulation, with mechanical recycling infrastructure maturing in Germany and the Netherlands to enable closed-loop service models.
- Packaging:Flexible films and food-contact applications face the fastest substitution pressure from retailer pre-certification requirements in Nordic and German markets ahead of ECHA's 2025 DINP restriction proposal.
- Consumer Goods:Toy and childcare article manufacturers are reformulating ahead of enforcement dates, with household goods segments responding fastest to pre-certified non-phthalate supply chain demands.
Construction anchors volume concentration. Automotive is climbing the fastest on value per ton.
Application:
Performance requirements fragment by installed environment, with wiring and flooring demanding long-term permanence while coatings and adhesives face accelerating VOC-driven technology displacement.
- Wiring:Electrical cable insulation and jacketing requires plasticizers with low volatility, high dielectric stability, and extraction resistance in enclosed conduit environments, with trimellitate grades capturing elevated-temperature specifications.
- Flooring:Commercial vinyl sheet and luxury tile applications concentrate procurement among specification-driven buyers, with Tarkett and Interface requiring supplier-specific EPD documentation and embedded carbon reporting in long-term offtake agreements.
- Coatings:Automotive sealant and textile coating applications face displacement of solvent-based plastisols under EPA NESHAP and EU Solvent Emissions Directive limits, compressing addressable market for conventional formulations.
- Adhesives:Pressure-sensitive and construction adhesive formulations leverage plasticizer compatibility with acrylic and rubber base polymers, with water-based technology segments gaining share in VOC-regulated jurisdictions.
Wiring commands the established base. Coatings are gaining share fastest on regulatory displacement.
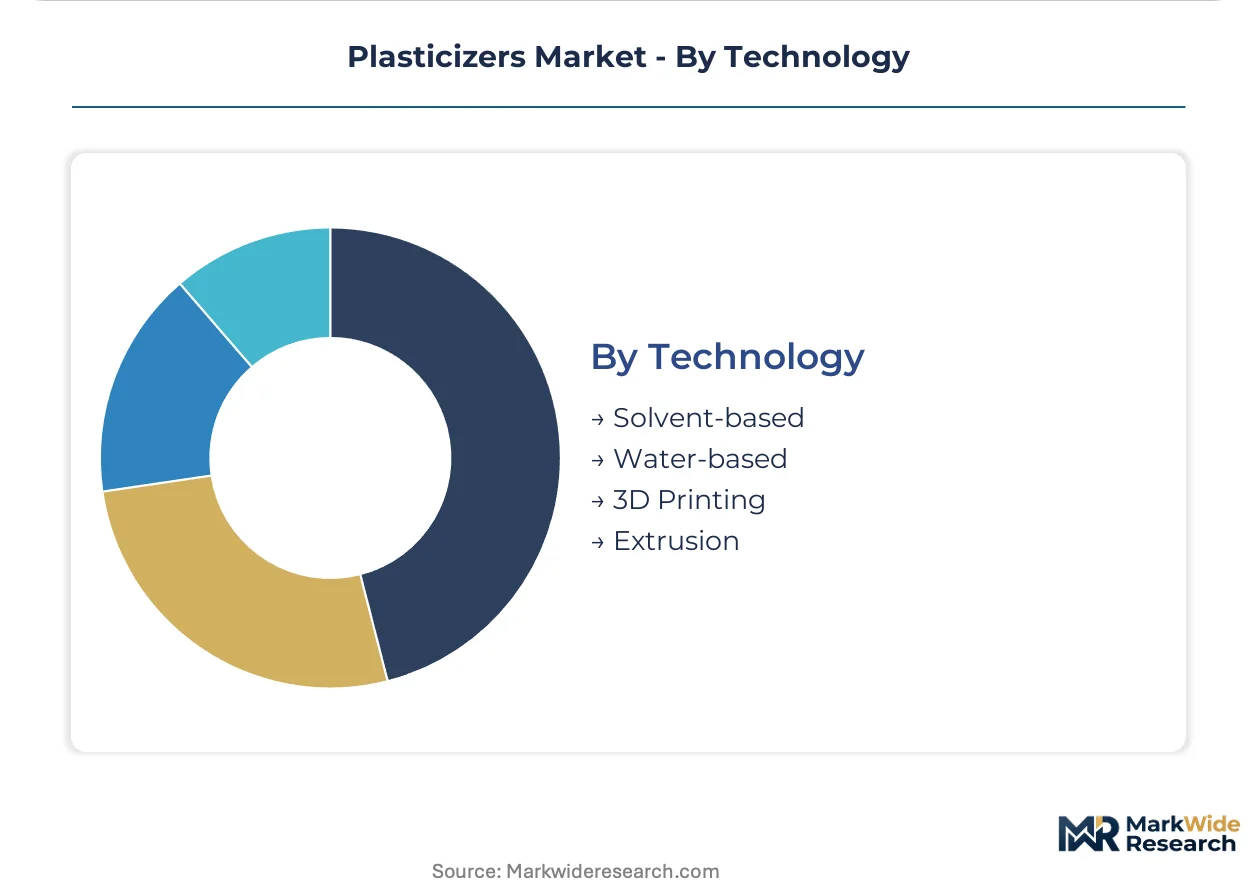
Technology:
Processing method determines plasticizer selection criteria, with viscosity stability, fusion behavior, and emission profiles varying across solvent, aqueous, and additive manufacturing platforms.
- Solvent-based:Traditional plastisol and organosol formulations dominate legacy automotive sealant and textile coating capacity, though regulatory pressure is compressing growth trajectories in California and EU markets.
- Water-based:Aqueous dispersion technology is displacing solvent systems under tightening VOC regimes, with formulation complexity increasing as plasticizer selection must balance film formation, stability, and emission profiles.
- 3D Printing:Flexible filament and resin formulations for additive manufacturing represent an emerging specification channel, with plasticizer compatibility testing still maturing for fused deposition modeling and vat photopolymerization platforms.
- Extrusion:Profile, sheet, and pipe extrusion processes require plasticizers with consistent fusion behavior and thermal stability across high-shear compounding lines, with adipate and trimellitate grades capturing technical specification premiums.
Extrusion commands the established base. Water-based technology is expanding most quickly on regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German plasticizer exports flow predominantly to automotive OEM clusters in France, Italy, and Central Europe, while Chinese production serves domestic construction and regional Southeast Asian cable manufacturing demand.
China
Infrastructure investment and automotive production sustain high-volume consumption of plasticizer compounds across residential and commercial building projects. MEE dual carbon goals and tightening GB standards are constraining conventional phthalate capacity expansion permits. Yangtze River Delta chemical parks host concentrated flexible PVC compounding operations serving domestic cable and flooring manufacturers.
United States
State-level environmental standards in California and automotive OEM specification tightening drive reformulation toward non-phthalate ester platforms. EPA TSCA Section 6 authority accelerates compliance timelines for imported plasticizer shipments. Gulf Coast petrochemical corridors leverage captive hydrocarbon feedstock positions to supply North American vinyl compounders.
Germany
REACH Annex XVII restrictions on ortho-phthalates redirect formulation R&D budgets toward bio-based and polymeric alternatives. ECHA's 2025 DINP restriction proposal compresses substitution timelines for consumer article applications. Ruhr Valley industrial clusters concentrate mechanical recycling infrastructure enabling closed-loop service models for construction waste streams.
India
Residential and commercial construction across metropolitan regions sustains flexible PVC consumption for flooring and cable insulation. CDSCO expansion of medical plastics regulatory frameworks creates positioning opportunities for DEHP-free IV bag formulations. Gujarat chemical corridors host emerging adipate and trimellitate qualification programs for automotive Tier 1 suppliers.
Japan
Automotive interior vinyl specifications emphasize cold-flex durability and low-VOC emission profiles for premium vehicle segments. METI industrial standards support polymeric plasticizer adoption in seating and trim applications requiring 10-year warranty compliance. Kansai industrial zones concentrate wire harness and cable jacketing compound development for export markets.
Plasticizers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into petrochemical majors with captive feedstock positions, specialty ester producers with backward integration into oxo-alcohols, and regional compounders serving construction and automotive qualification programs. Three archetypes dominate: integrated petrochemical conglomerates, technology-licensed specialty ester specialists, and regional formulation houses. Capacity expansion and strategic partnerships constitute the primary competitive moves, with long-term offtake agreements displacing spot-market purchasing among specification-driven buyers.
Among integrated petrochemical conglomerates, BASF SE anchors the biomass-balanced portfolio segment serving European automotive OEMs seeking lower-carbon vinyl compounds. Eastman Chemical Company exemplifies specialty ester specialists with proprietary non-phthalate technology positions. ExxonMobil Chemical occupies a channel-controlling position through North American manufacturing scale and captive hydrocarbon supply. These three represent divergent strategic archetypes: bio-content certification, proprietary formulation technology, and regional supply security.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| ExxonMobil Chemical |
| Evonik Industries |
| LG Chem |
| Lanxess AG |
| DIC Corporation |
| Arkema S.A. |
| UPC Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta chemical parks concentrate flexible PVC compounding capacity, and their output volumes directly determine pricing leverage for downstream adipate and trimellitate grades serving automotive wire harness manufacturers. REACH Annex XVII expansion and MEE dual carbon permitting are compressing margin pools for conventional phthalate producers while redirecting investment toward certified bio-based alternatives that command formulation premiums.
Pricing Analysis
Solvent-based legacy formulations, water-based conversion grades, and emerging bio-based premium tiers stratify across distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects certification status under EU Green Deal frameworks and volume commitment scale. Cost compression in commodity phthalate tiers is intensifying because Yangtze River Delta overcapacity and Indian import competition. Construction sector procurement teams exhibit highest price sensitivity, while automotive OEM specification engineers prioritize cold-flex performance over unit cost.
Supply Chain Analysis
Extended payment terms from German automotive Tier 1 suppliers and supply-chain finance facilities anchored by BASF's biomass-balanced portfolio are restructuring working capital requirements for mid-size ester producers. Feedstock supply draws from naphtha-cracker output in the US Gulf Coast, 2-ethylhexanol production in Germany's Ruhr Valley, and epoxidized soybean oil processing in China's Jiangsu province. Single-source vulnerability in oxo-alcohol supply exposes compounders to regional refinery maintenance cycles. Distribution runs through regional compounding hubs that blend plasticizers with PVC resin for just-in-time delivery to flooring and cable manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasticizer procurement is evolving toward service-attach models where formulation technical support and carbon accounting documentation generate recurring revenue streams expanding faster than base chemical volumes. Closed-loop vinyl compound recovery services in Germany and the Netherlands demonstrate how waste-stream management contracts now outgrow traditional product sales.
For Market Incumbents: Harden defensible positions in REACH-compliant non-phthalate ester technology through captive 2-ethylhexanol supply and automotive OEM qualification pipelines. Bio-based certification investment represents the critical lever against margin erosion from Yangtze River Delta commodity overcapacity. Capacity addition in Gujarat chemical corridors secures positioning ahead of India's CDSCO medical plastics framework expansion.
For New Entrants and Emerging Players: Establish a beachhead in India's DEHP-free IV bag and tubing segment where CDSCO regulatory expansion has not yet attracted established adipate suppliers. Water-based coating conversion for automotive sealant applications offers penetrable white-space as EPA NESHAP enforcement intensifies. A technical service-led go-to-market angle differentiates against commodity traders lacking formulation chemistry expertise.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between REACH, EPA TSCA Section 6, and China's MEE permitting creates persistent margin opportunities for multi-territory qualification specialists. Acquisition targets should display backward integration into oxo-alcohols or proprietary polymeric plasticizer patents. The signal to watch is ECHA restriction proposal enforcement velocity for DINP in consumer articles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohols | Eastman Chemical's captive 2-ethylhexanol supply secures margin control against naphtha-cracker volatility. |
| Biomass-Balanced Portfolio Certification | BASF's bio-content claims capture preferential access to BMW and Volvo lower-carbon vinyl specifications. |
| Long-term Offtake Agreements | Tarkett and Interface EPD documentation requirements displace spot-market purchasing in commercial flooring. |
| Water-Based Technology Conversion | EPA NESHAP compliance displaces solvent-based plastisols in automotive sealant and textile coating channels. |
| Closed-Loop Vinyl Recovery Services | German mechanical recycling infrastructure enables service-model transition for construction waste streams. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plasticizer plant managers, automotive Tier 1 procurement leads, flooring compound technical directors, and construction sector distribution channel partners. Secondary validation incorporated customs and trade data from ACC and Cefic, SEC 10-K filings from integrated petrochemical conglomerates, and ECHA substance restriction proposal documentation. Bottom-up volume modeling across product chemistry tiers and end-use segments triangulated against top-down macroeconomic indicators from infrastructure investment cycles.
Calibration against historical price realizations and capacity utilization rates anchored the analytical framework across the analysis window. Segmentation dimensions modeled include plasticizer chemistry type, end-use durability requirements, processing technology platform, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-level volume trajectories. Industry-specific forecast inputs encompassed automotive OEM specification tightening timelines and construction sector PVC consumption intensity per square meter of installed flooring.
Stress conditions across naphtha-cracker output volatility, REACH restriction proposal enforcement velocity, and MEE permitting approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure investment persistence and regulatory harmonization failure between jurisdictions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Water-Borne Coating Additives Market
Additives
Global Zinc Stearate Market
Additives
Gelatin Peptones Market
Additives
Global Packaging Additives Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Surface Modifiers Market
Additives
Low VOC Coating Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Global Cement Additives Market
Additives
Caustic Sulphite Caramel Market
Additives
Calcium Acetate Market
Additives
Competitive Inhibitors Market
Additives
Ruminant Feed Additive Market
Additives
Crystal Growth Modifier Market
Additives
Binding Agents Market