
 Crystal Growth Modifier Market | 2026-2036
Crystal Growth Modifier Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Growth Modifier Market Analytics
Modular additive kits that bundle crystal growth modifiers with complementary surfactants and polymers are restructuring how semiconductor foundries and solar cell manufacturers procure process chemicals. BASF SE leverages its integrated organosilicone platform to supply bundled modifier systems across European wafer fabs. Evonik Industries AG anchors its position through specialized polymer additives that control nucleation rates in high-purity silicon production. Dow Chemical Company competes by extending its surfactant expertise into customized modifier blends for hydrothermal crystal growth.
Crystal growth modifiers are specialty chemicals that alter nucleation kinetics, crystal morphology, and growth rates during crystallization, typically functioning at concentrations below one weight percent to direct phase formation in melts or solutions. These compounds serve primarily to eliminate structural defects, control grain boundaries, and enable uniform crystal expansion across photovoltaic, optoelectronic, and microelectronic manufacturing processes. Surfactant-based modifiers capture the largest volume share due to their cost efficiency in solar ingot production, while organosilicone modifiers command premium positioning in semiconductor-grade crystal pulling where defect tolerance approaches atomic-scale precision. Hydrothermal techniques drive fastest-growing modifier consumption as rare-earth and piezoelectric crystal production scales for 5G filter and sensor applications.
REACH registration requirements under ECHA mandate full toxicological profiling for modifier imports into European manufacturing zones, elevating compliance costs for non-EU suppliers. China's SAMR enforces GB standards that classify electronic-grade crystal modifiers by metallic impurity thresholds, directly conditioning market access for foreign producers. EPA oversight of perfluorinated surfactant discharge shapes modifier formulation strategies for US-based semiconductor fabrication. Stakeholders must monitor regulatory divergence between jurisdictions as purity specifications tighten and substitution timelines for legacy chemistries compress.
Market Dynamics
Semiconductor foundries are consolidating modifier procurement around bundled additive systems that eliminate defect rates in sub-10nm silicon pulling operations. This structural pull toward integrated chemical supply is compressing standalone modifier margins while elevating technical barriers for pure-play suppliers.
Growth Catalysts
- Organosilicone platform expansion:Wafer fabs in Taiwan and South Korea are scaling organosilicone modifier volumes for 300mm silicon ingot production. Defect tolerance thresholds now demand atomic-scale purity.
- REACH registration compliance:ECHA mandates under REACH are filtering out non-compliant imports, creating protected market access for registered European suppliers.
- Hydrothermal crystal scaling:Rare-earth and piezoelectric crystal production for 5G filters and sensors is accelerating modifier consumption in Japan and China.
Market Restraints
- High-purity feedstock concentration:Ultra-low metallic impurity organosilicones depend on concentrated German and Japanese precursor supply chains vulnerable to disruption.
- Perfluorinated surfactant substitution timelines:EPA discharge oversight is forcing rapid reformulation of legacy surfactant-based modifiers without performance-mature alternatives.
- Capital intensity of qualification cycles:Semiconductor-grade modifier validation requires 18-24 month fab qualification protocols that lock out new entrants.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme incentives for domestic wafer fabs are creating first-mover modifier supply contracts as fabrication clusters emerge near Gujarat and Tamil Nadu.
- Dual carbon alignment in China:MEE enforcement of dual carbon goals is accelerating water-based modifier adoption in solar ingot production versus solvent-heavy alternatives.
- Modular additive kit bundling:Foundries are consolidating surfactant-polymer-modifier procurement into single-supplier contracts, creating channel control for integrated chemical platforms.
Industry Challenges
- Specialized nucleation kinetics expertise:The talent pool for crystal growth mechanism modeling remains concentrated in German and Japanese research institutes, constraining modifier development teams.
- Cross-jurisdictional purity standard divergence:SAMR GB standards, REACH annexes, and EPA TSCA requirements impose conflicting metallic impurity thresholds that fragment formulation strategies.
- Legacy equipment integration:Hydrothermal growth systems designed for unmodified aqueous chemistry require retrofitting to accommodate precision-dosed modifier injection without contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Growth Modifier Market |
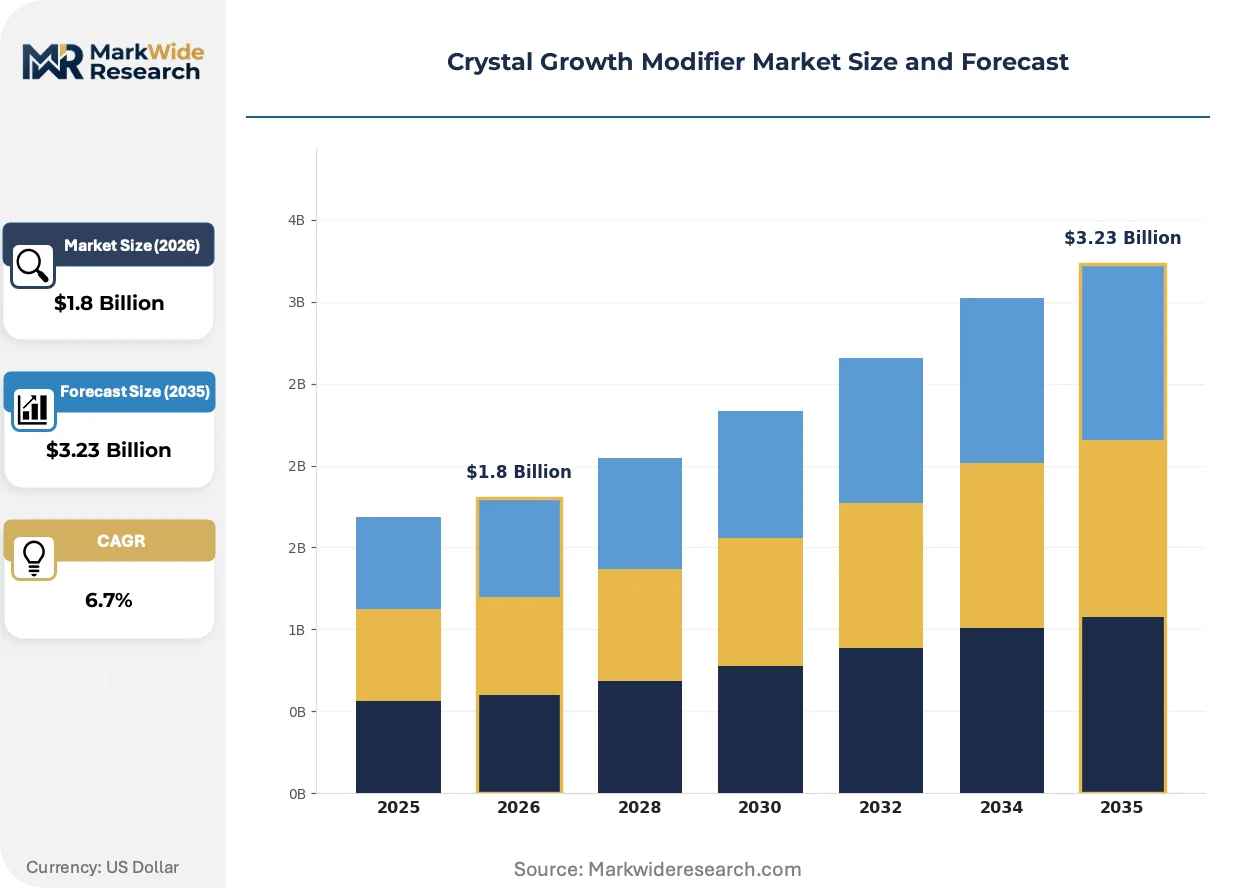
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organosilicone Modifiers, Surfactants, Polymers, Inorganic Additives Application: Solar Cells, Optical Devices, Electronics, Coatings End User: Semiconductor Industry, Renewable Energy, Laboratory Research, Defense Sector Technology: Solvothermal Methods, Hydrothermal Techniques, Melt Growth, Crystal Pulling |
| Companies Covered | BASF SE, Evonik Industries AG, Dow Chemical Company, Clariant, Solvay, Merck KGaA, Sigma-Aldrich, Huntsman Corporation, Borregaard LignoTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Growth Modifier Market Evolving Landscape
Modifier technology is converging around real-time nucleation control systems that integrate in-situ monitoring with automated dosing. This shift is compressing the gap between laboratory formulation and fab-scale deployment.
AI-driven crystal morphology prediction platforms are unifying computational materials science with fab process control. TSMC and Samsung Foundry are piloting these systems for silicon ingot pulling. The technology is unifying modifier selection with thermal gradient optimization, collapsing traditional trial-and-error qualification cycles.
REACH annex revisions under ECHA are tightening reproductive toxicity thresholds for organosilicone imports into European wafer fabrication zones. This is accelerating substitution investments toward bio-based nucleation controllers. German and French modifier suppliers are responding with accelerated green chemistry registration dossiers.
Long-term chemical management contracts are displacing spot purchasing at major semiconductor foundries. Modifier suppliers now embed technical service teams directly within fab process engineering groups. This restructuring is most visible in Taiwan's Hsinchu Science Park, where bundled supply agreements now span 5-7 year terms with performance-linked pricing.
Crystal Growth Modifier Market Segmentation
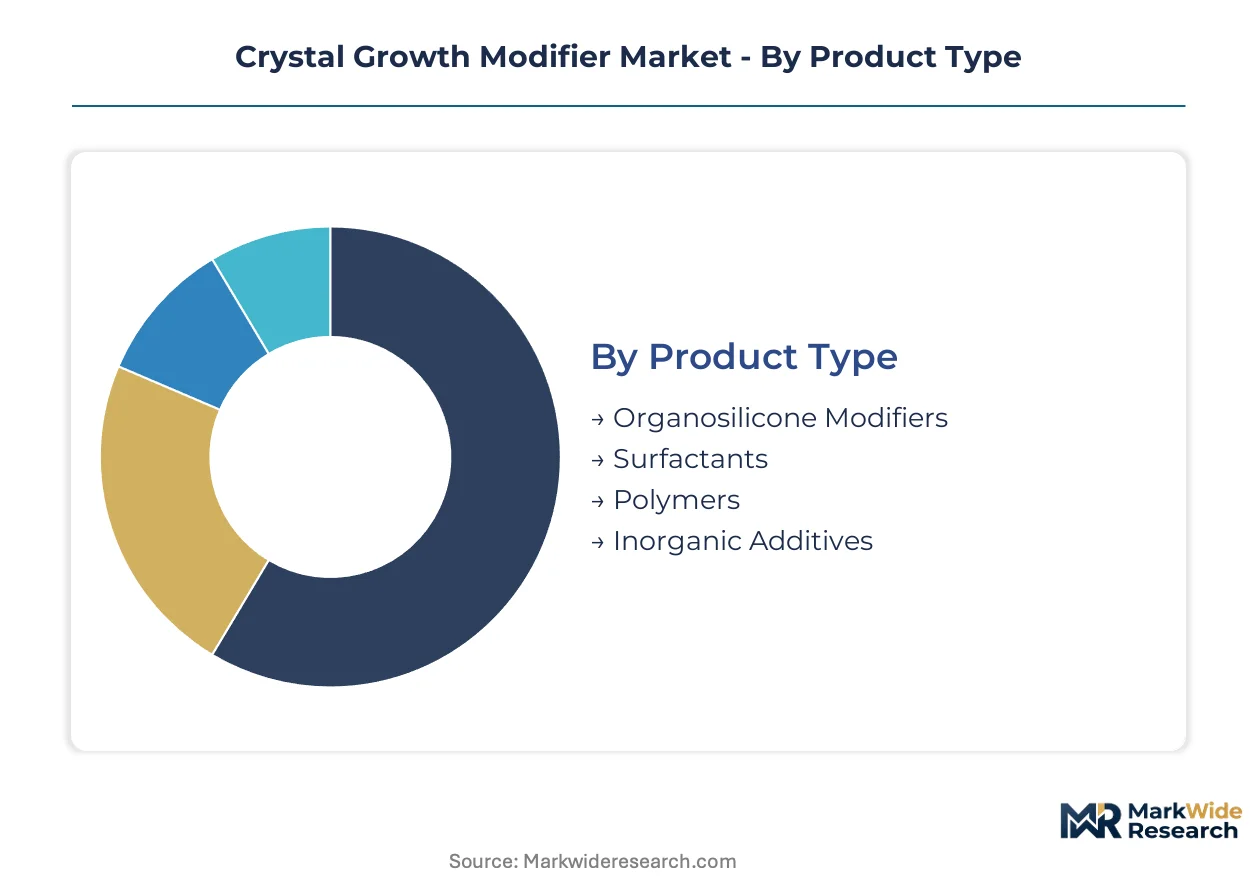
Crystal growth modifier procurement patterns diverge sharply by product chemistry and application purity requirements. Semiconductor foundries demand atomic-scale precision from organosilicone platforms, while solar ingot producers prioritize cost-efficient surfactant volumes. Understanding these segment boundaries exposes where technical specifications override price sensitivity.
Product Type:
Upgrade cycles in silicon wafer fabrication are accelerating replacement of legacy surfactant systems with organosilicone platforms capable of sub-10nm defect control.
- Organosilicone Modifiers:Silicon-based compounds engineered for atomic-scale purity in semiconductor-grade crystal pulling. Taiwan's TSMC and South Korea's Samsung Foundry are expanding procurement volumes for 300mm ingot production where metallic impurity thresholds approach parts-per-trillion specifications.
- Surfactants:Amphiphilic molecules that reduce interfacial tension in melt and solution growth environments. Solar cell manufacturers in China and India deploy surfactant-based modifiers for polycrystalline silicon ingot production where cost efficiency outweighs atomic precision requirements.
- Polymers:Macromolecular additives controlling nucleation kinetics through steric stabilization mechanisms. German and Japanese suppliers dominate qualification for specialty optical crystal growth.
- Inorganic Additives:Metallic salt and oxide compounds for high-temperature melt growth applications. Demand concentrates in legacy LED substrate and industrial sapphire production.
Volume placements concentrate in Surfactants; the faster expansion belongs to Organosilicone Modifiers.
Application:
Cost tier stratification separates premium semiconductor applications from standard-grade solar and coating segments.
- Electronics:Microelectronic manufacturing demands modifiers capable of eliminating dislocation densities in single-crystal silicon. Japan's Shin-Etsu Chemical and Germany's Wacker Chemie anchor supply for logic and memory chip fabrication where qualification cycles extend 18-24 months.
- Solar Cells:Photovoltaic ingot growth prioritizes throughput over atomic perfection. China's LONGi Green Energy and Tongwei Solar drive surfactant modifier consumption in multicrystalline and monocrystalline silicon casting.
- Optical Devices:Laser crystal and nonlinear optical material production requires precise dopant distribution control. Russian and Ukrainian raw material access disruptions have compressed modifier supply chains for YAG and YVO4 crystal growth.
- Coatings:Thin-film and protective layer crystallization uses modifiers to direct phase formation in vapor deposition processes. Aerospace and automotive glass coating applications in Germany and the United States sustain modest specialty volumes.
Electronics commands premium pricing; Solar Cells generates the steepest volume expansion trajectory.
End User:
Customer type determines contract structure, with semiconductor foundries demanding embedded technical service versus solar producers' spot purchasing.
- Semiconductor Industry:Integrated device manufacturers and pure-play foundries procure modifiers through 5-7 year bundled supply agreements. TSMC's Hsinchu cluster and Intel's Arizona fabs require suppliers to station process engineers on-site.
- Renewable Energy:Solar wafer and cell producers operate on quarterly procurement cycles with limited technical integration. India's PLI scheme incentives are creating first-mover modifier contracts as domestic ingot capacity scales near Gujarat.
- Laboratory Research:Academic and national laboratory crystal growth facilities purchase modifiers in kilogram quantities for materials science exploration. Japan's NIMS and Germany's Fraunhofer institutes influence early-stage formulation development.
- Defense Sector:Classified programs for infrared and piezoelectric crystal production impose security-cleared supply chain requirements. US-based modifier suppliers face ITAR compliance constraints on technical data sharing.
Semiconductor Industry locks in longest contract terms; Renewable Energy is climbing the fastest.
Technology:
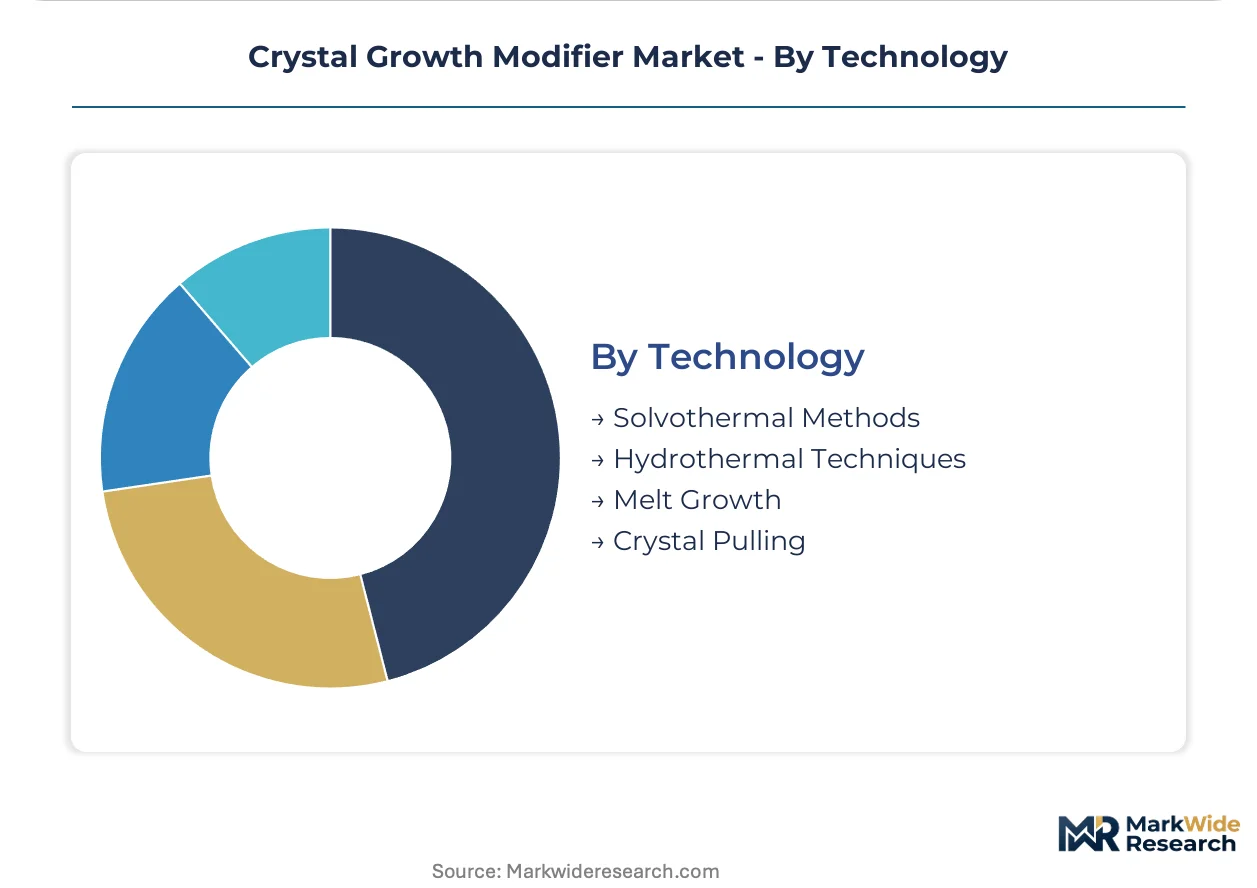
Technology maturity curves separate established melt methods from emerging hydrothermal scaling.
- Hydrothermal Techniques:High-pressure aqueous synthesis of rare-earth and piezoelectric crystals for 5G filter applications. Japan's Murata Manufacturing and China's CETC expand modifier consumption for quartz and langasite crystal production.
- Crystal Pulling:Czochralski and float-zone methods for semiconductor-grade silicon ingot growth. German and Japanese equipment suppliers specify modifier injection protocols for 300mm single-crystal production.
- Solvothermal Methods:Organic solvent-based synthesis for nanocrystal and quantum dot formation. South Korean display panel producers deploy solvothermal modifiers for OLED phosphor crystal engineering.
- Melt Growth:Bridgman and Stockbarger techniques for halide and oxide crystal solidification. Scintillator crystal production for medical imaging and radiation detection sustains steady modifier demand.
Crystal Pulling retains dominant volume share; Hydrothermal Techniques is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of solar-grade crystal growth modifiers while Taiwan and South Korea consume the highest-purity semiconductor grades. This production-consumption asymmetry shapes trade flows and qualification requirements across East Asian supply chains.
China
Domestic solar ingot manufacturers drive surfactant modifier volumes through LONGi Green Energy and Tongwei Solar expansion. SAMR enforces GB standards on metallic impurity thresholds for electronic-grade imports. Yangtze River Delta clusters near Shanghai concentrate hydrothermal quartz crystal production for 5G filter applications.
Taiwan
TSMC and United Microelectronics Corporation anchor global demand for organosilicone modifiers in 300mm silicon pulling. The island's national science council aligns procurement with REACH-equivalent purity protocols. Hsinchu Science Park hosts embedded technical service teams from major chemical suppliers under 5-7 year bundled contracts.
South Korea
Samsung Foundry and SK Hynix scale modifier consumption for sub-10nm logic and memory chip fabrication. MFDS regulates chemical imports through pharmaceutical-grade purity equivalency requirements. Pyeongtaek and Yongin semiconductor clusters specify atomic-scale defect tolerance in supplier qualification.
Germany
Wacker Chemie and Merck KGaA anchor European organosilicone modifier supply for domestic wafer fabs. ECHA REACH registration mandates filter non-compliant imports, creating protected market access. Saxony's Silicon Saxony cluster links Dresden fabs with qualification laboratories at Fraunhofer institutes.
Japan
Shin-Etsu Chemical and Murata Manufacturing drive dual demand for semiconductor and piezoelectric crystal modifiers. METI coordinates national purity standards with JIS certification requirements. Kyushu's Kumamoto and Miyazaki prefectures concentrate quartz crystal production for automotive and telecommunications applications.
Crystal Growth Modifier Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. BASF SE and Dow Chemical Company leverage integrated chemical platforms to bundle modifiers with complementary surfactants and polymers. Three archetypes dominate: integrated diversified platforms, organosilicone specialists, and surfactant-focused suppliers. Consolidation through long-term fab qualification partnerships and backward integration into high-purity precursor supply are reshaping competitive boundaries.
Within the integrated platform tier, BASF SE exemplifies conglomerate diversification across European wafer fab supply. Evonik Industries AG and Dow Chemical Company occupy positions spanning organosilicone and surfactant modifier categories. These three anchors represent distinct strategic postures: BASF's bundled system approach, Evonik's nucleation control specialization, and Dow's surfactant-to-modifier extension model.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Dow Chemical Company |
| Clariant |
| Solvay |
| Merck KGaA |
| Sigma-Aldrich |
| Huntsman Corporation |
| Borregaard LignoTech |
| Others |
Value Network & Pricing Analysis
High-purity organosilicone precursor indices in Germany and Japan cascade through three distinct pricing tiers, with semiconductor-grade modifiers commanding multiples over solar-grade surfactants due to concentrated feedstock control and extended qualification protocols.
Pricing Analysis
Margin tightening in solar-grade surfactant tiers reflects Chinese domestic capacity expansion and spot-market commoditization. Three-tier pricing structure across semiconductor-grade, industrial-grade, and solar-grade levels separates atomic-purity organosilicones from multicrystalline ingot additives. Cost-down pressure on standard-grade modifiers accelerates because LONGi and Tongwei are consolidating procurement volumes. Semiconductor foundries exhibit lowest price sensitivity due to defect-tolerance requirements, while solar cell manufacturers drive hardest bargain negotiations.
Supply Chain Analysis
Freight cost differentials between German precursor hubs and East Asian fabrication clusters widen landed cost spreads for European suppliers competing in Taiwan and South Korea. Supply concentrates in Germany, Japan, and China for high-purity organosilicones, chlorosilane precursors, and rare-earth processing reagents. Downstream distribution runs through qualified chemical distributors with fab-embedded technical service teams rather than commodity traders. Single-source vulnerability persists for semiconductor-grade organosilicone platforms where Wacker Chemie and Shin-Etsu Chemical anchor precursor supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into high-purity precursor production, with qualification-locked incumbents deepening captive supply of organosilicone feedstocks to defend margin structures against Asian cost competitors.
For Market Incumbents: Anchor position through exclusive long-term supply agreements with TSMC and Samsung Foundry that embed technical service teams on-site for 5-7 year contract windows. Deepen captive supply of chlorosilane precursors through Saxony-based production partnerships with Wacker Chemie to offset Asian cost pressure. Defend against modular additive kit bundling by BASF and Dow through nucleation kinetics specialization that pure-play surfactant suppliers cannot replicate. For New Entrants and Emerging Players: Solar cell manufacturers in India present the most penetrable entry point as PLI scheme incentives scale domestic ingot capacity near Gujarat and Tamil Nadu. Specialty polymer modifiers for hydrothermal quartz crystal production offer white-space opportunity given Murata Manufacturing's 5G filter expansion and limited qualified supplier base. Partner with established German or Japanese equipment OEMs to bypass 18-24 month standalone qualification protocols through pre-certified modifier injection systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap organosilicone specialists with REACH registration dossiers and existing fab relationships in European wafer fabrication zones. Long-term viability hinges on qualification moats that extend 5-10 years beyond initial contract signing. Monitor ECHA annex revisions on reproductive toxicity thresholds as inflection signal for bio-based nucleation controller substitution investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive chlorosilane production locks in margin control against Asian feedstock volatility. |
| Long-term Supply Agreement with Foundry | TSMC's Hsinchu cluster demands 5-7 year bundled contracts with performance-linked pricing mechanisms. |
| Green Chemistry Registration Dossier | ECHA REACH revisions accelerate bio-based nucleation controller qualification for European wafer fabs. |
| Joint Venture with Equipment OEM | Pre-certified modifier injection systems collapse 18-24 month standalone qualification timelines. |
| Capacity Expansion in India | PLI scheme incentives for domestic wafer fabs create first-mover modifier contracts near Gujarat clusters. |
Research Methodology
Independent corroboration across semiconductor process engineers, solar ingot production managers, and specialty chemical procurement leads underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with downstream OEM technical directors and distribution channel partners. Secondary validation drew from customs trade databases, SEC 10-K filings of diversified chemical platforms, and ECHA REACH registration dossiers. Bottom-up volume estimates from individual fab consumption patterns triangulate against top-down market sizing from precursor production capacity disclosures.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the projection horizon. Segmentation modeling incorporates product chemistry tier, application purity requirements, end-user contract structure, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical fab capacity announcements and announced precursor capacity additions. Industry-specific forecast inputs include semiconductor node migration timelines and solar cell technology shift rates from multicrystalline to monocrystalline architectures.
Caveats apply where ECHA REACH annex revisions, EPA perfluorinated surfactant discharge rulings, or SAMR GB standard updates could materially shift the outlook for modifier formulation strategies. Forecasts embed assumptions on qualification cycle durations and precursor supply chain stability that may compress or extend depending on geopolitical trade measures. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Wear Additives Market
Additives
Pearlizers Market
Additives
Triazine UV Absorber Market
Additives
Sodium Caprylate Market
Additives
Ascorbyl Stearate Market
Additives
North America Potassium Nitrate Market
Additives
Thallium Acetate Market
Additives
Polyols and Sorbitols Products Market
Additives
Disodium Inosinate Market
Additives
Global Propyl Acetate Market
Additives
Refining Additives Market
Additives
Bromine Derivatives Market
Additives
Octane Improver Fuel Additives Market
Additives
Tricalcium Citrate Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Shortstop Inhibitor Market