
 Gelatin Peptones Market | 2026-2036
Gelatin Peptones Market Size, Share, and Industry Trends Forecast 2026-2036
Gelatin Peptones Market Analytics
European gelatin hydrolysate producers is pivoting toward pharmaceutical-grade certification to capture bioprocessing demand. Thermo Fisher Scientific Inc. leverages its distribution depth across North American research institutions. Merck KGaA anchors European supply through ISO-certified manufacturing sites. HiMedia Laboratories competes on cost-optimized laboratory-grade formulations for emerging-market microbiology labs.
Gelatin peptones represent enzymatically digested collagen fractions, typically yielding peptides between 200 and 20,000 daltons, manufactured through controlled acid or alkaline hydrolysis of animal connective tissues for use as nitrogen-rich culture media supplements. The powder form dominates current procurement volumes due to stability and freight efficiency, though liquid concentrates gain traction in high-throughput automated workflows. Pharmaceutical-grade peptones command premium positioning as cell therapy manufacturers enforce raw-material traceability, while food-grade applications mature in fermented beverage and savory flavor production.
FDA oversight of cell culture media components and EMA guidelines on transmissible spongiform encephalopathies constrain bovine-source peptone circulation, creating compliance barriers for non-certified suppliers. China's NMPA and SAMR enforce parallel GB standards for domestic biopharmaceutical raw materials, fragmenting import pathways. Stakeholders must monitor evolving substitution economics as recombinant protein hydrolysates and plant-derived nitrogen sources challenge animal-based incumbent positions.
Market Dynamics
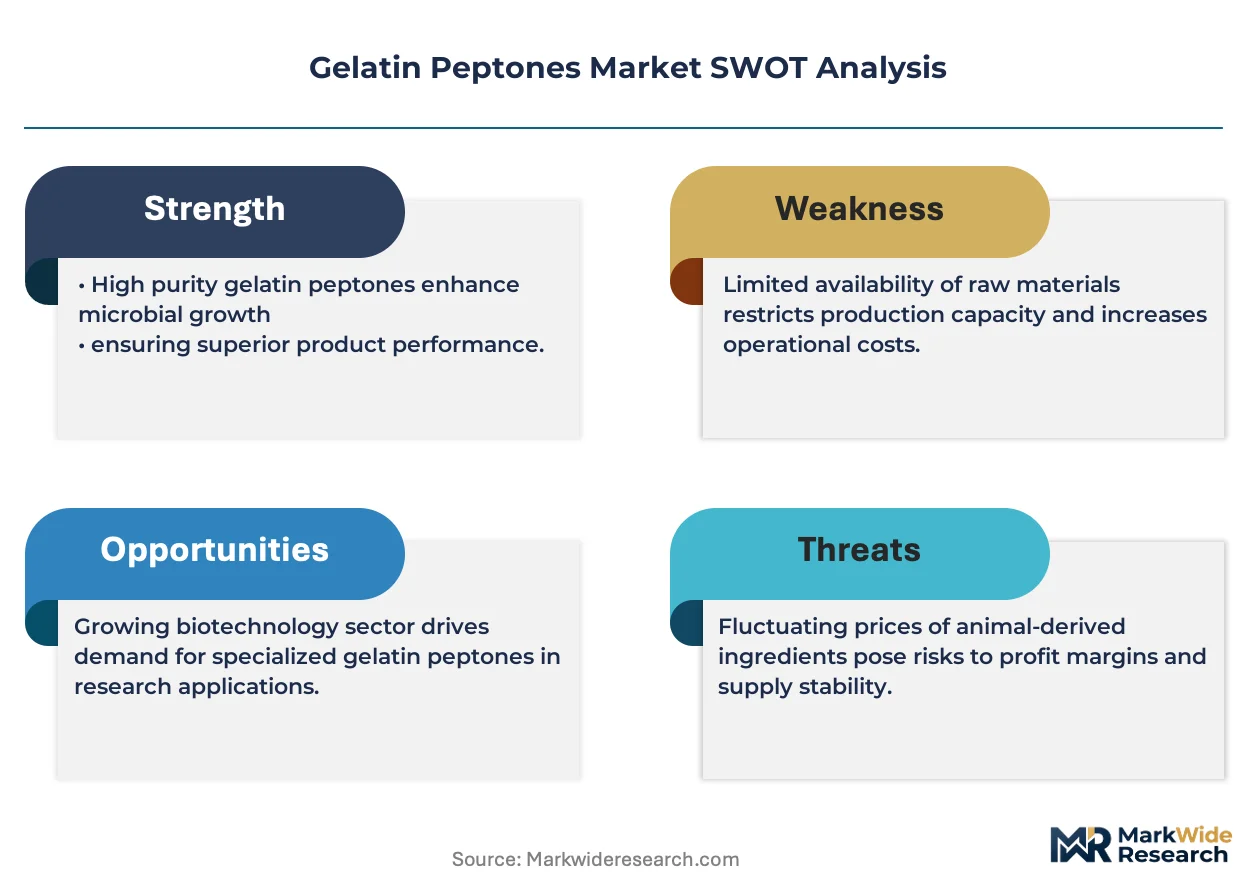
Regulatory divergence around bovine-source materials is fragmenting supply chains and forcing manufacturers to requalify raw-material streams across multiple certification regimes simultaneously.
Growth Catalysts
- Cell therapy manufacturing scale-up:Autologous and allogeneic cell therapy producers in the United States and Germany are expanding GMP-grade peptone consumption for serum-free media formulations.
- EMA TSE compliance deadlines:European biopharmaceutical manufacturers face mandatory documentation requirements for transmissible spongiform encephalopathy safety, accelerating certified porcine peptone procurement.
- Food safety testing infrastructure:China's SAMR is expanding microbiological surveillance networks, driving laboratory-grade peptone demand for pathogen detection workflows in provincial testing centers.
Market Restraints
- Collagen input cost volatility:Gelatin feedstock prices fluctuate with livestock supply cycles and rendering industry consolidation, compressing peptone producer margins.
- Bovine-source regulatory friction:FDA and EMA documentation requirements for bovine-derived materials create compliance barriers for non-certified suppliers seeking market access.
- Plant-derived nitrogen substitution:Soy and pea protein hydrolysates are gaining formulation trials in non-pharmaceutical applications, threatening commodity peptone positions.
Strategic Opportunities
- Marine collagen peptone certification:Fish-sourced hydrolysates offer TSE-free positioning for European and North American pharmaceutical markets with stringent prion safety requirements.
- Automated liquid handling adoption:High-throughput screening facilities are switching from powder to sterile liquid peptone concentrates to reduce preparation labor and contamination risk.
- Indian biopharmaceutical manufacturing expansion:CDSCO-aligned GMP facilities in Hyderabad and Bangalore represent underpenetrated demand for pharmaceutical-grade culture media components.
Industry Challenges
- Pharmaceutical-grade certification timelines:Achieving ISO 13485 and FDA Drug Master File status requires 18-24 month validation cycles that delay revenue recognition.
- Multi-regional traceability systems:Suppliers must maintain parallel documentation streams for EMA, FDA, and NMPA requirements, increasing quality management overhead.
- Skilled fermentation technologist scarcity:Enzymatic hydrolysis process optimization requires specialized expertise that concentrates among legacy gelatin industry personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelatin Peptones Market |
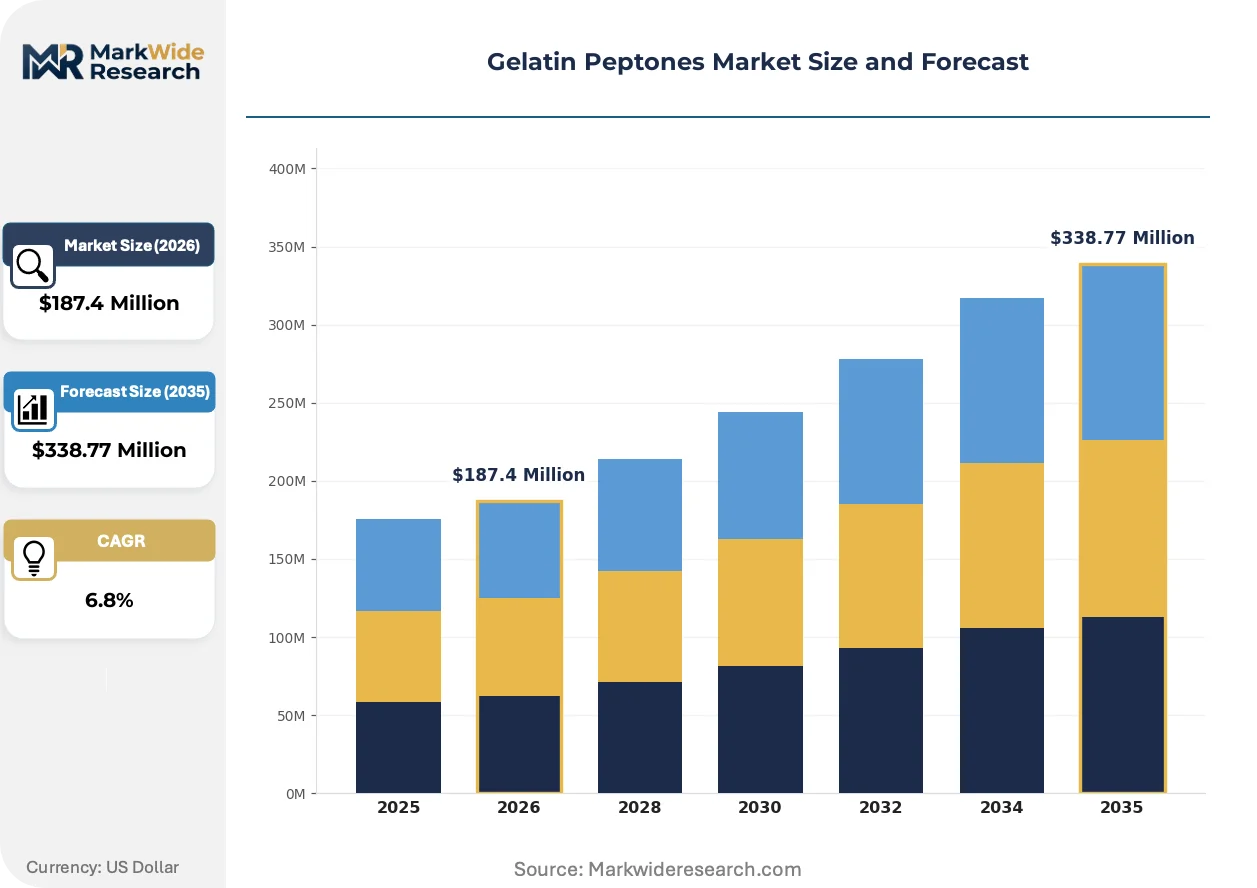
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Laboratory Grade, Technical Grade Application: Microbiology, Food Industry, Cosmetic Industry, Nutraceuticals Form: Powder, Granules, Gel, Liquid Source: Bovine, Porcine, Fish, Others |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, HiMedia Laboratories, Kerry Group, Biospringer S.A, Titan Biotech Limited, Central Drug House, BD Biosciences Systems & Reagents Inc., CONDALAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelatin Peptones Market Evolving Landscape
Enzymatic processing advances and regulatory data digitization are compressing product development cycles while raw-material traceability systems are becoming competitive differentiators in pharmaceutical procurement.
Spray-drying control systems with inline particle size monitoring are automating batch-to-batch consistency in peptone powder production. Contract manufacturing organizations in Germany and the United States are deploying these systems to meet pharmaceutical client specifications for peptide molecular weight distribution. The technology is automating quality assurance labor previously requiring offline chromatography verification.
EMA's updated guideline on minimizing risk of transmitting animal spongiform encephalopathies via medicinal products is tightening bovine-source documentation requirements. Manufacturers must now submit geographic sourcing certificates and rendering facility audits for each production lot. European plasma-derived therapy producers are responding by dual-sourcing porcine and marine alternatives to reduce supply interruption exposure.
Pharmaceutical buyers are consolidating supplier relationships around providers offering integrated raw-material traceability databases. Large biopharmaceutical manufacturers in the United States are replacing spot purchasing with multi-year sole-source agreements contingent on real-time batch record access. This pattern is most pronounced among cell therapy developers in Boston and San Francisco requiring uninterrupted GMP-grade supply for clinical manufacturing.
Gelatin Peptones Market Segmentation
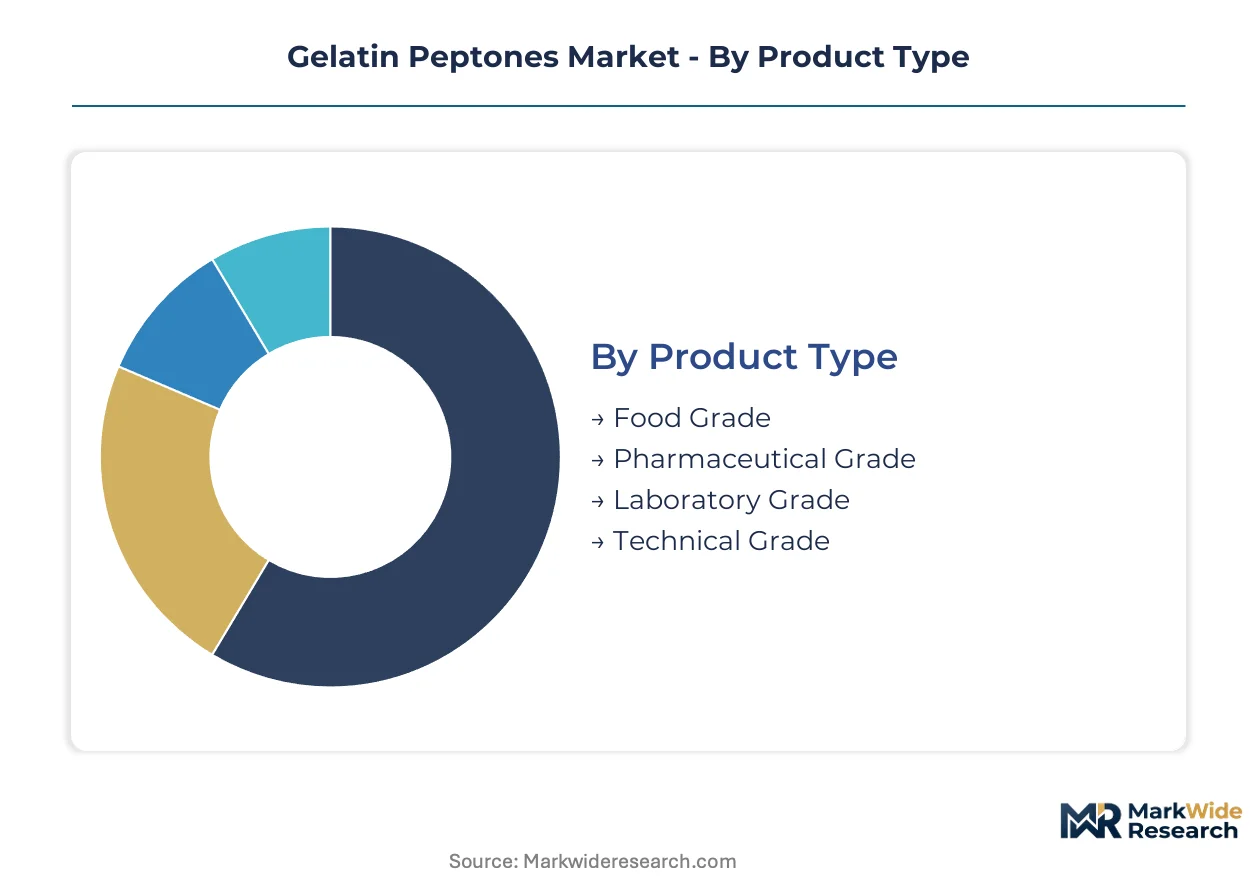
Peptone procurement patterns diverge sharply across certification tiers and end-use specifications, with pharmaceutical-grade traceability commanding premium positioning while laboratory-grade volumes scale through emerging-market infrastructure buildouts. Understanding these segment boundaries clarifies where margin compression and substitution threats concentrate.
Product Type:
Supply concentration in pharmaceutical-grade certification creates tiered market access, with ISO 13485 and FDA Drug Master File status filtering viable competitors.
- Pharmaceutical Grade:Peptones manufactured under GMP conditions with documented TSE-free sourcing and peptide molecular weight specifications between 200-20,000 daltons. Autologous cell therapy producers in the United States and Germany require sole-source agreements with real-time batch record access for clinical manufacturing workflows.
- Laboratory Grade:Standardized nitrogen supplements for diagnostic microbiology with validated growth promotion properties. China's provincial SAMR testing centers drive procurement volumes as food safety surveillance networks expand pathogen detection capacity.
- Food Grade:Fermented beverage and savory flavor production inputs with FSSAI or FDA food additive compliance.
- Technical Grade:Industrial fermentation and non-pharmaceutical bioprocessing applications with basic hydrolysate specifications.
Today's leader: Pharmaceutical Grade. Tomorrow's challenger: Laboratory Grade.
Application:
Cost tier differentiation separates serum-free media formulations from commodity nitrogen sourcing, with reimbursement economics dictating acceptable raw-material expenditure.
- Microbiology:Culture media foundation for bacterial enumeration and identification protocols. Academic and industrial laboratories in Germany and China represent core demand nodes as cell culture workflows standardize.
- Food Industry:Fermentation nutrient for yeast extracts, meat flavors, and beverage production. European savory flavor manufacturers source food-grade hydrolysates under EFSA additive regulations.
- Cosmetic Industry:Collagen-derived peptides for topical formulation claims with INCI nomenclature compliance.
- Nutraceuticals:Dietary supplement protein hydrolysates with amino acid profile labeling requirements.
Microbiology commands current procurement volumes. Nutraceuticals present the steepest expansion trajectory as functional ingredient portfolios diversify.
Form:
Volume economics favor powder stability and freight efficiency, though automated liquid handling is reshaping high-throughput facility specifications.
- Powder:Dominant procurement format with 24-month shelf stability and reduced shipping costs. Spray-drying control systems with inline particle size monitoring automate batch consistency for German and United States contract manufacturers.
- Liquid:Sterile concentrates for automated pipetting workstations in screening facilities. Boston and San Francisco cell therapy developers specify liquid formats to reduce preparation labor and contamination risk in GMP suites.
- Granules:Intermediate dissolution properties for specific fermentation vessel configurations.
- Gel:Specialized cosmetic and topical delivery applications with viscosity-controlled rheology.
Powder retains procurement dominance. Liquid concentrates gain share fastest in automated pharmaceutical manufacturing.
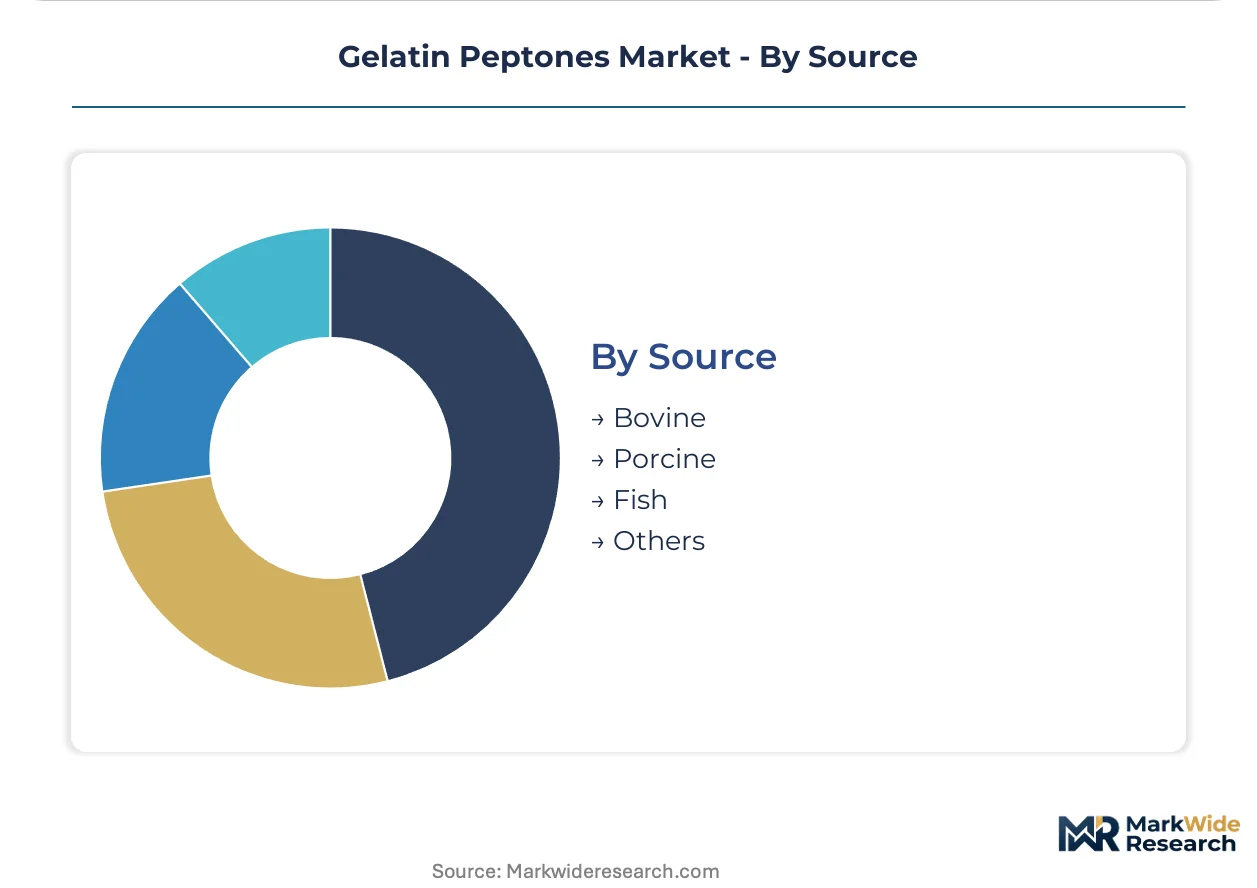
Source:
Geography-driven regulatory divergence fragments raw-material streams, with TSE compliance redirecting sourcing away from bovine origins in EMA and FDA jurisdictions.
- Porcine:Primary TSE-free alternative for European and North American pharmaceutical markets. EMA guideline updates mandate geographic sourcing certificates and rendering facility audits for each production lot, accelerating certified porcine procurement.
- Fish:Marine collagen hydrolysates with prion-free positioning for stringent safety requirements. European plasma-derived therapy producers dual-source fish alternatives to reduce supply interruption exposure.
- Bovine:Constrained by FDA and EMA documentation requirements for transmissible spongiform encephalopathies, creating compliance barriers for non-certified suppliers.
- Others:Poultry and avian-sourced hydrolysates with regional availability in specific markets.
Porcine anchors current supply security. Fish sources represent the fastest-climbing alternative as marine certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence in transmissible spongiform encephalopathy compliance is creating arbitrage opportunities where manufacturers relocate enzymatic hydrolysis capacity toward jurisdictions with streamlined certification pathways. This migration pattern concentrates investment in countries with aligned pharmaceutical-grade standards and accessible raw-material streams.
United States
Autologous cell therapy manufacturing in Boston and San Francisco drives GMP-grade peptone procurement for serum-free media formulations. FDA Drug Master File requirements and ISO 13485 certification filter viable suppliers, extending validation timelines for new market entrants. The Southeast corridor attracts contract manufacturing investment as pharmaceutical clusters expand beyond traditional Northeast strongholds.
Germany
EMA guideline updates on minimizing TSE transmission risk mandate geographic sourcing certificates and rendering facility audits for each production lot. Bavaria and North Rhine-Westphalia host ISO-certified manufacturing sites serving European plasma-derived therapy producers. Spray-drying control systems with inline particle size monitoring automate batch consistency for pharmaceutical clients demanding peptide molecular weight distribution specifications.
China
NMPA and SAMR enforcement of GB standards for domestic biopharmaceutical raw materials fragments import pathways while expanding provincial testing center capacity. Yangtze River Delta biopharmaceutical clusters absorb laboratory-grade peptone volumes as food safety surveillance networks strengthen pathogen detection infrastructure. Shanghai and Suzhou manufacturing bases serve both domestic demand and regulated export markets.
India
CDSCO-aligned GMP facilities in Hyderabad and Bangalore represent underpenetrated demand for pharmaceutical-grade culture media components as contract development and manufacturing organizations expand. Cost-optimized laboratory-grade formulations gain traction in academic microbiology laboratories. Central Drug House and regional distributors compete on freight efficiency to provincial testing centers.
Japan
PMDA oversight of cell culture media components aligns with EMA and FDA prion safety requirements, constraining bovine-source material circulation. Kanto region pharmaceutical manufacturers specify TSE-free porcine and marine alternatives for therapeutic protein production. METI industrial biotechnology programs support enzymatic hydrolysis process optimization for domestic gelatin hydrolysate producers seeking pharmaceutical-grade certification.
Gelatin Peptones Market Competitive Landscape
United States and German producers anchor the premium certification tier; Indian and Chinese specialists hold cost-optimized laboratory-grade positions. Market structure stratifies across three certification tiers with ISO 13485 and FDA Drug Master File status filtering viable competitors at the pharmaceutical grade. Strategic archetypes include diversified life science conglomerates with distribution depth, regional chemical manufacturers with enzymatic hydrolysis heritage, and emerging-market formulators competing on freight efficiency. Dominant competitive moves encompass backward integration into rendering operations and multi-year sole-source agreements contingent on real-time batch record access.
Within the diversified life science tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify archetypes combining distribution infrastructure with regulatory certification depth. HiMedia Laboratories occupies a position representing cost-optimized regional formulators serving emerging-market microbiology demand. These three anchors illustrate how competitive positioning diverges across certification tiers rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| HiMedia Laboratories |
| Kerry Group |
| Biospringer S.A |
| Titan Biotech Limited |
| Central Drug House |
| BD Biosciences Systems & Reagents Inc. |
| CONDALAB |
| Others |
Value Network & Pricing Analysis
Cell therapy manufacturers in Boston and San Francisco operate on multi-year sole-source agreements contingent on real-time batch record access, anchoring a contract-based pricing model where pharmaceutical-grade certification commands substantial premiums over laboratory-grade alternatives.
Pricing Analysis
Distributor margins absorb freight and cold-chain logistics costs for powder formats, while direct-to-manufacturer contracts eliminate intermediary markups for liquid concentrate volumes in high-throughput screening facilities. Three-tier pricing structure across pharmaceutical, laboratory, and food-grade levels reflects ISO 13485 certification status and peptide molecular weight distribution specifications. Pricing pressure stems from plant-derived nitrogen hydrolysates gaining formulation trials in non-pharmaceutical applications. Academic microbiology laboratories exhibit highest price sensitivity, whereas autologous cell therapy producers prioritize supply security over unit cost.
Supply Chain Analysis
Freight economics favor powder stability and extended shelf life, reducing per-unit logistics expenditure for German and United States contract manufacturers serving European plasma-derived therapy producers. Supply concentrates in Germany, China, and India, with enzymatic hydrolysis capacity clustering near rendering facilities and pharmaceutical manufacturing corridors. Raw material streams draw from porcine rendering operations, marine collagen harvesting, and bovine connective tissue processing where TSE documentation permits. Single-source vulnerability concentrates in certified porcine peptone streams for EMA-compliant pharmaceutical applications. Distribution runs through life science distributors for research-grade volumes and direct procurement channels for GMP-certified pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gelatin Peptones Market functions as a geographic-arbitrage play where EMA TSE compliance deadlines in Europe accelerate certified porcine procurement premiums while China's SAMR expansion creates volume absorption capacity at lower certification tiers.
For Market Incumbents: Lock in multi-year sole-source agreements with cell therapy developers requiring uninterrupted GMP-grade supply by investing in backward integration into rendering operations and ISO 13485 certification maintenance. Plant-derived nitrogen substitution threatens commodity peptone positions in food and technical grades; defend through marine collagen peptone certification for TSE-free pharmaceutical positioning. Prioritize spray-drying control systems with inline particle size monitoring to automate batch consistency and reduce quality assurance labor overhead. For New Entrants and Emerging Players: Capture underpenetrated demand in India's CDSCO-aligned GMP facilities in Hyderabad and Bangalore by offering cost-optimized laboratory-grade formulations with freight efficiency to provincial testing centers. The most penetrable segment lies in automated liquid handling adoption, where sterile liquid concentrates reduce preparation labor for high-throughput screening facilities. Pursue a go-to-market angle centered on real-time batch record access and integrated traceability databases that pharmaceutical buyers increasingly mandate. For Investors and Strategic Acquirers: Life science conglomerates with distribution depth represent the most active acquirer in this space, seeking enzymatic hydrolysis heritage to fill pharmaceutical-grade certification gaps. Over a five-to-ten-year horizon, recombinant protein hydrolysates and plant-derived nitrogen sources will displace animal-based incumbent positions in non-pharmaceutical tiers. Target acquisition archetypes include regional chemical manufacturers with ISO-certified manufacturing sites and established rendering relationships. Watch for inflection signals in EMA guideline updates tightening bovine-source documentation requirements, which accelerate certified porcine and marine alternative procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Collagen Peptone Certification | Fish-sourced hydrolysates unlock TSE-free positioning for EMA and FDA pharmaceutical markets with stringent prion safety requirements. |
| Automated Liquid Handling Adoption | Sterile liquid concentrates reduce preparation labor and contamination risk in Boston and San Francisco cell therapy GMP suites. |
| Backward Integration into Rendering | In-house production of porcine collagen feedstock secures supply continuity against livestock supply cycle volatility. |
| Real-Time Batch Record Access | Integrated traceability databases meet pharmaceutical buyer procurement criteria for sole-source agreement consolidation. |
| Spray-Drying Control System Deployment | Inline particle size monitoring automates batch-to-batch consistency for German contract manufacturers serving peptide molecular weight specifications. |
Research Methodology
Bottom-up microbiology laboratory and cell therapy manufacturing modeling reconciled against top-down gelatin hydrolysate production tracking forms the analytical core of this study. Primary interviews with fermentation technologists, quality assurance directors at peptone manufacturers, procurement managers at biopharmaceutical firms, and regulatory affairs specialists at EMA and FDA jurisdictions combined with secondary validation from customs trade data, SEC filings of diversified life science conglomerates, ISO certification registries, and EMA guideline documentation. Triangulation across these sources ensures demand-side consumption estimates align with supply-side capacity disclosures.
Input-output matrices map enzymatic hydrolysis capacity against end-use consumption across pharmaceutical grade, laboratory grade, food grade, and technical grade tiers, further segmented by powder, liquid, granule, and gel formats. Growth projections derive from cell therapy manufacturing expansion rates, EMA TSE compliance deadline impacts, and food safety testing infrastructure buildouts across the analysis window. Modeled dimensions include certification tier, application vertical, physical form, and collagen source origin, with CAGRs calibrated against historical price elasticity and substitution dynamics between animal-derived and plant-derived nitrogen sources.
Underlying measurement precision varies by segment; pharmaceutical-grade consumption carries tighter precision than technical-grade volumes given consolidated buyer concentration and mandatory reporting requirements. Forecasts reflect assumptions regarding EMA guideline enforcement timelines, NMPA GB standard alignment, and marine collagen certification pathway maturation. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Organic Friction Modifier Additives Market
Additives
Lead Stearate Market
Additives
Inorganic Filler Market
Additives
Anti-Creasing Agent Market
Additives
Canada Anti-Caking Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Thallium Acetate Market
Additives
Hydroxyethyl Cellulose Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Tackifier Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Canada Water Enhancer Market
Additives
Refinery Fuel Additives Market
Additives
Europe Citric Acid Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Citrate Ester Market