
 Dry-Mix Mortar Additives and Chemicals Market | 2026-2036
Dry-Mix Mortar Additives and Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Dry-Mix Mortar Additives and Chemicals Market Foresight
Premium performance additives is decoupling from commodity-grade chemicals as construction specifications tighten. BASF SE leverages its polymer dispersion portfolio to command pricing power in high-strength tile adhesives. Sika AG anchors its position through waterproofing-grade formulations that resist generic substitution. Wacker Chemie AG specializes in silicone-based additives for breathable plaster systems.
Dry-mix mortar additives comprise organic and inorganic compounds including cellulose ethers, redispersible polymer powders, and specialty surfactants that modify rheology, setting time, and adhesion in cementitious pre-blended mixtures. These chemicals enable consistent performance in factory-controlled formulations that outperform site-mixed alternatives for bonding strength and workability. Plasticizers and retarders dominate volume as infrastructure-grade mortar requires extended open times and flow control in hot-climate pouring. Tile adhesives and grouts represent the fastest-growing application channel as large-format tile installation spreads across residential and commercial finishes.
REACH registration in Europe and China's MEE emission standards constrain volatile organic compound content in additive formulations, forcing reformulation investments that favor established suppliers with regulatory compliance infrastructure. The US EPA and OSHA jointly govern silica exposure limits in dry-mix handling, shaping packaging and jobsite delivery protocols. Stakeholders must monitor tightening carbon-border adjustments and embodied-carbon disclosure rules that will resegment supplier competitiveness across export markets.
Market Dynamics
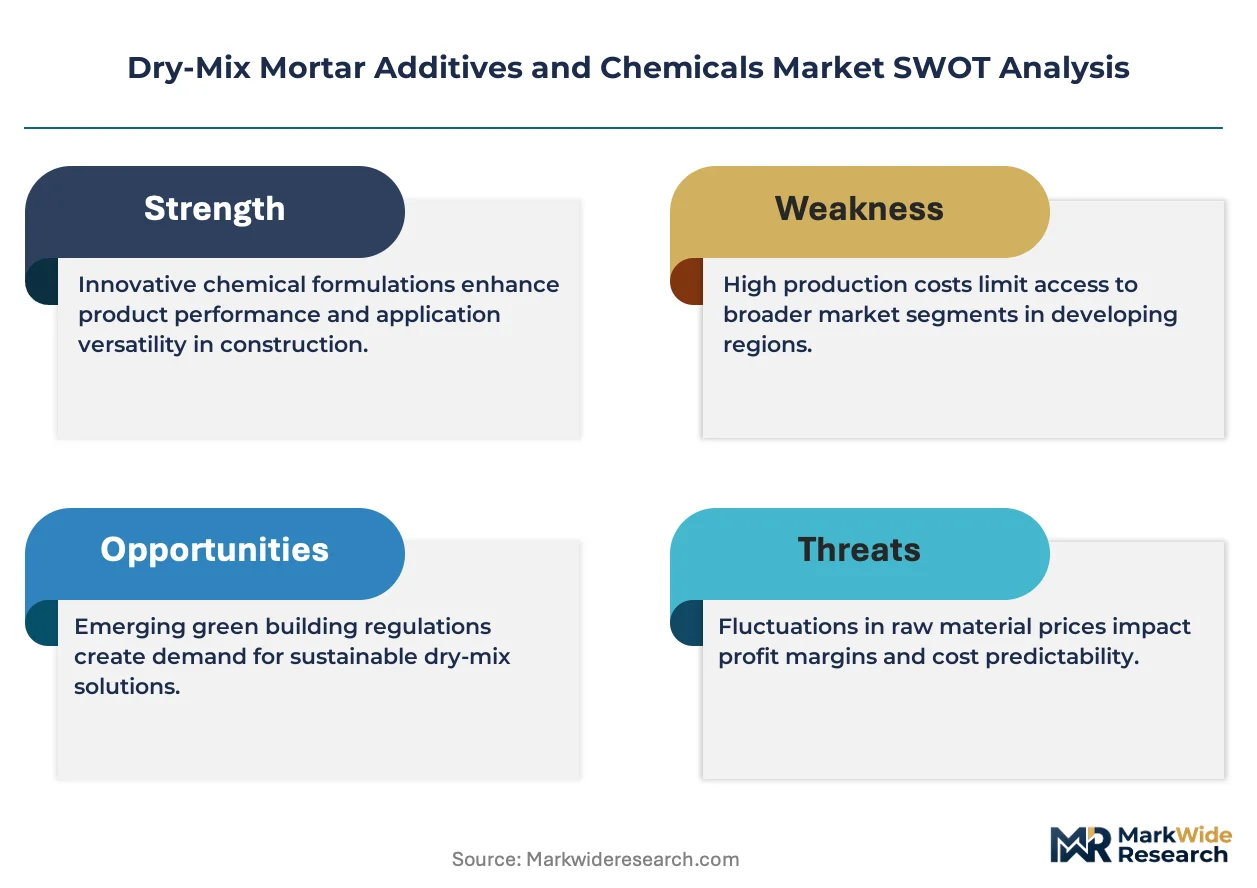
Formulation chemistry is bifurcating between performance-grade additives for large-format tile installation and commodity-grade chemicals for volume infrastructure, with regulatory compliance infrastructure becoming the decisive competitive moat.
Growth Catalysts
- Large-format tile specification:Architects in commercial and luxury residential projects mandate polymer-modified adhesives capable of bonding tiles exceeding 1.2 meters in dimension, pulling demand for redispersible polymer powders with enhanced deformability.
- REACH compliance infrastructure:European contractors now require full substance registration documentation for cellulose ethers and specialty surfactants, locking in suppliers with established ECHA dossiers and screening out opportunistic entrants.
- India's infrastructure acceleration:The National Infrastructure Pipeline drives cement consumption for highways and urban transit, expanding the addressable base for retarders and plasticizers in hot-climate pouring conditions.
Market Restraints
- Petrochemical feedstock volatility:Vinyl acetate monomer and ethylene derivatives, core inputs for redispersible polymer powders, expose formulators to margin compression when naphtha cracks widen.
- Specialty surfactant supply concentration:China dominates alkyl polyglucoside and ether sulfate production, creating single-source vulnerability for European and North American additive blenders.
- Cement substitution by precast:Modular construction methods reduce on-site mortar consumption by 15-30% in multi-family residential, directly compressing additive volume in affected geographies.
Strategic Opportunities
- Southeast Asia's specification upgrade:Vietnam and Indonesia are transitioning from site-mixed to pre-blended mortars for high-rise construction, opening premium additive penetration in markets previously served by commodity chemistry.
- China's dual carbon mandate:The MEE's emission intensity targets for chemical manufacturing create first-mover advantage for additive producers with low-carbon cellulose ether production and bio-based plasticizer portfolios.
- Digital specification platforms:Building information modeling integration allows additive suppliers to embed performance data directly into architect workflows, bypassing traditional distributor influence.
Industry Challenges
- Rheology modeling expertise scarcity:Formulation chemists capable of balancing open time, sag resistance, and bond strength across variable cement qualities command premium compensation and limited availability.
- Multi-jurisdiction registration timelines:Simultaneous ECHA, EPA, and NMPA substance notifications for novel additives extend commercialization cycles to 4-7 years, straining R&D amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry-Mix Mortar Additives and Chemicals Market |
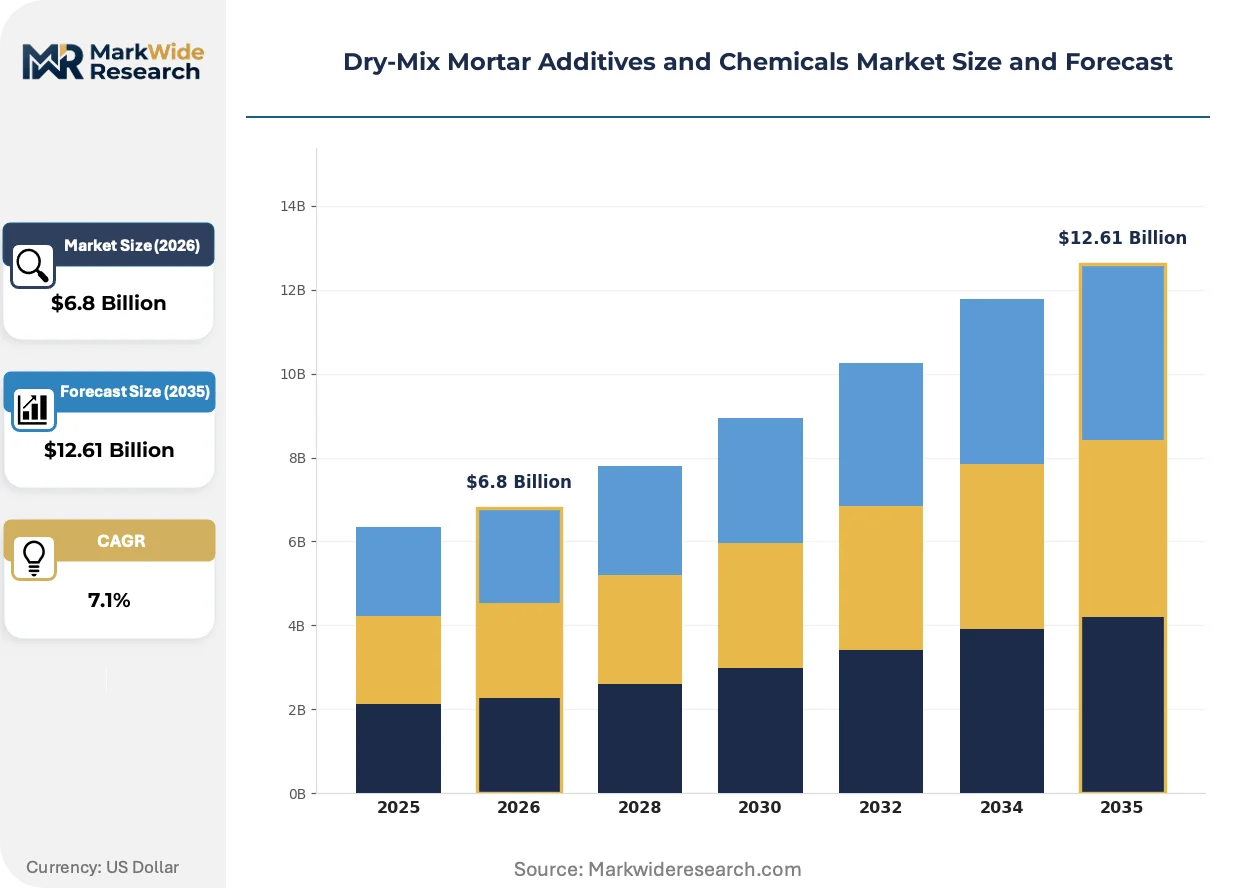
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Retarders, Accelerators, Antifungal Agents Application: Mortar, Plaster, Tile Adhesives, Grouts End User: Construction Companies, DIY Enthusiasts, Engineers, Contractors Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | BASF SE, Sika AG, Wacker Chemie AG, Dow, Saint-Gobain, LafargeHolcim, MAPEI S.p.A., Evonik Industries AG, MBCC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry-Mix Mortar Additives and Chemicals Market Shifts & Advancements
Digital tools are compressing the specification-to-procurement cycle while bio-based chemistry and modular formulation systems reshape how additive value is captured and delivered.
Pre-dosed additive packets for small-batch mortar mixing is modularizing the supply relationship between formulators and mid-sized contractors. Regional blending plants in Poland and Mexico now assemble custom additive kits from standardized base chemicals, reducing working capital requirements for distributors. This architecture enables rapid regional customization without full formulation redevelopment.
REACH's restriction of microplastic-containing additives forces reformulation of certain rheology modifiers by 2027. German and French mortar producers are accelerating qualification of cellulose-based alternatives ahead of enforcement deadlines. The tile adhesive segment faces the steepest substitution curve due to its reliance on polymer microspheres for sag resistance.
Direct procurement from additive manufacturers is displacing layered distribution in major metropolitan construction markets. Tier-one contractors in São Paulo and Mumbai now negotiate annual supply agreements for cellulose ethers and redispersible powders, extracting volume discounts previously captured by regional distributors. This concentration of buying power is most visible in commercial flooring and facade installation contracts exceeding $2 million in material value.
Dry-Mix Mortar Additives and Chemicals Market Segmentation
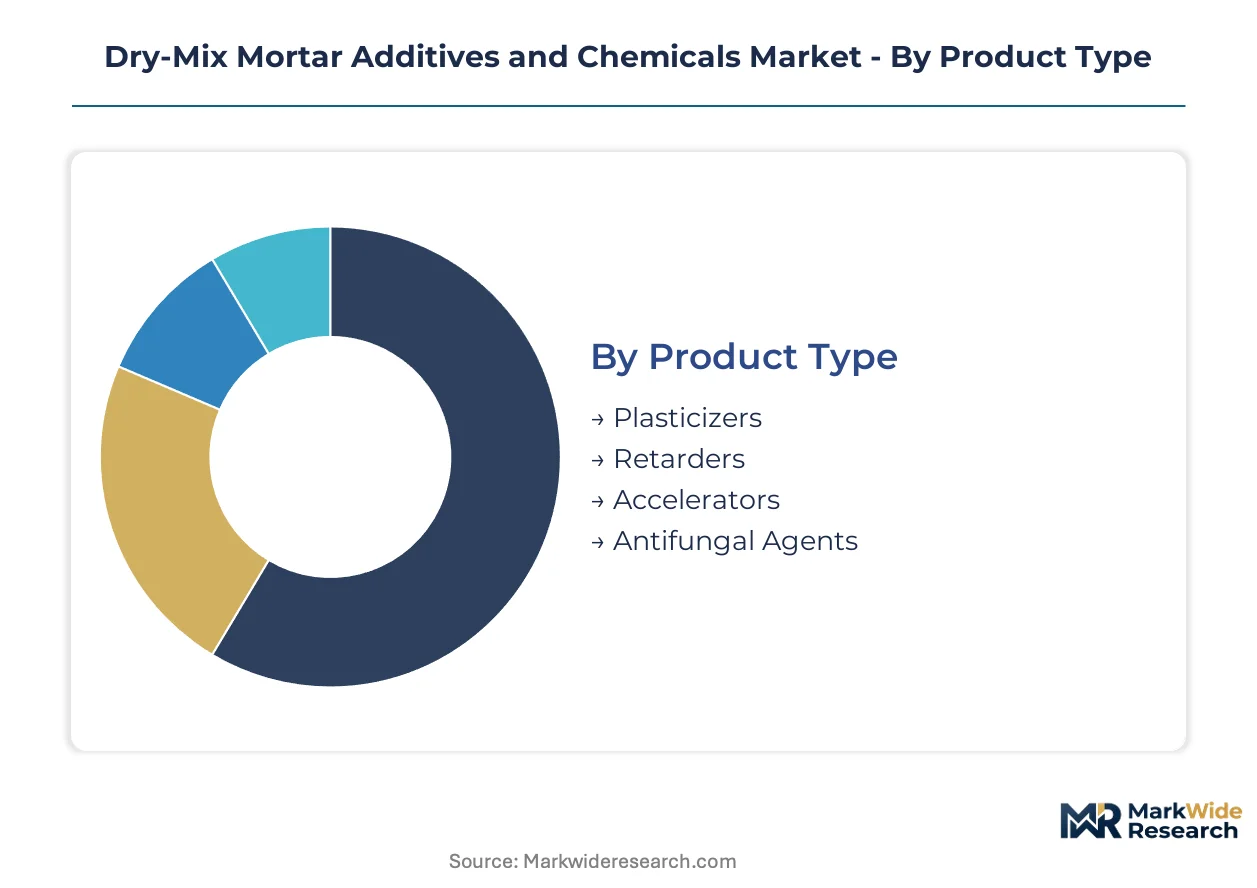
Dry-mix mortar additives segment across four functional dimensions that determine formulation complexity, margin structure, and channel strategy. Product chemistry defines performance tiers while application specificity dictates regulatory exposure and technical support requirements.
Product Type:
Customization intensity varies sharply across this category, with commodity plasticizers at one pole and specification-driven antifungal agents at the other.
- Plasticizers:Sulfonated melamine and polycarboxylate ether chemistries dominate volume for flow retention in hot-climate pouring. Demand concentrates in India's National Infrastructure Pipeline highway contracts where extended open times reduce waste in batch mixing.
- Retarders:Tartaric acid and citrate-based formulations delay cement hydration for large-surface finishing. Commercial flooring contractors in São Paulo specify these for polished concrete installations exceeding 1,000 square meters.
- Accelerators:Calcium chloride and non-chloride alternatives speed set times for cold-weather repair work.
- Antifungal Agents:Isothiazolinone and benzalkonium chloride biocides prevent efflorescence in humid climates.
Leading the category by volume: Plasticizers. Growing fastest: Antifungal Agents.
Application:
Application segments diverge by specification stringency, with facade-grade plaster demanding certified deformability while volume mortar tolerates broader performance bands.
- Mortar:Bonding and rendering mixtures consume the largest additive volumes for masonry jointing and surface leveling. Infrastructure-grade projects in Vietnam drive retarder demand for continuous pouring in tropical conditions.
- Tile Adhesives:Polymer-modified thin-set and large-format formulations require redispersible powders with enhanced slip resistance. Luxury residential towers in Mumbai specify these for tiles exceeding 1.2 meters.
- Plaster:Skim-coat and base-coat systems demand cellulose ethers for workability and water retention.
- Grouts:Cementitious and epoxy-based joint fillers complete installation systems for commercial flooring.
Tile Adhesives command premium pricing per kilogram. Mortar dominates absolute tonnage.
End User:
End-user segments separate by technical sophistication, with engineers specifying performance certificates and contractors optimizing for unit economics.
- Construction Companies:Tier-one builders negotiate direct additive procurement for projects exceeding $2 million material value, bypassing distributor margins in São Paulo and Mumbai metropolitan markets.
- Contractors:Mid-sized installation specialists drive pre-dosed additive packet adoption for small-batch flexibility.
- Engineers:Specification authority in commercial and institutional projects mandates certified rheology data.
- DIY Enthusiasts:Retail-packaged small-format additives serve renovation and repair segments through specialty stores.
Construction Companies concentrate procurement volume. Contractors represent the fastest-expanding specification influence.
Distribution Channel:
Channel structure reflects buyer scale and technical support requirements, with direct sales capturing complex formulations and online retail penetrating standardized products.
- Wholesale Distributors:Regional blending plants in Poland and Mexico assemble custom additive kits from standardized base chemicals, enabling rapid customization without full formulation redevelopment.
- Direct Sales:Annual supply agreements between additive manufacturers and tier-one contractors extract volume discounts previously captured by intermediaries.
- Online Retail:Digital platforms serve DIY segments and small contractors with pre-packaged cellulose ethers and redispersible powders.
- Specialty Stores:Technical consultation and immediate availability support professional installers in urban construction markets.
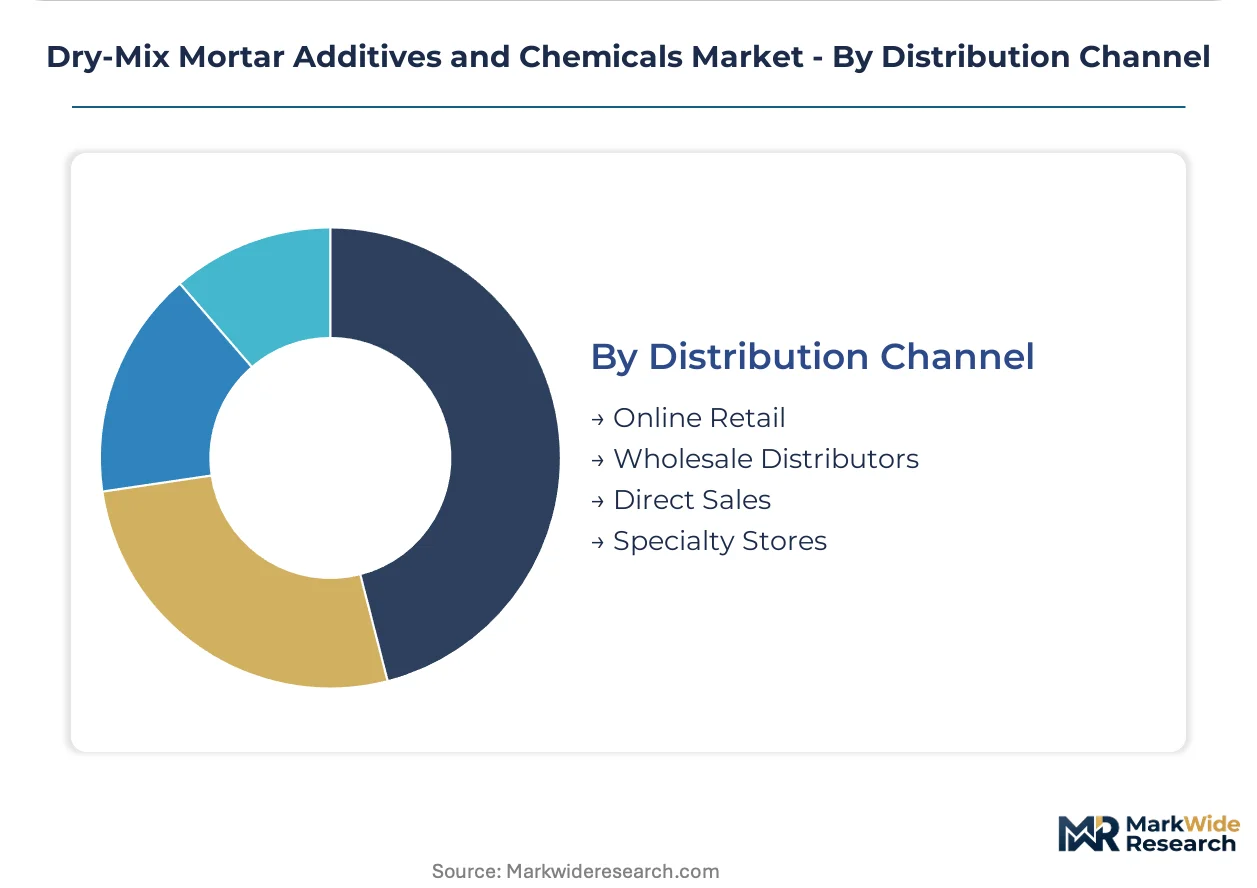
Wholesale Distributors retain the largest volume share. Direct Sales is climbing the fastest as procurement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors additive procurement concentration as tier-one contractors negotiate direct annual supply agreements for large-scale commercial flooring and facade installation projects exceeding two million dollars in material value.
China
The Yangtze River Delta drives cellulose ether consumption for breathable plaster systems in high-rise residential towers. MEE emission intensity targets for chemical manufacturing favor producers with low-carbon production infrastructure. Shanghai-based formulators accelerate qualification of bio-based plasticizers ahead of dual carbon enforcement deadlines.
Germany
Industrial flooring contractors in the Rhine-Ruhr corridor specify certified deformability data for polymer-modified tile adhesives. ECHA dossier requirements for cellulose ethers and specialty surfactants lock in established suppliers. Bavarian mortar plants assemble custom additive kits from standardized base chemicals for rapid regional customization.
India
The National Infrastructure Pipeline expands retarder and plasticizer volumes for highway and urban transit cement consumption in tropical pouring conditions. BIS certification requirements tighten formulation documentation for imported specialty surfactants. Gujarat's regional blending facilities serve mid-sized contractors with pre-dosed additive packets for small-batch flexibility.
United States
Commercial developers in Texas and Florida specify waterproofing-grade formulations for large-format tile installations in humid climates. EPA and OSHA joint silica exposure limits shape packaging protocols for dry-mix handling. Southeast metropolitan markets witness direct procurement concentration as tier-one contractors bypass traditional distributor channels.
Brazil
São Paulo's metropolitan construction market concentrates annual supply agreement negotiations between additive manufacturers and tier-one contractors. ANVISA biocide registration timelines extend commercialization cycles for novel antifungal agents. Regional distributors in the Southeast industrial corridor modularize supply relationships through pre-dosed additive packet systems.
Dry-Mix Mortar Additives and Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance infrastructure. The market structure bifurcates between performance-grade specialists commanding specification authority and volume-grade suppliers competing on unit economics. Three archetypes dominate: integrated chemical conglomerates with polymer dispersion portfolios, construction-material specialists with waterproofing expertise, and regional blenders with modular kit assembly capabilities. Competitive moves concentrate on backward integration into cellulose ether production and geographic expansion through regional blending plant networks.
Among German chemical conglomerates, BASF SE and Wacker Chemie AG exemplify the integrated archetype with captive supply of core polymer inputs. Sika AG anchors the construction-specialist tier with Swiss-originated expertise in waterproofing-grade formulations. These three occupy positions where regulatory compliance infrastructure and formulation chemistry capabilities create defendable margin structures against commodity substitution.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Wacker Chemie AG |
| Dow |
| Saint-Gobain |
| LafargeHolcim |
| MAPEI S.p.A. |
| Evonik Industries AG |
| MBCC Group |
| Others |
Supply & Pricing Matrix
Captive supply of vinyl acetate monomer and ethylene derivatives anchors both cost position and pricing power for redispersible polymer powder producers. BASF SE and Wacker Chemie AG leverage backward integration into these petrochemical inputs to buffer margin compression when naphtha cracks widen, while non-integrated blenders absorb volatility or sacrifice share.
Pricing Analysis
Outcome-based pricing tied to certified tile bond strength anchors premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered cellulose ethers from commodity-grade plasticizers. Cost compression in commodity retarders is intensifying because cement substitution by precast methods shrinks volume demand. Mid-sized contractors show highest price sensitivity, while tier-one construction companies prioritize specification compliance over unit cost.
Supply Chain Analysis
Empty additive packaging and spent solvent drums flow through licensed waste handlers under MEE and EPA hazardous material protocols. China, Germany, and India concentrate cellulose ether production capacity. Formulation chemistry draws from alkyl polyglucoside surfactants and tartaric acid retarders. Single-source vulnerability runs through Chinese ether sulfate supply. Distribution runs through regional blending plants that assemble custom kits for mid-sized contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. REACH dossier requirements for cellulose ethers and specialty surfactants erect a barrier-to-entry moat that rewards established European suppliers with ECHA infrastructure.
For Market Incumbents: Acquire regional blending plant networks to capture distributor margin and enable rapid customization. BASF SE and Sika AG should deepen captive supply of redispersible polymer powders to defend against vinyl acetate monomer volatility. Cement substitution by precast construction threatens volume-grade additive demand; incumbents must shift capacity toward specification-grade tile adhesive formulations. For New Entrants and Emerging Players: China's MEE emission intensity targets open a window for low-carbon cellulose ether producers with bio-based plasticizer portfolios. Southeast Asia's specification upgrade from site-mixed to pre-blended mortars offers the most penetrable geography. New entrants should embed performance data directly into architect BIM workflows to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in construction-specialist firms with waterproofing-grade formulation expertise and established regulatory compliance infrastructure. Long-term viability favors additive producers with backward integration into polymer dispersion chemistry and multi-jurisdiction registration capabilities. Investors should monitor carbon-border adjustment implementation timelines as an inflection indicator for supplier competitiveness resegmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Ether Production | Captive supply of core rheology modifiers buffers margin compression from petrochemical volatility. |
| Regional Blending Plant Network Expansion | Poland and Mexico facilities enable rapid customization without full formulation redevelopment cycles. |
| REACH-Compliant Bio-Based Plasticizer Qualification | German and French mortar producers accelerate substitution ahead of microplastic restriction deadlines. |
| BIM-Integrated Performance Data Embedding | Direct architect workflow penetration bypasses traditional distributor influence in specification decisions. |
| Long-Term Supply Agreement Concentration | São Paulo and Mumbai tier-one contractors extract volume discounts previously captured by intermediaries. |
Research Methodology
Trade databases, ECHA registration dossiers, and customs records formed the secondary backbone for supply-side mapping. Primary interviews with formulation chemists, procurement leads at tier-one contractors, distribution channel partners, and technical R&D directors at additive manufacturers validated demand patterns. Bottom-up segmentation modeling triangulated against top-down chemical consumption estimates from national infrastructure pipeline disclosures.
Historical trendline analysis of cellulose ether and redispersible polymer powder consumption established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including functional additive type, application specificity, end-user procurement scale, and regional regulatory cluster. CAGRs derived from cement consumption forecasts, infrastructure spending pipelines, and specification upgrade penetration curves in emerging markets.
Caveats apply where petrochemical feedstock volatility, carbon-border adjustment implementation, or cement substitution acceleration by precast methods could materially shift the outlook. Practitioners should monitor naphtha crack spreads, MEE enforcement intensity, and modular construction adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plasticizers Market
Additives
Global Chelated Trace Minerals Market
Additives
Citrate Ester Market
Additives
Trioctyldodecyl Citrate Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Automotive Coolant Additives Market
Additives
High Performing Matting Agents Market
Additives
Phthalate Plasticizer Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Powder Induction and Dispersion Systems Market
Additives
South Africa Acidulants Market
Additives
Asia Pacific Silage Additives Market
Additives
Magnesium Stearate Market
Additives
Caustic Sulphite Caramel Market
Additives
Middle East Lubricant Additives Market
Additives
Inorganic Rheology Modifiers Market