
 Calcium Acetate Market | 2026-2036
Calcium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Acetate Market Analysis
Aftermarket technical service revenue is narrowing as a margin pool toward formulation partners and compounding specialists. Merck KGaA leverages its pharmaceutical-grade chemical portfolio to anchor high-purity supply contracts for dialysis applications. Solvay competes through backward integration into acetic acid sourcing, which sustains cost discipline across European manufacturing. Niacet specializes in food-grade and pharmaceutical-grade calcium salts, positioning its product lines for dual-use regulatory compliance.
Calcium acetate is the calcium salt of acetic acid, typically manufactured through the neutralization of calcium carbonate or calcium hydroxide with acetic acid, yielding a white crystalline solid with the formula Ca(C₂H₃O₂)₂ and primary application as a phosphate binder in renal care and as a food stabilizer. The pharmaceutical intermediary segment dominates value capture due to stringent USP and EP certification requirements that filter out commodity producers. Tablet and capsule formulations represent the fastest-growing product type category as dialysis clinics and hospital systems standardize on unit-dose compliance packaging. Powder grades retain volume leadership in food additive applications where bulk blending into bakery and condiment formulations remains prevalent.
The US FDA enforces Current Good Manufacturing Practice standards and USP monograph compliance for calcium acetate active pharmaceutical ingredients, while the European Medicines Agency applies ICH Q3D elemental impurity guidelines that elevate testing costs for non-EU suppliers. China's National Medical Products Administration has tightened registration pathways for imported drug excipients, creating divergent market access conditions across major pharmaceutical consumption zones. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards to anticipate qualification burden shifts.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing the supplier base as dialysis clinics and hospital systems consolidate procurement around USP and EP-compliant manufacturers. This quality-tier bifurcation is redistributing margin pools toward high-purity producers while marginalizing commodity-grade suppliers.
Growth Catalysts
- Chronic kidney disease prevalence:Rising dialysis patient populations in the United States are expanding phosphate binder prescriptions. Hospital systems are standardizing calcium acetate formularies.
- REACH compliance evolution:ECHA substance registration requirements are elevating documentation standards for European pharmaceutical excipient suppliers. This regulatory tightening favors established manufacturers with dedicated compliance infrastructure.
- Acetic acid supply security:Backward integration into acetic acid feedstock is reducing cost volatility for integrated calcium acetate producers. Captive supply chains insulate margins from petrochemical price swings.
Market Restraints
- Calcium carbonate input volatility:Mining-grade limestone and precipitated calcium carbonate prices fluctuate with construction sector demand cycles. This input cost instability compresses margins for non-integrated producers.
- Sevelamer substitution threat:Polymeric phosphate binders are capturing share in premium dialysis segments where hypercalcemia risk is elevated. Sevelamer hydrochloride and carbonate formulations are displacing calcium-based binders in certain clinical protocols.
- ICH Q3D testing burden:Elemental impurity guideline compliance adds analytical cost layers for suppliers serving European and US markets. Non-EU manufacturers face disproportionate qualification expenses.
Strategic Opportunities
- Food-grade dual-use positioning:Bakery and condiment manufacturers are expanding calcium acetate procurement for pH control and mold inhibition. Dual-certification infrastructure spreads fixed compliance costs across pharmaceutical and food additive revenue streams.
- Unit-dose packaging standardization:Dialysis clinics are migrating toward blister-packed tablet formats to reduce medication errors. Packaging line investments by formulation partners create partnership opportunities for API suppliers.
- India CDSCO pathway expansion:India's pharmaceutical regulator is streamlining drug excipient registration for imported active ingredients. Early entrants can establish preferred supplier status with domestic generic formulation houses.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and elemental impurity testing expertise is concentrated among specialized contract laboratories. Manufacturers face recruitment competition from broader pharmaceutical testing services.
- USP-NF monograph update lag:Revision cycles for calcium acetate specification documents create timing uncertainty for qualification planning. Suppliers must maintain dual-version compliance during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Acetate Market |
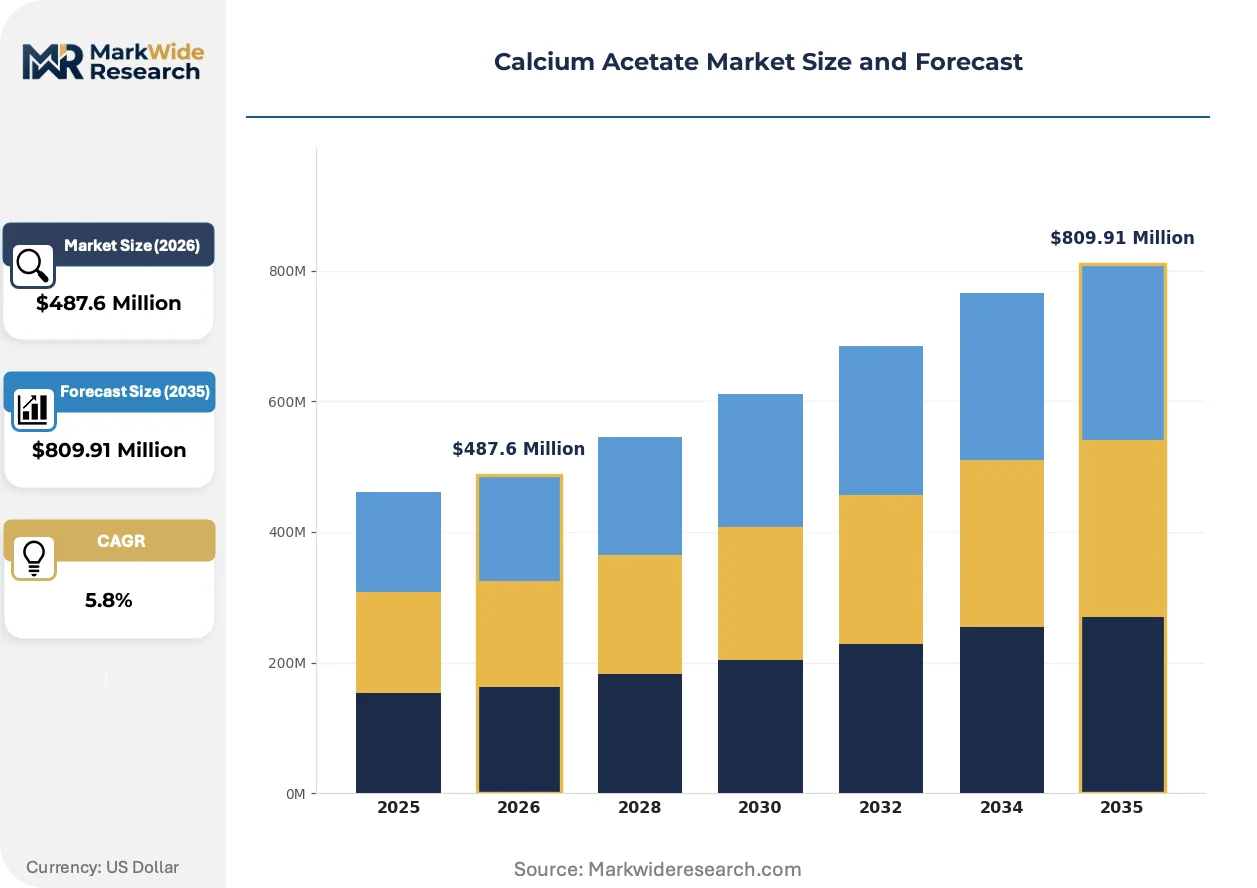
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Food Additive, Pharmaceutical Intermediary, De-icing Agent, Fertilizer Component End User: Healthcare, Agriculture, Food Industry, Construction Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Dr. Paul Lohmann GmbH & Co. KGAA, Merck KGaA, Solvay, Macco Organiques, Niacet, Avantor Performance Materials, Jiangsu Kolod Food Ingredients, Alfa Aesar, Tengzhou Aolong Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Acetate Market Emerging Trajectories
Continuous manufacturing technologies are disrupting batch-process economics in pharmaceutical-grade chemical production. Regulatory acceptance of process analytical technology is accelerating validation pathways for real-time quality control systems.
Direct compression-grade calcium acetate excipients are rendering obsolete traditional wet granulation workflows in tablet manufacturing. Dialysis-focused contract manufacturers are adopting these pre-processed grades to reduce production cycle times. The shift is compressing capital requirements for formulation partners while elevating specification demands on API suppliers.
EMA's evolving ICH Q3D implementation guidance is tightening elemental impurity surveillance across European pharmaceutical supply chains. Manufacturers must demonstrate comprehensive risk assessments for calcium sources and acetic acid feedstocks. High-purity calcium acetate producers with documented supply chain controls are capturing disproportionate share of EU dialysis binder contracts.
Hospital purchasing consortiums are consolidating calcium acetate procurement through centralized formulary committees. Group purchasing organizations are displacing direct manufacturer relationships for mid-size dialysis clinic chains. The United States exhibits the most pronounced concentration, where three national GPOs control the majority of institutional phosphate binder purchasing decisions.
Calcium Acetate Market Segmentation
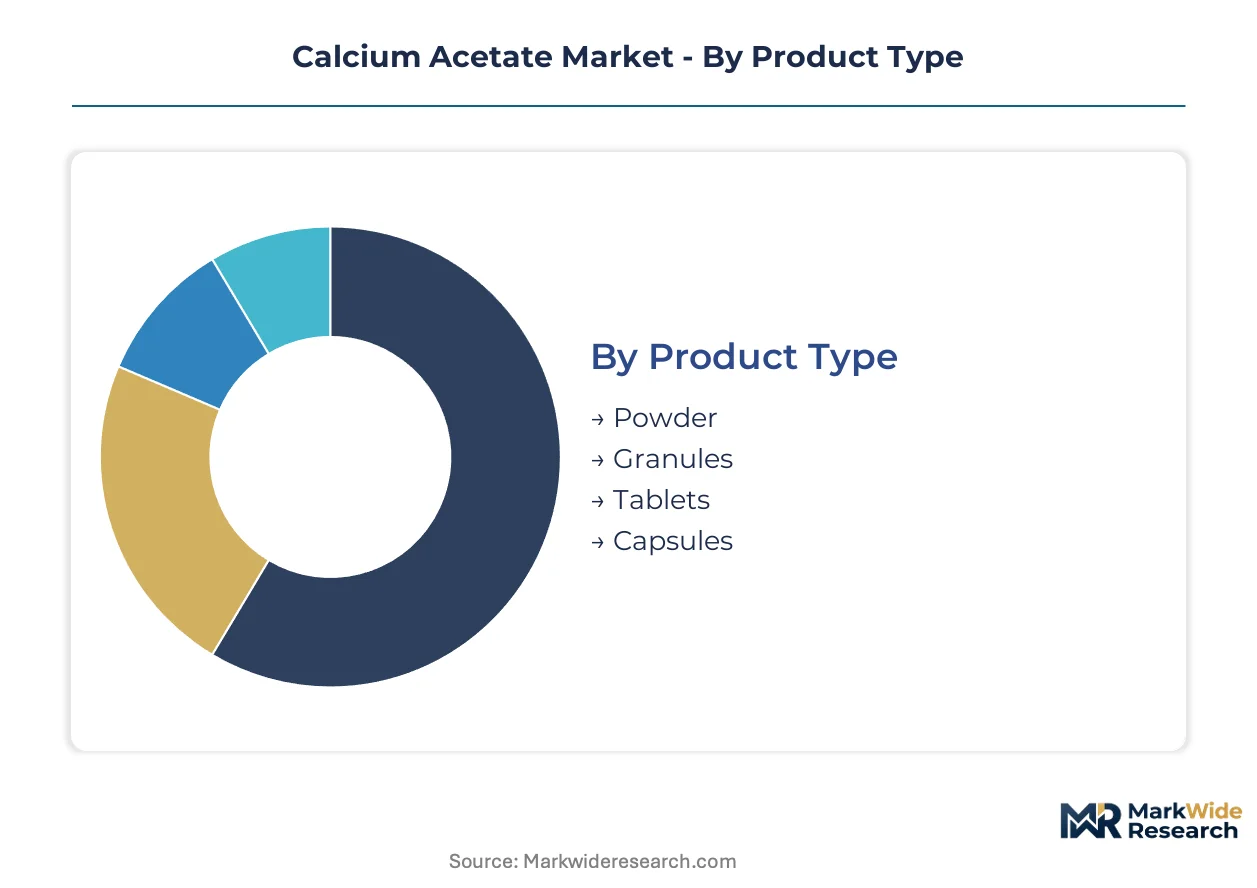
Calcium acetate's dual regulatory footprint across pharmaceutical and food additive domains creates distinct specification tiers that reshape procurement patterns. Manufacturers must navigate divergent purity requirements, packaging standards, and documentation burdens across each segment boundary.
Product Type:
Physical form dictates processing compatibility, shelf stability, and dosing precision across end-use environments.
- Tablets:Direct-compression grades with USP monograph compliance dominate dialysis clinic formularies. Unit-dose blister packaging demand from United States hospital systems is compressing production cycle times for pre-processed excipient suppliers.
- Powder:Fine crystalline grades with specified particle size distributions serve bulk pharmaceutical compounding and food additive blending. Bakery and condiment manufacturers in North America specify powder grades for pH control and mold inhibition applications.
- Granules:Intermediate particle size for controlled-release formulations and industrial buffer applications.
- Capsules:Encapsulation-grade material with enhanced flow properties for high-speed filling operations.
Tablets hold installed capacity. Capsules are rotating up the share rankings.
Application:
Functional use determines regulatory pathway, testing burden, and margin structure for calcium acetate suppliers.
- Pharmaceutical Intermediary:USP and EP certification requirements filter out commodity producers. FDA Current Good Manufacturing Practice enforcement and EMA ICH Q3D elemental impurity guidelines elevate analytical costs for dialysis binder applications.
- Food Additive:pH control and preservative functions in bakery, condiment, and beverage formulations. Dual-certification infrastructure spreads fixed compliance costs across pharmaceutical and food revenue streams.
- De-icing Agent:Low-purity grades for airport runway and municipal road applications.
- Fertilizer Component:Calcium enrichment and soil pH amendment in agricultural formulations.
Pharmaceutical Intermediary commands premium positioning. Food Additive is climbing the fastest as clean-label preservation demand expands.
End User:
Customer category shapes volume scale, contract structure, and technical service intensity.
- Healthcare:Dialysis clinic chains and hospital systems drive phosphate binder procurement. United States chronic kidney disease prevalence concentrates demand among three national group purchasing organizations.
- Food Industry:Bakery, condiment, and processed food manufacturers specify calcium acetate for pH control. REACH compliance documentation requirements favor established European suppliers with dedicated regulatory infrastructure.
- Agriculture:Fertilizer blenders and soil amendment distributors.
- Construction:Concrete admixture and industrial chemical applications.
Healthcare holds installed capacity. Food Industry is rotating up the share rankings.
Distribution Channel:
Channel selection reflects order scale, geographic reach, and technical support requirements.
- Direct Sales:Multi-year supply contracts with pharmaceutical manufacturers and dialysis clinic chains. Backward integration into acetic acid feedstock enables integrated producers to sustain cost discipline for high-volume healthcare accounts.
- Distributors:Regional chemical distributors serve mid-size food additive and agricultural customers. Inventory pooling reduces working capital burdens for non-integrated calcium acetate producers.
- Online Retail:E-commerce platforms for laboratory-scale and specialty chemical procurement.
- Wholesalers:Bulk commodity trading for industrial-grade applications.
Direct Sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dialysis clinic procurement in the United States shows the lowest price elasticity, while food additive buyers in emerging markets exhibit acute sensitivity to input cost swings. European pharmaceutical manufacturers absorb regulatory compliance premiums with limited volume response. Asian industrial consumers shift rapidly between calcium acetate and alternative pH control agents based on spot pricing.
United States
Chronic kidney disease prevalence drives phosphate binder consumption through three dominant group purchasing organizations. FDA Current Good Manufacturing Practice enforcement and USP monograph compliance elevate supplier qualification barriers. The Cleveland Clinic dialysis network and Fresenius Medical Care facilities in the Midwest concentrate procurement volume for high-purity tablet grades.
Germany
REACH registration requirements and ECHA documentation standards filter commodity producers from pharmaceutical excipient supply. EMA ICH Q3D elemental impurity guidelines impose analytical cost burdens on non-EU manufacturers seeking market access. The Rhine-Ruhr industrial corridor hosts backward-integrated acetic acid producers supplying certified calcium acetate to European dialysis formulation houses.
China
NMPA registration pathway tightening for imported drug excipients creates divergent access conditions for foreign suppliers. Domestic food additive manufacturers in Shandong Province expand calcium acetate blending capacity for bakery and condiment exports. The Yangtze River Delta pharmaceutical cluster concentrates domestic phosphate binder formulation capacity serving hospital systems.
India
CDSCO streamlining of drug excipient registration creates early-mover advantages for API suppliers establishing preferred relationships with domestic generic houses. FSSAI food additive standards govern calcium acetate use in processed food manufacturing. Gujarat's specialty chemical belt hosts expanding pharmaceutical-grade calcium salt production targeting export markets.
Japan
PMDA pharmaceutical-grade chemical oversight maintains stringent purity specifications for dialysis applications. METI industrial policy supports domestic acetic acid supply security for chemical manufacturers. The Kansai region's Osaka-based pharmaceutical formulation cluster sustains consistent demand for EP-compliant calcium acetate intermediaries.
Calcium Acetate Market Vendor Landscape
Capability concentration sits with integrated pharmaceutical-grade specialists; scale advantage sits with diversified chemical conglomerates. The supplier base compresses around USP and EP certification holders as dialysis clinic procurement consolidates. Three archetypes dominate: backward-integrated acetic acid producers, dual-certification pharmaceutical-food specialists, and regional commodity chemical fabricators. Competitive moves center on captive feedstock security and multi-jurisdiction pharmacopeial qualification.
Within the premium certification tier, Dr. Paul Lohmann GmbH & Co. KGAA and Merck KGaA exemplify European pharmaceutical-grade chemical positioning. Solvay occupies a position bridging industrial scale and healthcare compliance. Niacet represents dual-use regulatory infrastructure spanning food additive and pharmaceutical applications. Jiangsu Kolod Food Ingredients anchors Chinese domestic supply for processed food manufacturing. Tengzhou Aolong Chemical sits within the regional industrial chemical fabricator archetype serving non-pharmaceutical applications.
| Leading Market Players |
|---|
| Dr. Paul Lohmann GmbH & Co. KGAA |
| Merck KGaA |
| Solvay |
| Macco Organiques |
| Niacet |
| Avantor Performance Materials |
| Jiangsu Kolod Food Ingredients |
| Alfa Aesar |
| Tengzhou Aolong Chemical |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr industrial corridor anchors European acetic acid supply security, and its captive production economics translate directly into pricing leverage for integrated calcium acetate manufacturers serving dialysis binder contracts.
Pricing Analysis
Aftermarket technical service revenue drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across USP-certified premium, EP-compliant standard, and food-grade economy levels segments buyers by purity requirement and documentation burden. Pricing pressure stems from sevelamer hydrochloride substitution in hypercalcemia-risk dialysis protocols. Hospital purchasing consortiums exhibit lowest price sensitivity, while food additive manufacturers in emerging markets absorb acute margin compression from calcium carbonate input volatility.
Supply Chain Analysis
Contract manufacturing concentration sits with Merck KGaA, Dr. Paul Lohmann, and Solvay for pharmaceutical-grade output. Germany, China, and India anchor global supply capacity, with each hub drawing from distinct limestone mining and petrochemical acetic acid feedstocks. Single-source vulnerability concentrates in acetic acid supply chains tethered to regional refinery operations. Distribution runs through direct sales for healthcare accounts and regional chemical distributors for food additive blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sevelamer polymeric binders threaten calcium acetate incumbents in premium dialysis segments, forcing substitution defense through certification deepening and clinical protocol anchoring.
For Market Incumbents: Pre-empt sevelamer displacement by locking multi-year formulary contracts with Fresenius and DaVita clinic networks. Deepen backward integration into acetic acid feedstock to insulate margins from petrochemical volatility. Prioritize USP-NF monograph update readiness to capture qualification timing advantages during specification transitions. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-streamlined excipient registration pathway before domestic generic houses consolidate preferred supplier rosters. Target food-grade dual-certification positioning to spread fixed compliance costs across pharmaceutical and bakery additive revenue streams. Lead with direct compression-grade excipient technical service to differentiate from commodity powder suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated pharmaceutical-grade specialists with documented ICH Q3D supply chain controls. Long-term viability hinges on pharmacopeial harmonization between USP, EP, and ChP standards. Acquisition focus should center on European manufacturers with REACH-registered infrastructure. Watch EMA elemental impurity guidance enforcement intensity as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive supply chains insulate Merck KGaA and Solvay from petrochemical price swings. |
| Dual-Certification Infrastructure Investment | Niacet spreads fixed compliance costs across pharmaceutical and food additive revenue streams. |
| Direct Compression-Grade Excipient Development | Pre-processed grades reduce production cycle times for dialysis-focused contract manufacturers. |
| India CDSCO Registration Pathway Entry | Early entrants secure preferred supplier status with Gujarat-based generic formulation houses. |
| Unit-Dose Packaging Line Partnership | Blister-packed tablet formats reduce medication errors in United States hospital systems. |
Methodological Framework
The analysis maps pharmaceutical intermediary, food additive, de-icing, and fertilizer sub-sectors, each validated through procurement directors at dialysis clinic chains, regulatory affairs leads at excipient manufacturers, and technical R&D directors at bakery formulation houses. Primary interview insights triangulate against FDA 483 inspection observations, EMA ICH Q3D implementation guidance, customs trade data for calcium acetate HS codes, and SEC filings from diversified chemical conglomerates. Bottom-up volume builds from end-use consumption patterns reconcile with top-down production capacity estimates across the analysis window.
Assumptions held fixed include REACH registration continuity, USP-NF monograph compliance timelines, and chronic kidney disease prevalence trajectories in the United States. Variables stress-tested encompass sevelamer substitution rates, acetic acid feedstock price bands, and ICH Q3D testing cost inflation. Segmentation dimensions modeled span product type, application, end user, and distribution channel, with regional regulatory cluster overlays. CAGRs derive from normalized historical consumption patterns projected through demand elasticity coefficients and input cost pass-through assumptions.
Stress conditions across sevelamer clinical protocol adoption, limestone mining capacity constraints, and EMA elemental impurity enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of dialysis clinic formulary shifts, CDSCO registration approval velocities, and acetic acid spot pricing spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Propyl Gallate Market
Additives
High Performing Matting Agents Market
Additives
Potting Mix Additives Market
Additives
Global UV Stabilizers Market
Additives
Maltitol Based on Corn Starch Market
Additives
Europe Citric Acid Market
Additives
Low Melt Inclusions Market
Additives
Water-Borne Coating Additives Market
Additives
Stabilizers Market
Additives
Global Silica-Based Matting Agents Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Epoxy Type Stabilizers Market
Additives
Triazine UV Absorber Market
Additives
Binder Excipients Market
Additives
Plasticizers Market
Additives
Engine Oil Additive Market