
 Low VOC Coating Additives Market | 2026-2036
Low VOC Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Low VOC Coating Additives Market Foresight
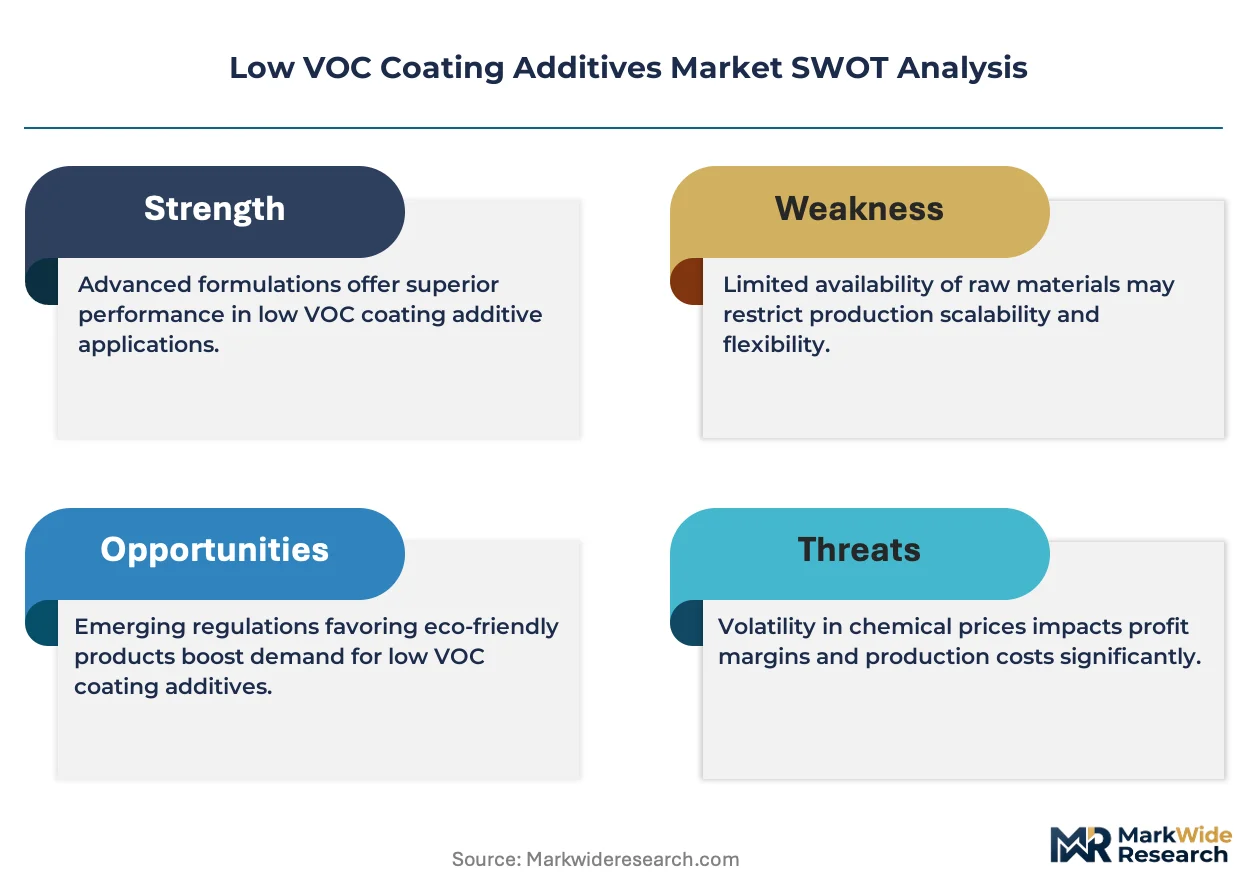
EPA Rule 40 CFR 59 is pivoting the cost-of-entry calculus for coating additive suppliers by mandating stricter volatile organic compound thresholds in architectural and industrial finishes. BASF SE leverages its integrated resins portfolio to sustain formulation leadership across water-based systems. BYK (ALTANA) anchors its position through specialized dispersant technology that navigates compliance without sacrificing film performance.
Low VOC coating additives are chemical modifiers—typically comprising surfactants, defoamers, rheology agents, and coalescing aids—that reduce volatile organic compound emissions in paint and coating systems to below regulatory thresholds, generally under 50 grams per liter for architectural applications. The primary industrial purpose centers on enabling film formation, flow control, and substrate adhesion in environmentally constrained formulations. Rheology modifiers within the additives type category command the deepest margin pools due to their technical specificity and reformulation complexity when switching from solvent-based to water-based systems. Automotive application demand is accelerating fastest as OEMs enforce supplier compliance with interior air quality protocols, while powder formulation growth remains tethered to industrial coating lines with captive curing infrastructure.
The EPA enforces VOC limits under 40 CFR 59 and 40 CFR 63, while the EU operates through REACH substance restrictions and the F-Gas Regulation on fluorinated compounds used in specialty coatings. China's MEE implements GB standards that progressively tighten VOC content in architectural coatings, compressing the reformulation timeline for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions where additive portfolios require region-specific validation rather than unified global registration.
Market Dynamics
Regulatory compression across the US, EU, and China is forcing simultaneous reformulation cycles, creating a structural bottleneck where additive suppliers must validate water-based chemistries against divergent compliance timelines rather than unified global standards.
Growth Catalysts
- EPA 40 CFR 59 thresholds:Architectural coating manufacturers face mandatory VOC ceilings that drive additive procurement for compliant film formation.
- Automotive interior air protocols:OEM supplier mandates accelerate demand for low-emission additives in cabin coatings and sealants.
- China's GB standard progression:Domestic architectural projects pursuing green building certification concentrate procurement of compliant water-based systems.
Market Restraints
- Petrochemical feedstock volatility:Bio-based surfactant precursors face price instability that compresses formulation margins.
- Rheology modifier supply concentration:Specialty acrylic and cellulosic thickener production clusters in Western Europe create geographic dependency.
- REACH substance restriction friction:ECHA's evolving SVHC list forces additive portfolios into costly re-registration cycles.
Strategic Opportunities
- India's PLI scheme for chemicals:Domestic manufacturing incentives create localized production capacity for Asia-Pacific coating supply chains.
- Powder coating additive development:Industrial lines with captive curing infrastructure seek low-temperature flow agents for heat-sensitive substrates.
- Digital formulation platforms:AI-driven additive selection tools compress R&D timelines for custom water-based systems.
Industry Challenges
- Colloid chemistry expertise scarcity:Formulation chemists skilled in solvent-to-water transition protocols command premium compensation.
- Regional certification fragmentation:Additive portfolios require separate validation for EPA, REACH, and GB standard compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low VOC Coating Additives Market |
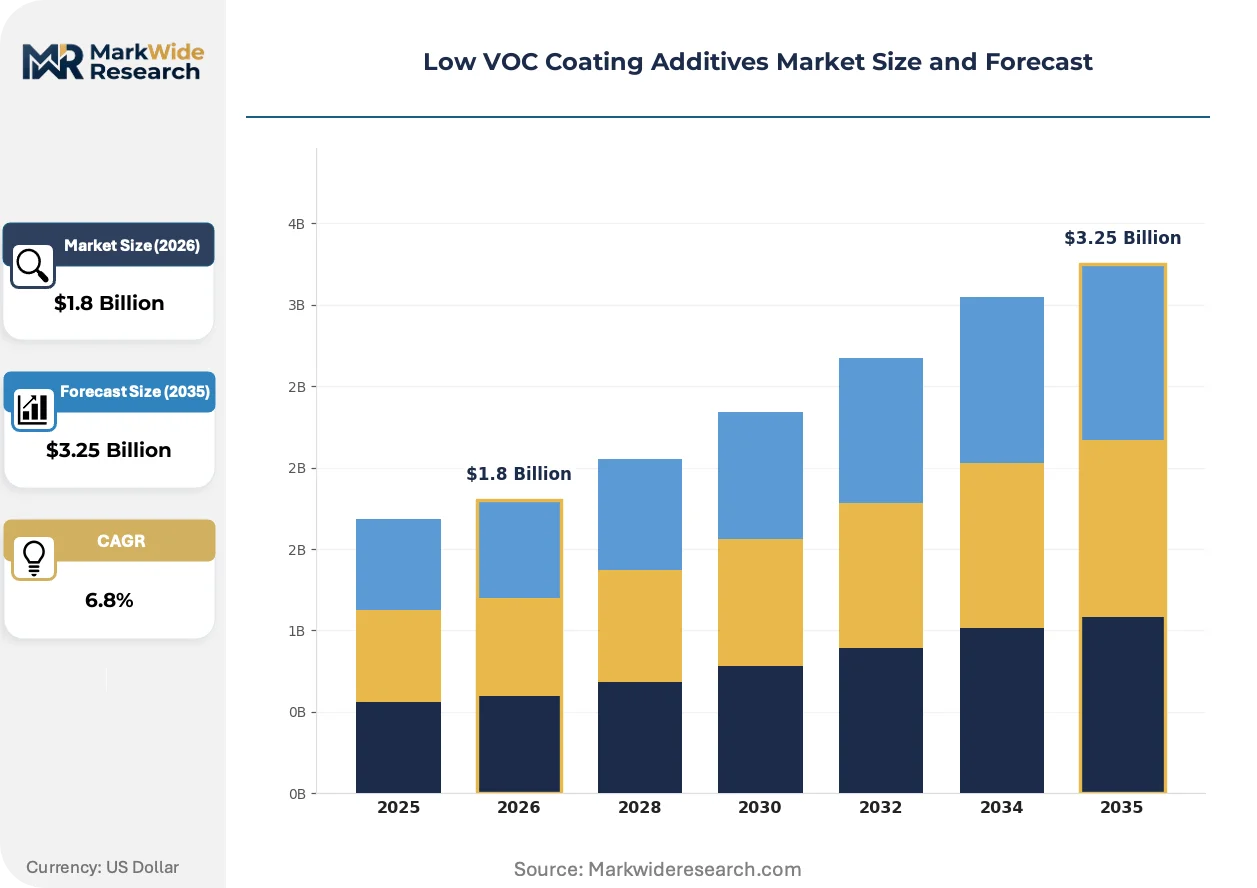
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Architectural, Industrial, Automotive, Consumer Goods Type: Additives, Resins, Colorants, Fillers End User: Manufacturers, Contractors, DIY Consumers, OEMs Formulation: Water-Based, Solvent-Based, Powder, Gel |
| Companies Covered | PPG Industries, BYK (ALTANA), BASF SE, Arkema Group, Lubrizol Corporation, Evonik Industries, Elementis plc, Eastman Chemical Company, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low VOC Coating Additives Market Shifts & Advancements
Active reformulation across automotive, architectural, and industrial coating verticals is compressing development cycles and elevating additive performance requirements beyond baseline compliance.
Hybrid dispersant technology is unifying pigment stabilization and substrate wetting functions into single-molecule architectures. Tier-one automotive coaters in Germany and Japan adopt these systems at pilot scale. This convergence is unifying previously separate additive categories, reducing formulation complexity while tightening supplier qualification barriers.
REACH substance restriction updates from ECHA are accelerating substitution timelines for fluorinated wetting agents. Coating manufacturers face reformulation deadlines that compress validation windows. Decorative and wood coating segments in Scandinavia and Benelux respond fastest due to early retailer sustainability mandates.
Specification-led buying now dominates large architectural projects where green building certification status determines additive selection. Distributor technical service teams displace traditional specification sales roles in North American and Western European markets. This shift concentrates influence with certification bodies and their approved product lists.
Low VOC Coating Additives Market Segmentation
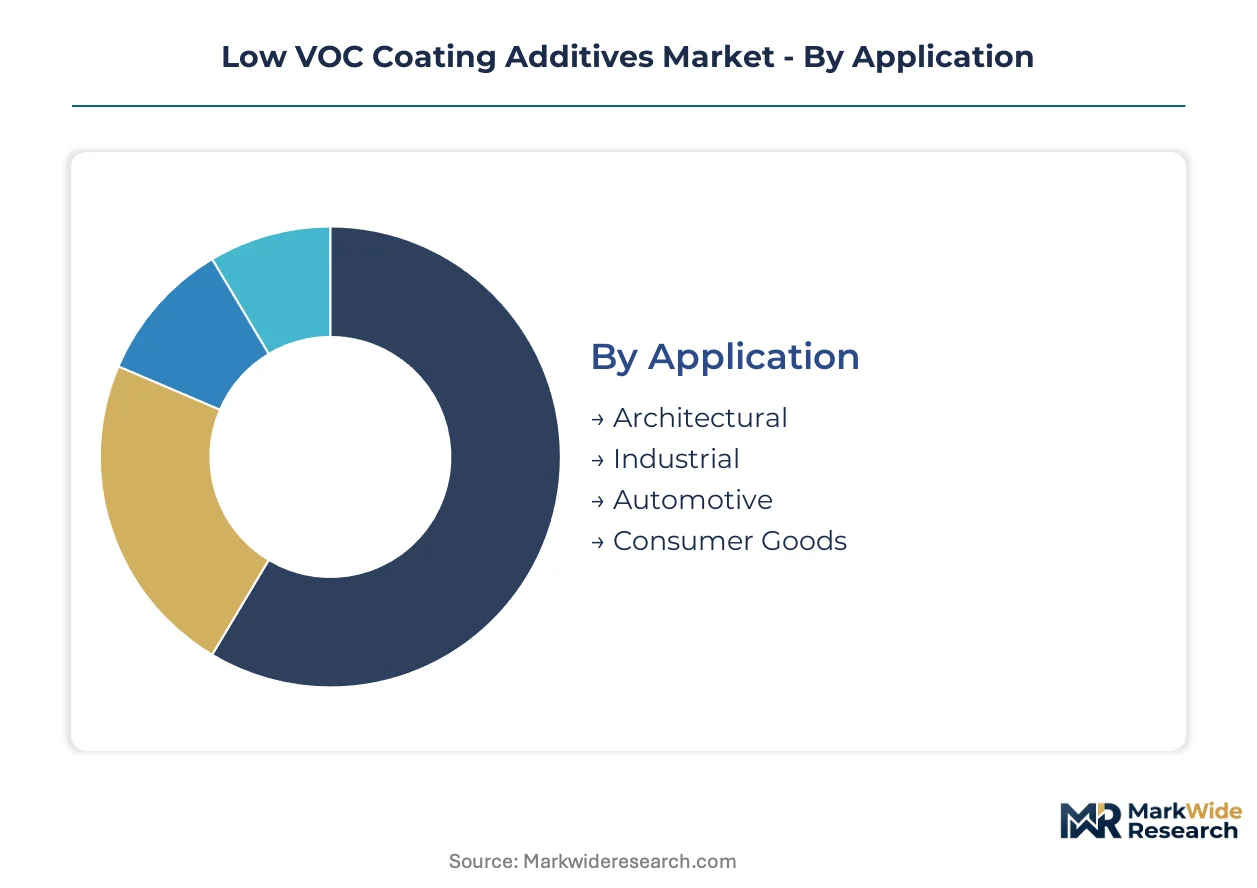
Low VOC coating additives serve divergent compliance regimes and performance specifications across end-use verticals. Segmentation reveals where formulation complexity concentrates margin capture and where supply bottlenecks shape procurement leverage.
Application:
Supply concentration in automotive and architectural additive production clusters creates geographic dependency for compliant formulation sourcing.
- Architectural:Water-based rheology modifiers and coalescing aids dominate this segment, formulated to meet EPA 40 CFR 59 thresholds below 50 grams per liter. Procurement concentrates in China as domestic projects pursue green building certification under tightening GB standards.
- Automotive:Interior cabin coatings and sealants drive specialized low-emission additive demand, with OEM supplier mandates enforcing compliance with air quality protocols. German and Japanese coaters pilot hybrid dispersant systems at scale.
- Industrial:Protective and marine coatings utilize corrosion-resistant additive packages.
- Consumer Goods:Appliance and furniture finishes require scratch-resistant low-VOC modifiers.
Today's leader: Architectural. Tomorrow's challenger: Automotive.
Type:
Cost tier stratification separates commodity fillers from specialty rheology agents commanding technical premiums.
- Additives:Surfactants, defoamers, rheology agents, and coalescing aids reduce VOC emissions while enabling film formation and substrate adhesion. Rheology modifiers capture the deepest margin pools due to reformulation complexity in solvent-to-water transitions.
- Resins:Water-based acrylic and polyurethane dispersions form the backbone of compliant coating systems. Integrated suppliers leverage captive resin production to sustain formulation leadership across architectural and automotive verticals.
- Colorants:Pigment dispersions and tinting systems require specialized dispersant technology.
- Fillers:Extender pigments and functional fillers adjust coating properties at lower cost tiers.
Additives command current margin concentration. Resins present the steepest expansion trajectory as water-based systems displace solvent formulations.
End User:
Customer type determines specification authority and volume procurement patterns across the value chain.
- Manufacturers:Large coating producers operate specification-led buying with direct additive supplier relationships. Technical service teams displace traditional sales roles in North American and Western European markets.
- OEMs:Automotive and appliance original equipment manufacturers enforce supplier compliance through mandated low-emission protocols. Procurement shifts toward approved product lists tied to certification bodies.
- Contractors:Professional applicators select additives based on project certification requirements.
- DIY Consumers:Retail channel demand responds to sustainability labeling and VOC disclosure mandates.
Manufacturers retain specification control. OEMs are gaining procurement leverage fastest through compliance mandates.
Formulation:
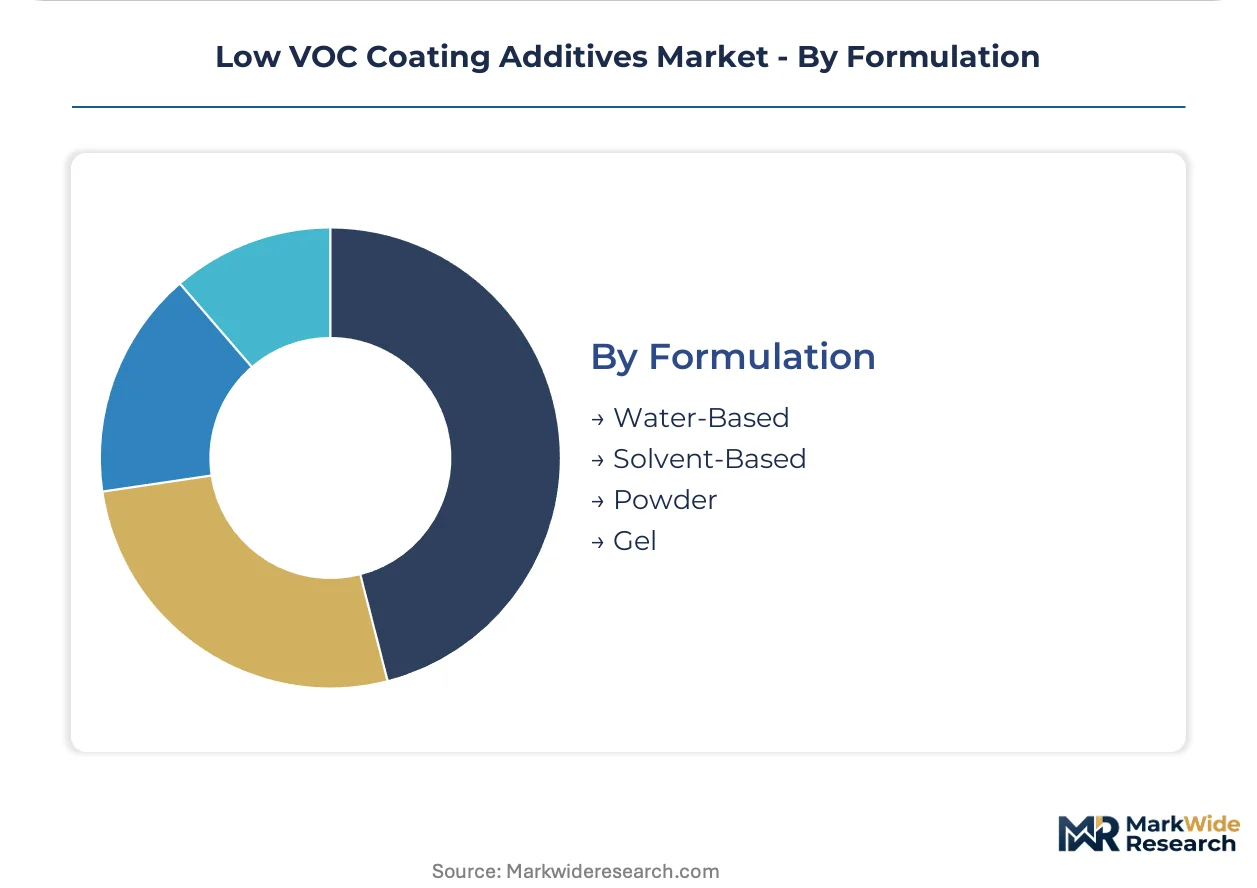
Volume distribution favors water-based systems while powder formulations remain tethered to industrial curing infrastructure.
- Water-Based:Dominant compliant platform utilizing surfactants and rheology modifiers to achieve film performance in reduced-VOC architectures. Regulatory compression across EPA, REACH, and GB standards accelerates reformulation cycles.
- Powder:Zero-VOC thermoset systems require specialized flow agents and curing catalysts. Growth concentrates in industrial coating lines with captive curing infrastructure for heat-sensitive substrates.
- Solvent-Based:Declining share confined to specialty applications exempt from strict thresholds.
- Gel:Thixotropic systems for vertical surface application and controlled film build.
Water-based formulations anchor current volume. Powder systems present the most constrained expansion path due to infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany's industrial Rhine corridor and China's coastal manufacturing zones, anchoring regional technical capacity for water-based system development.
United States
Automotive OEMs in Michigan and Ohio enforce interior air quality protocols that drive additive procurement for cabin coatings. EPA Rule 40 CFR 59 mandates VOC ceilings below 50 grams per liter for architectural finishes. Houston's petrochemical corridor hosts specialty surfactant production serving Gulf Coast coating manufacturers.
China
Domestic architectural projects in Shanghai and Beijing pursue green building certification under tightening GB standards. MEE implements progressive VOC content restrictions that compress reformulation timelines for multinational suppliers. The Yangtze River Delta concentrates water-based additive manufacturing capacity for Asia-Pacific distribution.
Germany
Tier-one automotive coaters in Stuttgart and Munich pilot hybrid dispersant systems at scale. REACH substance restrictions from ECHA accelerate substitution timelines for fluorinated wetting agents. The Rhine-Ruhr industrial belt anchors specialty rheology modifier production for European coating supply chains.
Japan
Automotive suppliers in Toyota City and Yokohama adopt low-emission additives for interior sealant applications. METI promotes environmental compliance standards that align with OEM supplier mandates. The Kansai region hosts integrated resin-additive production clusters serving precision coating manufacturers.
India
Domestic coating producers in Maharashtra and Gujarat expand water-based formulation capacity for infrastructure projects. The PLI scheme for chemicals incentivizes localized manufacturing of compliant additives. The Delhi-Mumbai Industrial Corridor attracts specialty chemical investments serving regional architectural demand.
Low VOC Coating Additives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The market structure concentrates margin capture among integrated resin-additive suppliers while fragmenting at the commodity surfactant level. Three archetypes dominate: integrated chemical majors with captive resin portfolios, specialty additive houses with dispersant technology leadership, and regional compounders serving localized certification requirements. Competitive moves center on backward integration into bio-based feedstocks and strategic partnerships with automotive OEMs for approved supplier list placement.
Within the integrated chemical major tier, BASF SE and Dow Chemical Company exemplify scale-driven formulation leadership through captive production of water-based system components. BYK (ALTANA) occupies a specialist position anchored in dispersant technology for pigment stabilization. These three entities represent divergent strategic postures: full-system integration versus functional specialization versus regional technical service density.
| Leading Market Players |
|---|
| PPG Industries |
| BYK (ALTANA) |
| BASF SE |
| Arkema Group |
| Lubrizol Corporation |
| Evonik Industries |
| Elementis plc |
| Eastman Chemical Company |
| Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility propagates downstream through three distinct pricing tiers, compressing margins for bio-based surfactant precursors while integrated resin producers capture formulation premiums in automotive and architectural verticals.
Pricing Analysis
Bundled technical service contracts separate from base additive pricing, with formulation support, regulatory compliance documentation, and custom rheology testing commanding 15-25% premiums over commodity surfactant supply. Price differentiation hinges on certification grade—EPA 40 CFR 59 compliance verification versus REACH SVHC screening—and volume scale, with automotive OEM procurement aggregating sufficient tonnage to negotiate long-term offtake agreements. Cost compression in standard-grade architectural additives intensifies as Chinese domestic manufacturers expand water-based system capacity. DIY consumers through retail channels exhibit highest price sensitivity, while automotive OEM specification engineers prioritize performance validation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by Tier 1 automotive coaters and multinational architectural manufacturers force additive suppliers to maintain qualified production across multiple geographies. Supply concentrates in Germany, China, and the United States, with specialty acrylic and cellulosic rheology modifier production anchored in Western Europe's industrial Rhine corridor. Raw material dependencies span ethylene oxide derivatives, bio-based fatty alcohols, and fluorinated wetting agent precursors. Single-source vulnerability persists for hybrid dispersant technologies where patent-protected molecular architectures limit supplier qualification. Distribution runs through regional compounding facilities that blend masterbatch concentrates for just-in-time delivery to coating manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA 40 CFR 59 threshold enforcement generates sustained additive procurement cycles across architectural and automotive reformulation waves.
For Market Incumbents: Hedge against bio-based feedstock price instability through backward integration into renewable alcohol production or strategic partnerships with agricultural processing cooperatives. Defend formulation leadership by embedding digital formulation platforms that compress customer R&D timelines. Capacity addition in India's chemical corridor under PLI scheme incentives secures Asia-Pacific supply chain positioning against Chinese domestic competitor expansion. For New Entrants and Emerging Players: Capture specification influence in India's infrastructure coating segment where green building certification adoption lags China and Western Europe, creating white-space for compliant water-based system introduction. Target contractor-grade architectural projects through distributor technical service partnerships that displace traditional specification sales roles. Lowest penetration exists in low-temperature powder coating flow agents for heat-sensitive industrial substrates. For Investors and Strategic Acquirers: Consolidation pressure builds where regional certification fragmentation forces additive portfolios into separate EPA, REACH, and GB standard validation cycles, favoring scaled players with regulatory affairs infrastructure. Mid-cap specialists with hybrid dispersant technology and automotive OEM approved-supplier-list placement represent prime acquisition targets. Watch ECHA SVHC list expansion velocity as inflection indicator for fluorinated wetting agent substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive renewable alcohol supply insulates margin compression from agricultural commodity volatility. |
| Digital Formulation Platform Deployment | AI-driven additive selection tools compress automotive OEM qualification timelines by 30-40%. |
| Regional Compounding Facility Expansion | Localized India production under PLI scheme reduces logistics exposure to Western European thickener clusters. |
| Hybrid Dispersant R&D Investment | Single-molecule pigment stabilization and wetting convergence tightens supplier qualification barriers. |
| OEM Approved Supplier List Placement | Automotive interior air protocol mandates concentrate procurement influence with certified additive portfolios. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating formulation chemists, automotive OEM supplier quality engineers, architectural manufacturer procurement directors, and specialty chemical distribution technical service managers with secondary validation against EPA regulatory filings, ECHA SVHC candidate list updates, ACC and Cefic industry statistics, and customs trade data for surfactant and rheology modifier flows. Bottom-up additive consumption estimates by end-use vertical triangulated against top-down coating production volume projections.
Segment-weighting approaches distributed value and volume across application, type, end user, and formulation dimensions, with water-based versus powder system splits calibrated to regional regulatory enforcement intensity. CAGRs derived from regression analysis of historical additive intensity ratios and forward projection of reformulation cycle timing. Automotive interior air quality protocol adoption curves and China's GB standard progression timelines served as industry-specific demand drivers.
Petrochemical feedstock volatility, ECHA substance restriction acceleration, and Chinese domestic manufacturer capacity expansion are the dominant revision risks that could compress or extend forecast additive demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tragacanth Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Surface Modifiers Market
Additives
Flux Injection System Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Trioctyldodecyl Citrate Market
Additives
1,4 Butanediol Derivatives Market
Additives
Global Propyl Acetate Market
Additives
Sodium Benzoate Market
Additives
Anti-Wear Additives Market
Additives
Global Cement Additives Market
Additives
Coating Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Antiblock Agents Market