
 Water-Borne Coating Additives Market | 2026-2036
Water-Borne Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Coating Additives Market Analytics
The EU Green Deal's chemical sustainability targets is shifting procurement priorities toward low-emission coating systems across European manufacturing. BASF SE leverages integrated polymer research to sustain leadership in dispersant chemistry for water-borne formulations. Dow Inc. anchors its position through controlled manufacturing scale in North American specialty additives. Evonik Industries AG differentiates via surface-active agent technology tailored for high-performance industrial coatings.
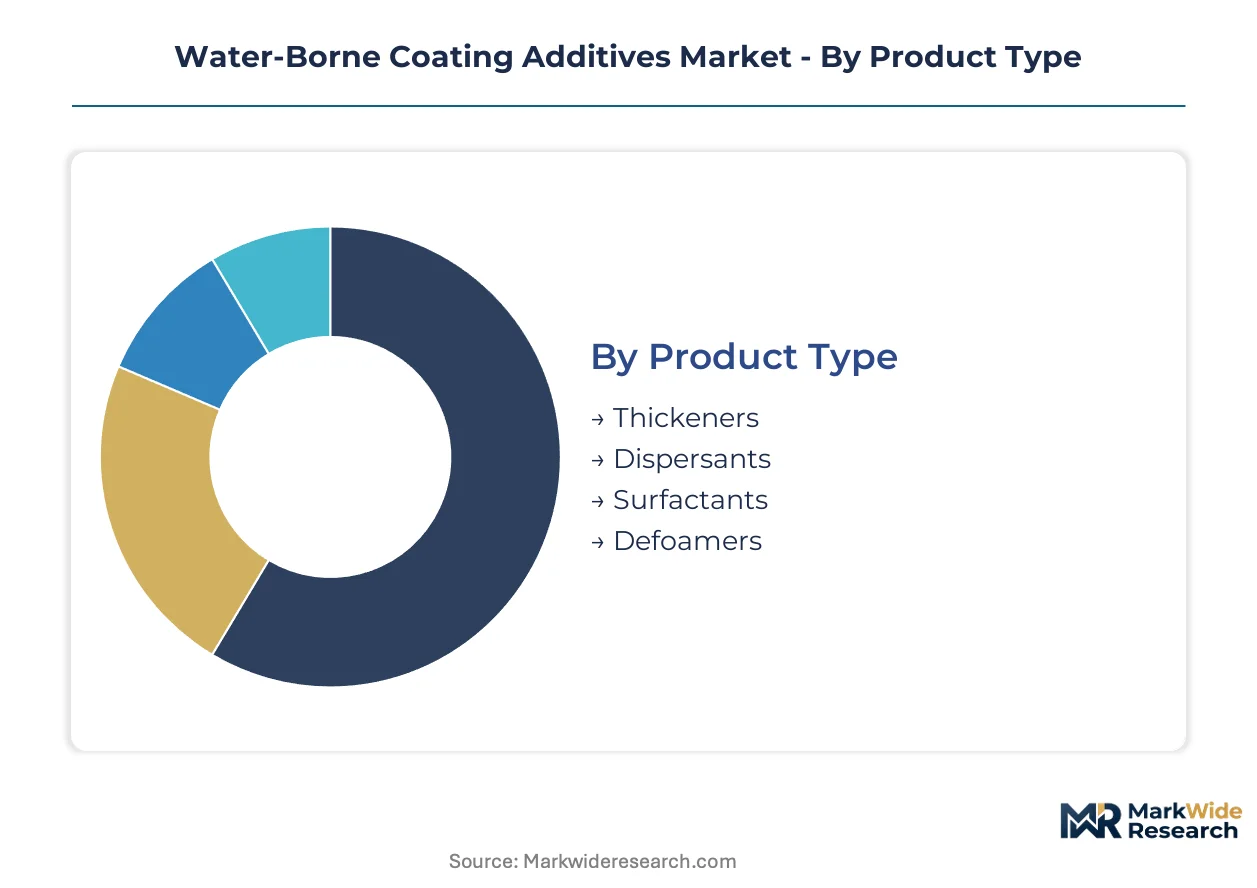
Water-borne coating additives are specialty chemicals—typically surfactants, dispersants, or rheology modifiers—formulated at active contents of 20-60% solids in aqueous media to stabilize pigments, control flow, and eliminate foam during paint application. Their primary purpose is enabling solvent-free or low-VOC coating systems that meet environmental compliance without sacrificing film performance. Dispersant chemistry captures the largest margin pool as pigment stabilization demands intensify across premium architectural grades. Bio-based technology represents the fastest-expanding segment as renewable feedstock verification becomes a procurement criterion for European and North American buyers. Defoamers remain mature with stable volumes but compressed pricing as Asian suppliers expand commodity-grade capacity.
REACH restrictions on volatile organic compound emissions and the EU F-Gas Regulation on industrial process standards shape product formulation requirements across European coating value chains. EPA oversight of hazardous air pollutants in the United States and China's MEE enforcement of dual carbon goals similarly constrain solvent-based system expansion in major manufacturing geographies. Stakeholders must monitor regulatory divergence between jurisdictions while aligning R&D portfolios with bio-based certification trajectories.
Market Dynamics
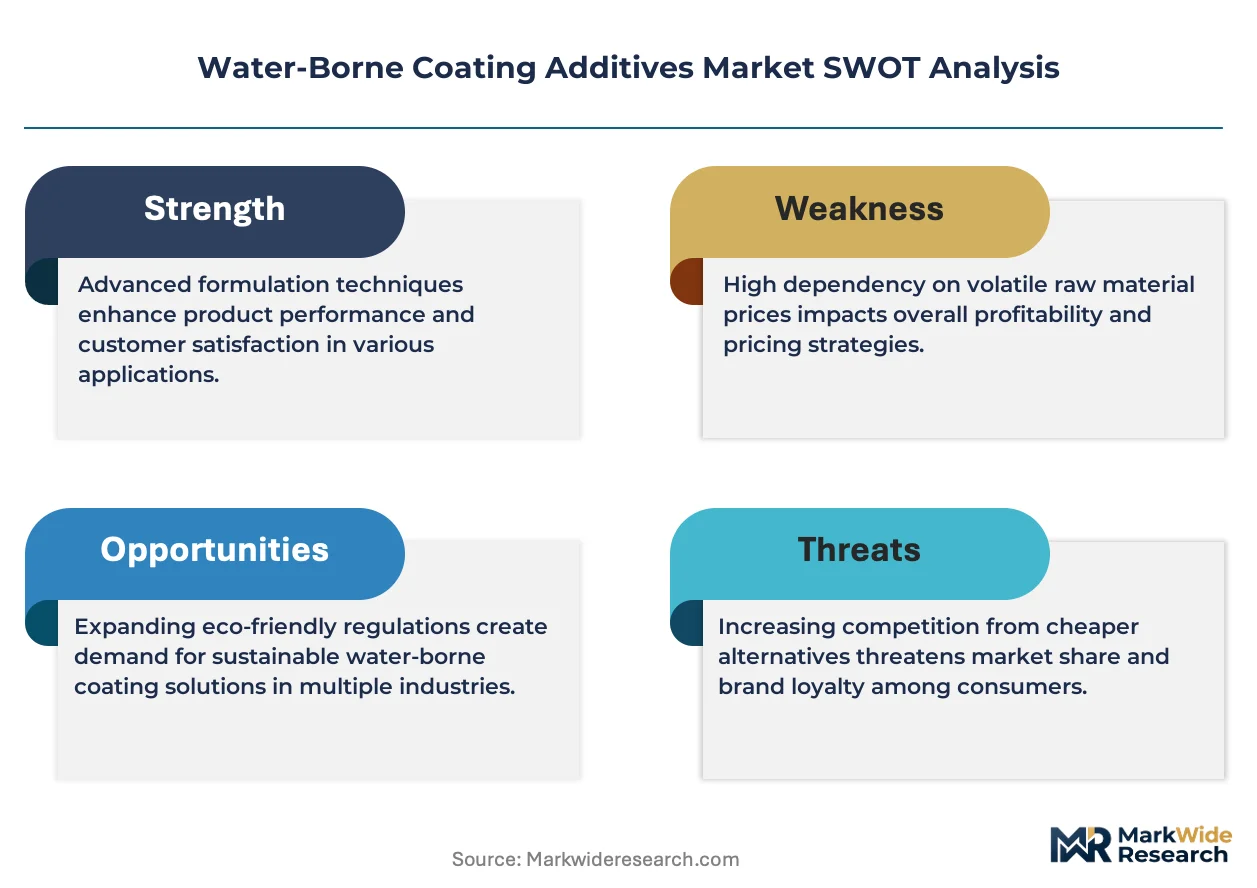
REACH enforcement and EPA hazardous air pollutant rules are compressing solvent-based coating volumes while redirecting capital toward aqueous formulation infrastructure across manufacturing clusters.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Procurement officers in European manufacturing now mandate low-emission coating systems for supplier qualification.
- Construction sector specification shifts:Architectural finish contractors in Germany and the United States increasingly specify low-VOC water-borne systems for commercial building projects.
- Dispersant chemistry advancement:Pigment stabilization technology enables premium-grade architectural coatings without solvent-borne performance trade-offs.
Market Restraints
- Bio-based feedstock cost volatility:Renewable raw material prices fluctuate with agricultural commodity cycles, squeezing margin on certified sustainable additive grades.
- Asian commodity defoamer oversupply:Capacity expansion by regional suppliers compresses pricing power in mature foam-control segments.
- Performance ceiling in extreme-climate applications:Water-borne film formation struggles versus solvent systems in high-humidity or sub-zero industrial coating environments.
Strategic Opportunities
- India infrastructure build-out:National highway and urban housing projects create first-mover advantage for low-VOC coating specification in a historically solvent-heavy market.
- Automotive refinish channel conversion:Collision repair networks in California and the Netherlands face regulatory deadlines accelerating water-borne basecoat adoption.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment mandates tighten industrial emission standards, forcing domestic coating producers toward aqueous additive portfolios.
Industry Challenges
- Formulation chemist scarcity:Water-borne rheology control and freeze-thaw stability expertise concentrates among senior specialists at major additive houses.
- Multi-jurisdiction certification timelines:Bio-based content verification under EU Ecolabel, USDA BioPreferred, and emerging Chinese green product standards requires parallel track submissions.
- Legacy solvent-borne equipment retrofit:Coating applicators face capital burden converting spray booths and drying lines for aqueous system compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Coating Additives Market |
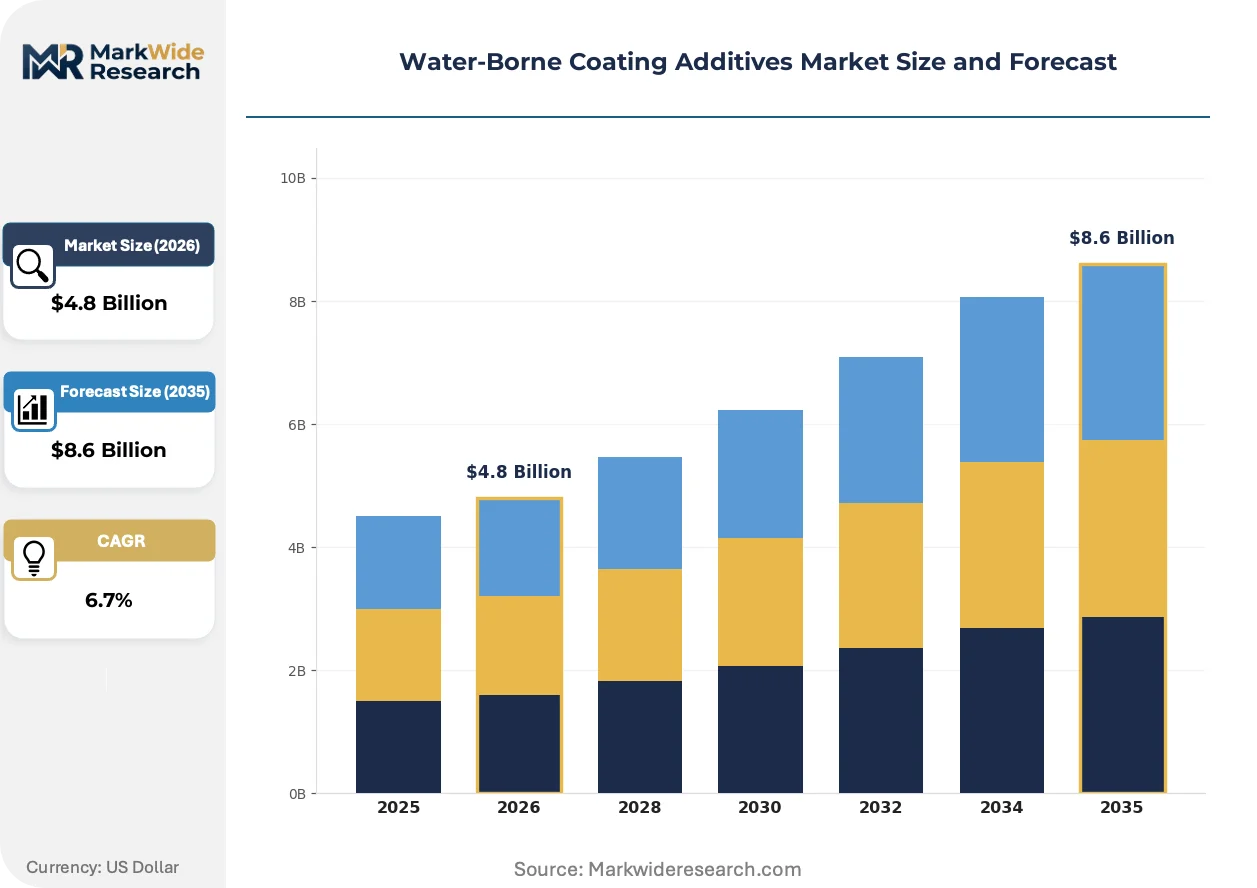
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickeners, Dispersants, Surfactants, Defoamers Application: Architectural Coatings, Industrial Coatings, Wood Coatings, Protective Coatings End User: Construction, Automotive, Furniture, Marine Technology: Polymerization, Microencapsulation, Nanotechnology, Bio-based |
| Companies Covered | BASF SE, Evonik Industries AG, Akzo Nobel N.V., BYK, Dow Inc., Allnex GMBH, ALTANA AG, The Lubrizol Corporation, Belami Fine Chemicals Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Coating Additives Market Evolving Landscape
Formulation intelligence platforms and feedstock traceability systems are compressing development cycles while embedding compliance documentation directly into additive specification workflows.
Machine learning formulation tools are automating dispersant selection and dosage optimization across architectural coating laboratories. Mid-tier paint manufacturers in the United States and Germany deploy these platforms to match premium-grade pigment stability without dedicated research chemists. The technology is automating technical service functions previously delivered through supplier field support, compressing headcount in regional coating operations.
REACH authorization procedures and the EU F-Gas Regulation are eliminating legacy surfactant chemistries from industrial coating value chains. ECHA substance evaluation drives substitution of fluorosurfactants in high-performance finishes. Automotive OEM coating specifications in Germany and the Czech Republic now exclude chemistries under sunset date review, forcing additive suppliers to accelerate bio-based replacements through validation pipelines.
Direct additive procurement from specialty chemical houses is displacing distributor-mediated purchasing among large coating manufacturers. Volume buyers in China and the United States negotiate frame contracts for dispersant and defoamer supply, extracting price transparency previously obscured by regional chemical distribution layers. This pattern concentrates procurement leverage with top-ten global paint producers while marginalizing independent regional formulators dependent on distributor technical service.
Water-Borne Coating Additives Market Segmentation
Water-borne coating additives demand fragments across distinct performance tiers and application specifications. Procurement patterns diverge sharply between commodity volume buyers and premium-grade formulators seeking certified sustainable chemistries.
Product Type:
Volume concentrates in mature foam-control chemistries while premium margin pools cluster around pigment stabilization technologies.
- Dispersants:Polymeric and small-molecule dispersants stabilize pigment particles at 20-50% active content, preventing flocculation in high-solids architectural formulations. Demand concentrates in Germany and the United States where premium paint manufacturers specify advanced dispersant packages for color consistency in commercial building projects. REACH authorization timelines for legacy surfactants accelerate substitution toward bio-based polyacrylate alternatives.
- Thickeners:Associative and cellulosic rheology modifiers control sag resistance and brush drag in water-borne systems. Construction sector specification shifts in China and India drive volume expansion as regional formulators upgrade from solvent-borne alkyd technologies.
- Surfactants:Wetting agents and emulsifiers reduce surface tension for substrate adhesion.
- Defoamers:Mineral oil and silicone-based foam control agents address entrained air during high-speed dispersion.
Today's leader: Dispersants. Tomorrow's challenger: Bio-based thickeners.
Application:
End-use concentration follows regulatory enforcement intensity across major manufacturing geographies.
- Architectural Coatings:Interior and exterior decorative finishes represent the dominant volume sink for water-borne additives. EU Green Deal procurement mandates and EPA hazardous air pollutant rules compress solvent-borne alternatives in commercial building specifications across Germany, the Netherlands, and California. Low-VOC compliance now gates supplier qualification for major retail paint channels.
- Industrial Coatings:Factory-applied finishes for metal and plastic substrates demand freeze-thaw stable additive packages. MEE dual carbon enforcement in China forces domestic appliance and automotive component coaters toward aqueous system conversion.
- Wood Coatings:Furniture and flooring finishes require defoamer and flow-control chemistries compatible with spray application.
- Protective Coatings:Infrastructure and marine corrosion protection represents the most technically demanding segment for water-borne film formation.
Architectural coatings dominate current procurement volumes. Industrial coatings are climbing the fastest as Chinese manufacturing upgrades aqueous capacity.
End User:
Customer-type differentiation separates project-based construction demand from specification-driven automotive qualification cycles.
- Construction:Commercial and residential building contractors specify water-borne systems for interior air quality compliance. Low-VOC mandates in German federal building codes and California Title 24 standards redirect additive procurement toward certified emission-free grades.
- Automotive:OEM and refinish coaters face technology conversion deadlines in the Netherlands and California collision repair networks.
- Furniture:Residential and contract furniture manufacturers specify water-borne finishes for indoor air quality certification.
- Marine:Shipyard and offshore platform coaters balance corrosion performance against environmental discharge regulations.
Construction commands present volume. Automotive refinish channels are gaining share fastest through regulatory deadline compression.
Technology:
Process innovation separates cost-optimized commodity production from patent-protected premium performance tiers.
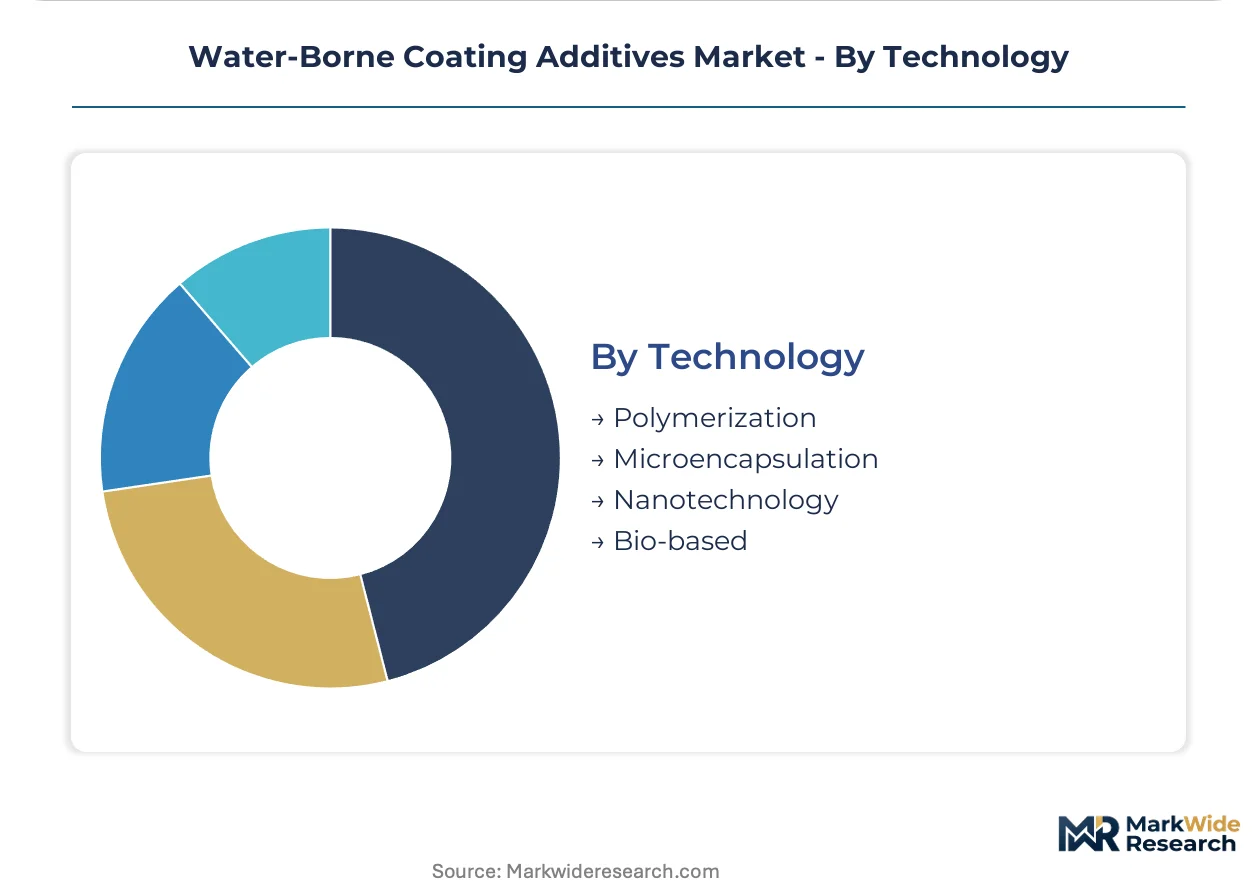
- Bio-based:Renewable feedstock additives verified under EU Ecolabel and USDA BioPreferred standards command procurement premiums. Agricultural commodity price volatility squeezes margin on certified sustainable grades, yet European and North American buyers increasingly mandate renewable content verification.
- Polymerization:Controlled radical and emulsion polymerization techniques produce dispersant and thickener architectures with defined molecular weight distribution.
- Microencapsulation:Shell-core particle engineering enables triggered release of active ingredients during film formation.
- Nanotechnology:Sub-100nm particle additives modify surface properties and barrier performance.
Polymerization anchors current production economics. Bio-based technology is expanding most quickly as certification becomes a procurement gate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern water-borne coating chemistry through integrated polymer research clusters established in the 1960s. BASF SE and Evonik Industries AG scaled dispersant manufacturing from Ludwigshafen and Essen, creating the technical foundation that now diffuses across Asia-Pacific production bases.
United States
California collision repair networks and federal building specifications drive water-borne additive demand. EPA hazardous air pollutant rules compress solvent-borne alternatives in automotive refinish channels. Houston-Gulf Coast petrochemical corridors host Dow Inc.'s specialty additive manufacturing, supplying aqueous dispersant packages to North American paint formulators.
Germany
Premium architectural coatings and automotive OEM specifications concentrate demand for high-performance dispersants. REACH authorization timelines and EU Green Deal procurement mandates eliminate legacy surfactant chemistries from industrial value chains. Ludwigshafen and Essen industrial clusters anchor BASF SE and Evonik Industries AG integrated research-to-production infrastructure for water-borne additive families.
China
Domestic appliance manufacturing and infrastructure construction accelerate aqueous coating system conversion. MEE dual carbon enforcement tightens industrial emission standards, forcing coating producers toward water-borne additive portfolios. Yangtze River Delta chemical parks in Jiangsu and Zhejiang provinces expand water-borne production capacity to serve Asian architectural and industrial coating markets.
Netherlands
Automotive refinish regulatory deadlines and sustainable building certification drive low-VOC specification. EU F-Gas Regulation and ECHA substance evaluation eliminate fluorosurfactant chemistries from high-performance finishes. Rotterdam-Antwerp chemical corridor hosts Akzo Nobel N.V. formulation research, bridging European regulatory compliance with aqueous technology deployment.
India
National highway and urban housing projects create first-mover opportunity for low-VOC coating specification in historically solvent-heavy construction markets. BIS emission standards and state-level green building codes gradually tighten architectural finish requirements. Maharashtra and Gujarat industrial corridors attract water-borne additive investments serving domestic coating manufacturers upgrading from alkyd technologies.
Water-Borne Coating Additives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the water-borne coating additives sector. Integrated chemical conglomerates with captive polymer research infrastructure command premium dispersant margins, while regional compounders source commodity defoamer packages from Asian manufacturing bases. Three archetypes dominate: integrated polymer houses with backward control into feedstock supply, specialty additive boutiques focused on formulation intelligence services, and volume-scale Asian suppliers competing on cost-optimized commodity grades. Competitive moves concentrate on direct procurement frame contracts with top-ten paint manufacturers and bio-based certification acceleration to meet EU Ecolabel and USDA BioPreferred verification timelines.
Among German-integrated chemical conglomerates, BASF SE and Evonik Industries AG exemplify the research-intensive archetype with Ludwigshafen and Essen-based polymer science infrastructure. Dow Inc. represents North American manufacturing scale, anchoring controlled production of specialty additives for aqueous formulation markets. Akzo Nobel N.V. occupies a position bridging European regulatory compliance expertise with global coating specification networks, while BYK and ALTANA AG sit within the precision additive tier serving high-performance industrial finish requirements.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Akzo Nobel N.V. |
| BYK |
| Dow Inc. |
| Allnex GMBH |
| ALTANA AG |
| The Lubrizol Corporation |
| Belami Fine Chemicals Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between bio-based verified additives and commodity petroleum-derived grades splits pricing power across parallel supply channels. European and North American buyers mandate EU Ecolabel and USDA BioPreferred verification, extracting transparency premiums from additive houses with captive renewable feedstock supply. Asian commodity producers without certification infrastructure compete on spot pricing for unverified defoamer and thickener volumes, compressing margins in standardized product tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs water-borne additive transactions. Premium tiers command verification premiums for bio-based dispersants under REACH-compliant sustainability protocols, while economy tiers face relentless price compression from Chinese and Indian commodity suppliers. Cost compression in mature defoamer segments intensifies because regional Asian capacity expansion outpaces demand absorption. Large paint manufacturers with direct procurement frame contracts exhibit lowest price sensitivity; independent regional formulators dependent on distributor technical service face highest sensitivity.
Supply Chain Analysis
Petrochemical feedstock supply rests on integrated producers in Germany, the United States, and Saudi Arabia with backward control into ethylene oxide and acrylic acid monomers. Specialty surfactant production draws from propylene oxide derivatives and renewable fatty alcohols sourced through agricultural commodity markets. Single-source vulnerability concentrates in bio-based fatty acid methyl esters tied to palm and rapeseed oil harvest cycles. Distribution runs through direct frame contracts between top-ten global paint producers and integrated additive houses, marginalizing regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as construction sector procurement shifts toward low-VOC certified architectural finishes. Regulatory deadline compression in automotive refinish channels accelerates premium-grade dispersant specification.
For Market Incumbents: Extend backward integration into renewable feedstock supply to defend margin position against agricultural commodity volatility. Accelerate bio-based certification pipelines under EU Ecolabel and USDA BioPreferred timelines before sunset date reviews eliminate legacy surfactant chemistries. Capacity addition in Yangtze River Delta chemical parks anchors Asian market share against domestic Chinese additive houses. For New Entrants and Emerging Players: Launch via specialty distributor partnerships serving mid-tier paint manufacturers without direct procurement leverage with BASF SE or Evonik Industries AG. Target India's infrastructure build-out for first-mover advantage in historically solvent-heavy construction markets. Pursue automotive refinish channel conversion in California and the Netherlands where regulatory deadlines force aqueous system adoption. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates technical expertise among senior specialists at major additive houses. Long-term viability favors asset-light designers with machine learning formulation platforms automating dispersant selection. Acquisition target archetype: specialty additive boutiques with validated bio-based replacements for fluorosurfactants under ECHA substance evaluation. Watch MEE dual carbon enforcement intensity as inflection indicator for Chinese domestic coating producer conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | BASF SE and Evonik Industries AG secure margin stability against agricultural commodity price cycles. |
| Bio-Based Certification Acceleration | EU Ecolabel and USDA BioPreferred verification gates supplier qualification for European and North American procurement officers. |
| Direct Procurement Frame Contracts | Top-ten global paint producers extract price transparency previously obscured by regional chemical distribution layers. |
| Machine Learning Formulation Platforms | Mid-tier paint manufacturers in Germany and the United States match premium-grade pigment stability without dedicated research chemists. |
| Capacity Expansion in Yangtze River Delta | Jiangsu and Zhejiang chemical parks serve Asian architectural and industrial coating markets under MEE dual carbon enforcement. |
Research Methodology
Bottom-up construction sector modeling reconciled against top-down specialty chemical production tracking forms the analytical core. Primary interviews with formulation chemists at major additive houses, procurement leads at top-ten paint manufacturers, plant managers at Yangtze River Delta chemical parks, and technical R&D directors at integrated polymer houses supplied demand-side validation. Secondary sources included customs and trade data from Eurostat and USITC, REACH authorization timelines from ECHA, SEC 10-K filings from listed chemical conglomerates, and MEE enforcement bulletins from China's Ministry of Ecology and Environment.
Input-output matrices mapped additive consumption intensity across architectural, industrial, wood, and protective coating applications throughout the forecast period. Segmentation dimensions covered product type, application, end user, and technology tier with regional production hub differentiation. CAGRs were derived from regression analysis against construction sector investment cycles and regulatory enforcement intensity indices. Industry-specific forecast inputs included REACH sunset date schedules and MEE dual carbon mandate implementation trajectories.
Several conditions sit outside the modeled scope, including abrupt shifts in agricultural commodity pricing for bio-based feedstocks and unilateral tariff impositions on specialty chemical imports. Forecasts reflect documented assumptions about regulatory enforcement continuity and construction sector investment patterns. A small set of named triggers warrants ongoing watch: ECHA substance evaluation acceleration, MEE inspection intensity in Jiangsu province, and California Title 24 standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phthalate Plasticizer Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Middle East Feed Additives Market
Additives
Europe UV Stabilizers Market
Additives
Mycotoxin Binders Market
Additives
Extrusion Aids Market
Additives
Rosin Ester Market
Additives
Tricalcium Citrate Market
Additives
China Sodium Reduction Ingredient Market
Additives
Saudi Arabia Feed Additives Market
Additives
Citric Acid Anhydrous Market
Additives
Nucleotide Premix Market
Additives
Sorbitan Tristearate Market
Additives
Global Metal Scavenging Agents Market
Additives
Global Formulation Additives Market
Additives
Isobutyl Acetate Market