
 Binding Agents Market | 2026-2036
Binding Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Binding Agents Market Analytics
Asset-light toll manufacturing and third-party leasing of polymerization capacity is tilting competitive dynamics toward firms that can access flexible production without owning fixed assets. BASF SE leverages its integrated petrochemical feedstock network to control input costs across synthetic resin lines. Dow anchors its position through membrane-grade cellulose ether technologies serving pharmaceutical and construction end users. Wacker Chemie AG specializes in dispersible polymer powders that command premium positioning in European dry-mix mortar applications.
Binding agents are adhesive or cohesive substances—spanning natural polymers, synthetic resins, starch derivatives, and cellulose ethers—that physically or chemically bond particulate matter into stable matrices, typically functioning at loadings between 2% and 15% by weight depending on substrate porosity and end-use performance requirements. The construction application segment dominates current volume as cementitious and gypsum-based systems rely heavily on redispersible polymer powders and cellulose derivatives for workability retention and crack resistance. Synthetic resins represent the fastest-expanding product category, driven by waterborne acrylic and vinyl acetate formulations displacing solvent-borne alternatives in regulated coating and adhesive markets.
REACH registration requirements in Europe, EPA VOC emissions rules under the Clean Air Act in the United States, and BIS certification mandates for construction chemicals in India collectively elevate compliance costs while accelerating substitution toward bio-based and low-emission binder platforms. ECHA substance evaluation protocols and evolving GB standards under China's SAMR framework are further narrowing the acceptable formulation space for formaldehyde-releasing and heavy-metal-containing systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D pipelines.
Market Dynamics
Formulation chemistry is pivoting toward waterborne and bio-based platforms as REACH, EPA Clean Air Act, and BIS certification mandates collectively disqualify legacy solvent-borne and formaldehyde-releasing systems across construction, pharmaceutical, and coating end uses.
Growth Catalysts
- Green building code tightening:Germany's federal building regulations, California's Title 24 standards, and India's Energy Conservation Building Code are mandating low-VOC admixtures in cementitious systems, pulling demand for redispersible polymer powders and cellulose ethers.
- REACH substance evaluation:ECHA's ongoing scrutiny of formaldehyde-releasing binders and heavy-metal catalysts is accelerating substitution toward bio-based lignin and starch derivatives in European dry-mix mortar applications.
- Waterborne acrylic polymerization:Advances in emulsion polymerization technology are enabling high-solids, low-VOC vinyl acetate-ethylene copolymers to penetrate wood adhesive and architectural coating segments previously dominated by solvent-borne alkyd systems.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings directly compress margins for synthetic resin binders, particularly waterborne acrylics and vinyl acetate emulsions where monomer costs constitute 40-60% of finished goods economics.
- Regional supply concentration:Dispersible polymer powder capacity clusters disproportionately in Western Europe and coastal China, exposing buyers in India, Southeast Asia, and Latin America to freight cost inflation and currency-driven price instability.
- Performance ceiling of bio-based alternatives:Lignin and starch-derived binders currently exhibit inferior moisture resistance and tensile adhesion compared to synthetic resins, restricting their penetration in exterior-grade construction and high-humidity pharmaceutical applications.
Strategic Opportunities
- India's infrastructure build-out:National Highway Authority and Smart Cities Mission procurement is scaling demand for tile adhesives, waterproofing membranes, and self-leveling underlayments where cellulose ether and redispersible powder loadings are rising.
- Pharmaceutical excipient grade certification:USP-NF and EP compliance for tablet binding applications creates premium pricing power for cellulose ether producers capable of meeting residual solvent and heavy-metal specifications.
- Digital formulation platforms:AI-driven rheology modeling and predictive compatibility screening are compressing R&D cycles for custom binder blends, enabling toll manufacturers to serve regional construction chemical formulators with faster turnaround.
Industry Challenges
- Cross-jurisdictional registration complexity:REACH dossier maintenance, EPA TSCA Section 5 notifications, and China's MEE new chemical registration create overlapping compliance burdens that strain mid-sized producers without dedicated regulatory affairs infrastructure.
- Specialized polymerization engineering scarcity:Talent capable of scaling semi-batch emulsion processes from pilot to commercial scale commands premium compensation, constraining capacity expansion timelines for emerging market entrants.
- Legacy equipment retrofit requirements:Transitioning solvent-borne production lines to waterborne systems demands capital-intensive vessel cleaning, drying system upgrades, and explosion-proofing modifications that extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binding Agents Market |
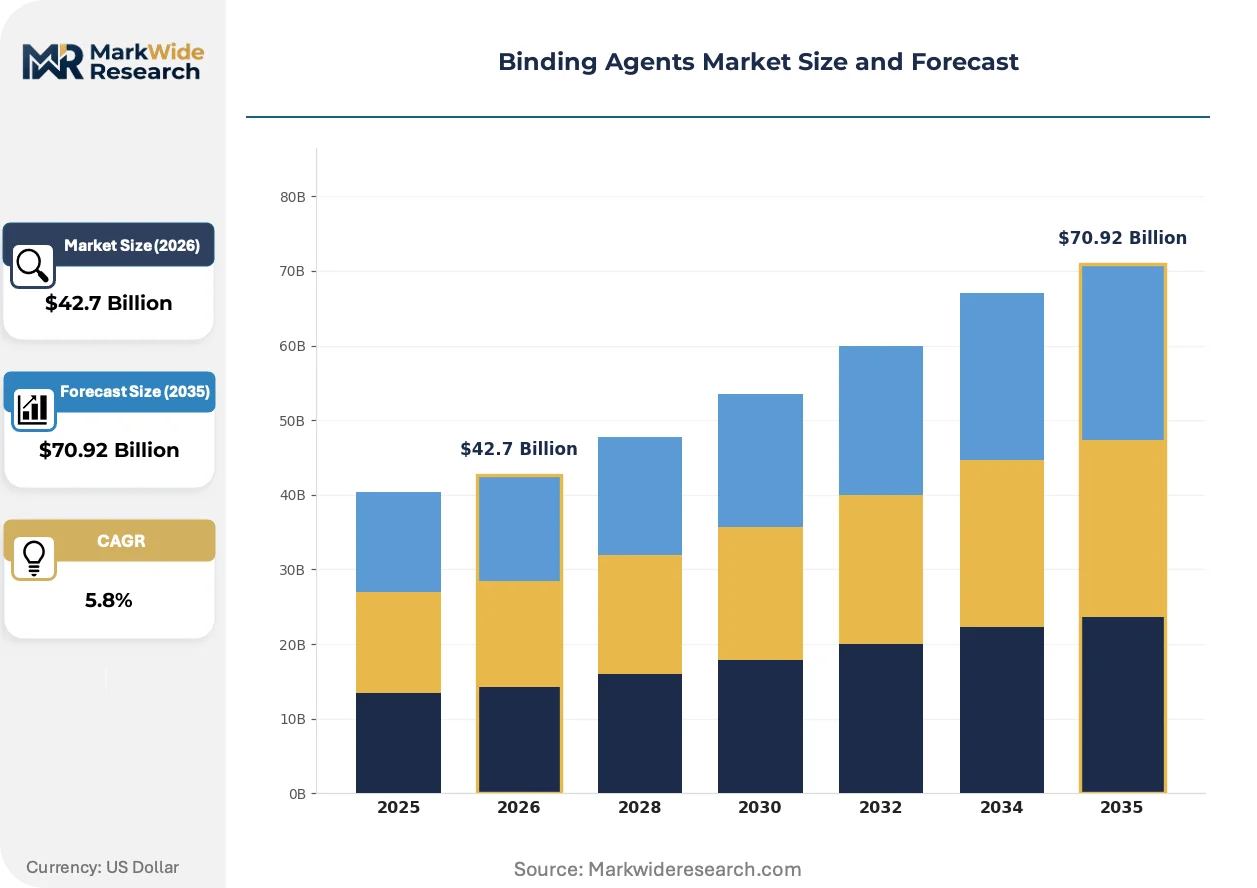
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
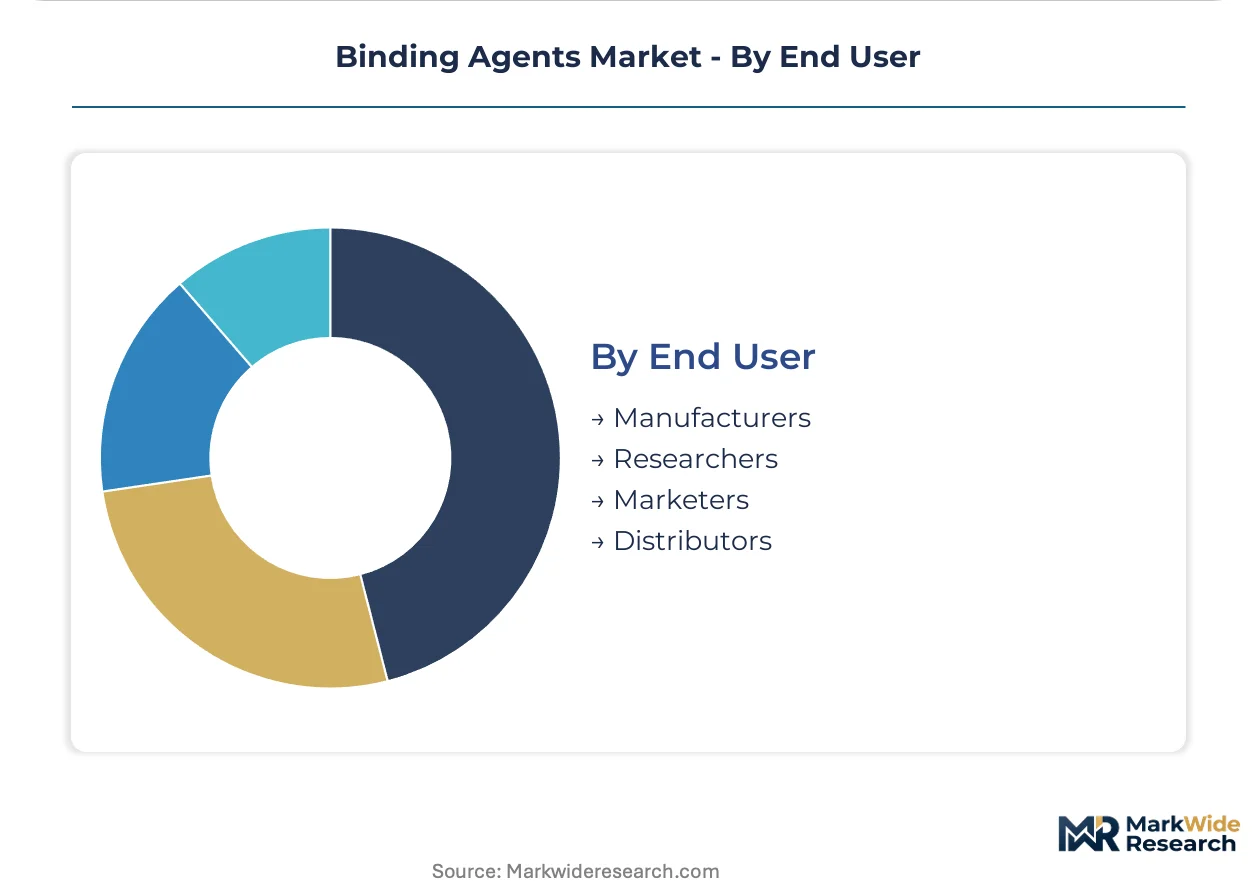
| Segmentation | Product Type: Natural Polymers, Synthetic Resins, Starch-Based Agents, Cellulose Derivatives Application: Pharmaceuticals, Food & Beverage, Construction, Personal Care Form: Granules, Powders, Liquids, Sheets End User: Manufacturers, Researchers, Marketers, Distributors |
| Companies Covered | BASF SE, Dow, Arkema, Celanese Corporation, Wacker Chemie AG, H.B. Fuller, Henkel AG, Synthomer PLC, OMNOVA Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binding Agents Market Evolving Landscape
Active materials science and digital manufacturing tools are compressing formulation development timelines while regulatory chemistry restrictions are narrowing the acceptable molecular design space for new product introductions.
Enzymatic modification of starch and protein binders is rendering obsolete energy-intensive chemical derivatization routes that relied on acid hydrolysis and etherification at elevated temperatures. Construction chemical formulators in Northern Europe are piloting these biocatalytic platforms for interior-grade gypsum board and wallpaper paste applications. The technology is compressing carbon intensity metrics while meeting stricter EPD and LEED v4.1 disclosure requirements.
EPA's amended National Emission Standards for Hazardous Air Pollutants for miscellaneous organic chemical manufacturing is tightening residual monomer limits in emulsion polymers used in consumer-facing adhesives and coatings. US-based producers are investing in stripping column upgrades and post-polymerization scavenger chemistry to maintain market access. The rule is most acute for vinyl acetate-ethylene emulsions serving the DIY wood adhesive segment.
Specification-driven procurement by multinational construction chemical distributors is displacing spot-market purchasing for standard-grade cellulose ethers and redispersible powders. Tier-one dry-mix mortar producers in Germany and the United States are consolidating supplier panels and demanding lot-to-lot viscosity consistency data with certificate of analysis documentation. This behavior is most visible in facade insulation systems where warranty liability for adhesive failure concentrates with the formulator rather than the binder supplier.
Binding Agents Market Segmentation
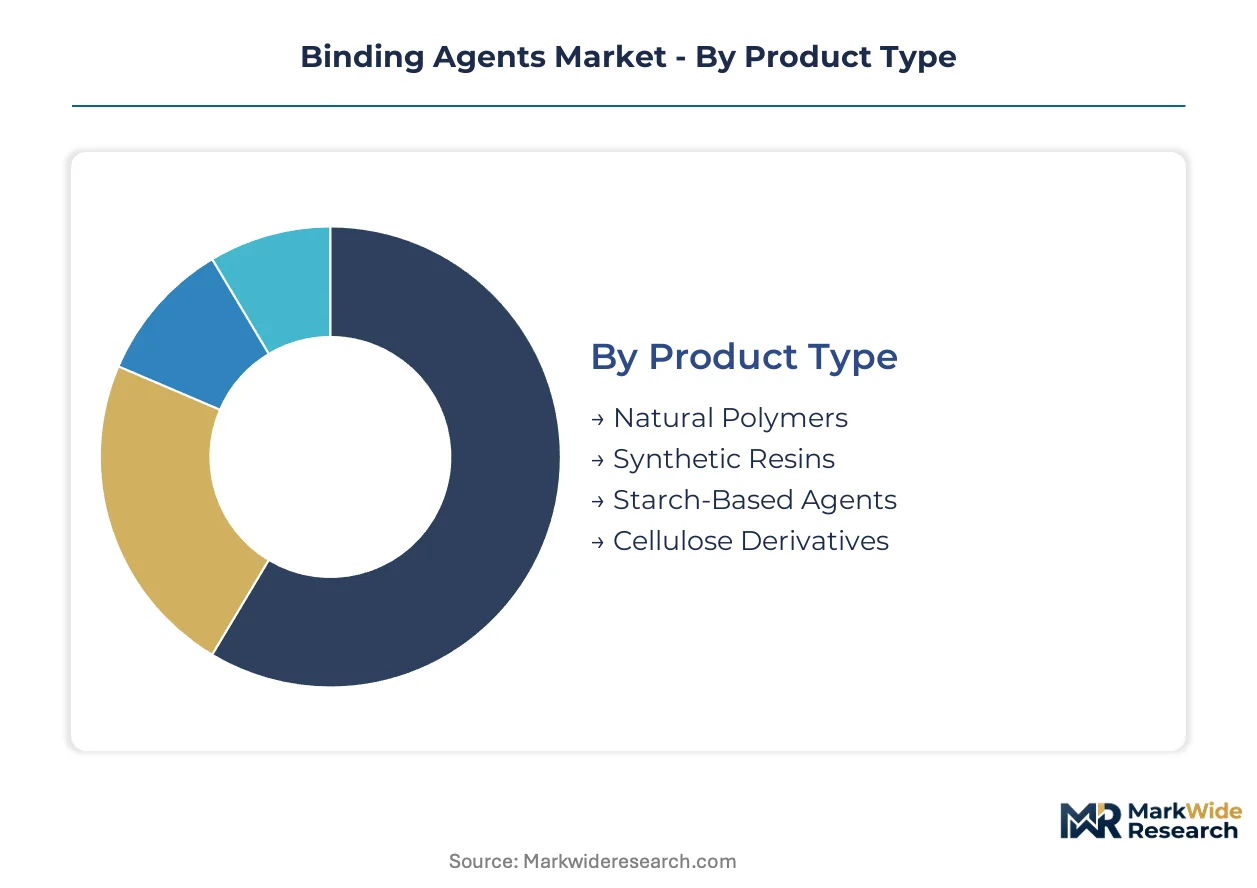
Binding agents serve functionally distinct end uses where formulation specifications, regulatory thresholds, and procurement volumes diverge sharply. Segmentation reveals where margin concentrates versus where volume scales, guiding capital allocation across product development and geographic expansion.
Product Type:
Synthetic resins turn inventory fastest through construction chemical channels, while natural polymers move slowly through pharmaceutical qualification cycles. Cellulose derivatives and starch-based agents occupy intermediate velocity tiers depending on end-use certification requirements.
- Synthetic Resins:Waterborne acrylic and vinyl acetate-ethylene copolymers dominate cementitious admixtures and architectural coatings. Demand concentrates in China's infrastructure procurement and Germany's dry-mix mortar sector as green building codes tighten. REACH substance evaluation is accelerating substitution away from formaldehyde-releasing systems.
- Cellulose Derivatives:Etherified cellulose grades function as rheology modifiers and tablet binders across pharmaceutical and construction applications. USP-NF and EP compliance creates premium pricing power for producers meeting residual solvent specifications. Specification-driven procurement by multinational distributors is consolidating supplier panels.
- Natural Polymers:Lignin and protein-based systems serve interior-grade gypsum board and wallpaper paste applications. Enzymatic modification routes are displacing energy-intensive acid hydrolysis in Northern European pilot programs.
- Starch-Based Agents:Modified starch derivatives bind pharmaceutical tablets and food formulations. BIS certification mandates in India and FDA food additive regulations govern acceptable modification chemistries.
Synthetic resins dominate installed base. Natural polymers are where expansion concentrates as bio-based procurement policies mature.
Application:
Cost tier stratification separates commodity construction chemicals from premium pharmaceutical excipients, with food and personal care occupying intermediate value bands.
- Construction:Cementitious systems, tile adhesives, and self-leveling underlayments consume redispersible polymer powders and cellulose ethers at 2-15% loadings. India's National Highway Authority and Smart Cities Mission procurement is scaling volumes fastest.
- Pharmaceuticals:Tablet binding and controlled-release matrix applications demand excipient-grade certification with heavy-metal and residual solvent documentation. USP-NF compliance creates supplier stickiness through qualification timelines.
- Food & Beverage:Modified starches and natural gums stabilize emulsions and control moisture migration. FSSAI standards in India and FDA GRAS listings determine acceptable additive chemistries.
- Personal Care:Film-forming polymers and rheology modifiers serve skin and hair care formulations. EPA VOC emissions rules under the Clean Air Act constrain solvent-borne system availability.
Construction commands volume leadership. Pharmaceuticals deliver margin concentration.
Form:
Supply chain configuration favors powders for dry-mix mortar distribution, while liquid emulsions require specialized tanker logistics and shorter shelf-life management.
- Powders:Redispersible polymer powders and cellulose ether granules dominate European and Chinese dry-mix mortar production. Freight cost inflation from Western European capacity clusters pressures Indian and Southeast Asian buyers.
- Liquids:Waterborne emulsion polymers serve wood adhesives and architectural coatings. EPA's amended National Emission Standards for Hazardous Air Pollutants is tightening residual monomer limits in consumer-facing applications.
- Granules:Direct-compression pharmaceutical grades and construction admixtures flow through automated dosing systems. Particle size distribution consistency determines lot-to-lot performance.
- Sheets:Specialized film-forming applications in personal care and food lamination occupy niche procurement channels with longer lead times.
Powders anchor production capacity. Liquids are climbing the fastest as waterborne formulation platforms displace solvent systems.
End User:
Customer type determines specification intensity, with manufacturers demanding certificate-of-analysis documentation while distributors prioritize inventory velocity.
- Manufacturers:Construction chemical formulators and pharmaceutical compounders drive bulk procurement with stringent viscosity consistency requirements. Tier-one dry-mix mortar producers in Germany and the United States are consolidating supplier panels.
- Distributors:Multinational construction chemical distributors are displacing spot-market purchasing with specification-driven procurement frameworks. Lot-to-lot documentation requirements concentrate sourcing with qualified suppliers.
- Researchers:Custom binder blend development for pilot-scale applications generates smaller volume, higher margin transactions. AI-driven rheology modeling is compressing R&D cycle times.
- Marketers:Private-label and co-branded positioning drives differentiated formulation requests with premium positioning objectives.
Manufacturers dominate procurement volume. Distributors are where channel control concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European capacity clusters command premium pricing power against Indian buyers who absorb freight-inflated redispersible polymer powders. Chinese infrastructure procurement anchors volume leadership while German green building codes tighten formulation specifications. Regional divergence in regulatory stringency is fragmenting acceptable chemistries across jurisdictions.
Germany
Dry-mix mortar producers in Bavaria and North Rhine-Westphalia are consolidating supplier panels for facade insulation adhesives. Federal building regulations under the Energy Conservation Ordinance mandate low-VOC admixtures in cementitious systems. The Rhine-Ruhr industrial corridor hosts redispersible polymer powder capacity serving specification-driven procurement by tier-one construction chemical distributors.
United States
California's Title 24 standards and EPA Clean Air Act amendments are tightening residual monomer limits in waterborne emulsion polymers. DIY wood adhesive manufacturers in the Midwest are investing in stripping column upgrades to maintain consumer-facing market access. The Southeast construction corridor from Texas to Florida is scaling tile adhesive consumption behind residential and commercial build-out.
China
Infrastructure spending through the National Development and Reform Commission is pulling vinyl acetate-ethylene copolymer volumes into cementitious admixtures. SAMR's evolving GB standards under the dual carbon goals are narrowing acceptable formulation space for formaldehyde-releasing systems. The Yangtze River Delta concentration of pharmaceutical tablet production is scaling excipient-grade cellulose ether procurement.
India
The National Highway Authority and Smart Cities Mission are scaling demand for self-leveling underlayments and waterproofing membranes. BIS certification mandates for construction chemicals are elevating compliance costs for imported redispersible powders. Gujarat and Maharashtra industrial clusters are emerging as domestic formulation hubs seeking to reduce dependence on Western European supply.
Binding Agents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positioning. The vendor base organizes around three archetypes: integrated petrochemical conglomerates with captive feedstock access, specialty chemical houses with pharmaceutical-grade certification capabilities, and toll manufacturers leveraging asset-light capacity leasing. Consolidation pressures concentrate among mid-scale emulsion polymer producers lacking REACH dossier infrastructure or EPA compliance bandwidth. Dominant competitive moves include backward integration into monomer supply and geographic expansion through regional tolling partnerships.
Within the integrated petrochemical tier, BASF SE and Dow exemplify scale-driven positioning anchored by feedstock network control. Wacker Chemie AG occupies a specialist position focused on dispersible polymer powder technologies. These three entities represent divergent strategic postures: feedstock-integrated breadth, membrane-grade cellulose ether verticality, and European dry-mix mortar premium positioning respectively.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Arkema |
| Celanese Corporation |
| Wacker Chemie AG |
| H.B. Fuller |
| Henkel AG |
| Synthomer PLC |
| OMNOVA Solutions Inc. |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility compresses margin structures across synthetic resin tiers while simultaneously forcing supply chain reconfiguration toward regional tolling partnerships. This dual pressure mechanism widens spreads between premium excipient-grade cellulose ethers and commodity construction admixtures as buyers absorb divergent risk profiles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the binding agents market. Pharmaceutical excipient-grade cellulose ethers command substantial premiums over construction-grade redispersible powders due to USP-NF certification requirements and residual solvent documentation. Pricing pressure stems from monomer cost volatility in waterborne acrylic emulsions where feedstock swings constitute the dominant cost component. Spot-market purchasers in India's construction chemical sector exhibit the highest price sensitivity, while qualified pharmaceutical compounders demonstrate stickiness through multi-year supply agreements.
Supply Chain Analysis
Export-control restrictions on advanced polymerization catalysts limit technology transfer to emerging production hubs in India and Southeast Asia. Dispersible polymer powder capacity concentrates in Germany, coastal China, and the United States, creating freight-inflated delivered costs for buyers in India and Latin America. Raw material dependencies center on vinyl acetate monomer, ethylene feedstock, and purified cellulose pulp sourced from integrated petrochemical networks. Single-source vulnerability concentrates in Western European redispersible powder supply to India's infrastructure build-out. Distribution runs through multinational construction chemical distributors consolidating supplier panels for tier-one dry-mix mortar producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The binding agents market requires substitution defense against enzymatically modified starch and protein binders as bio-based procurement policies mature in Northern Europe. Lignin-derived alternatives threaten synthetic resin incumbents in interior-grade construction applications where moisture resistance requirements are less stringent.
For Market Incumbents: Build regulatory dossier moats by accelerating REACH registration completion and EPA TSCA Section 5 notification breadth before mid-scale competitors exhaust compliance bandwidth. Defensive consolidation should prioritize backward integration into vinyl acetate monomer supply and captive cellulose pulp sourcing to insulate margin structures from petrochemical volatility. Channel control investments in India's emerging Gujarat and Maharashtra formulation hubs reduce dependence on distributor intermediaries.
For New Entrants and Emerging Players: Build out enzymatic modification capabilities for starch and protein binders serving Northern European gypsum board and wallpaper paste applications where EPD and LEED disclosure requirements favor biocatalytic platforms. India's National Highway Authority procurement for self-leveling underlayments represents the most penetrable volume opportunity given BIS certification barriers filtering Western European imports. Go-to-market positioning should emphasize toll manufacturing partnerships with domestic Indian formulators seeking supply security.
For Investors and Strategic Acquirers: REACH substance evaluation milestones reshapes the acquisition landscape by stranding mid-scale emulsion polymer producers lacking dedicated regulatory affairs infrastructure. Long-term viability favors specialty chemical houses with pharmaceutical-grade certification capabilities and integrated petrochemical conglomerates with captive feedstock networks. Acquisition target archetypes include toll manufacturers with flexible polymerization capacity and regional distribution assets in underserved Indian and Southeast Asian markets. The signal to watch is ECHA's formaldehyde-releasing binder restriction timeline as an inflection indicator for bio-based substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive vinyl acetate production insulates margin compression from crude oil volatility in waterborne emulsion economics. |
| Pharmaceutical Excipient Grade Certification | USP-NF compliance creates supplier stickiness through multi-year qualification timelines and premium pricing power. |
| Regional Tolling Partnership Expansion | Asset-light capacity leasing in India reduces freight exposure from Western European redispersible powder clusters. |
| Enzymatic Modification Platform Development | Biocatalytic starch processing meets EPD disclosure requirements while displacing energy-intensive acid hydrolysis routes. |
| Digital Formulation Platform Deployment | AI-driven rheology modeling compresses R&D cycles for custom binder blends serving regional construction chemical formulators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at downstream construction chemical OEMs, distribution channel partners, and pharmaceutical formulation scientists; alongside secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and BIS certification registries. Bottom-up volume modeling triangulated against top-down macroeconomic indicators anchored the market sizing framework.
Forecast inputs considered grade tier stratification across excipient, technical, and industrial specifications; end-use industry segmentation spanning construction, pharmaceutical, food, and personal care applications; packaging format differentiation between powders, liquids, and granules; and regional production hub concentration in Germany, the United States, China, and India. CAGRs were derived through regression analysis of historical procurement patterns and forward projection of regulatory-driven substitution rates, incorporating monomer cost elasticity and infrastructure spending trajectories as binding agents market-specific variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or predatory pricing by integrated petrochemical conglomerates would shift outcomes beyond modeled ranges. Material shifts in REACH substance evaluation timelines, EPA residual monomer limit enforcement, or India's BIS certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cosmetic Grade Color Additives Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Global Metal Scavenging Agents Market
Additives
Conditioning Agent Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
North America Citric Acid Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Canada Anti-Caking Market
Additives
Global Slip Additives Market
Additives
Shortstop Inhibitor Market
Additives
Anti-Foaming Agent Market
Additives
Apocarotenal Market
Additives
Packaging Coating Additives Market
Additives
Adjustive Agents Market
Additives
North America Paints and Coatings Additives Market