
 Europe Pharmaceutical Plastic Packaging Market | 2026-2036
Europe Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Plastic Packaging Market Insights
Modular packaging configurations combining primary containers with integrated closure and desiccant systems is broadening buyer choice across dosage formats. Gerresheimer AG leverages its blow-molded bottle platform to serve high-volume oral solid demand. Amcor plc anchors multi-layer blister capacity for moisture-sensitive biologics. Berry Global differentiates through in-house resin compounding that tightens specification control for European pharma clients.
Europe pharmaceutical plastic packaging encompasses bottles, blisters, bags, and closures manufactured from polyethylene, polypropylene, PVC, or polystyrene via injection molding, blow molding, thermoforming, or extrusion, engineered to meet child-resistance, tamper-evidence, and barrier permeability standards for drug stability and patient safety. Blister packs lead unit volume due to unit-dose compliance advantages, while blow-molded bottles capture expanding margin pools in liquid and semi-solid formats. Polyethylene dominates material selection as formulators prioritize extractables-leachables profiles aligned with EMA quality guidelines.
EMA pharmacovigilance directives, REACH substance restrictions, and the EU Green Deal circularity targets collectively tighten material approval pathways and elevate documentation burdens for packaging converters. F-Gas Regulation phase-downs indirectly reshape blow-molding energy profiles as manufacturers retrofit heating systems. Stakeholders must monitor evolving MDR traceability extensions that may mandate packaging-level digital integration beyond current serialization requirements.
Market Dynamics
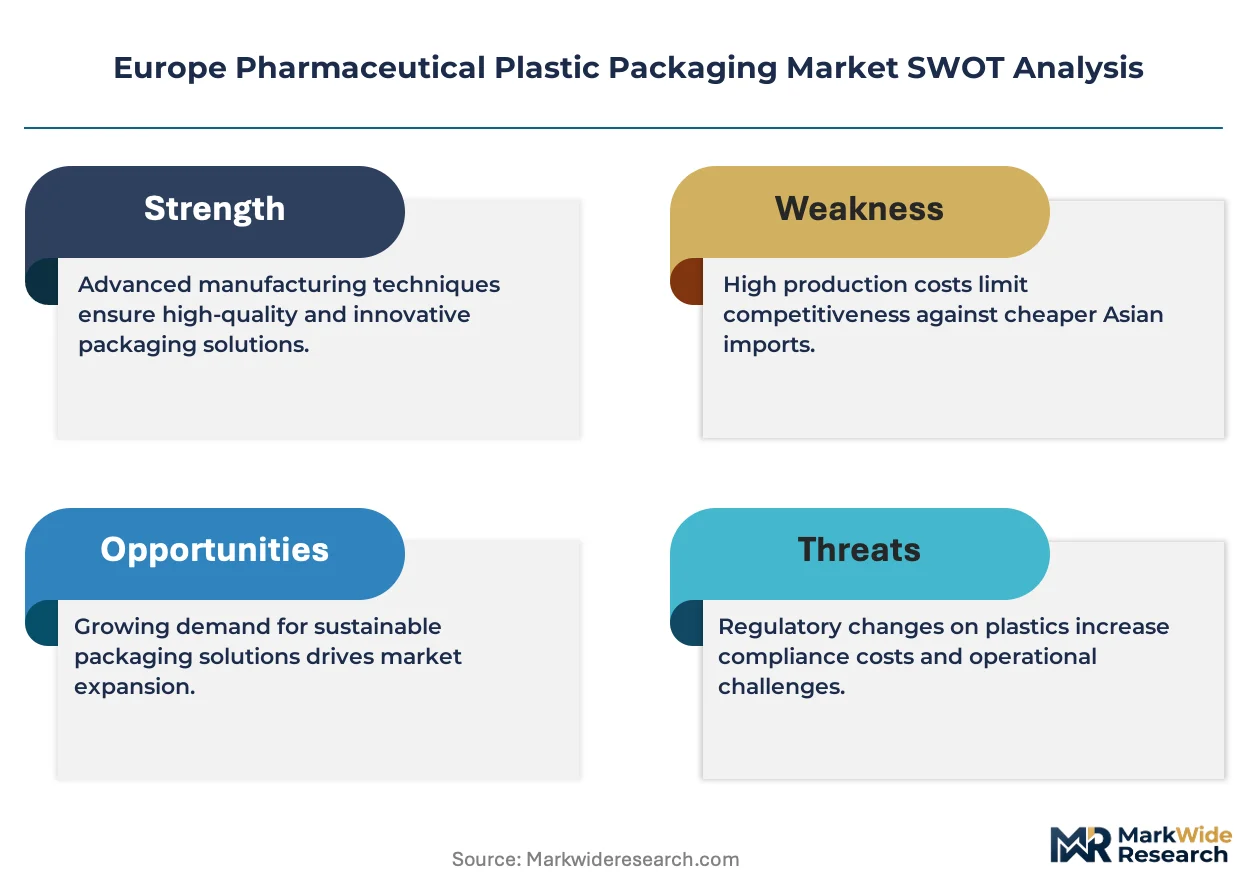
REACH substance restrictions and the EU Green Deal circularity targets are forcing packaging converters to abandon PVC in favor of polyethylene and polypropylene alternatives, reshaping raw material procurement patterns across the continent.
Growth Catalysts
- EMA serialization mandates:Tightening track-and-trace requirements for pharmaceuticals are driving contract manufacturers toward multi-layer barrier bottles with integrated coding surfaces.
- Biologics expansion:Moisture-sensitive biologic formulations are accelerating demand for high-barrier blister configurations and desiccant-integrated closures.
- German sterile filling concentration:High-volume parenteral production clusters in the Rhine-Main and Upper Bavaria regions are anchoring regional demand for blow-molded containers.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock costs fluctuate with European refinery utilization rates, compressing converter margins on fixed-price contracts.
- F-Gas Regulation phase-down:Blow-molding heating system retrofits require capital outlays that smaller converters struggle to finance without parent-company support.
- Glass substitution persistence:High-value parenterals and certain orphan drugs remain committed to borosilicate vials due to perceived stability advantages over cyclic olefin polymers.
Strategic Opportunities
- Central and Eastern Europe capacity gaps:Poland and the Czech Republic lack domestic sterile filling infrastructure, creating import substitution potential for regional packaging hubs.
- MDR traceability extensions:Anticipated packaging-level digital integration requirements beyond current serialization standards favor early movers on smart-label platforms.
- Monomaterial blister convergence:Combining barrier performance with single-polymer recyclability opens positioning for converters ahead of extended producer responsibility schemes.
Industry Challenges
- Extractables-leachables validation timelines:EMA quality guideline compliance requires 12-18 month stability studies that delay new material approvals.
- Multi-site quality system harmonization:Converters with dispersed European manufacturing footprints face audit complexity under divergent national competent authority interpretations.
- Serialization equipment integration:Legacy filling lines require mechanical and software retrofits that disrupt production schedules during validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Plastic Packaging Market |
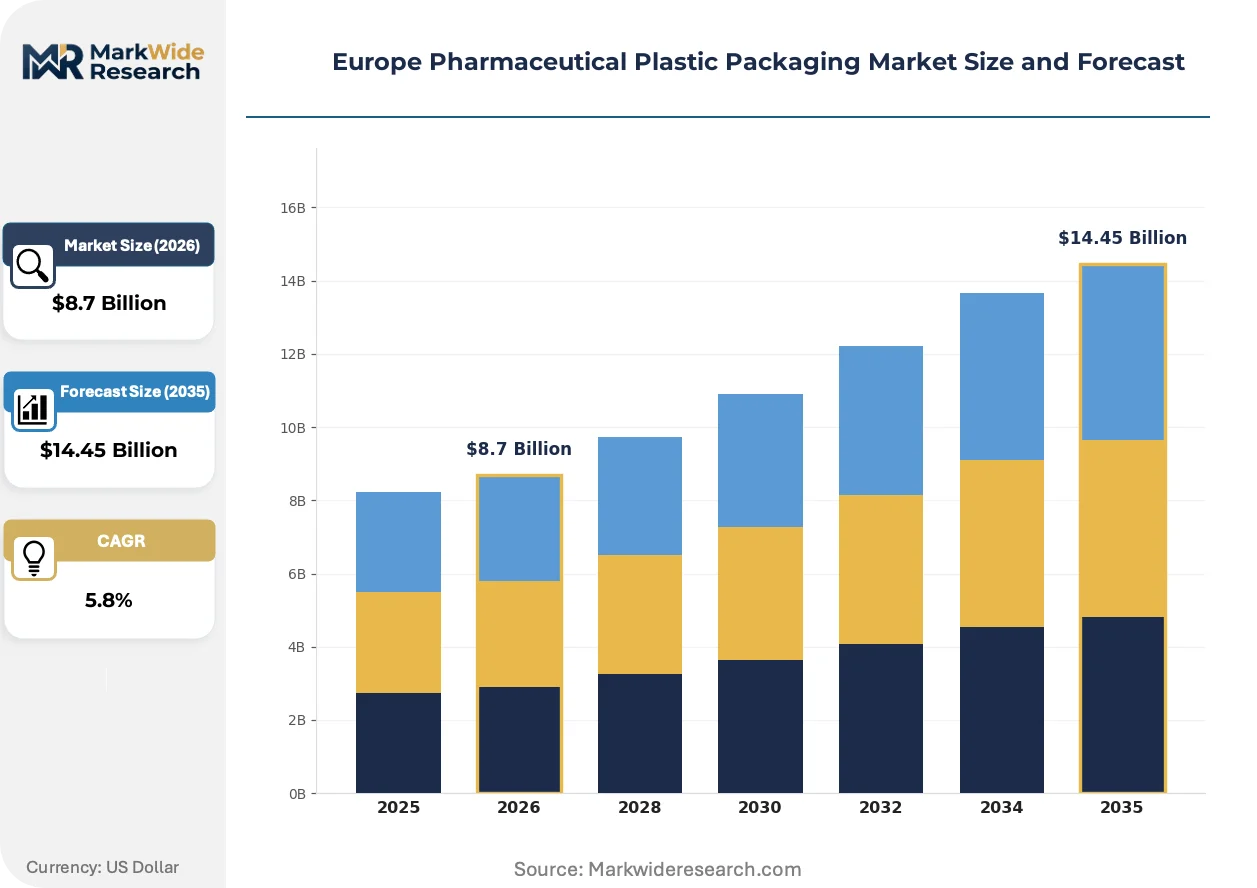
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Bags, Closures Material: Polyethylene, Polypropylene, PVC, Polystyrene End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Pharmacies Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | Gerresheimer AG, Amcor plc, Berry Global, AptarGroup, West Pharmaceutical Services, Schott AG, Alpla Group, Nolato AB, Origin Pharma Packaging, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Plastic Packaging Market Trends and Innovations
Digital integration across primary packaging is compressing validation timelines while circular material specifications are redefining supplier qualification criteria. These shifts are reshaping how converters allocate R&D resources and structure customer partnerships.
Radio-frequency identification (RFID) inlays embedded within blister lidding foil are integrating with hospital pharmacy inventory management systems to reduce dispensing errors and enable cold-chain verification. Large hospital networks in the Netherlands and Scandinavia are piloting these configurations for high-value oncology therapies. The technology is integrating track-and-trace functionality directly into unit-dose formats, bypassing secondary packaging serialization steps.
The EU Green Deal's packaging and packaging waste regulation revision is mandating recycled content minimums for plastic pharmaceutical containers by the end of the decade. ECHA is simultaneously tightening substance restrictions under REACH Annex XVII for additives used in legacy PVC formulations. Blow-molded bottle segments serving oral solids are responding fastest, with converters accelerating post-consumer polyethylene sourcing agreements.
Consolidated buying by European contract manufacturing organizations is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Mid-sized converters in Italy and Spain are losing preferred vendor status as purchasing concentrates among three pan-European procurement platforms. German and Swiss innovator pharma companies remain the exception, maintaining direct supplier relationships for customized barrier specifications.
Europe Pharmaceutical Plastic Packaging Market Segmentation
Segmentation in Europe pharmaceutical plastic packaging reveals how material specifications, manufacturing technology, and customer procurement power intersect to determine margin capture. Understanding these divides exposes where converters can defend pricing and where commoditization pressures concentrate.
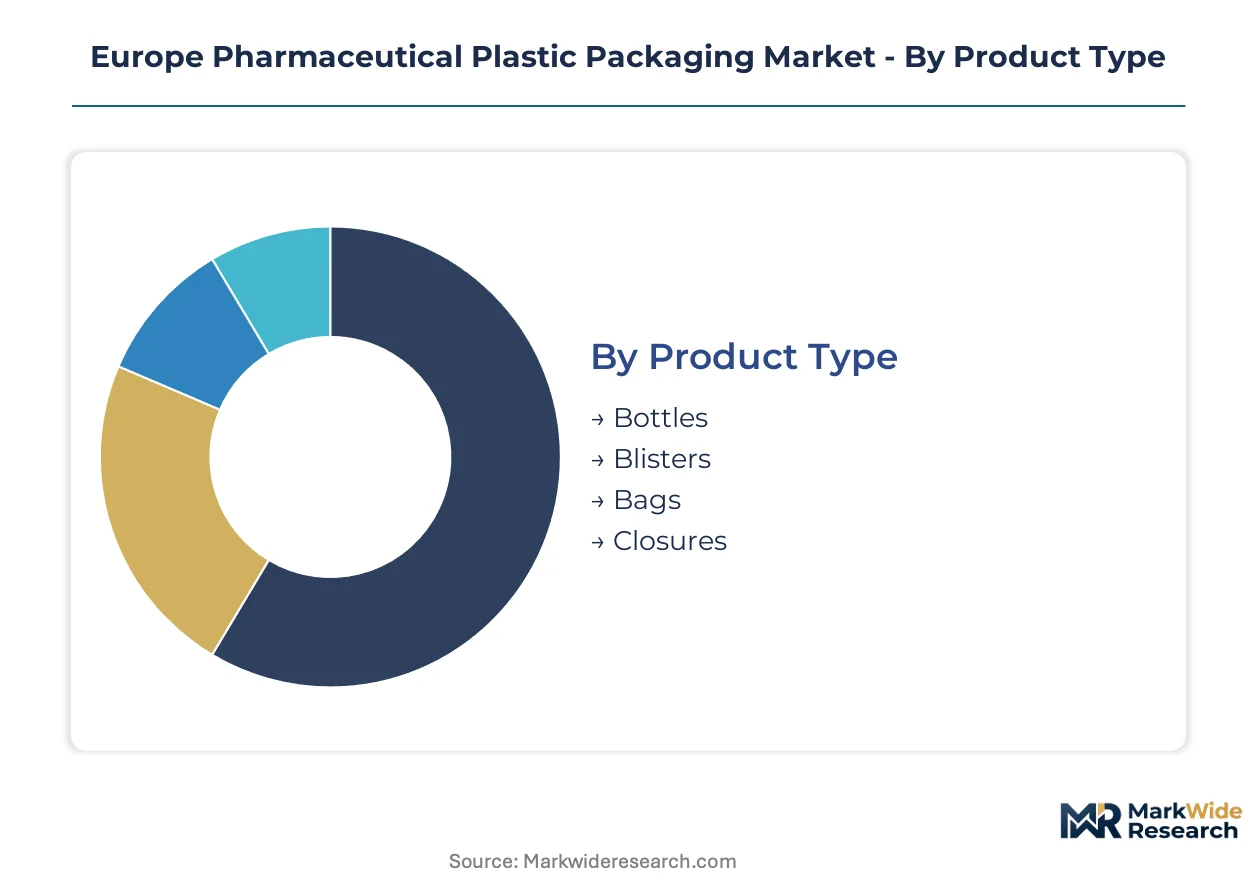
Product Type:
Volume leadership sits with high-throughput formats serving oral solids, while premium margins concentrate in barrier-intensive configurations for moisture-sensitive biologics.
- Bottles:Blow-molded containers in HDPE and PP dominate oral solid and liquid dispensing across German and French manufacturing clusters. Contract manufacturers in the Rhine-Main region are scaling procurement of multi-layer barrier bottles as EMA serialization mandates tighten track-and-trace requirements.
- Blisters:Thermoformed PVC and PP lidding assemblies capture unit-dose compliance advantages in cardiovascular and CNS therapies. Demand for high-barrier cold-form foil alternatives is climbing fastest in Swiss and Dutch hospital pharmacy networks managing high-value oncology inventories.
- Bags:IV solution and parenteral nutrition containers in multilayer films serve sterile filling operations concentrated in Upper Bavaria and Baden-Württemberg.
- Closures:Child-resistant and tamper-evident designs in PP and HDPE integrate desiccant chambers for humidity-sensitive formulations.
Today's leader: Bottles. Tomorrow's challenger: Blisters.
Material:
REACH substance restrictions and EU Green Deal circularity targets are forcing rapid substitution away from legacy chemistries toward recyclability-aligned alternatives.
- Polyethylene:HDPE and LDPE grades dominate oral solid bottles due to favorable extractables-leachables profiles aligned with EMA quality guidelines. German converters are accelerating post-consumer PE sourcing agreements ahead of packaging waste regulation recycled content mandates.
- Polypropylene:Random and impact copolymers serve closures and sterile containers requiring autoclave stability. The material is gaining share fastest in blow-molded segments as converters seek monomaterial solutions compatible with extended producer responsibility schemes.
- PVC:Legacy blister and IV bag applications face phasedown pressure from ECHA Annex XVII additive restrictions and healthcare sector sustainability procurement policies.
- Polystyrene:Clear HIPS and GPPS retain niche use in diagnostic kit components and visual-inspection vial trays.
Polyethylene commands current volume. Polypropylene is climbing the fastest as circularity requirements harden.
End User:
Procurement concentration among pan-European contract manufacturing platforms is compressing supplier margins while direct pharma relationships preserve customization premiums.
- Pharmaceutical Companies:Innovator firms in Switzerland and Germany maintain direct supplier relationships for customized barrier specifications, insulating preferred converters from price-driven procurement platforms.
- Contract Manufacturers:Consolidated buying by European CMOs is unbundling technical service from material supply contracts and squeezing mid-sized Italian and Spanish converters from preferred vendor lists.
- Hospitals:Large Netherlands and Scandinavia networks are piloting RFID-embedded blister configurations for inventory management and cold-chain verification.
- Pharmacies:Retail dispensing demand concentrates in standard HDPE bottles and compliance-prompting blister cards.
Contract Manufacturers drive volume concentration. Pharmaceutical Companies sustain margin pools.
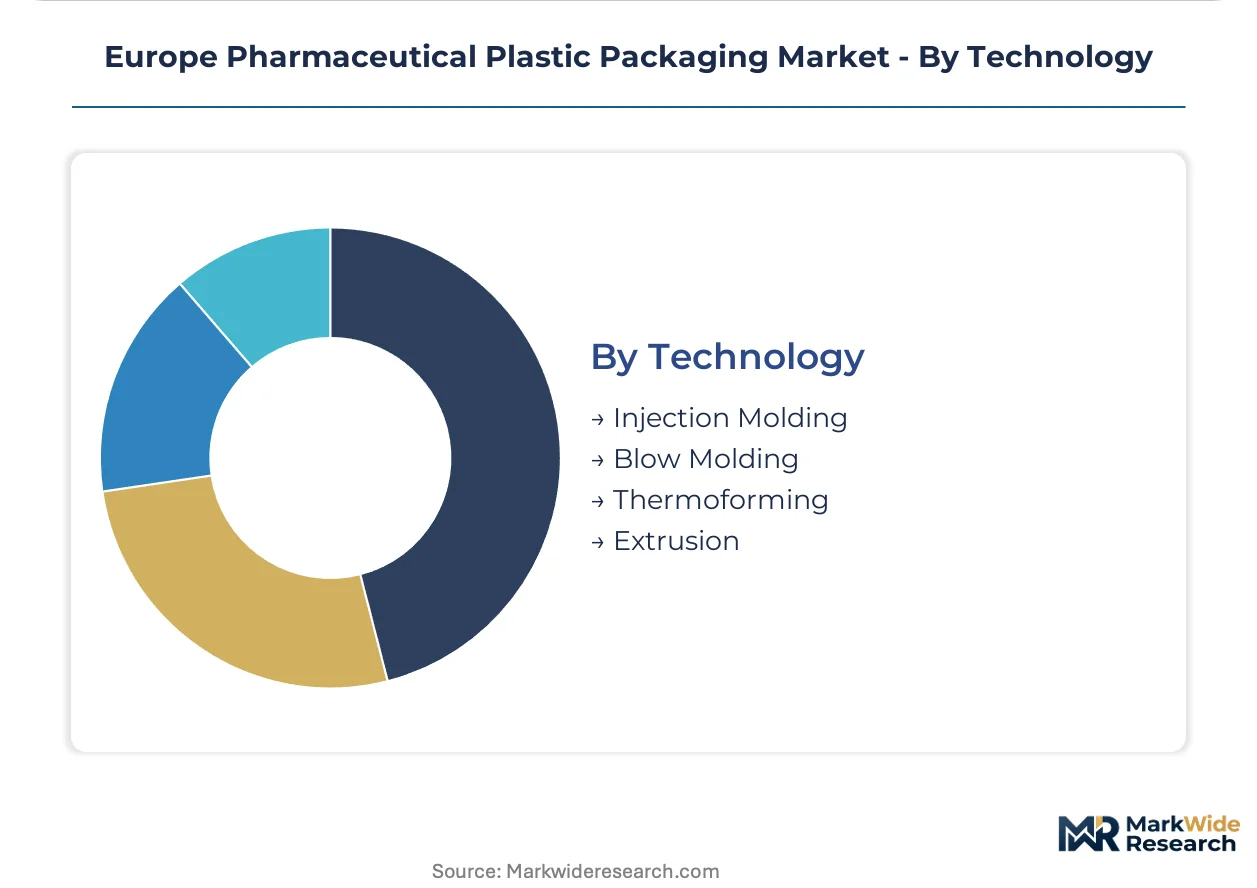
Technology:
Energy-intensive heating processes face retrofit pressure from F-Gas Regulation phase-downs, favoring capital-rich converters with parent-company backing.
- Injection Molding:Precision closure and cap production in multi-cavity tools serves high-volume oral solid formats. German and Swiss equipment installations lead integration of all-electric drives reducing heating energy intensity.
- Blow Molding:Extrusion and injection blow processes dominate bottle production for liquid and semi-solid pharmaceuticals. F-Gas Regulation compliance is forcing heating system retrofits that smaller converters struggle to finance.
- Thermoforming:Roll-fed and cut-sheet processes produce blister cavities and trays at highest unit velocities across Spanish and Italian converter bases.
- Extrusion:Sheet and film extrusion supplies upstream feedstock for thermoforming and multilayer bag constructions.
Blow Molding anchors current capacity. Injection Molding is expanding most quickly through all-electric technology transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical plastic packaging in Europe traces its industrial lineage to post-war German chemical engineering clusters, where blow-molding expertise developed alongside the Rhine-Main pharmaceutical manufacturing corridor.
Germany
Rhine-Main sterile filling operations and Upper Bavaria parenteral nutrition production anchor continental demand for multi-layer barrier bottles. EMA serialization mandates tighten track-and-trace requirements, accelerating procurement of integrated coding surfaces. Gerresheimer AG maintains high-volume blow-molded capacity serving oral solid and liquid formats across the region.
Switzerland
Basel-area biologics manufacturing and Zurich oncology formulation clusters drive premium demand for high-barrier blister configurations. Swissmedic pharmacovigilance standards exceed baseline EMA requirements, elevating documentation burdens for packaging converters. Hospital pharmacy networks pilot RFID-embedded lidding foil for cold-chain verification of high-value therapies.
France
Paris-Saclay biotech incubation and Lyon pharmaceutical manufacturing sustain demand for child-resistant closures and desiccant-integrated systems. ANSM interprets REACH substance restrictions with particular stringency on legacy PVC additives. Contract manufacturing concentration in the Grand Est region pressures mid-sized converters on pricing.
Netherlands
Rotterdam logistics hubs and Leiden life science clusters create import substitution demand for regional sterile filling infrastructure. Large hospital networks pilot digital inventory management integrating RFID-enabled blister packs. ECHA headquarters proximity accelerates converter compliance timelines for evolving Annex XVII restrictions.
Italy
Lombard pharmaceutical manufacturing and Emilia-Romagna packaging machinery production sustain thermoforming capacity for unit-dose cardiovascular therapies. Mid-sized Italian converters face procurement consolidation as pan-European CMO platforms concentrate buying power. Piedmont-based resin compounding operations supply specification-controlled materials for EMA-aligned extractables-leachables profiles.
Europe Pharmaceutical Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with parent-company balance sheet capacity. German and Swiss-headquartered players anchor premium positioning through direct innovator pharma relationships, while mid-tier converters face margin compression from consolidated contract manufacturing procurement. Two strategic archetypes dominate: integrated resin-to-container specialists and multi-material platform operators. M&A activity concentrates on acquiring sterile filling-adjacent capabilities, while geographic expansion targets Central and Eastern European capacity gaps.
Among Germany-based diversified packaging groups, Gerresheimer AG and Berry Global occupy positions exemplifying integrated platform scale. Amcor plc represents the multi-regional conglomerate archetype with European pharmaceutical-specific capacity. These three entities anchor the competitive landscape as converters navigate REACH compliance and EU Green Deal circularity mandates.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Amcor plc |
| Berry Global |
| AptarGroup |
| West Pharmaceutical Services |
| Schott AG |
| Alpla Group |
| Nolato AB |
| Origin Pharma Packaging |
| Others |
Pricing and Supply Chain Analysis
EMA serialization mandates and consolidated procurement by pan-European contract manufacturing platforms are compressing converter margins and forcing supply-side consolidation among resin compounders and blow-molding specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates customized barrier specifications for Swiss innovator pharma from commodity HDPE bottles serving retail pharmacies. Price differentiation hinges on EMA extractables-leachables certification grade and volume scale commitments. Cost compression in standard-tier oral solid bottles is intensifying because German CMOs are unbundling technical service from material contracts. Retail pharmacy procurement shows highest price sensitivity, while direct relationships with Basel-area biologics manufacturers preserve premium pricing.
Supply Chain Analysis
Post-consumer polyethylene sourcing agreements and monomaterial blister recyclability programs are creating reverse-logistics partnerships between German converters and Dutch waste management operators. Raw material supply concentrates in Germany, Belgium, and the Netherlands, with resin compounding anchored in Piedmont and the Rhine-Ruhr corridor. The supply chain draws from ethylene and propylene feedstocks tied to European refinery utilization rates, exposing converters to commodity price volatility. Distribution runs through Rotterdam logistics hubs and Leiden life science clusters serving sterile filling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe pharmaceutical plastic packaging market functions as a stable compounder, with regulatory compliance mandates creating durable demand for certified barrier configurations.
For Market Incumbents: Acquire sterile filling-adjacent capabilities in Central and Eastern Europe to capture import substitution demand from Polish and Czech pharmaceutical manufacturing. Deepen backward integration into post-consumer polyethylene sourcing to secure recycled content supply ahead of EU Green Deal mandates. Consolidate quality systems across dispersed manufacturing footprints to reduce audit complexity under divergent national competent authority interpretations. For New Entrants and Emerging Players: Enter via RFID-enabled blister configurations for Netherlands and Scandinavia hospital pharmacy networks piloting digital inventory management. Target the Central European capacity gap in sterile filling infrastructure as the most penetrable white space. Pursue direct supplier relationships with Swiss and German innovator pharma companies as the go-to-market angle that bypasses consolidated CMO procurement platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized Italian and Spanish converters possessing EMA-aligned extractables-leachables profiles but lacking parent-company balance sheet capacity for F-Gas Regulation heating retrofits. Long-term viability favors platforms with integrated resin-to-container capabilities and established post-consumer sourcing agreements. Monitor MDR traceability extension announcements for inflection signals on smart-label platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | In-house specification control tightens EMA extractables-leachables compliance timelines for German pharma clients. |
| Post-Consumer PE Sourcing Agreements | Recycled content supply security positions converters ahead of EU Green Deal packaging waste regulation mandates. |
| RFID-Enabled Blister Platform Development | Smart-label integration captures Netherlands and Scandinavia hospital pharmacy pilot demand for cold-chain verification. |
| Sterile Filling Capacity Expansion | Central and Eastern European facility investments address Polish and Czech import substitution gaps. |
| All-Electric Blow Molding Retrofit | F-Gas Regulation compliance reduces heating energy intensity while parent-company financing excludes smaller competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging development directors, regulatory affairs leads at EMA-notified bodies, hospital procurement managers in Dutch and Scandinavian networks, and resin compounding technical directors with secondary validation against ECHA Annex XVII restriction updates, EU Green Deal packaging regulation drafts, and customs data on polyethylene and polypropylene trade flows. Bottom-up capacity assessments at converter facilities across Germany, Switzerland, and Italy were triangulated against top-down demand modeling from pharmaceutical manufacturing cluster outputs.
Segment-weighting approaches applied differential growth assumptions across material types, product formats, and end-user procurement channels throughout the forecast period. The analytical framework modeled dosage form requirements, barrier performance tiers, and regional regulatory cluster variations. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs included EMA serialization mandate implementation timelines and F-Gas Regulation phase-down schedules affecting blow-molding energy profiles.
Inputs from EMA guidance documents and ECHA restriction proposals were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term volume projections. Practitioners should monitor MDR traceability extension regulatory drafts and recycled content mandate enforcement schedules for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market