
 Europe Pharmaceutical Plastic Bottles Market | 2026-2036
Europe Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Plastic Bottles Market Insights
German blow-molding capacity for pharmaceutical-grade polymers is realigning toward barrier-enhanced multilayer structures. Amcor Group GmbH leverages its European extrusion network to sustain high-volume supply contracts with major generics producers. Gerresheimer AG anchors specialized glass-plastic hybrid containment for biologics. Berry Global Inc. competes on scale across HDPE container lines for over-the-counter portfolios.
Europe pharmaceutical plastic bottles are blow-molded or injection-stretched containers, typically manufactured from polyethylene terephthalate, high-density polyethylene, or polypropylene, with wall thicknesses calibrated for moisture vapor transmission rates below specified thresholds to protect drug stability. These vessels serve as primary packaging for oral liquids, solids, and topical formulations across regulated supply chains. Dropper bottles command premium positioning in ophthalmic and pediatric segments where dosing precision determines prescribing preferences. High-density polyethylene dominates container bottles for tablet and capsule formats due to its cost-position and chemical inertness. Child-resistant closures represent the fastest-growing closure category as poison-prevention mandates tighten across EU member states.
EMA guidelines on plastic immediate packaging materials, combined with REACH substance restrictions and the EU Medical Device Regulation's extended scope, compel reformulation of additives and colorants in pharmaceutical-grade resins. Germany's national pharmaceutical regulator enforces supplementary stability testing protocols that exceed baseline EU requirements. Stakeholders must monitor evolving EFSA opinions on recycled content authorization for food-contact-grade polymers repurposed into pharmaceutical applications.
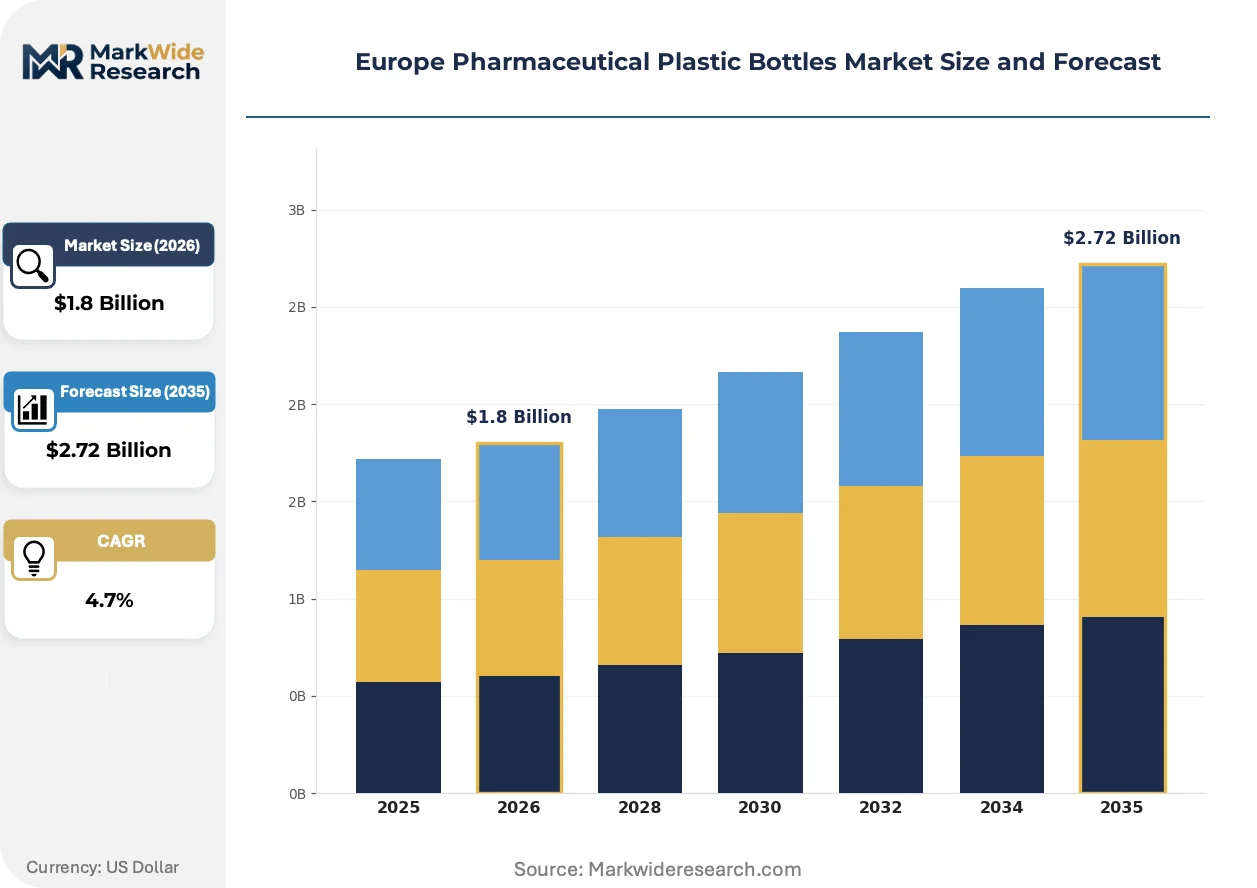
Market Dynamics
Barrier-enhanced multilayer blow-molding is absorbing capital from conventional single-layer HDPE lines as chronic disease volumes and moisture sensitivity requirements tighten across European generics supply chains.
Growth Catalysts
- EMA plastic packaging guidance updates:The 2023 revisions to immediate packaging materials guidelines are compelling reformulation investments that expand the addressable market for compliant resin grades and certified converters.
- Germany's supplementary stability protocols:The national pharmaceutical regulator's extended testing mandates for container-closure systems are creating premium positioning for manufacturers with in-house validation capabilities.
- Child-resistant closure mandates:Poison-prevention regulations tightening across EU member states are accelerating specification upgrades in tablet and capsule packaging lines.
Market Restraints
- Pharmaceutical-grade resin supply concentration:European polymer supply chains for medical-use HDPE and PET remain concentrated among a limited set of certified compounders in Germany and the Netherlands.
- REACH substance restriction timelines:ECHA's evolving authorization lists for additives and colorants are compressing formulation windows and forcing premature obsolescence of established resin grades.
- Glass-primary containment substitution:Biologics manufacturers in Switzerland and Germany continue specifying borosilicate glass for high-value parenterals, capping plastic penetration in the fastest-growing therapy segment.
Strategic Opportunities
- Recycled content authorization pathways:EFSA opinions on food-contact-grade polymer repurposing for pharmaceutical applications are opening regulatory frameworks for circular material integration.
- Ophthalmic dropper bottle specialization:Dosing precision requirements in pediatric and glaucoma segments are creating premium niches for calibrated multilayer structures with integrated tamper evidence.
- Central and Eastern European manufacturing expansion:Underdeveloped blow-molding capacity in Poland and the Czech Republic offers greenfield locations for proximity to emerging generics production clusters.
Industry Challenges
- Validation engineer scarcity:European pharmaceutical packaging converters face acute shortages of professionals capable of executing EMA-compliant stability protocols and extractables-leachables studies.
- Legacy line retrofit complexity:Multilayer barrier structures require coextrusion equipment upgrades that disrupt validated production schedules and trigger requalification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Plastic Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Ointment Jars, Container Bottles, Rigid Bottles Material: Polyethylene Terephthalate, Polyvinyl Chloride, High-Density Polyethylene, Polypropylene Closure Type: Screw Caps, Child-Resistant Caps, Droppers, Tamper-Evident Caps End User: Pharmaceutical Companies, Hospitals, Retail Pharmacies, Contract Manufacturers |
| Companies Covered | ALPLA Werke Alwin Lehner GmbH & Co KG, AptarGroup Inc., Amcor Group GmbH, Comar LLC, Plastipak Holdings Inc., Gerresheimer AG, Pretium Packaging, Frapak Packaging, Berry Global Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Plastic Bottles Market Trends and Innovations
Active barrier technologies and circular material pathways are restructuring competitive advantage in European pharmaceutical primary packaging, separating converters with integrated material science capabilities from commodity blow-molders.
Coextruded multilayer bottles with ethylene vinyl alcohol interlayers are absorbing technical investment from generics manufacturers seeking 24-month shelf-life extension for hygroscopic solid dosages. German and Swiss contract packagers are specifying these structures for central nervous system and cardiovascular portfolios where moisture ingress compromises API stability. The technology is absorbing market share from desiccant-capped single-layer alternatives by integrating barrier function into the container wall itself.
REACH authorization requirements for recycled content are forcing additive package redesigns across European resin compounders. The regulation is compressing formulation flexibility as ECHA scrutinizes plasticizers and stabilizers in post-consumer feedstocks. Oral solid dosage packaging lines in the Rhine-Main cluster are responding by qualifying virgin-equivalent mechanical recycling streams ahead of anticipated EFSA pharmaceutical-grade approvals.
Hospital and pharmacy procurement consolidation is compressing supplier rosters across Northern Europe. Buying groups in Germany and the Netherlands are consolidating annual bottle contracts into multi-year framework agreements with technical audit requirements. This concentration is most visible in the over-the-counter segment, where retail pharmacy chains are specifying direct-to-line supply with serialized aggregation to eliminate distribution center handling.
Europe Pharmaceutical Plastic Bottles Market Segmentation
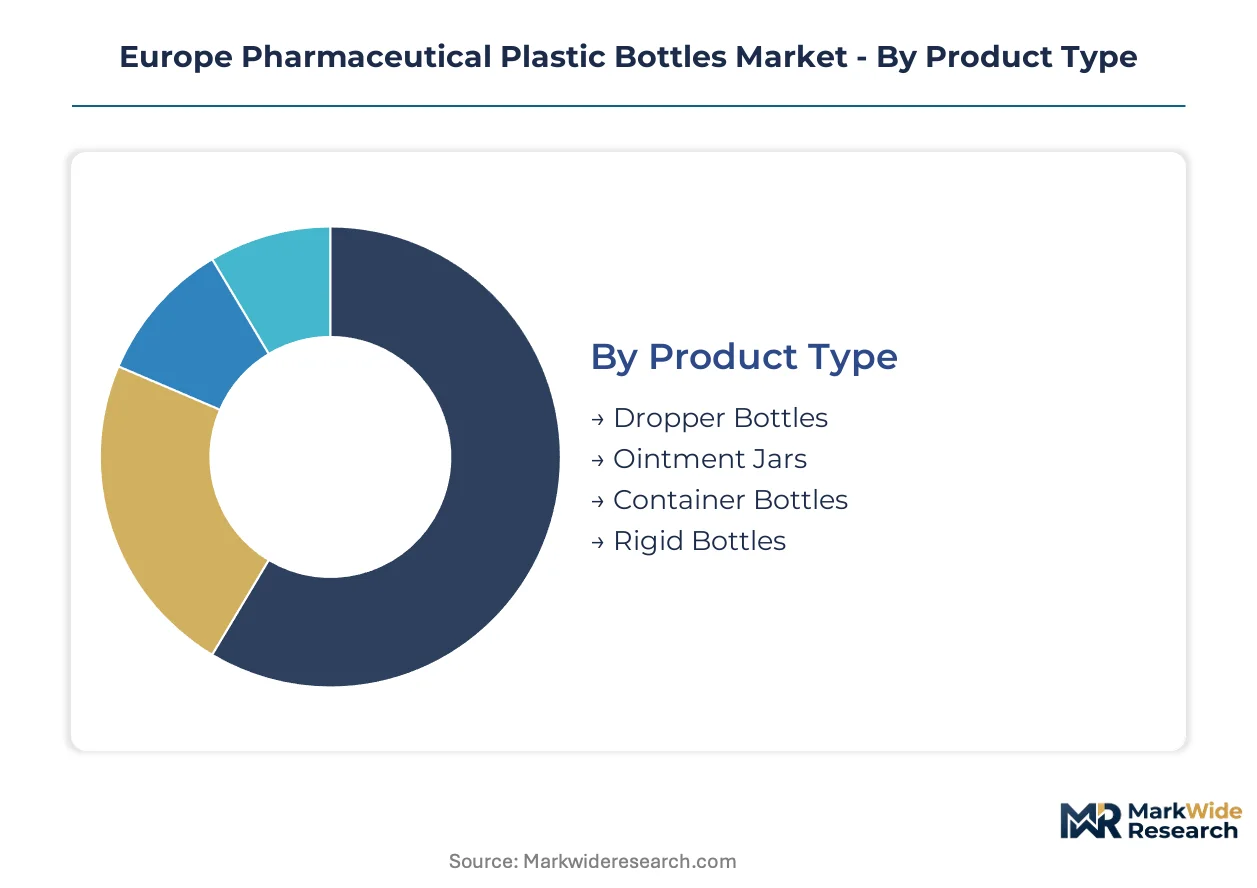
Pharmaceutical plastic bottle procurement in Europe stratifies across four distinct decision hierarchies. Product type determines barrier requirements and manufacturing process. Material selection triggers REACH compliance pathways and stability validation protocols. Closure specifications respond to poison-prevention mandates. End-user category dictates volume scale and technical audit intensity.
Product Type:
Buyers prioritize barrier performance and dosing precision when selecting container formats for chronic disease therapies.
- Dropper Bottles:Calibrated multilayer structures with integrated pipette assemblies serve ophthalmic and pediatric liquid formulations. Demand clusters in Switzerland's Basel biopharma hub where glaucoma and pediatric prescribing protocols require exact volume dispensing. EMA extractables-leachables guidance drives specification of medical-grade elastomer bulbs over conventional rubber.
- Container Bottles:High-density polyethylene dominates tablet and capsule containment across European generics supply chains. Germany's Rhine-Main pharmaceutical cluster absorbs the highest volumes for cardiovascular and central nervous system portfolios where moisture vapor transmission rates below specified thresholds protect API stability during 24-month shelf lives.
- Ointment Jars:Wide-mouth polypropylene vessels accommodate semisolid topical formulations. Pharmaceutical companies in the Netherlands specify these for dermatology portfolios requiring finger-accessible dosing.
- Rigid Bottles:Thick-walled injection-molded containers serve effervescent and hygroscopic solid dosages. Poland's emerging generics manufacturers are qualifying these structures for central European distribution.
Volume sits with container bottles; growth tilts toward dropper bottles.
Material:
Resin selection in Europe follows REACH authorization status and EFSA recycling pathway approvals rather than commodity pricing.
- High-Density Polyethylene:Blow-molded HDPE delivers chemical inertness and cost-position for high-volume oral solid dosage lines. German compounders dominate pharmaceutical-grade supply, though ECHA's evolving additive restriction lists compress formulation flexibility for stabilizers and colorants.
- Polyethylene Terephthalate:Injection-stretch blow-molded PET offers clarity and oxygen barrier for liquid formulations. Swiss contract packagers specify these for oral solution portfolios where visual inspection of contents supports compliance protocols.
- Polypropylene:Random and block copolymer grades serve ointment jars and closures requiring autoclavable resilience. Italian converters specialize in nucleated PP for dropper bottle collars.
- Polyvinyl Chloride:Plasticized PVC retains niche positioning for certain topical applications despite REACH scrutiny of phthalate plasticizers. Spanish manufacturers maintain limited qualification for established dermatology lines.
HDPE commands current volume share; PET climbs the fastest on barrier-enhanced multilayer adoption.
Closure Type:
Regulatory mandates on child safety and supply chain integrity now override cost considerations in closure procurement.
- Child-Resistant Caps:Push-and-turn mechanisms with senior-friendly torque specifications serve tablet and capsule bottles. Germany's poison-prevention regulations mandate these across all pediatric-accessible packaging, driving specification upgrades in retail pharmacy supply chains.
- Tamper-Evident Caps:Ring-break or shrink-band designs provide visual integrity assurance for over-the-counter portfolios. Dutch buying groups require these for direct-to-line supply contracts with serialized aggregation.
- Screw Caps:Standard continuous-thread closures retain volume positioning for institutional and hospital dispensing where child-resistance is managed through storage protocols rather than primary packaging.
- Droppers:Calibrated glass or polyethylene pipettes integrate with bottle neck finishes for ophthalmic applications. Precision molding capabilities concentrate among specialized German and Swiss converters.
Child-resistant caps gain share fastest; screw caps retain institutional volume.
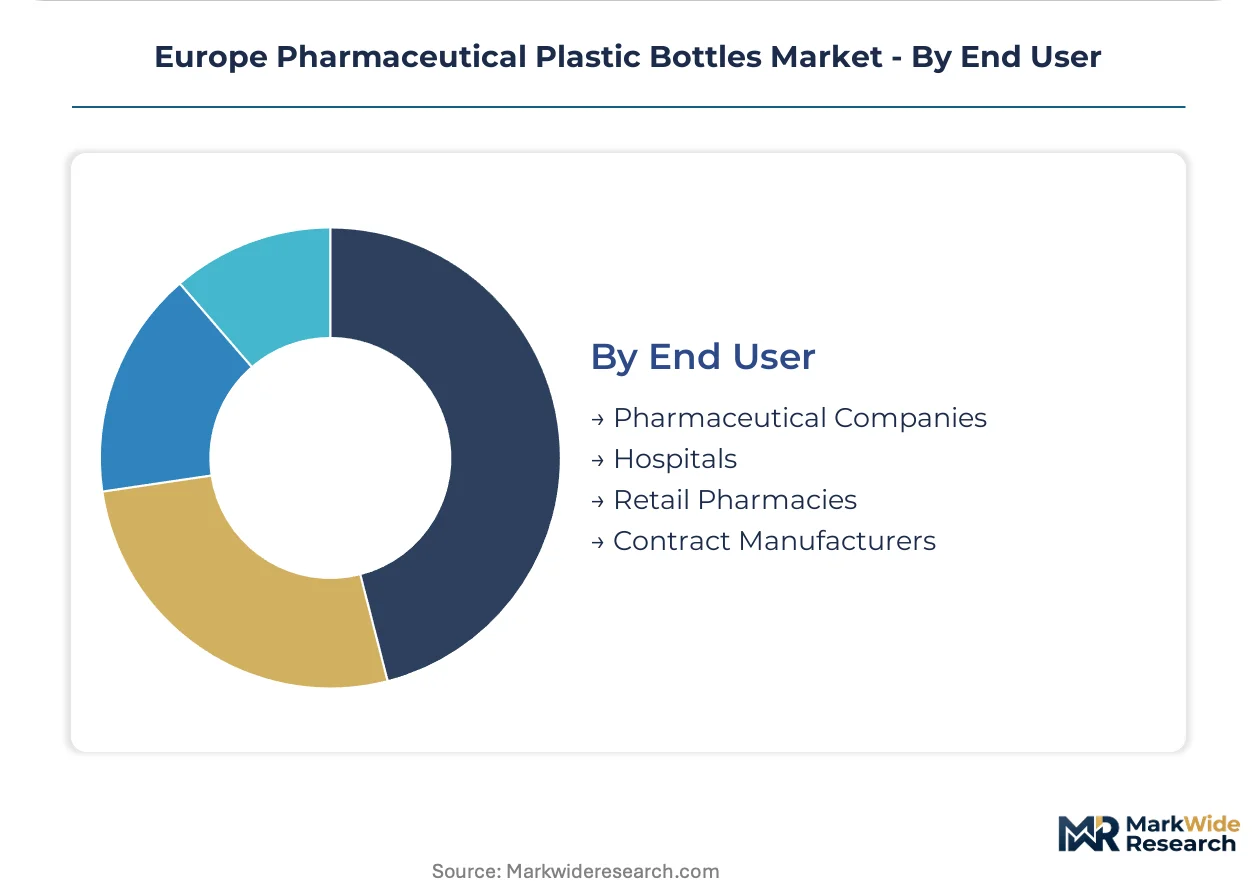
End User:
Procurement scale and technical validation requirements separate end-user categories across Northern and Central Europe.
- Pharmaceutical Companies:Integrated manufacturers in Germany and Switzerland specify multilayer barrier structures with in-house stability validation. These buyers drive coextrusion technology adoption through multi-year framework agreements requiring technical audits.
- Contract Manufacturers:European contract packagers absorb flexible volume across multiple client portfolios. Poland and Czech Republic locations are expanding blow-molding capacity to serve emerging generics production clusters with proximity advantages.
- Retail Pharmacies:Consolidated buying groups in the Netherlands and Germany negotiate direct-to-line supply with serialized aggregation requirements. These specifications eliminate distribution center handling for over-the-counter portfolios.
- Hospitals:Institutional procurement in France and Italy prioritizes unit-dose and compliance-prompting formats over conventional bulk bottles. Volume per SKU runs lower but specification complexity remains high.
Pharmaceutical companies anchor volume; contract manufacturers represent the steepest expansion trajectory on Central European capacity buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polymer compounders in the Rhine-Main corridor supply the certified HDPE and PET resins that anchor European pharmaceutical packaging manufacturing. The region's blow-molding capacity concentrates around regulatory validation expertise and multilayer coextrusion infrastructure.
Germany
The Rhine-Main pharmaceutical cluster absorbs the highest volumes of barrier-enhanced bottles for cardiovascular and central nervous system generics. Germany's national pharmaceutical regulator enforces supplementary stability testing protocols that exceed baseline EMA requirements. Frankfurt-area converters are retrofitting single-layer HDPE lines toward ethylene vinyl alcohol interlayer structures.
Switzerland
Basel's biopharma hub drives demand for calibrated dropper bottles in ophthalmic and pediatric applications. Swissmedic maintains stringent extractables-leachables guidance that shapes elastomer bulb specifications. Precision molding capabilities concentrate among specialized converters serving glaucoma therapy portfolios.
Netherlands
Dutch buying groups consolidate annual bottle contracts into multi-year framework agreements with technical audit requirements. ECHA's REACH authorization timelines compress formulation windows for additives in post-consumer feedstocks. Rotterdam-area packagers are qualifying virgin-equivalent mechanical recycling streams ahead of anticipated EFSA pharmaceutical-grade approvals.
Poland
Emerging generics manufacturers in Central Europe are qualifying rigid thick-walled containers for regional distribution. The country's national pharmaceutical regulator aligns with EMA guidelines while offering faster qualification pathways for established formats. Warsaw and Łódź locations are expanding blow-molding capacity to serve proximity advantages.
France
Hospital procurement in the Île-de-France region prioritizes unit-dose and compliance-prompting formats over conventional bulk bottles. ANSM enforces poison-prevention mandates that accelerate child-resistant closure specifications. Lyon-area contract packagers absorb flexible volume across multiple client portfolios with lower technical audit intensity than German counterparts.
Europe Pharmaceutical Plastic Bottles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barrier technologies and circular material pathways. The vendor base stratifies across three archetypes: integrated packaging conglomerates with European extrusion networks, specialized pharmaceutical converters with in-house validation capabilities, and regional blow-molders competing on scale for over-the-counter portfolios. Consolidation pressure intensifies through multi-year framework agreements with technical audit requirements. Capacity expansion and backward integration into certified resin sourcing represent the dominant competitive moves.
Within the integrated packaging tier, Amcor Group GmbH and Berry Global Inc. represent archetypes of scale-driven supply consolidation. Gerresheimer AG anchors specialized positioning at the premium end. These three exemplify how geographic footprint and validation infrastructure separate winners from commodity competitors in a market where procurement concentration favors suppliers with multi-country extrusion networks and EMA-compliant stability protocols.
| Leading Market Players |
|---|
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| AptarGroup Inc. |
| Amcor Group GmbH |
| Comar LLC |
| Plastipak Holdings Inc. |
| Gerresheimer AG |
| Pretium Packaging |
| Frapak Packaging |
| Berry Global Inc. |
| Others |
Pricing and Supply Chain Analysis
European polymer price indices for pharmaceutical-grade HDPE and PET cascade through converter pricing tiers, compressing margins for single-layer blow-molders while multilayer specialists capture stability-testing premiums. German resin compounders transmit ECHA authorization costs downstream, forcing three-tier pricing stratification across certified, standard, and unvalidated supply tiers.
Pricing Analysis
Validation service bundling separates premium converters from commodity suppliers, with EMA-compliant stability protocols and extractables-leachables studies packaged into multiyear framework agreements. Price differentiation hinges on certification grade and geographic delivery cost, with Rhine-Main cluster proximity commanding logistics premiums. Cost compression in standard HDPE lines is intensifying because REACH additive reformulation forces premature equipment obsolescence. Retail pharmacy buying groups exhibit highest price sensitivity; integrated pharmaceutical manufacturers in Switzerland and Germany show lowest sensitivity due to therapy-value protection requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Frankfurt, and Basel operate hub-and-spoke patterns for just-in-line pharmaceutical manufacturing. Supply concentrates in Germany, the Netherlands, and Switzerland for certified resin compounding and precision blow-molding. Raw material dependencies center on ethylene and propylene feedstocks from North Sea crackers, plus ethylene vinyl alcohol barrier resins from Japanese and European specialty polymer producers. Single-source vulnerability runs through pharmaceutical-grade HDPE compounders in the Rhine-Main corridor. Distribution runs through direct-to-line supply contracts with serialized aggregation, eliminating traditional wholesaler tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of EMA-validated blow-molding capacity props pricing power for incumbent converters, with multilayer coextrusion equipment lead times extending qualification bottlenecks.
For Market Incumbents: Lock in multi-year framework agreements with German and Swiss pharmaceutical companies before Central European capacity expansion matures. Prioritize backward integration into certified resin sourcing to offset REACH-driven additive cost volatility. Defend against emerging Polish and Czech blow-molders through technical audit intensity that new entrants cannot replicate. For New Entrants and Emerging Players: The premium-to-economy price gap in child-resistant closure systems offers white-space entry for specialized molders with senior-friendly torque engineering. Target Poland's emerging generics cluster with rigid thick-walled containers for regional distribution. Pursue toll-manufacturing arrangements with established compounders to bypass resin qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with dormant EMA validation credentials in Benelux geographies. Five-to-ten year viability hinges on circular material pathway positioning ahead of EFSA pharmaceutical-grade recycling approvals. Watch ECHA authorization timelines for recycled content as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Captures shelf-life extension premiums from hygroscopic solid dosage manufacturers in Germany. |
| Backward Integration into Certified Resin Sourcing | Insulates margin structure from ECHA-driven additive reformulation cycles in Dutch compounders. |
| Recycled Content Qualification Program | Positions converters for anticipated EFSA pharmaceutical-grade mechanical recycling authorizations. |
| Child-Resistant Closure Technology Licensing | Monetizes senior-friendly torque IP across EU poison-prevention mandate expansions. |
| Central European Manufacturing Footprint | Reduces logistics costs for Poland's emerging generics production clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with blow-molding operations managers, pharmaceutical packaging procurement leads, EMA regulatory affairs specialists, and resin compounder technical directors. Primary fieldwork covered German, Swiss, and Dutch converter facilities. Secondary sources included EMA packaging guidelines, ECHA REACH authorization lists, Cefic polymer trade statistics, and pharmaceutical company annual procurement disclosures. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Granularity-level modeling deployed product-type, material-grade, closure-mechanism, and end-user-category dimensions at the country-cluster level across the analysis window. CAGRs derived from polynomial trend fitting of historical volume trajectories, adjusted for regulatory inflection points. Forecast inputs incorporated REACH substance restriction timelines, EFSA recycling pathway opinion schedules, and generics manufacturing capacity buildout in Central Europe.
Inputs from EMA guidance documents and ECHA authorization registers were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and polymer feedstock cost stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market