
 Philippines Pharmaceutical Packaging Market | 2026-2036
Philippines Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Pharmaceutical Packaging Market Analytics
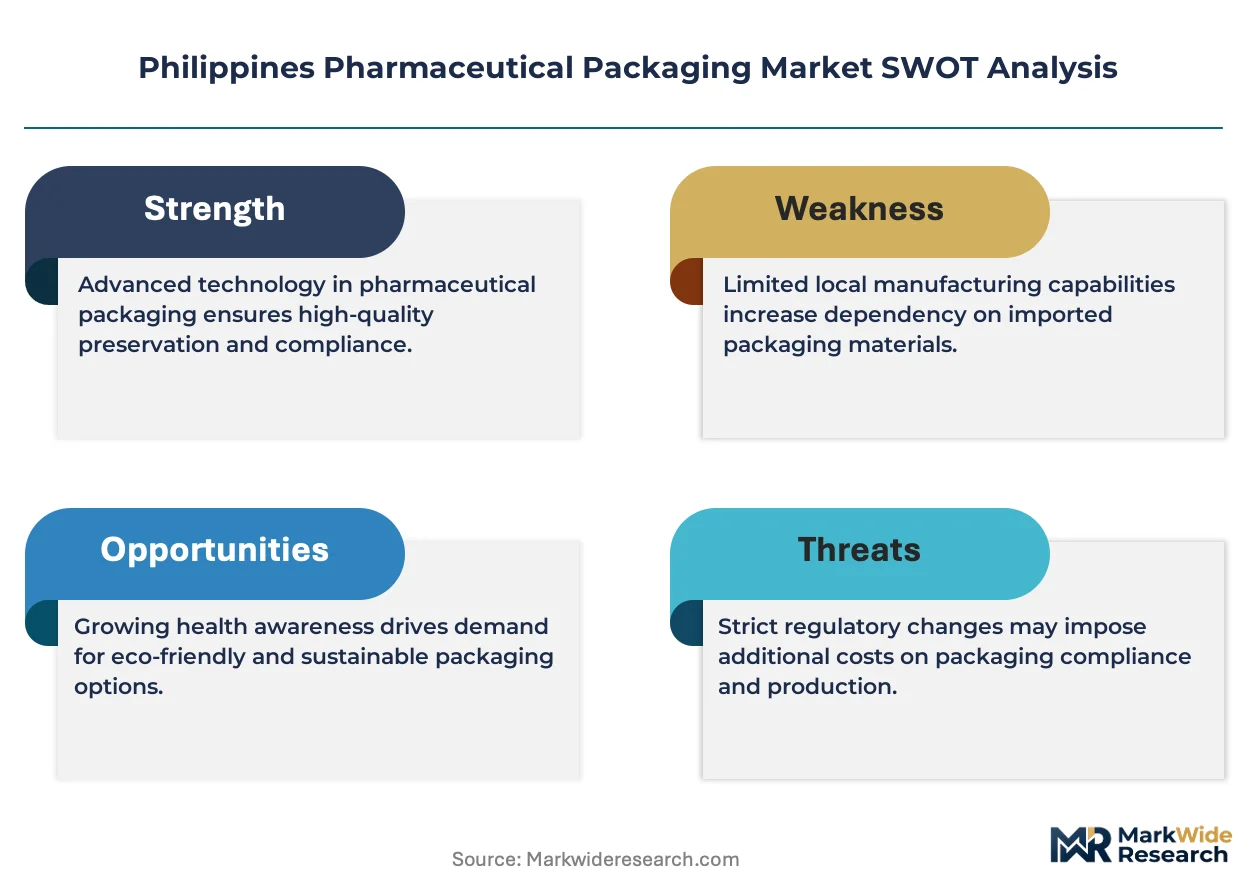
Asset-light leasing arrangements for blister-forming equipment is fragmenting competitive entry barriers across the Philippine archipelago. Bestpak Packaging Solutions anchors its position through captive tooling partnerships with domestic generic houses. Unilab leverages vertically integrated blister lines to sustain cost leadership in metro Manila. Amcor PLC competes via imported barrier film technologies that extend shelf life for tropical humidity conditions.
Philippine pharmaceutical packaging encompasses primary, secondary, and tertiary containment systems engineered to protect drug stability across tropical supply chains, with barrier specifications typically requiring moisture vapor transmission rates below 0.5 g/m²/day for humidity-sensitive formulations. Plastic and aluminum blister configurations dominate unit-dose dispensing for the country's expanding generic antibiotic sector, where tropical stability requirements command premium material specifications. Primary packaging leads value contribution as contract packagers absorb serialization compliance costs, while secondary packaging segments face margin compression from paperboard price volatility.
FDA Philippines enforces ASEAN Common Technical Dossier alignment for packaging material safety, while the Department of Health mandates cold-chain integrity standards for vaccine distribution that reshape tertiary packaging demand. BIS-equivalent material certifications and the FDA's forthcoming track-and-trace regulations will force contract packagers to upgrade line integration or exit the market. Stakeholders must weigh serialization capital deployment against the consolidation risk of smaller packagers losing DOH accreditation.
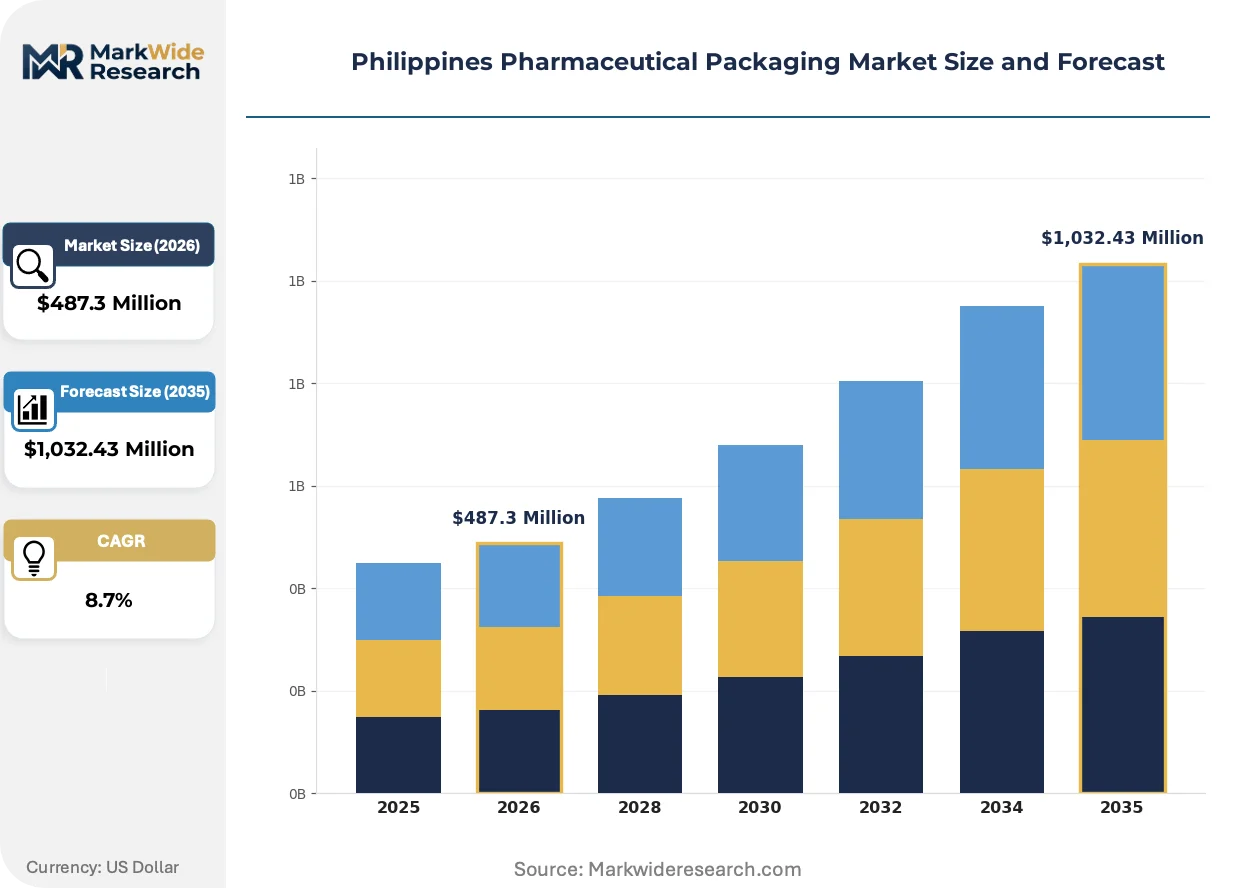
Market Dynamics
FDA Philippines serialization mandates are forcing contract packagers to absorb capital-intensive line upgrades or surrender DOH accreditation, concentrating market power among Metro Manila facilities with integrated track-and-trace capabilities.
Growth Catalysts
- ASEAN Common Technical Dossier alignment:FDA Philippines harmonization with regional safety standards accelerates cross-border generic drug approvals, expanding packaging demand for export-oriented manufacturers.
- Blister-forming equipment leasing:Asset-light machinery arrangements lower entry barriers for regional packagers across Visayas and Mindanao, dispersing production capacity beyond the capital region.
- Vaccine cold-chain mandates:Department of Health distribution integrity requirements for temperature-sensitive biologics drive tertiary packaging investment in insulated container systems.
Market Restraints
- Aluminum barrier film import dependency:Tropical-grade moisture vapor transmission specifications below 0.5 g/m²/day require specialized imported substrates, exposing margins to currency volatility and supply lead times.
- Metro Manila production clustering:Over 70 percent of pharmaceutical manufacturing concentrates within National Capital Region contract packaging hubs, creating geographic concentration risk for national distribution resilience.
- Paperboard input cost volatility:Secondary packaging segments face sustained margin compression from fluctuating pulp prices and domestic corrugated supply constraints.
Strategic Opportunities
- Visayas regional expansion:Cebu-based generic manufacturers remain underserved by high-speed blister lines, creating white space for serialization-capable contract packagers.
- Track-and-trace regulatory tailwind:FDA Philippines forthcoming full serialization enforcement will disqualify non-compliant packagers, enabling accredited facilities to capture stranded volume.
- RFID-barcode convergence:Integration of radio-frequency identification with linear barcode systems enables real-time cold-chain monitoring for biologics distributors.
Industry Challenges
- Serialization validation expertise scarcity:Qualified engineers capable of integrating line-level aggregation systems with national traceability databases command premium compensation, constraining workforce scalability.
- Legacy equipment retrofit complexity:Existing blister lines require extensive mechanical and software modification to meet FDA Philippines aggregation requirements, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Pharmaceutical Packaging Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Labels, Pouches Material: Plastic, Glass, Aluminum, Paperboard End User: Pharmaceutical Manufacturers, Contract Packagers, Distributors, Hospitals Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Customized Packaging |
| Companies Covered | Robicel Trading, Euro-med Laboratories Phil., Inc, Bestpak Packaging Solutions, Inc., Netpak Phils., Inc., Gl Otometz Corporation, Unilab, Amcor PLC, Mondi PLC, Huhtamäki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Pharmaceutical Packaging Market Evolving Landscape
Packaging material science and digital traceability systems are converging to address tropical stability requirements while compliance architectures reshape competitive positioning among Philippine contract manufacturers.
High-barrier coextruded films with embedded desiccant layers are collapsing the traditional separation between primary containment and moisture management functions. Generic antibiotic manufacturers in Cavite and Laguna are adopting these substrates at accelerating rates, eliminating separate sachet insertion steps and compressing unit-dose packaging cycle times by integrating barrier and absorption properties within single material structures.
FDA Philippines alignment with ASEAN Common Technical Dossier safety protocols is mandating extractables and leachables documentation for all plastic primary packaging materials. This regulatory friction most acutely affects small-volume generic houses lacking in-house analytical capabilities, which are responding by consolidating supplier relationships with film vendors holding pre-validated BIS-equivalent certifications.
Hospital procurement committees are consolidating purchasing authority for pharmaceutical packaging services, displacing fragmented departmental sourcing with centralized vendor qualification systems. This concentration is most visible within Philippine Department of Health referral networks, where single-contractor agreements for sterile barrier systems now cover multiple regional medical centers simultaneously.
Philippines Pharmaceutical Packaging Market Segmentation
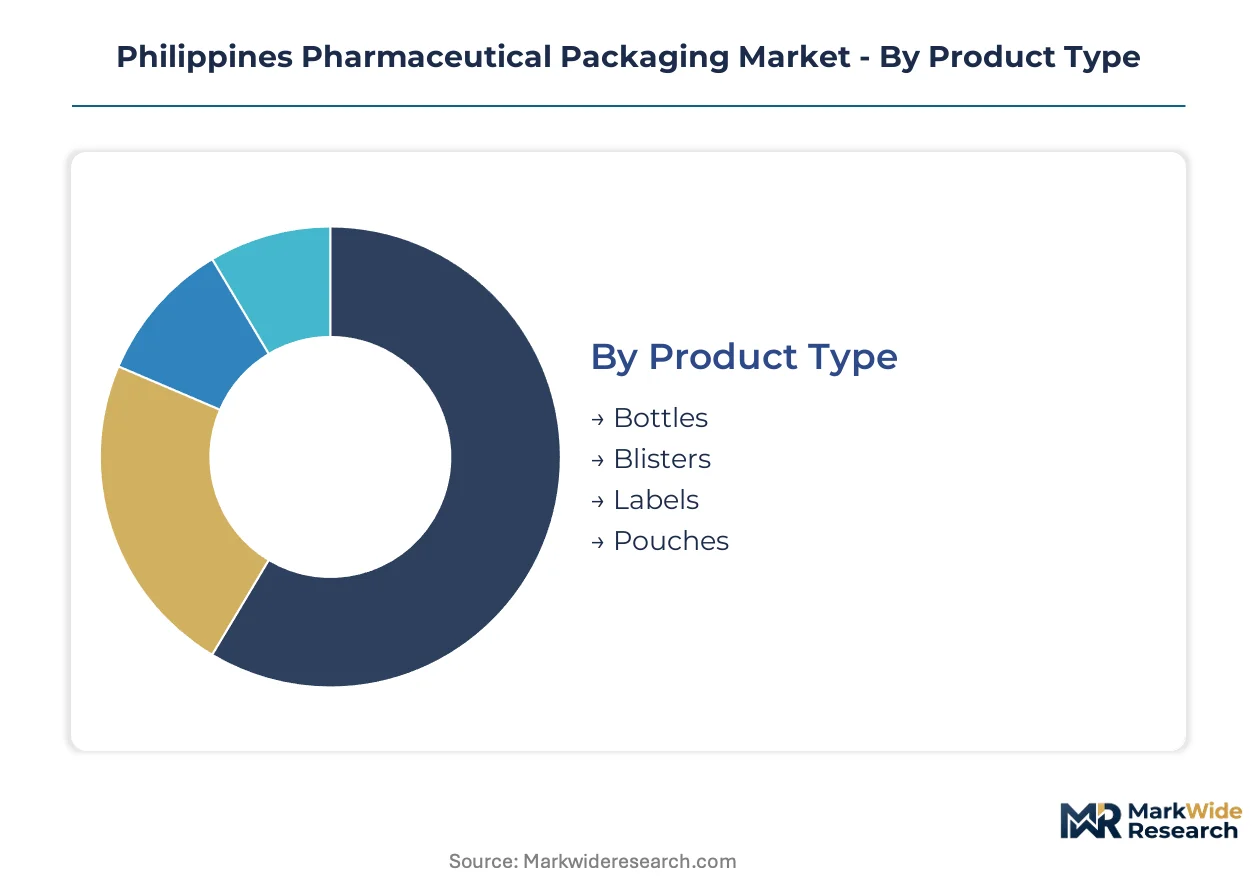
Segmentation reveals how tropical stability requirements, serialization compliance costs, and cold-chain mandates concentrate value across distinct packaging tiers in the Philippine pharmaceutical supply chain.
Product Type:
Application-specific functional demands determine material specifications and line investment intensity across unit-dose and multi-dose formats.
- Blisters:Aluminum-plastic laminate configurations with moisture vapor transmission rates below 0.5 g/m²/day dominate generic antibiotic unit-dose dispensing in Cavite and Laguna manufacturing clusters. FDA Philippines serialization mandates force capital upgrades on blister-forming lines, concentrating production among Metro Manila contract packagers with integrated track-and-trace capabilities.
- Bottles:High-density polyethylene and polypropylene containers serve oral solid dosage forms requiring desiccant integration, with demand clustering around Unilab's vertically integrated facilities in metro Manila. Child-resistant closure specifications for analgesic and cough-cold formulations drive specialized tooling investments that smaller generic houses outsource to contract packagers.
- Labels:Pressure-sensitive adhesive substrates with tamper-evident features incorporate linear barcodes and RFID inlays for cold-chain biologics tracking.
- Pouches:Flexible film structures accommodate powder and granule formulations with reseal functionality for humid tropical conditions.
Blisters command the established base. The steepest expansion runs through pouches as regional generic manufacturers seek lightweight export formats.
Material:
Cost tier positioning separates premium barrier specifications from commodity substrates, with tropical climate requirements elevating material performance thresholds.
- Plastic:Coextruded high-barrier films with embedded desiccant layers collapse primary containment and moisture management functions for humidity-sensitive antibiotics. Extractables and leachables documentation requirements under ASEAN Common Technical Dossier alignment favor suppliers with pre-validated BIS-equivalent certifications.
- Aluminum:Cold-form foil and strip pack substrates deliver sub-0.1 g/m²/day moisture protection for effervescent and hygroscopic formulations, with import dependency exposing margins to currency volatility and extended supply lead times.
- Glass:Borosilicate and soda-lime vials serve parenteral and vaccine applications requiring USP Type I/II/III hydrolytic resistance certification.
- Paperboard:Corrugated and folding carton structures face sustained margin compression from pulp price volatility and domestic supply constraints.
Plastic commands the established base. The steepest expansion runs through aluminum as tropical-grade barrier specifications tighten.
End User:
Customer type determines serialization validation depth, cold-chain infrastructure requirements, and procurement centralization patterns.
- Contract Packagers:Metro Manila-based facilities absorb FDA Philippines track-and-trace compliance costs through integrated aggregation systems, capturing stranded volume from smaller packagers losing DOH accreditation. Asset-light leasing arrangements for blister-forming equipment fragment entry barriers across Visayas and Mindanao.
- Pharmaceutical Manufacturers:Domestic generic houses in Cavite and Laguna consolidate supplier relationships with film vendors holding pre-validated certifications to overcome analytical capability gaps.
- Distributors:Cold-chain integrity mandates for vaccine distribution reshape tertiary packaging procurement toward insulated container systems.
- Hospitals:DOH referral networks consolidate purchasing authority through centralized vendor qualification systems covering multiple regional medical centers.
Contract packagers command the established base. The steepest expansion runs through hospitals as procurement centralization accelerates.
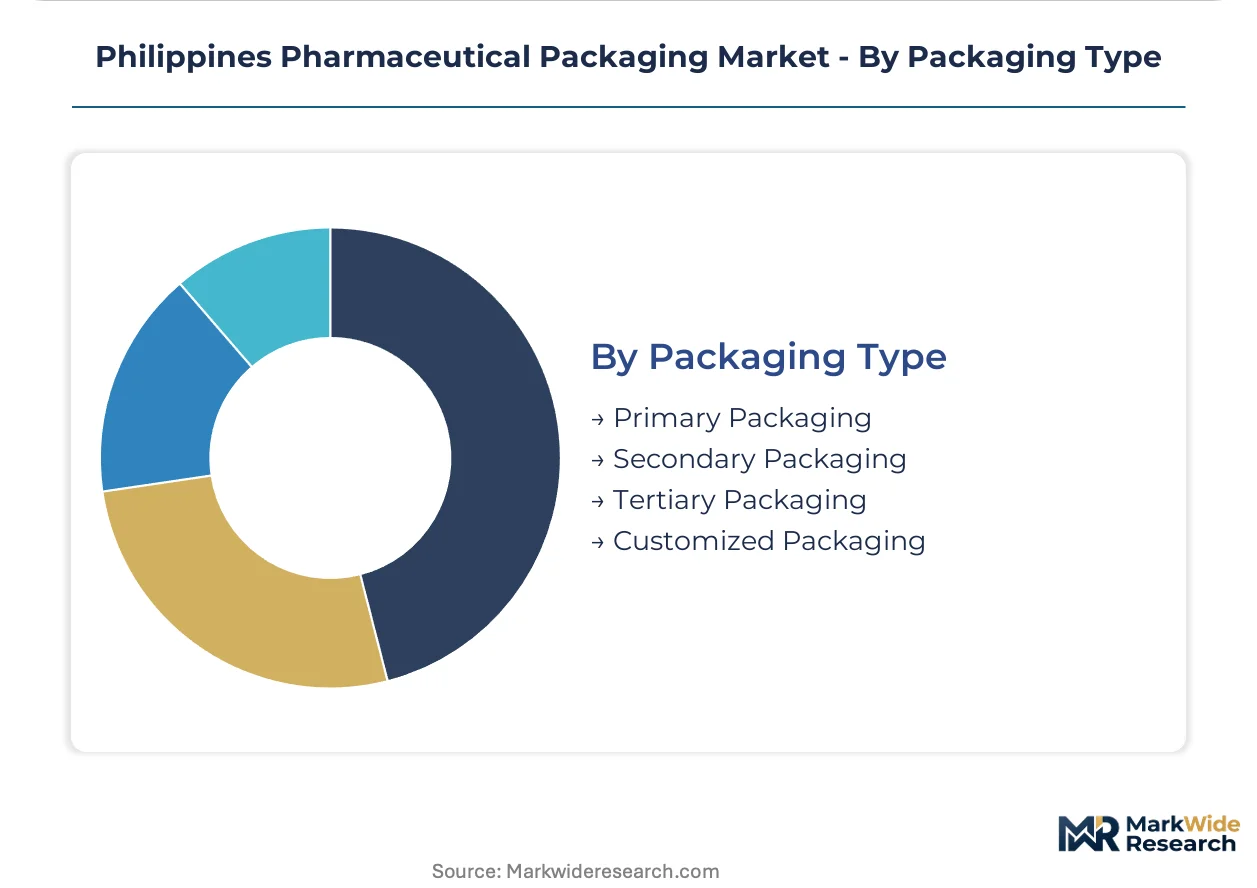
Packaging Type:
Maturity and margin profiles separate primary containment systems from secondary and tertiary tiers, with compliance architectures reshaping value capture.
- Primary Packaging:Blister packs, bottles, and vials constitute the direct drug-contact layer where barrier specifications and serialization integration concentrate capital deployment. Contract packagers absorb line upgrade costs here, preserving margin through volume scale and accreditation barriers.
- Secondary Packaging:Folding cartons and labels face compression from paperboard input volatility, with value migrating to serialization-capable suppliers.
- Tertiary Packaging:Insulated shipping containers and temperature-monitoring systems gain priority from DOH vaccine cold-chain mandates.
- Customized Packaging:Patient-centric designs and adherence-enhancing formats serve specialty therapeutic categories with differentiated compliance requirements.
Primary packaging commands the established base. The steepest expansion runs through tertiary packaging as biologics distribution requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippine pharmaceutical packaging sector operates as a net importer of high-performance barrier materials, with domestic production concentrated in Metro Manila while specialized substrates flow from regional suppliers. Export-oriented generic manufacturers in Cavite and Laguna drive outbound packaging demand for ASEAN markets.
Metro Manila
FDA Philippines serialization mandates concentrate contract packaging investment in the National Capital Region, where integrated track-and-trace capabilities preserve DOH accreditation. The department's cold-chain integrity standards for vaccine distribution reshape tertiary packaging procurement across Quezon City and Caloocan manufacturing zones. Bestpak Packaging Solutions anchors blister-forming capacity in this cluster through captive tooling partnerships with domestic generic houses.
Calabarzon
Generic antibiotic manufacturers in Cavite and Laguna generate sustained demand for aluminum-plastic laminate configurations with sub-0.5 g/m²/day moisture vapor transmission specifications. Unilab leverages vertically integrated blister lines across this southern Luzon corridor to sustain cost leadership in oral solid dosage forms. The region's production gravity attracts asset-light equipment leasing arrangements that fragment entry barriers for mid-scale packagers.
Central Visayas
Cebu-based generic manufacturers remain underserved by high-speed blister lines with serialization capabilities, creating white space for accredited contract packagers. The Department of Health's regional distribution networks for vaccine cold-chain mandates drive insulated container procurement from tertiary packaging specialists. Domestic corrugated supply constraints in this central island group elevate paperboard input costs for secondary packaging segments.
Davao Region
Mindanao's expanding pharmaceutical distribution infrastructure generates demand for humidity-resistant primary packaging as generic drug penetration deepens in southern Philippines markets. FDA Philippines ASEAN Common Technical Dossier alignment accelerates cross-border approvals for export-oriented manufacturers in Davao del Sur. Regional packagers deploy leased blister-forming equipment to serve dispersed manufacturing footprints without Metro Manila's capital intensity.
Philippines Pharmaceutical Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around serialization-accredited facilities as regulatory compliance costs disqualify smaller operators. Tiered competitive dynamics separate multinational material suppliers from domestic contract packagers and vertically integrated pharmaceutical manufacturers. Three archetypes dominate: integrated generic houses with captive packaging operations, specialized contract packagers with track-and-trace accreditation, and imported barrier film distributors serving tropical stability requirements. Market power concentrates through M&A activity among Metro Manila facilities and strategic partnerships between domestic packagers and ASEAN-certified material vendors.
Within the domestic contract packaging tier, Bestpak Packaging Solutions and Netpak Phils. occupy positions as Metro Manila-based operators with established generic manufacturer relationships. Unilab exemplifies the vertically integrated archetype through captive blister line ownership across Calabarzon manufacturing zones. Amcor PLC represents the multinational material supplier category with imported barrier film technologies addressing tropical humidity specifications. These three anchors illustrate how competitive positioning stratifies across accreditation depth, integration scope, and material sourcing geography.
| Leading Market Players |
|---|
| Robicel Trading |
| Euro-med Laboratories Phil., Inc |
| Bestpak Packaging Solutions, Inc. |
| Netpak Phils., Inc. |
| Gl Otometz Corporation |
| Unilab |
| Amcor PLC |
| Mondi PLC |
| Huhtamäki Oyj |
| Others |
Value Network & Pricing Analysis
Imported aluminum cold-form foil from Japan and South Korea commands premium positioning in Philippine pharmaceutical packaging, with tropical-grade barrier specifications below 0.5 g/m²/day moisture vapor transmission anchoring margin pools at the primary packaging tier. Domestic contract packagers absorb currency volatility while generic manufacturers in Cavite and Laguna face pass-through pressure on unit-dose formats.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Metro Manila packaging hubs. Price differentiation separates FDA Philippines serialization-accredited facilities from non-compliant operators losing DOH accreditation, with volume scale and cold-chain certification tiering quotes. Cost compression in secondary packaging runs through paperboard input volatility and corrugated supply constraints. Regional generic manufacturers in Visayas exhibit highest price sensitivity due to freight absorption requirements, while vaccine distributors show lowest sensitivity given cold-chain mandate compliance costs.
Supply Chain Analysis
Bestpak Packaging Solutions and Netpak Phils. hold concentrated blister-forming capacity across National Capital Region contract packaging zones. Geographic supply concentration draws from Japan, South Korea, and Thailand for high-barrier aluminum substrates and coextruded films. Raw material dependencies rest on imported desiccant-embedded films, tropical-grade adhesives, and serialization-capable label stocks. Single-source vulnerability for cold-form foil exposes margins to yen-peso exchange rate swings. Distribution feeds from Metro Manila contract packagers through DOH regional referral networks and Cebu-based generic manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine pharmaceutical packaging represents an early-cycle expansion story, with FDA Philippines track-and-trace mandates creating accreditation scarcity that concentrates volume among prepared facilities.
For Market Incumbents: Build regulatory moats through DOH serialization accreditation and ASEAN Common Technical Dossier-aligned supplier certifications. Bestpak Packaging Solutions and Unilab should consolidate captive tooling partnerships and vertically integrated blister lines to capture stranded volume from de-accredited regional packagers. Cold-chain infrastructure investment in Quezon City and Caloocan manufacturing zones defends against emerging Visayas-based competitors with leased equipment. For New Entrants and Emerging Players: Cebu-based generic manufacturers with underserved high-speed blister line requirements represent the most penetrable entry point for serialization-capable contract packagers. Asset-light equipment leasing arrangements across Central Visayas and Davao Region enable service of dispersed manufacturing footprints without Metro Manila capital intensity. RFID-barcode convergence for biologics cold-chain monitoring offers differentiated go-to-market positioning against incumbent barcode-only suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward Metro Manila contract packagers with integrated track-and-trace capabilities and existing DOH accreditation, as regulatory tailwinds disqualify smaller operators over the medium-term horizon. Acquisition targets should demonstrate pre-validated BIS-equivalent film supplier relationships and hospital procurement committee centralization wins. The signal to watch is FDA Philippines full serialization enforcement timing, which will trigger accelerated volume migration toward compliant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Line Integration | FDA Philippines mandates force capital deployment toward track-and-trace aggregation systems in Metro Manila facilities. |
| Cold-Chain Infrastructure Partnership | DOH vaccine distribution requirements drive insulated container procurement from tertiary packaging specialists in Quezon City. |
| Backward Integration into Barrier Films | Pre-validated BIS-equivalent certifications reduce extractables documentation friction for ASEAN Common Technical Dossier alignment. |
| Regional Equipment Leasing Arrangement | Asset-light blister-forming deployment across Visayas and Mindanao fragments entry barriers without National Capital Region capital intensity. |
| Hospital Procurement Committee Consolidation | Centralized vendor qualification across DOH referral networks captures multi-facility sterile barrier contracts simultaneously. |
Research Methodology
Cross-validation between primary interviews with contract packaging executives and secondary FDA Philippines regulatory filings anchors the qualitative findings in this study. Conversations with generic manufacturer procurement leads, hospital purchasing committee members, and cold-chain logistics specialists informed operational constraints and adoption timelines. Secondary sources include ASEAN Common Technical Dossier guidance documents, Department of Health cold-chain integrity standards, and customs data on aluminum barrier film imports. Bottom-up facility capacity estimates triangulate against top-down pharmaceutical production value projections.
Calibration against historical serialization adoption curves in comparable ASEAN markets shapes the analytical framework across the analysis window. Segmentation dimensions span product type, material grade, end-user archetype, and packaging tier, with dosage form and regional regulatory cluster as pharmaceutical-specific overlays. CAGRs derive from installed base growth, line throughput assumptions, and unit value trends for tropical-grade barrier specifications. Industry-specific inputs include FDA Philippines enforcement timeline probabilities and DOH accreditation attrition rates.
Macroeconomic conditions sit as an overlay; deviation in peso-yen exchange rates, pulp commodity indices, or ASEAN generic drug export demand would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pacing and cold-chain mandate expansion scope. Quarterly review of FDA Philippines serialization guidance updates, DOH accreditation registry changes, and hospital procurement centralization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market