
 Asia-Pacific Pharmaceutical Vials Market | 2026-2036
Asia-Pacific Pharmaceutical Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Vials Market Outlook
Glass furnace capacity across East Asia is hardening as energy costs and environmental compliance tighten. SCHOTT AG leverages its borosilicate expertise to anchor premium segments in Japan and South Korea. Shandong Pharmaceutical Glass competes aggressively on volume, supplying domestic injectable makers with molded vials at scale. Gerresheimer AG differentiates through ready-to-use formats and coating technologies that reduce protein adsorption.
Asia-Pacific pharmaceutical vials are sterile containers, typically borosilicate glass or cyclic olefin polymer, designed to maintain drug stability across temperatures from minus eighty degrees Celsius to ambient storage. They protect parenteral formulations from oxygen ingress, light degradation, and particulate contamination throughout shelf life and administration. Single-dose glass vials dominate current revenue due to biologics sensitivity and regulatory preference for reduced contamination risk. Prefilled formats represent the fastest-expanding segment as pharmaceutical companies outsource fill-finish operations to contract manufacturers in Singapore and South Korea. Plastic alternatives, particularly polypropylene, occupy niche positions for cytotoxic compounds where breakage risk must be eliminated.
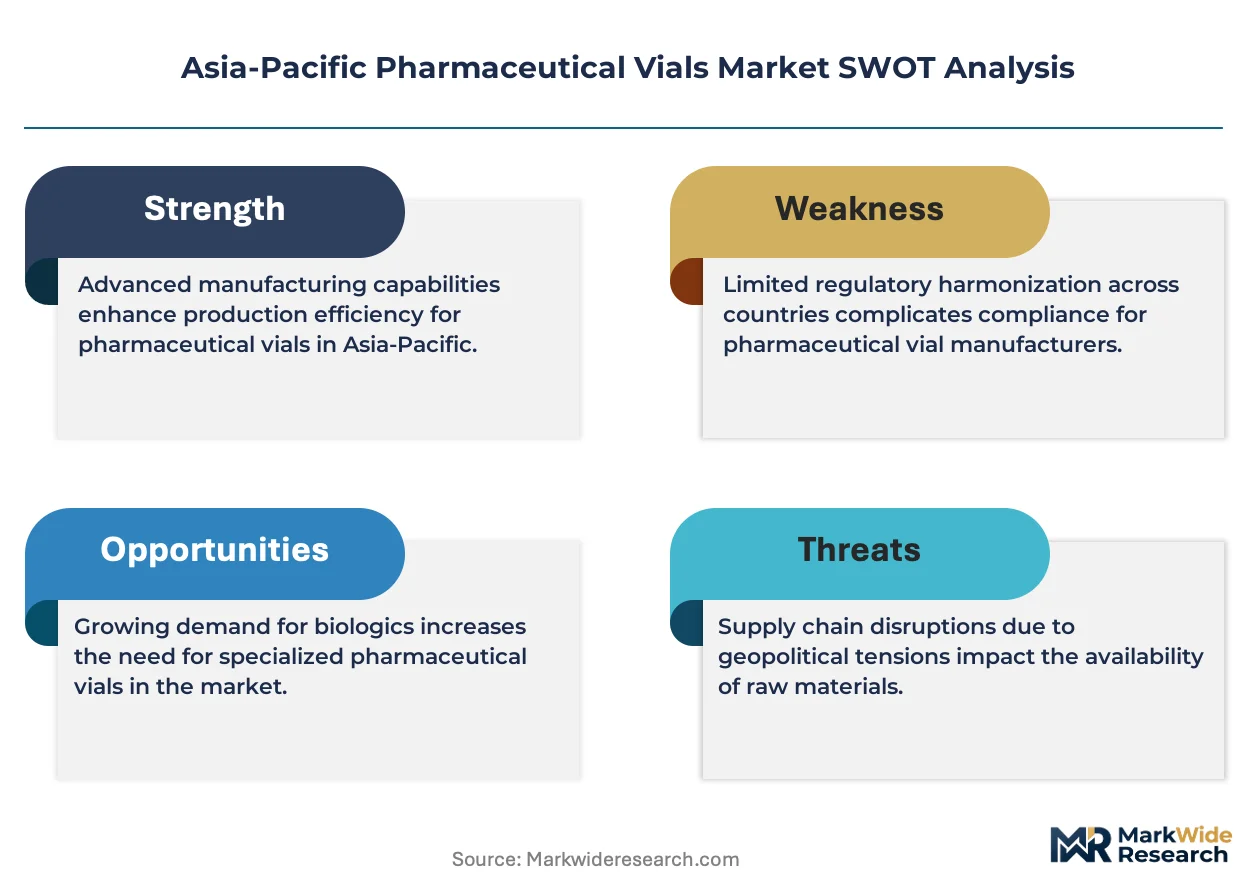
China's NMPA enforces GB standards harmonized with ICH Q1A stability guidelines, while India's CDSCO mandates BIS certification for imported glassware used in sterile injectables. Japan's PMDA applies JIS standards that exceed pharmacopeial baselines, creating a quality gradient that filters supplier eligibility. Australia's TGA alignment with European MDR further complicates market access for uncertified producers. Stakeholders must monitor evolving EMA-equivalence negotiations and carbon border adjustments that could reshape raw material sourcing across Southeast Asian manufacturing hubs.
Market Dynamics
Biologics manufacturing expansion across India and China is compressing lead times for container closure integrity testing, forcing vial suppliers to co-locate technical service teams within pharmaceutical clusters.
Growth Catalysts
- CDSCO Pharmacopeial Harmonization:India's tightened BIS certification requirements for sterile glassware are filtering out subscale importers and consolidating procurement toward qualified domestic molders.
- Cold-Chain Biologics Scale-Up:Injectable drug production in Gujarat and Maharashtra pharmaceutical clusters is generating concentrated demand for borosilicate vials with validated thermal shock resistance.
- NMPA Stability Alignment:China's GB standard convergence with ICH Q1A guidelines is mandating oxygen ingress documentation that only premium-coated vial formats can reliably satisfy.
Market Restraints
- Energy-Intensive Glass Furnace Operations:East Asian natural gas price volatility is squeezing margin structures for high-volume molded vial producers dependent on continuous melting.
- Single-Source Boron Supply Concentration:Turkey and Kazakhstan dominate refined boron feedstock, exposing vial manufacturers to geopolitical disruption in specialty glass chemistry.
- Polypropylene Substitution in Cytotoxic Handling:Plastic alternatives are capturing oncology compound packaging where glass breakage risk triggers costly cleanroom contamination protocols.
Strategic Opportunities
- Southeast Asian Fill-Finish Outsourcing:Singapore and South Korean contract manufacturers are expanding ready-to-use vial demand as pharmaceutical companies divest in-house aseptic filling capacity.
- Japan PMDA Premium Tier:JIS standards exceeding pharmacopeial baselines create a protected segment for coating technologies that reduce protein adsorption in monoclonal antibody formulations.
- Australia TGA-EMA Alignment:Regulatory equivalence negotiations are opening pathway opportunities for European-certified vial suppliers to bypass redundant local testing.
Industry Challenges
- Container Closure Integrity Validation Talent:Vacuum decay and helium leak testing expertise is scarce across Asia-Pacific contract laboratories, extending qualification timelines for new vial formats.
- Carbon Border Adjustment Preparation:Glass manufacturers face capital requirements for emissions documentation systems as European carbon border mechanisms threaten export competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Vials Market |
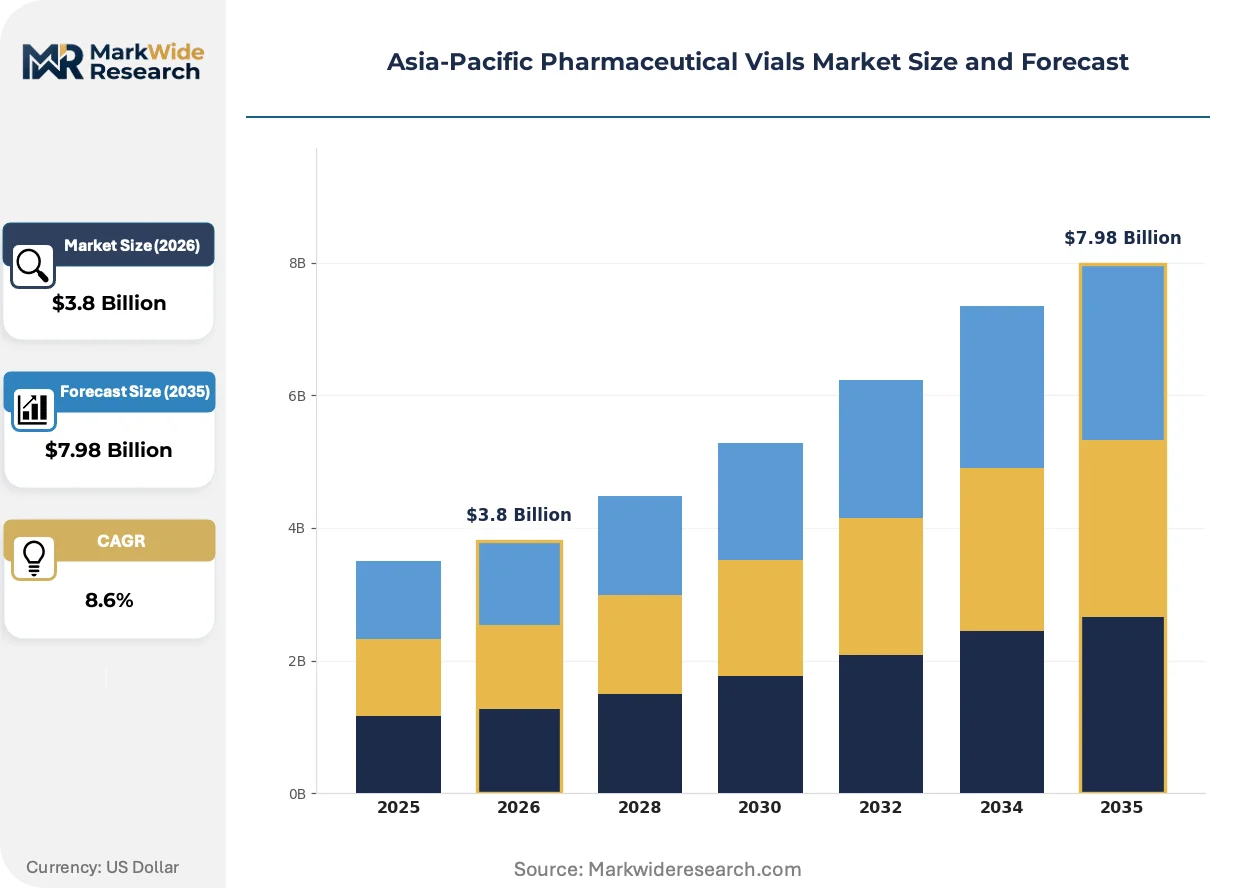
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose, Multi Dose, Custom Designed, Prefilled Material: Glass, Plastic, Polypropylene, PVC End User: Pharmaceutical Companies, Contract Manufacturers, Research Labs, Hospitals Closure Type: Flip-Off Caps, Screw Caps, Rubber Stoppers, Sealable Caps |
| Companies Covered | Gerresheimer AG, SGD Pharma, SCHOTT AG, Stevanato Group, DWK Life Sciences, Shandong Pharmaceutical Glass, Nipro Corporation, Bormioli Pharma, Shiotani Glass, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Vials Market Strategic Shifts
Ready-to-use vial formats are compressing fill-finish timelines as pharmaceutical outsourcing accelerates across Asia-Pacific manufacturing hubs.
Cyclic olefin polymer vials are overtaking borosilicate glass in protein-based biologics where surface interaction minimization determines shelf-life extension. Contract manufacturers in Singapore are specifying these formats for temperature-sensitive monoclonal antibodies. The shift is overtaking traditional glass qualification cycles and compressing supplier approval windows to under six months.
Japan's PMDA is tightening JIS Z 7253 labeling requirements for traceable container closure systems, forcing vial suppliers to integrate serialization-ready surface treatments. The industrial consequence is a bifurcation between premium coated formats and commodity molded glass. Biologics manufacturers in Osaka and Tokyo pharmaceutical corridors are absorbing compliance costs through dedicated supplier qualification programs.
Pharmaceutical procurement teams are consolidating vendor panels from twelve-plus suppliers to three qualified partners per geography, prioritizing technical service proximity over unit cost. Contract manufacturing organizations in South Korea are driving this consolidation through master service agreements that bundle vial supply with fill-finish capacity. The pattern is most visible in Singapore's Tuas biomedical manufacturing district where integrated supplier partnerships now dominate new facility commissioning.
Asia-Pacific Pharmaceutical Vials Market Segmentation
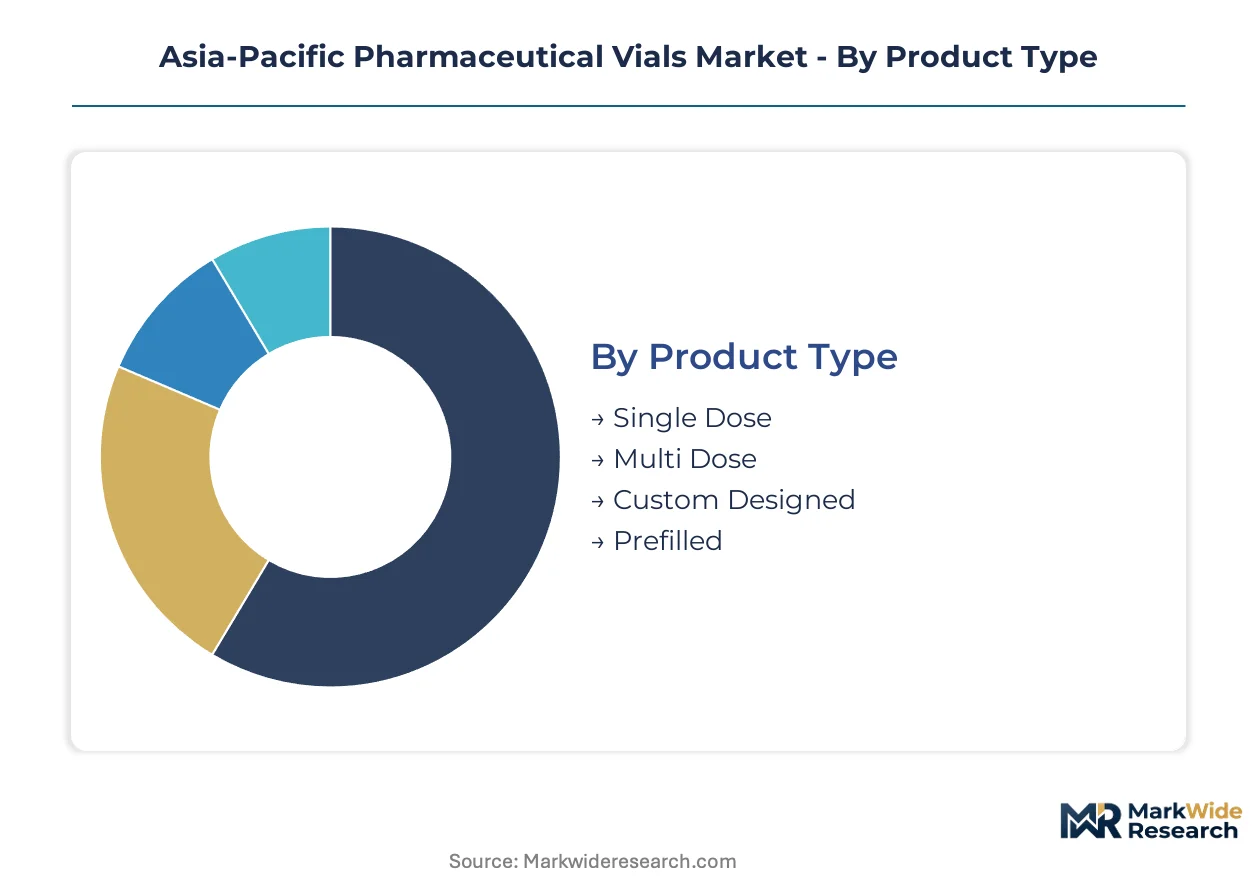
Segmentation in Asia-Pacific pharmaceutical vials reflects divergent upgrade cycles across biologics manufacturing, cold-chain infrastructure, and regulatory compliance timelines. Pharmaceutical procurement teams are consolidating vendor relationships around segments that compress qualification timelines while satisfying tightening pharmacopeial standards.
Product Type:
Replacement cycles accelerate where container closure integrity failures trigger batch recalls, driving pharmaceutical clusters toward formats with validated performance documentation.
- Single Dose:Borosilicate glass construction dominates biologics packaging where contamination risk elimination outweighs unit cost considerations. Gujarat and Maharashtra injectable manufacturers specify these formats for monoclonal antibody production requiring validated thermal shock resistance across minus eighty degrees Celsius to ambient storage.
- Prefilled:Ready-to-use formats integrate drug product with container closure systems, eliminating separate fill-finish operations. Singapore and South Korean contract manufacturers are expanding procurement of these formats as pharmaceutical companies divest in-house aseptic filling capacity and compress time-to-market timelines.
- Multi Dose:Shared-dose formats serve cost-sensitive therapeutic categories where multiple withdrawals from a single vial reduce per-dose packaging expenditure.
- Custom Designed:Application-specific geometries address niche formulation requirements including viscous biologics or lyophilized products requiring specialized reconstitution protocols.
Volume placements concentrate in Single Dose formats; the faster expansion belongs to Prefilled configurations.
Material:
Cost tier differentiation separates premium-coated borosilicate from commodity alternatives, with procurement decisions hinging on oxygen ingress specifications and protein adsorption profiles.
- Glass:Borosilicate chemistry provides thermal shock resistance and oxygen barrier properties essential for biologics stability. India's CDSCO mandates BIS certification for imported glassware used in sterile injectables, filtering procurement toward qualified domestic molders in Gujarat pharmaceutical corridors.
- Polypropylene:Cyclic olefin polymer construction eliminates breakage risk in cytotoxic compound handling where glass fragmentation triggers costly cleanroom contamination protocols. Contract manufacturers in Singapore specify these formats for temperature-sensitive monoclonal antibodies requiring surface interaction minimization.
- Plastic:General polymer alternatives occupy niche positions where weight reduction or impact resistance outweighs barrier performance requirements.
- PVC:Legacy polymer formats persist in specific therapeutic applications where established regulatory filings constrain material substitution timelines.
Procurement volumes cluster in Glass; Polypropylene is climbing the fastest as biologics portfolios expand.
End User:
Customer type determines technical service intensity, with contract manufacturers demanding co-located supplier support that commodity distributors cannot provide.
- Pharmaceutical Companies:Integrated drug developers maintain direct vial procurement relationships for proprietary formulations, prioritizing coating technologies that reduce protein adsorption in monoclonal antibody products. Japan's PMDA JIS standards exceeding pharmacopeial baselines create protected segments for premium formats.
- Contract Manufacturers:Fill-finish outsourcing specialists in Singapore's Tuas biomedical district bundle vial supply with aseptic processing capacity, consolidating vendor panels from twelve-plus suppliers to three qualified partners per geography.
- Research Labs:Early-stage formulation development generates small-batch demand for flexible specification vials with accelerated qualification timelines.
- Hospitals:Point-of-care settings prioritize ready-to-use formats that minimize preparation steps and reduce medication error risk in high-stakes therapeutic administration.
Contract Manufacturers absorb the steepest volume growth; Pharmaceutical Companies retain the largest absolute procurement scale.
Closure Type:
Margin structures vary with validation complexity, as helium leak testing and vacuum decay documentation requirements extend qualification timelines for premium seal configurations.
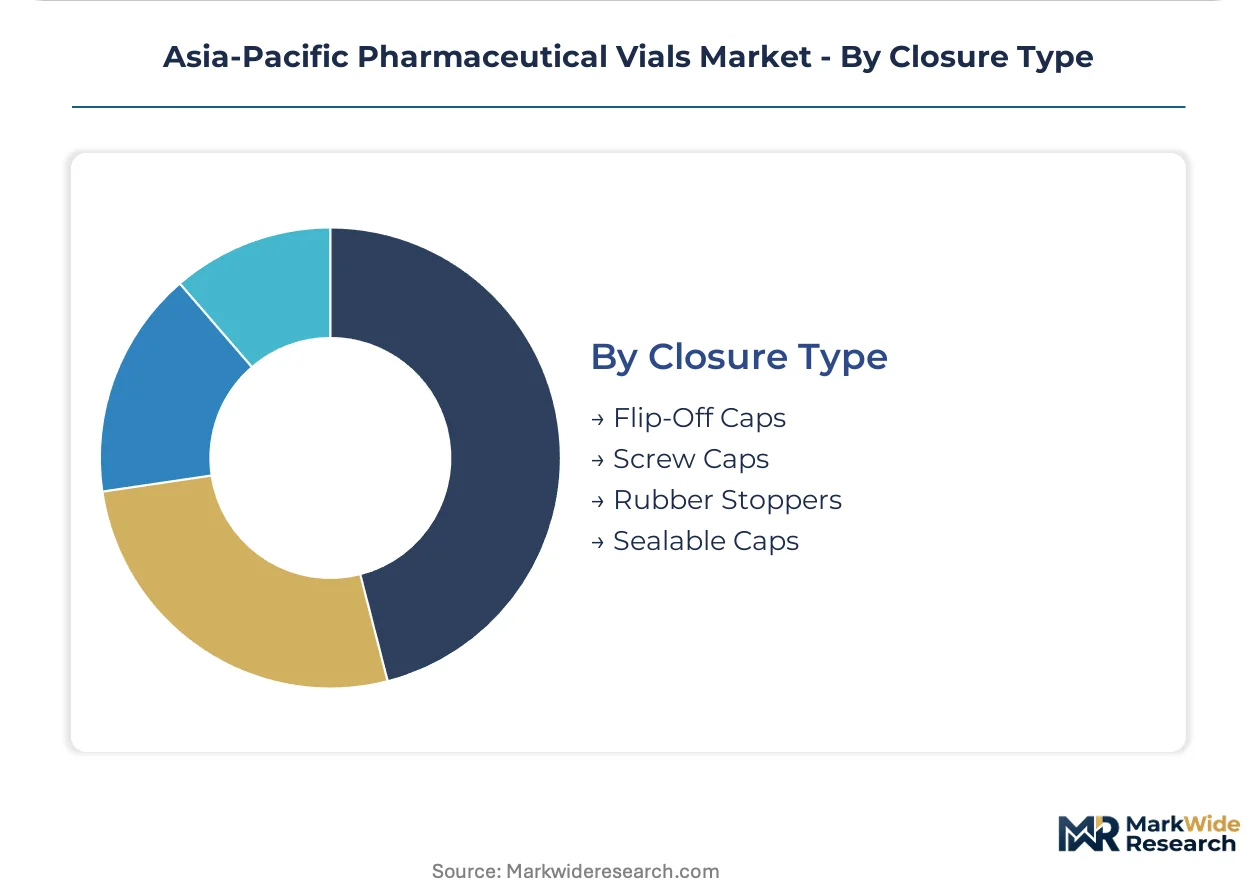
- Flip-Off Caps:Aluminum-plastic composite designs enable rapid needle access while maintaining sterility barriers. China's NMPA GB standards harmonized with ICH Q1A guidelines mandate oxygen ingress documentation that premium-coated flip-off assemblies satisfy.
- Rubber Stoppers:Elastomeric seals with validated extractables profiles protect parenteral formulations from contamination. Japan's PMDA tightening of JIS Z 7253 labeling requirements forces integration of serialization-ready surface treatments in stopper specifications.
- Screw Caps:Threaded closure systems serve multi-dose applications where repeated access demands mechanical durability across shelf life.
- Seal Caps:Permanent crimp seals address single-use applications where tamper evidence and container closure integrity supersede reopening functionality.
Flip-Off Caps command the highest placement volumes; Rubber Stoppers are gaining share fastest as biologics sensitivity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey and Kazakhstan dominate refined boron feedstock supply, anchoring specialty glass chemistry for vial manufacturers across Asia-Pacific pharmaceutical corridors.
China
Injectable biologics production in Jiangsu and Zhejiang provinces is scaling cold-chain infrastructure for temperature-sensitive formulations. NMPA enforces GB standards harmonized with ICH Q1A stability guidelines, mandating oxygen ingress documentation that premium-coated vial formats satisfy. Shandong Peninsula glass manufacturers supply domestic injectable makers with molded borosilicate vials at volume.
India
Monoclonal antibody manufacturing in Gujarat and Maharashtra pharmaceutical clusters is generating concentrated demand for validated thermal shock resistance. CDSCO tightened BIS certification requirements for imported glassware used in sterile injectables, filtering procurement toward qualified domestic molders. Ahmedabad and Mumbai corridors now host technical service teams co-located with pharmaceutical production facilities.
Japan
Protein-based biologics formulation in Osaka and Tokyo pharmaceutical corridors is absorbing compliance costs for surface interaction minimization. PMDA applies JIS standards exceeding pharmacopeial baselines, creating protected segments for coating technologies that reduce protein adsorption. Kansai region manufacturers specify serialization-ready surface treatments under tightening JIS Z 7253 labeling requirements.
South Korea
Contract manufacturing organizations in Seoul Capital Area are consolidating vendor panels from twelve-plus suppliers to three qualified partners per geography. MFDS alignment with international stability guidelines supports fill-finish outsourcing expansion. Busan-Ulsan biomedical districts bundle vial supply with aseptic processing capacity through master service agreements.
Singapore
Temperature-sensitive monoclonal antibody production in Tuas biomedical manufacturing district is driving ready-to-use vial procurement. The national pharmaceutical regulator maintains equivalence pathways with European standards, streamlining supplier qualification for European-certified vial manufacturers. Integrated supplier partnerships now dominate new facility commissioning across the city-state's pharmaceutical hubs.
Asia-Pacific Pharmaceutical Vials Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue ready-to-use formats and coating specializations. The vendor base separates between high-volume molded glass suppliers and premium coated-format specialists. Three archetypes dominate: German and Japanese precision glasshouses with borosilicate expertise, Chinese scale-driven molders serving domestic injectable demand, and European coating-technology specialists. Capacity expansion and geographic co-location with pharmaceutical clusters constitute the dominant competitive moves.
Among German precision glasshouses, SCHOTT AG and Gerresheimer AG exemplify the premium-tier archetype through borosilicate specialization. Shandong Pharmaceutical Glass represents the scale-driven Chinese molder segment supplying domestic volume demand. These three occupy positions across the quality gradient created by divergent national pharmacopeial standards, with each anchoring distinct procurement tiers based on certification depth and technical service proximity.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SGD Pharma |
| SCHOTT AG |
| Stevanato Group |
| DWK Life Sciences |
| Shandong Pharmaceutical Glass |
| Nipro Corporation |
| Bormioli Pharma |
| Shiotani Glass |
| Others |
Value Chain & Pricing Dynamics
Contract manufacturers in Singapore and South Korea concentrate procurement volumes, anchoring a contract-based long-term offtake model where technical service bundling commands premium positioning over unbundled commodity supply.
Pricing Analysis
Warranty and container closure integrity validation services are bundled for premium coated borosilicate formats while commodity molded glass ships unbundled. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified Japanese supply from CDSCO-compliant Indian molders and uncertified regional alternatives. Price differentiation rests on certification grade and geographic delivery cost, with energy-intensive furnace operations squeezing margins in the standard tier. Pharmaceutical companies in Japan absorb the highest service premiums; injectable makers in India exhibit acute price sensitivity.
Supply Chain Analysis
India's tightened BIS certification requirements for imported glassware are reshaping sourcing toward qualified domestic molders in Gujarat and Maharashtra. Raw material supply draws from Turkish and Kazakhstani boron feedstock, Chinese soda ash, and regional silica sand deposits. Single-source vulnerability in refined boron chemistry exposes manufacturers to geopolitical disruption. Distribution runs through pharmaceutical cluster co-location agreements where technical service teams embed within production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific pharmaceutical vials are transitioning from commodity borosilicate glass to cyclic olefin polymer formats as protein-based biologics displace legacy small-molecule injectables.
For Market Incumbents: Cement dominance in Japan's PMDA-regulated premium tier through coating technology investments that reduce protein adsorption. Acquire technical service capabilities in Singapore's Tuas biomedical district to defend against contract manufacturer consolidation. Backward integration into boron feedstock partnerships mitigates single-source concentration risk from Turkey and Kazakhstan. For New Entrants and Emerging Players: The price-point gap between SCHOTT AG's premium coated formats and Shandong Pharmaceutical Glass's commodity molded volumes creates white-space opportunity. Target India's CDSCO-filtered procurement environment where BIS certification barriers have eliminated subscale importers. Penetrate through ready-to-use format specialization bundled with accelerated six-month qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor European-certified coating-technology specialists with dormant Asia-Pacific distribution. Long-term viability hinges on regulatory equivalence pathways between Australia's TGA and EMA standards. Watch NMPA oxygen ingress documentation mandates as the inflection signal for premium format adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Acquisition | Protein adsorption reduction capabilities unlock Japan's PMDA premium segment access. |
| Pharmaceutical Cluster Co-Location | Technical service proximity satisfies Singapore and South Korean contract manufacturer consolidation demands. |
| Boron Feedstock Partnership | Upstream supply security addresses geopolitical concentration risk in Turkish and Kazakhstani sources. |
| Ready-to-Use Format Expansion | Pre-sterilized vial configurations compress fill-finish timelines for monoclonal antibody outsourcing. |
| Serialization-Ready Surface Treatment | JIS Z 7253 compliance enables traceable container closure system integration for Osaka and Tokyo corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific pharmaceutical vials analysis. Primary interviews with fill-finish operations directors, CDSCO regulatory affairs leads, pharmaceutical procurement managers, and container closure integrity testing specialists combined with NMPA GB standard documentation, BIS certification registries, and pharmaceutical import databases. Bottom-up vial volume estimates triangulated against top-down biologics production forecasts across the analysis window.
Segment-level modeling tracked product type, material chemistry, end-user category, and closure configuration at country-resolution for China, India, Japan, South Korea, and Singapore. CAGRs derived from biologics pipeline expansion rates, cold-chain infrastructure investment trajectories, and pharmacopeial harmonization timelines. Forecast inputs incorporated monoclonal antibody manufacturing capacity additions and contract manufacturing organization fill-finish outsourcing announcements.
Inputs from PMDA and MFDS regulatory databases were available through the study window; gaps in real-time pharmaceutical procurement contract disclosures introduce uncertainty bands around vendor consolidation velocity assumptions. Forecasts reflect documented assumptions regarding CDSCO enforcement intensity and NMPA-ICH Q1A alignment progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market