
 Pharmaceutical 3PL Market | 2026-2036
Pharmaceutical 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical 3PL Market Analytics
Biopharmaceutical manufacturing is decoupling from traditional small-molecule supply chains, creating divergent logistics requirements for temperature-sensitive biologics. DHL Supply Chain & Global Forwarding leverages dedicated pharmaceutical campuses in key logistics corridors to anchor its cold chain infrastructure. Kuehne + Nagel sustains competitive positioning through specialized active container fleets and GDP-certified warehouse networks. Cardinal Health differentiates via integrated distribution services that bridge manufacturer-to-pharmacy channels with regulatory compliance embedded throughout.
Pharmaceutical third-party logistics encompasses outsourced supply chain management for life sciences products, encompassing temperature-controlled storage, serialized inventory tracking, and validated transportation under GDP and cGMP standards. These services maintain product integrity across 2°C to 8°C, -20°C, and cryogenic ranges while enabling regulatory traceability from manufacture to patient administration. Cold chain logistics leads service investment as biologics and personalized medicines expand, with warehouse automation representing the fastest-growing technology segment as labor costs and accuracy requirements intensify. Distribution services concentrate margin pools in last-mile hospital and pharmacy delivery, where time-definite performance directly impacts patient outcomes.
FDA Drug Supply Chain Security Act requirements and EU Good Distribution Practice guidelines shape market access by mandating serialization, verification, and temperature documentation across all pharmaceutical shipments. Health Canada and the UK's MHRA impose parallel standards that multi-national 3PL providers must navigate simultaneously. Stakeholders must monitor evolving cell and gene therapy logistics protocols, as these therapies demand cryogenic chain integrity and ultra-rapid delivery windows that exceed current infrastructure capabilities in most markets.
Market Dynamics
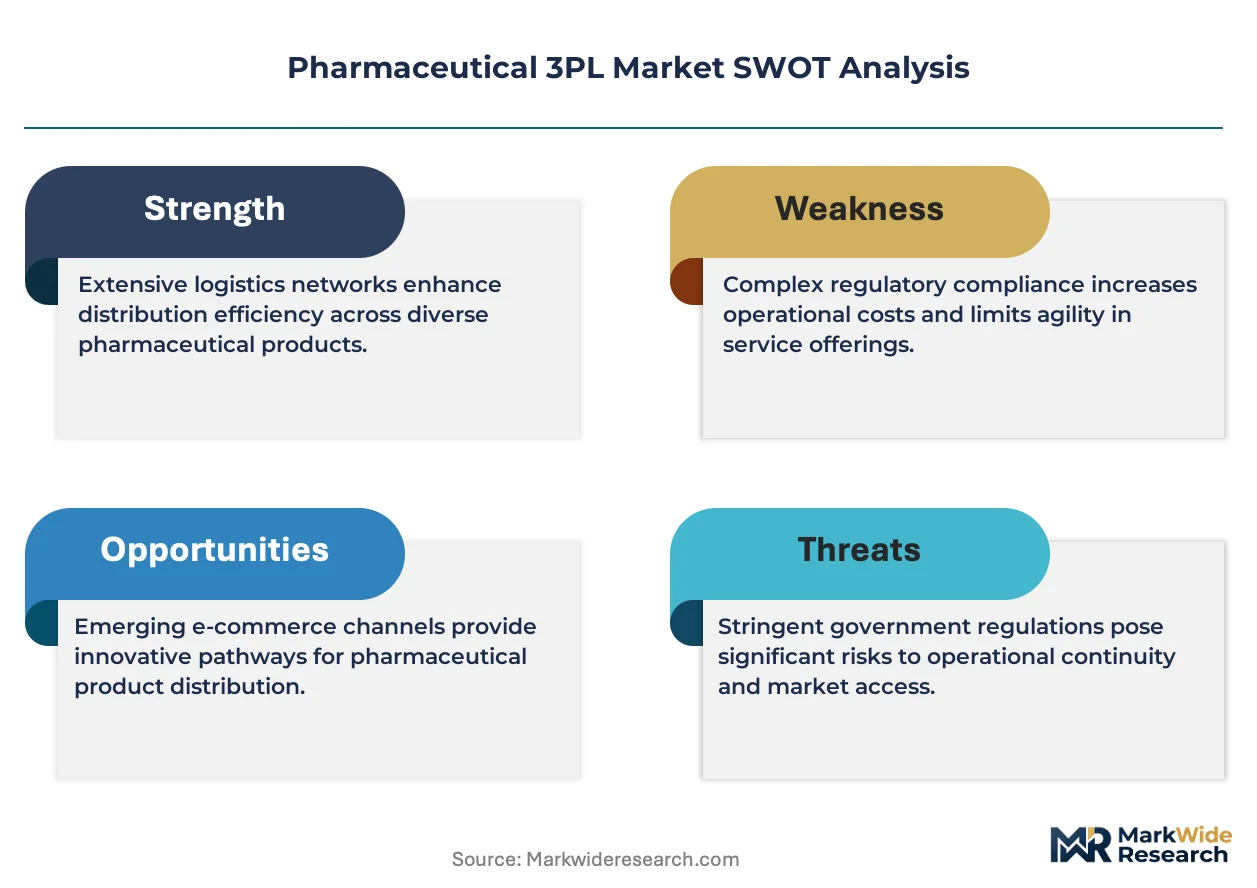
Cell and gene therapies are fragmenting pharmaceutical logistics into parallel cold chain networks requiring cryogenic integrity, forcing 3PL providers to build temperature-specific infrastructure rather than generic pharmaceutical handling capacity.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates compel manufacturers to outsource track-and-trace capabilities to specialized 3PL operators with validated IT infrastructure.
- Biologics manufacturing concentration:Germany's Rhine-Main logistics corridor anchors European biopharma distribution, drawing specialized cold chain investment from global freight forwarders.
- Active container fleets:Temperature-controlled shipping systems enable lane-agnostic transport of high-value biologics without fixed cold chain infrastructure dependency.
Market Restraints
- Qualified personnel scarcity:GDP certification requirements and cold chain engineering expertise command wage premiums that compress 3PL margins.
- Specialized warehouse capex:cGMP-compliant storage facilities with redundant cooling systems require capital intensity that limits mid-tier operator expansion.
- Cross-border regulatory friction:Divergent EU Good Distribution Practice interpretations between member states create compliance duplication costs for pan-European networks.
Strategic Opportunities
- Cell therapy logistics protocols:Cryogenic chain integrity standards for CAR-T treatments remain undefined in most markets, creating first-mover service definition potential.
- India's pharmaceutical export growth:CDSCO regulatory alignment with ICH standards positions Indian contract manufacturers to demand compliant 3PL partnerships for regulated-market shipments.
- Real-time monitoring convergence:Integration of IoT sensors with blockchain verification creates auditable temperature documentation that satisfies FDA and EMA inspection requirements simultaneously.
Industry Challenges
- Cryogenic handling certification:Liquid nitrogen infrastructure maintenance and safety protocols require specialized technician training programs that extend onboarding timelines.
- Legacy WMS integration:Pharmaceutical manufacturers' validated warehouse management systems resist API connectivity with 3PL platforms, forcing expensive custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical 3PL Market |
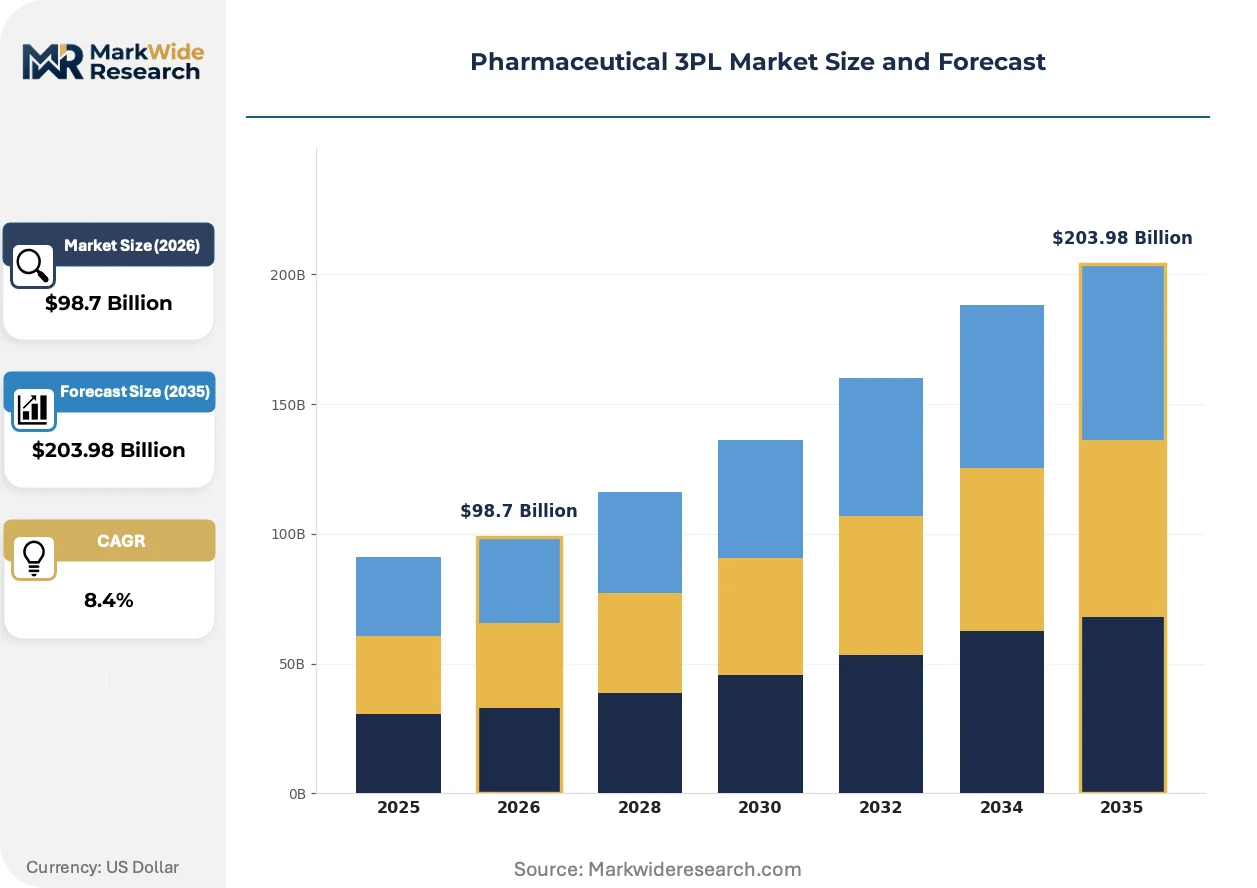
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Distribution, Transportation, Order Fulfillment End User: Pharmaceutical Manufacturers, Biotech Companies, Healthcare Providers, Retail Pharmacies Technology: Cold Chain Logistics, Inventory Management Systems, Tracking Solutions, Warehouse Automation Distribution Channel: Direct Sales, Third-Party Distributors, Online Platforms, Wholesalers |
| Companies Covered | UPS Healthcare, CEVA Logistics, DHL Supply Chain & Global Forwarding, Agility Logistics, Kerry Logistics Network, Kuehne + Nagel, DB Schenker, Cardinal Health, FedEx Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical 3PL Market Evolving Landscape
Biopharmaceutical logistics is bifurcating into distinct operational models: high-velocity personalized medicine networks versus scale-driven generic distribution, with technology investment diverging accordingly.
Autonomous mobile robots are overtaking conventional warehouse automation in pharmaceutical facilities. These systems navigate temperature-controlled environments without human contamination risk. Biologics manufacturers with high-SKU, low-volume production profiles are deploying AMR fleets for picking accuracy. The technology is overtaking fixed conveyor infrastructure by enabling facility reconfiguration without structural modification.
EU Good Distribution Practice revisions are tightening temperature excursion documentation requirements for cross-border shipments. The 2024 guidance mandates continuous data logging rather than interval-based monitoring. Cold chain operators serving the European Economic Area are retrofitting container fleets with enhanced sensor density to maintain compliance.
Hospital pharmacy consolidation is compressing delivery window requirements from 48-hour to same-day for critical biologics. Integrated delivery networks are bypassing wholesale distributors for direct manufacturer relationships. This pattern concentrates most acutely in the United States, where health system aggregation creates volume concentration that justifies dedicated logistics lanes.
Pharmaceutical 3PL Market Segmentation
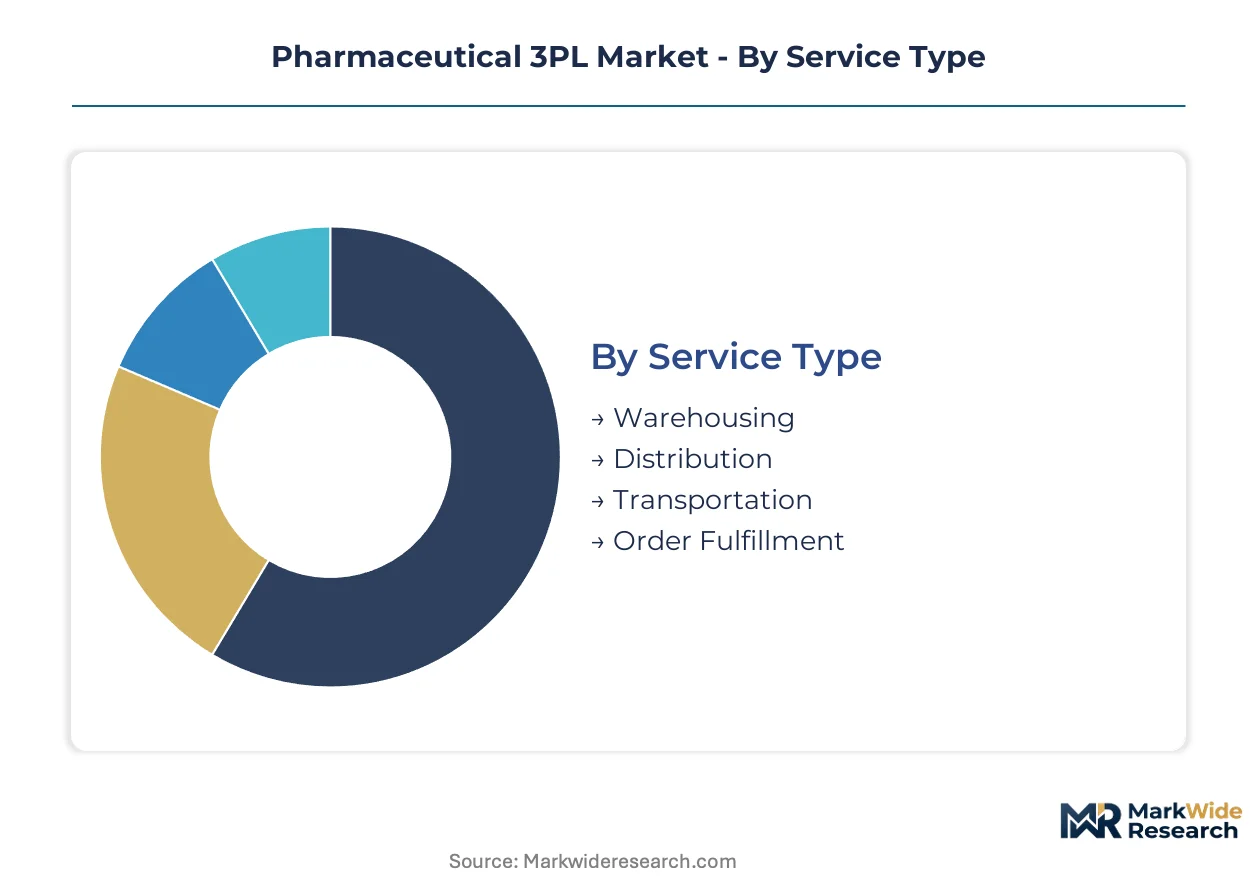
Pharmaceutical 3PL segmentation reflects divergent infrastructure requirements across temperature ranges, regulatory complexity tiers, and delivery velocity demands. Service providers configure distinct operational models for each segment combination rather than deploying uniform capabilities.
Service Type:
Temperature specification and handling protocol complexity define competitive positioning across service categories.
- Warehousing:cGMP-compliant facilities with redundant cooling systems and validated environmental monitoring anchor cold chain integrity for biologics storage. Demand concentrates in Germany's Rhine-Main corridor, where centralized European distribution positioning and dense air cargo connectivity draw specialized investment from global freight forwarders facing qualified personnel scarcity.
- Distribution:Last-mile hospital and pharmacy delivery commands premium positioning where time-definite performance directly impacts patient outcomes. Hospital pharmacy consolidation in the United States compresses delivery windows from 48-hour to same-day for critical biologics, concentrating margin pools in integrated delivery networks bypassing wholesale channels.
- Transportation:Lane-agnostic active container fleets enable validated temperature maintenance across variable infrastructure.
- Order Fulfillment:Serialized inventory tracking with GDP-compliant documentation supports direct-to-patient models.
Mature deployment sits with warehousing. Newer deployment is concentrated in order fulfillment.
End User:
Customer type determines regulatory burden intensity and cold chain specification requirements.
- Biotech Companies:Cell and gene therapy manufacturers demand cryogenic chain integrity and ultra-rapid delivery windows exceeding current infrastructure capabilities in most markets. CDSCO regulatory alignment with ICH standards in India positions contract manufacturers to require compliant 3PL partnerships for regulated-market shipments.
- Pharmaceutical Manufacturers:FDA Drug Supply Chain Security Act mandates compel outsourcing of track-and-trace capabilities to operators with validated IT infrastructure.
- Healthcare Providers:Integrated delivery networks seek direct manufacturer relationships with embedded compliance.
- Retail Pharmacies:Serialized inventory verification requirements shape partnership selection criteria.
Mature deployment sits with pharmaceutical manufacturers. Newer deployment is concentrated in biotech companies.
Technology:
Investment intensity and labor substitution potential differentiate technology deployment patterns.
- Warehouse Automation:Autonomous mobile robots navigate temperature-controlled environments without human contamination risk, enabling facility reconfiguration without structural modification. Biologics manufacturers with high-SKU, low-volume production profiles deploy AMR fleets for picking accuracy as labor costs and precision requirements intensify.
- Cold Chain Logistics:Continuous data logging systems satisfy EU Good Distribution Practice revisions mandating temperature excursion documentation rather than interval-based monitoring.
- Inventory Management Systems:Legacy WMS integration challenges force expensive custom interface development with pharmaceutical manufacturers' validated platforms.
- Tracking Solutions:IoT sensor integration with blockchain verification creates auditable temperature documentation satisfying FDA and EMA inspection requirements simultaneously.
Mature deployment sits with cold chain logistics. Newer deployment is concentrated in warehouse automation, which is gaining share fastest among technology categories.
Distribution Channel:
Channel selection reflects customer scale, regulatory familiarity, and geographic coverage requirements.
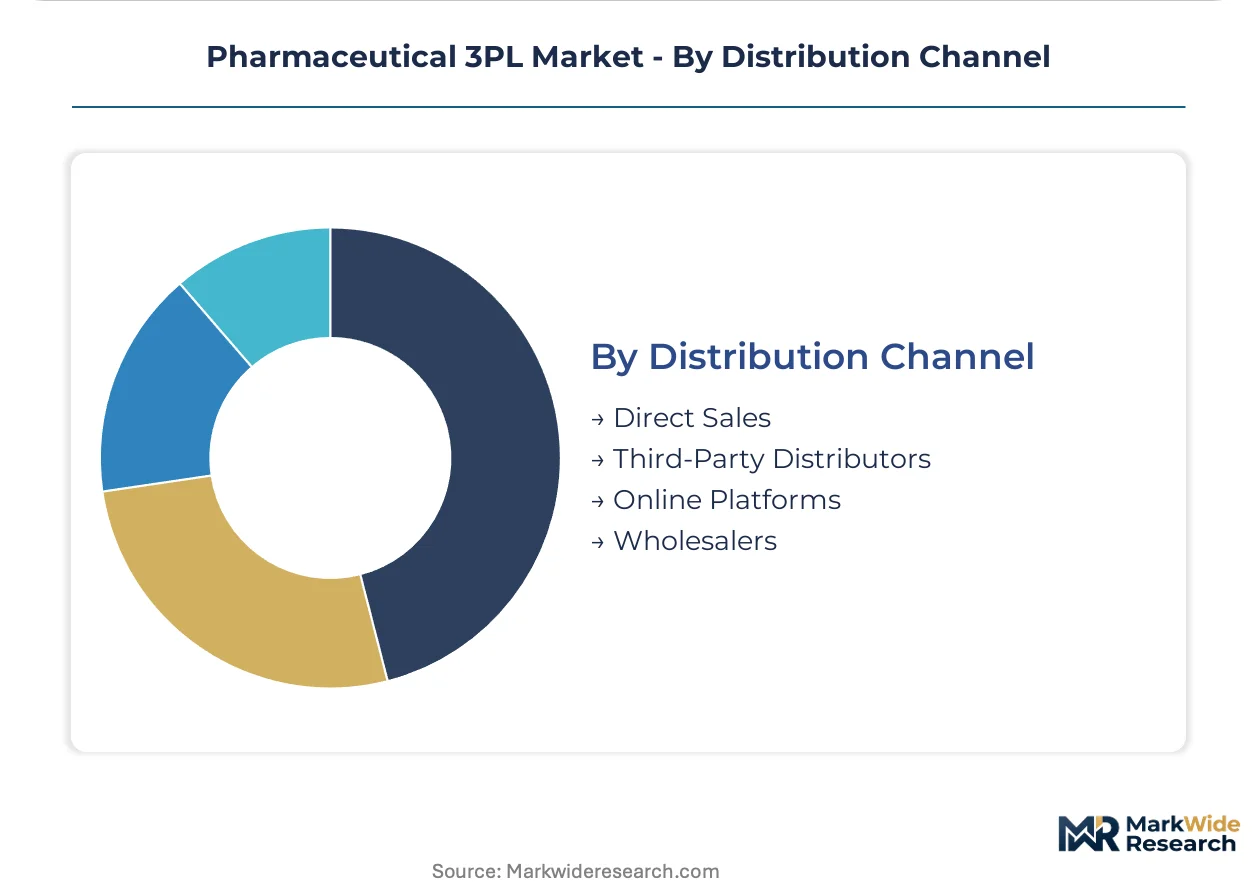
- Third-Party Distributors:Established GDP-certified networks provide regulatory navigation across divergent EU member state interpretations, though compliance duplication costs compress margins for pan-European operators.
- Direct Sales:Manufacturer-controlled relationships enable serialization mandate compliance with validated IT infrastructure.
- Wholesalers:Traditional volume aggregation faces displacement from integrated delivery network consolidation.
- Online Platforms:Direct-to-patient models require last-mile temperature integrity protocols still under development.
Mature deployment sits with wholesalers. Newer deployment is concentrated in third-party distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and special economic zones in India are concentrating pharmaceutical logistics investment through customs facilitation and infrastructure subsidies. These zones attract 3PL operators seeking streamlined cross-border clearance and temperature-controlled warehousing capacity. Regulatory harmonization initiatives in each region determine competitive positioning for contract logistics providers.
United States
FDA Drug Supply Chain Security Act mandates compel manufacturers to outsource serialization infrastructure to validated 3PL operators. The DSCSA's 2023 enforcement deadline accelerated track-and-trace capability investment across distribution networks. Integrated delivery networks in Texas and Florida are consolidating pharmacy procurement, compressing delivery windows for critical biologics to same-day requirements.
Germany
Rhine-Main logistics corridor positioning draws specialized cold chain investment from global freight forwarders serving European biopharma distribution. EU Good Distribution Practice revisions mandate continuous data logging rather than interval-based temperature monitoring, forcing container fleet retrofits. Frankfurt and Cologne clusters benefit from dense air cargo connectivity and centralized European distribution infrastructure.
India
CDSCO regulatory alignment with ICH standards positions contract manufacturers to demand GDP-compliant 3PL partnerships for regulated-market exports. Pharmaceutical export growth from Gujarat and Maharashtra is driving cold chain infrastructure investment near Mumbai and Ahmedabad ports. Special economic zone status in Hyderabad and Visakhapatnam attracts temperature-controlled warehousing development for active pharmaceutical ingredient shipments.
Switzerland
Swissmedic's stringent GDP enforcement and proximity to EU markets create dual-compliance requirements for logistics operators serving Basel and Zurich clusters. The country's pharmaceutical manufacturing concentration around Lake Geneva generates specialized cryogenic handling demand for biologics exports. Geneva and Basel airports maintain dedicated pharma cargo terminals with redundant cooling systems.
United Kingdom
MHRA post-Brexit regulatory divergence from EU GDP guidelines creates compliance duplication costs for pan-European networks serving UK-EU lanes. Heathrow's pharmaceutical cargo volumes sustain specialized cold chain infrastructure despite customs friction. The Midlands distribution corridor maintains temperature-controlled capacity serving both domestic hospital networks and re-export operations to Ireland.
Pharmaceutical 3PL Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated healthcare distributors controlling manufacturer-to-pharmacy channels while pure-play logistics operators capture international freight forwarding. The market structure concentrates around three tiers: global freight forwarders with dedicated pharmaceutical campuses, healthcare-integrated distributors with embedded compliance infrastructure, and regional specialists with lane-specific cold chain expertise. Strategic moves center on active container fleet expansion and GDP-certified warehouse network densification. Technology licensing partnerships for real-time monitoring systems represent an emerging competitive vector.
Within the global freight forwarding tier, DHL Supply Chain & Global Forwarding and Kuehne + Nagel exemplify scale-driven positioning through specialized pharmaceutical campuses and active container fleet deployment. Cardinal Health occupies a distinct position as a healthcare-integrated distributor bridging manufacturer compliance requirements with pharmacy channel delivery. These three companies represent divergent archetypes: the freight forwarder with infrastructure-heavy cold chain investment, and the integrated distributor with regulatory compliance embedded across channel control.
| Leading Market Players |
|---|
| UPS Healthcare |
| CEVA Logistics |
| DHL Supply Chain & Global Forwarding |
| Agility Logistics |
| Kerry Logistics Network |
| Kuehne + Nagel |
| DB Schenker |
| Cardinal Health |
| FedEx Logistics |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in Texas and Florida anchor demand concentration for same-day biologics delivery, compressing pricing power toward time-definite performance premiums rather than commodity warehousing rates. Contract manufacturers in India and Germany split procurement volume between GDP-certified international operators and regional specialists, creating bifurcated pricing tiers tied to regulatory validation depth rather than pure capacity scale.
Pricing Analysis
Short lead-time premiums for cryogenic CAR-T logistics command 40-60% markups over standard cold chain rates, while spot inventory availability for active container fleets enables dynamic pricing during capacity crunches. Three-tier pricing structure across GDP-certified premium, standard pharmaceutical-grade, and economy generic storage separates compliance depth from temperature range complexity. Cost compression in standard-grade warehousing is intensifying because qualified technician scarcity drives wage premiums that operators struggle to pass through. Hospital pharmacy buyers exhibit highest price sensitivity for routine generics, while cell therapy manufacturers absorb premium rates without elasticity given patient outcome dependencies.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical special economic zones are reshaping sourcing patterns, requiring foreign 3PL operators to establish local joint ventures for SEZ warehouse access. Active pharmaceutical ingredient supply draws from China, India, and Switzerland, while temperature-controlled container manufacturing rests on German and Japanese precision engineering. Single-source vulnerability concentrates in liquid nitrogen infrastructure components, where cryogenic valve and sensor suppliers number fewer than five globally. Distribution runs through manufacturer-to-hospital direct lanes for biologics, bypassing traditional wholesale aggregation in consolidated US health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical logistics is transitioning from passive cold chain monitoring to autonomous warehouse robotics, with AMR fleets displacing fixed conveyor infrastructure as biologics manufacturers reconfigure facilities for personalized medicine scale. This technology replacement cycle rewards operators who embed robotics expertise before competitor capacity hardens.
For Market Incumbents: Lock in cryogenic handling certification programs ahead of cell therapy protocol standardization, securing technician pipelines that emerging competitors cannot replicate quickly. Expand active container fleet ownership in the Rhine-Main corridor to defend lane control against freight forwarders building parallel pharmaceutical campuses. Vertical integration into real-time monitoring software reduces API dependency with legacy manufacturer WMS platforms. For New Entrants and Emerging Players: Blockchain-verified temperature documentation offers a technology-first wedge into audit-intensive EU cross-border lanes where incumbents struggle with GDP interpretation fragmentation. Target Indian pharmaceutical export corridors from Gujarat and Maharashtra, where CDSCO-aligned manufacturers demand compliant 3PL partnerships but local GDP-certified capacity remains underdeveloped. Lead with subscription-based sensor-as-a-service pricing to bypass capital-intensive container ownership barriers. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional specialists with lane-specific cryogenic expertise over asset-heavy global forwarders facing margin compression from qualified personnel scarcity. Acquisition targets should demonstrate existing GDP certification in multiple regulatory jurisdictions plus active container fleet deployment. Watch for FDA guidance finalization on cell therapy logistics protocols as the inflection signal that separates prepared operators from retrofitting laggards.| Strategic Initiative | Industry Significance |
|---|---|
| GDP-Certified Warehouse Network Expansion | EU Good Distribution Practice revisions in Germany and Switzerland mandate continuous data logging infrastructure. |
| Active Container Fleet Acquisition | Lane-agnostic temperature control reduces dependency on fixed cold chain infrastructure in variable markets. |
| Autonomous Mobile Robot Deployment | AMR navigation in cGMP environments eliminates human contamination risk for high-SKU biologics picking. |
| Cryogenic Handling Certification Program | Liquid nitrogen safety protocols and technician training address CAR-T therapy infrastructure gaps. |
| Blockchain Temperature Verification Integration | Auditable documentation satisfies simultaneous FDA and EMA inspection requirements for cross-border shipments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cold chain engineering directors, GDP compliance officers, hospital pharmacy procurement managers, and biologics supply chain executives. FDA Drug Supply Chain Security Act implementation reports, EMA Good Distribution Practice guidance documents, and IATA pharmaceutical cargo statistics provided external validation. Bottom-up facility capacity estimates and top-down pharmaceutical trade flow analysis were triangulated against operator-reported service line revenues.
Reconciliation of customs shipment volumes, air cargo pharmaceutical tonnage, and 3PL contract value disclosures informed the analytical framework across the analysis window. Segmentation modeling incorporated service type, temperature specification tier, end-user regulatory burden intensity, and regional certification cluster. CAGRs were derived from weighted capacity expansion announcements and biologics manufacturing location trends. Cryogenic infrastructure investment pipelines and cell therapy clinical trial geography shaped forward-looking supply assumptions.
Several conditions sit outside the modeled scope, including potential FDA serialization deadline extensions, abrupt EU member state GDP interpretation divergences, and breakthroughs in room-temperature biologics stabilization that would eliminate cold chain dependency. Forecasts reflect documented assumptions about regulatory enforcement continuity and biopharma manufacturing location stickiness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market