
 Pharmaceutical Plastic Packaging Market | 2026-2036
Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Plastic Packaging Market Outlook
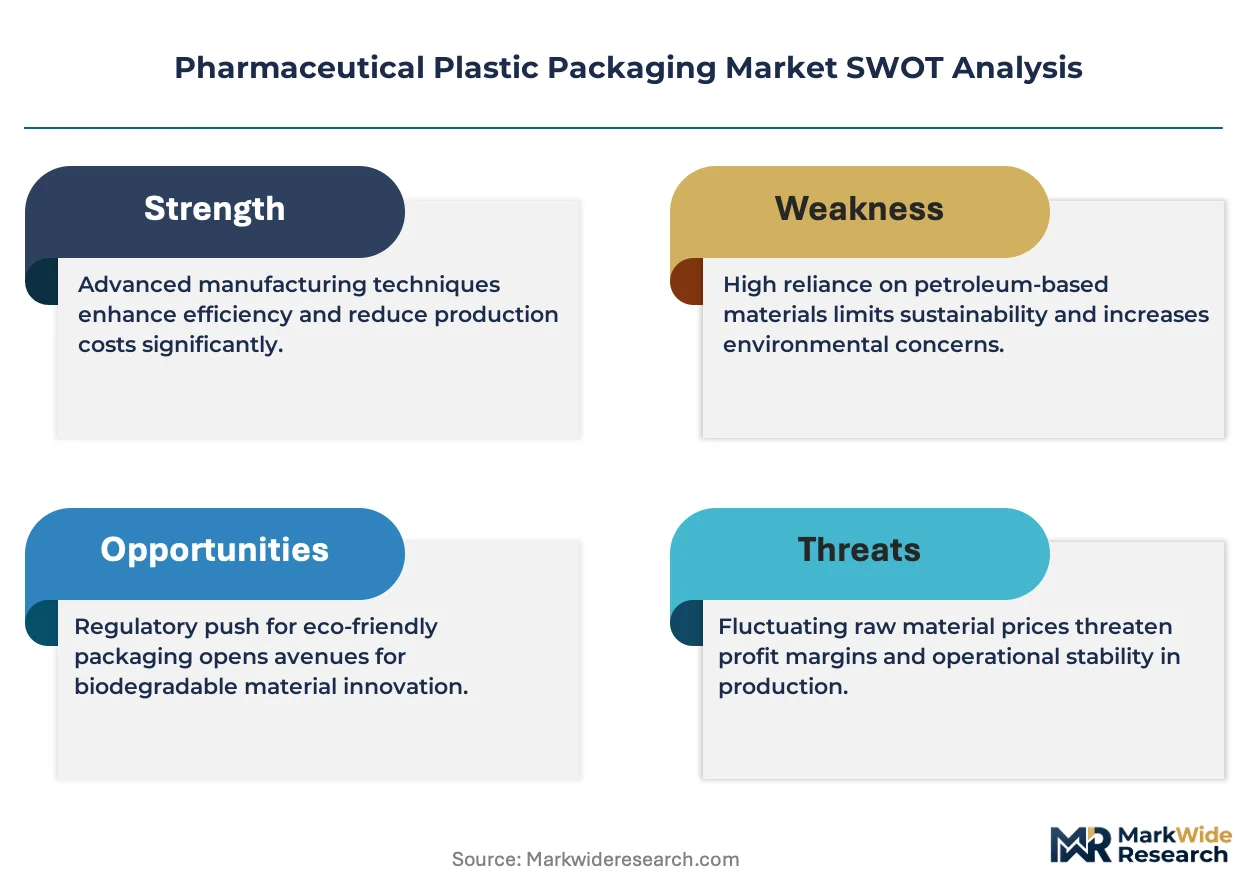
Polyethylene terephthalate is consolidating share from glass in parenteral packaging as blow-fill-seal technology cuts unit costs and breakage rates. Amcor plc leverages its multi-layer extrusion footprint across North America and Europe to capture biologics contracts. Gerresheimer AG anchors its position through deep specialization in COP/COC polymer syringes and cartridge systems for mRNA therapies. Berry Global Group, Inc. competes aggressively on scale in oral solid dose bottles, operating some of the highest-throughput injection-blow molding lines in the industry.
Pharmaceutical plastic packaging denotes polymer-based primary and secondary containment systems engineered to meet USP <661> extractables and leachables thresholds, barrier specifications for oxygen and moisture ingress, and child-resistant closure mechanics. These systems protect drug product stability from manufacture through patient administration across temperature-variable supply chains. Blister packaging dominates unit volume in oral solid dose dispensing due to its unit-dose compliance advantages and aluminum-PVC cold-form cost structure. Polypropylene is displacing PVC in respiratory device components as halogen-free material preferences intensify among European pharmaceutical companies. Oncology therapy area packaging commands premium specification tiers given cytotoxic handling protocols and the sensitivity of monoclonal antibody formulations.
The FDA enforces USP <661.1> and <661.2> standards that govern plastic packaging system qualification, directly determining which polymer grades gain formulary acceptance by major drug sponsors. The EU MDR and REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC reformulation across medical device and blister applications, redirecting R&D spend toward TPE and polyolefin alternatives. India's CDSCO has aligned with ICH Q3D elemental impurity guidelines, raising barrier-to-entry for imported packaging resins that lack certified analytical documentation. Stakeholders must monitor how polymer recycling certification schemes and mass-balance accounting rules reshape supplier qualification criteria ahead of anticipated pharmaceutical sector EPR obligations.
Market Dynamics
Biologics fill-finish capacity expansions in Germany, India, and the United States are compressing procurement cycles for high-barrier polymer systems as sterile drug manufacturers prioritize supply security over unit cost minimization.
Growth Catalysts
- EU MDR traceability mandates:Serialization upgrades across primary packaging lines accelerate replacement demand for legacy blister and vial formats throughout European pharmaceutical operations.
- Blow-fill-seal technology:Unit cost and breakage rate advantages over glass are consolidating polyethylene terephthalate share in parenteral packaging applications.
- mRNA therapy manufacturing:Cyclic olefin polymer syringe requirements from biologics producers in the United States and Germany expand specialty polymer procurement volumes.
Market Restraints
- Resin supply concentration:Polypropylene and polyethylene feedstock pricing volatility ties packaging cost structures to Gulf Coast petrochemical complex output fluctuations.
- REACH Annex XVII phthalate restrictions:PVC reformulation requirements across European medical device and blister applications redirect R&D expenditure toward thermoplastic elastomer alternatives without immediate cost parity.
- Extractables documentation burden:USP 661.1 and 661.2 qualification protocols extend polymer grade approval timelines for imported resins lacking certified analytical packages.
Strategic Opportunities
- India CDSCO ICH Q3D alignment:Elemental impurity guideline adoption creates qualification barriers for uncertified imports, advantaging domestic polymer compounders with established documentation.
- Mass-balance accounting rules:Anticipated pharmaceutical sector extended producer responsibility obligations in the European Union reshape supplier qualification criteria toward certified recycled content.
- Halogen-free respiratory devices:Polypropylene displacement of PVC in European inhaler components opens material specification windows for polymer suppliers with medical-grade polyolefin portfolios.
Industry Challenges
- Multi-layer extrusion technician scarcity:Coextrusion die tuning and barrier layer thickness control expertise concentrates among aging workforces in Germany and the United States.
- Serialization line capex intensity:FDA Drug Supply Chain Security Act compliance requires pharmaceutical packagers to deploy aggregation hardware and verification software across packaging suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Plastic Packaging Market |
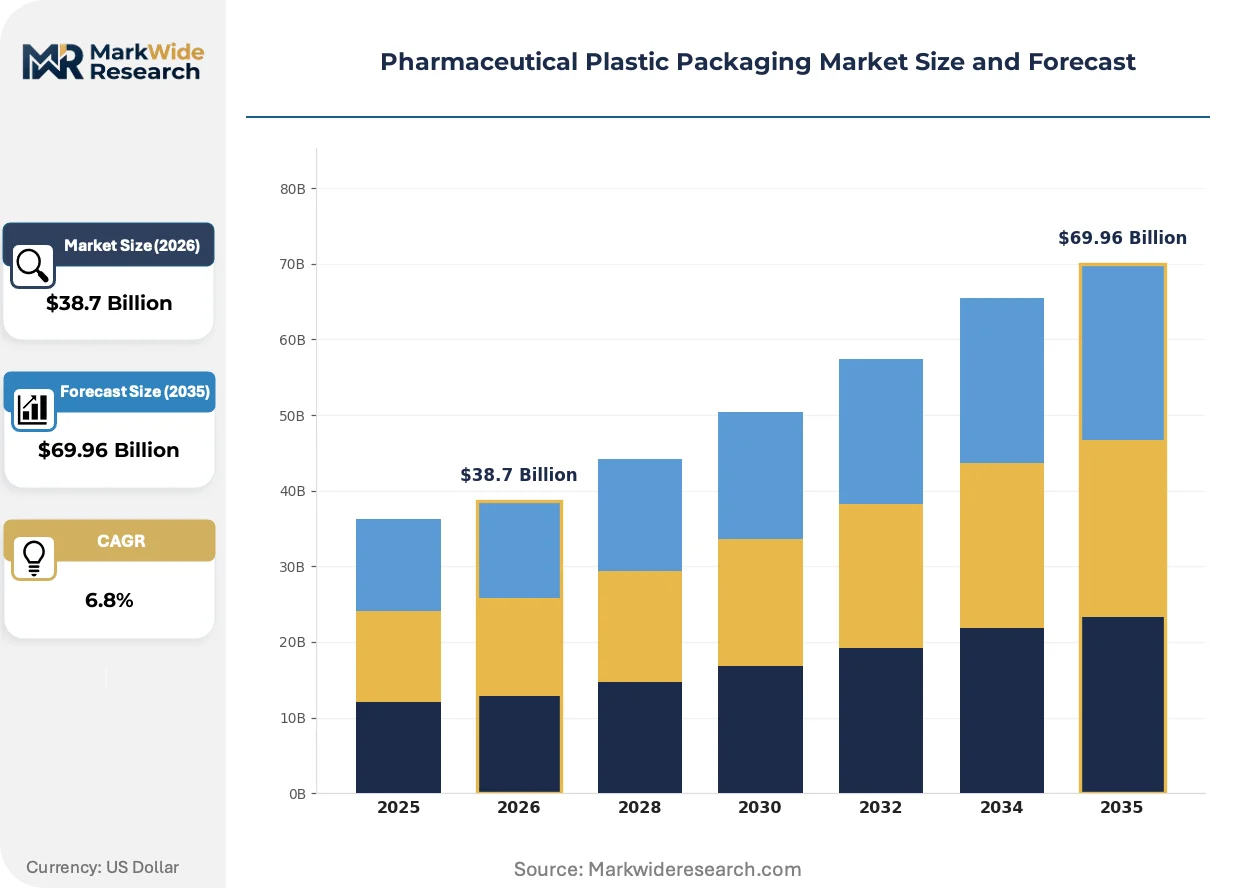
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Containers, Ampoules Material: Polyethylene, Polypropylene, PVC, PET Therapy Area: Oncology, Cardiology, Neurology, Infectious Diseases End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Pharmacies |
| Companies Covered | Amcor plc, Gerresheimer AG, AptarGroup, Inc., West Pharmaceutical Services, Inc., Berry Global Group, Inc., Schott AG, Klöckner Pentaplast Group, Mondi Group, Essel Propack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Plastic Packaging Market Strategic Shifts
Active pharmaceutical ingredient sensitivity to oxygen and moisture ingress is driving material specification upgrades across primary containment systems, with polymer engineering and regulatory compliance converging as competitive differentiators.
Multi-layer coextrusion with ethylene vinyl alcohol barrier cores is electrifying high-value biologics packaging as contract manufacturers in Germany and the United States adopt these structures for monoclonal antibody vials and cartridges. Blow-fill-seal equipment upgrades accommodate these complex wall constructions. The technology is compressing acceptable oxygen transmission rate thresholds for premium parenteral formats.
REACH Annex XVII phthalate restrictions are forcing PVC reformulation across European blister and medical device applications, redirecting compounder R&D toward thermoplastic elastomer and polyolefin alternatives. ECHA enforcement timelines compress transition windows. Oncology therapy area packaging faces the steepest specification recertification burden given cytotoxic handling protocol requirements.
Consolidated buying by large biologics sponsors is compressing supplier qualification timelines as procurement functions centralize polymer sourcing decisions across global manufacturing networks. Tier-one drug manufacturers now specify barrier performance thresholds directly rather than delegating material selection to packaging converters. This concentration is most visible in United States and German sterile fill-finish corridors where capacity expansion concentrates demand.
Pharmaceutical Plastic Packaging Market Segmentation
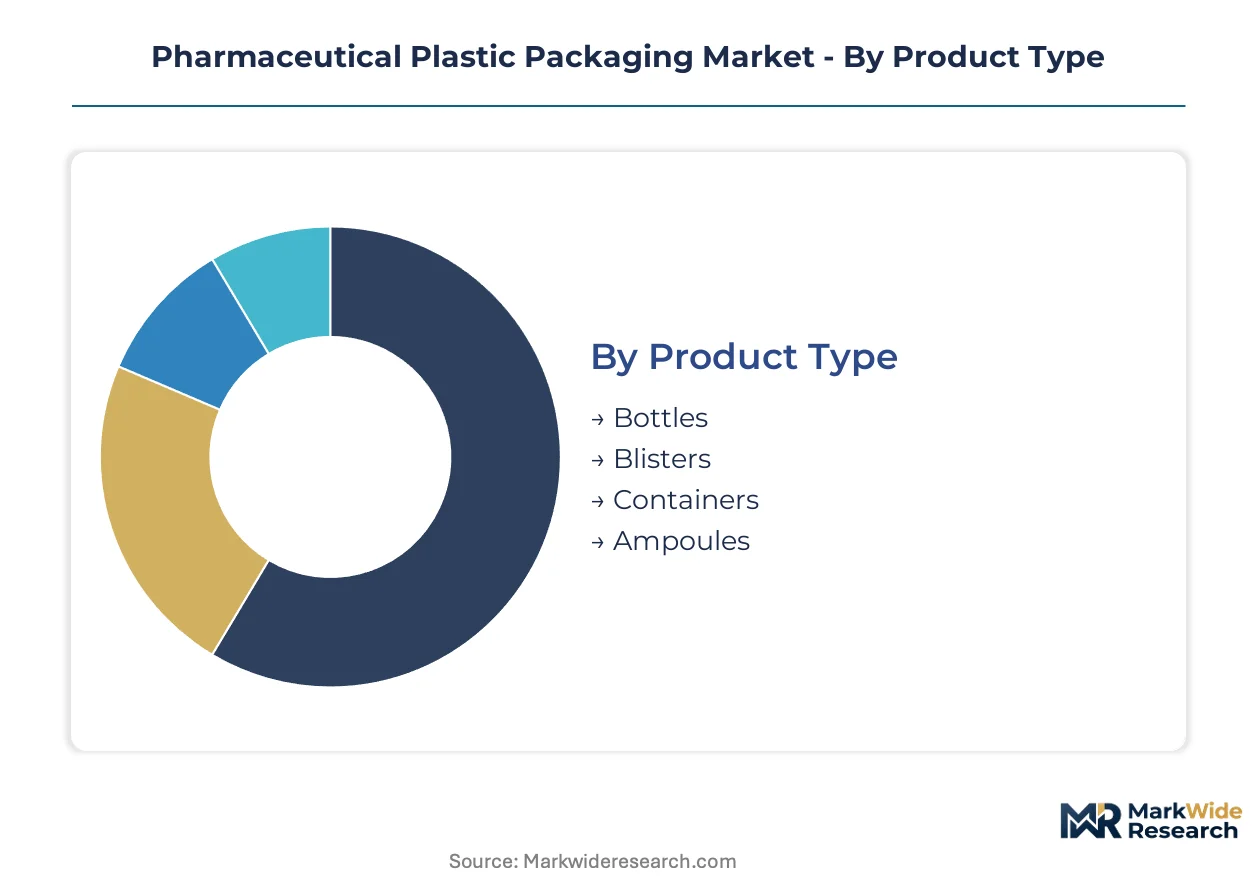
Pharmaceutical plastic packaging segmentation reveals how material specifications, therapy area requirements, and end-user procurement patterns create distinct competitive arenas. Upgrade cycles vary dramatically across these dimensions, with biologics applications driving faster replacement timelines than oral solid dose formats.
Product Type:
Replacement cycles accelerate where serialization mandates and barrier specification upgrades intersect, compressing equipment depreciation schedules for converters serving regulated markets.
- Blisters:Aluminum-PVC and aluminum-PVDC cold-form structures dominate oral solid dose dispensing through unit-dose compliance advantages. Demand concentrates in Germany and India as contract manufacturers expand high-speed thermoforming lines to serve EU MDR serialization requirements.
- Bottles:High-density polyethylene and polypropylene injection-blow molded containers serve oral liquid and solid dose formats with child-resistant closure integration. Pharmaceutical companies in the United States prioritize stock-keeping unit rationalization, driving demand for standardized neck-finish geometries across high-volume prescription fills.
- Containers:Wide-mouth polypropylene jars and pails accommodate bulk active pharmaceutical ingredient storage and hospital pharmacy compounding. Contract manufacturers specify UN-certified designs for hazardous material transport, tightening dimensional tolerance requirements.
- Ampoules:Blow-fill-seal polyethylene and polypropylene formats displace glass in parenteral applications through breakage reduction and aseptic processing integration. German sterile fill-finish corridors drive specialty polymer procurement for cytotoxic drug containment.
Volume placements concentrate in Blisters; the faster expansion belongs to Ampoules.
Material:
Cost tier differentiation separates commodity polyolefins from specialty polymers, with regulatory documentation burdens widening the procurement gap between grades.
- PET:Polyethylene terephthalate delivers clarity and oxygen barrier performance for blow-fill-seal parenteral applications through multi-layer coextrusion with EVOH cores. United States biologics manufacturers specify certified low-acetaldehyde grades for sensitive protein formulations.
- Polypropylene:This polymer displaces PVC in respiratory device components and halogen-sensitive applications across European pharmaceutical operations. India's CDSCO ICH Q3D alignment advantages domestic compounders with established elemental impurity documentation.
- Polyethylene:HDPE and LDPE grades serve cost-sensitive oral solid dose bottles and closure systems with established USP 661.1 qualification pathways. Resin pricing volatility ties packaging economics to Gulf Coast petrochemical complex output fluctuations.
- PVC:Polyvinyl chloride retains blister lidding and medical device applications despite REACH Annex XVII phthalate restrictions forcing compound reformulation. ECHA enforcement timelines compress transition windows toward thermoplastic elastomer alternatives.
Procurement volumes cluster in Polypropylene; Polyethylene faces margin compression from feedstock volatility.
Therapy Area:
Application severity dictates barrier specification tiers, with cytotoxic handling protocols and protein stability requirements creating premium material windows.
- Oncology:Monoclonal antibody and cytotoxic drug packaging commands the highest barrier specifications, with EVOH-core multi-layer structures and specialized closure systems. German and United States sterile fill-finish expansions concentrate demand for COP/COC polymer syringes and cartridges.
- Infectious Diseases:Vaccine vial and prefilled syringe requirements drive cyclic olefin polymer adoption for temperature-stable primary containment. mRNA manufacturing scale-up in the United States expands specialty polymer procurement volumes.
- Cardiology:Oral solid dose blister packs and compliance-prompting packaging dominate this therapy area, with standard aluminum-PVC cold-form cost structures. European serialization mandates accelerate line upgrades across legacy formats.
- Neurology:Prefilled pen injectors and complex delivery devices for biologic therapies require precision-molded components with tight dimensional tolerances. Contract manufacturers in Germany specialize in these high-value assemblies.
Specification intensity peaks in Oncology; Infectious Diseases applications are climbing the fastest.
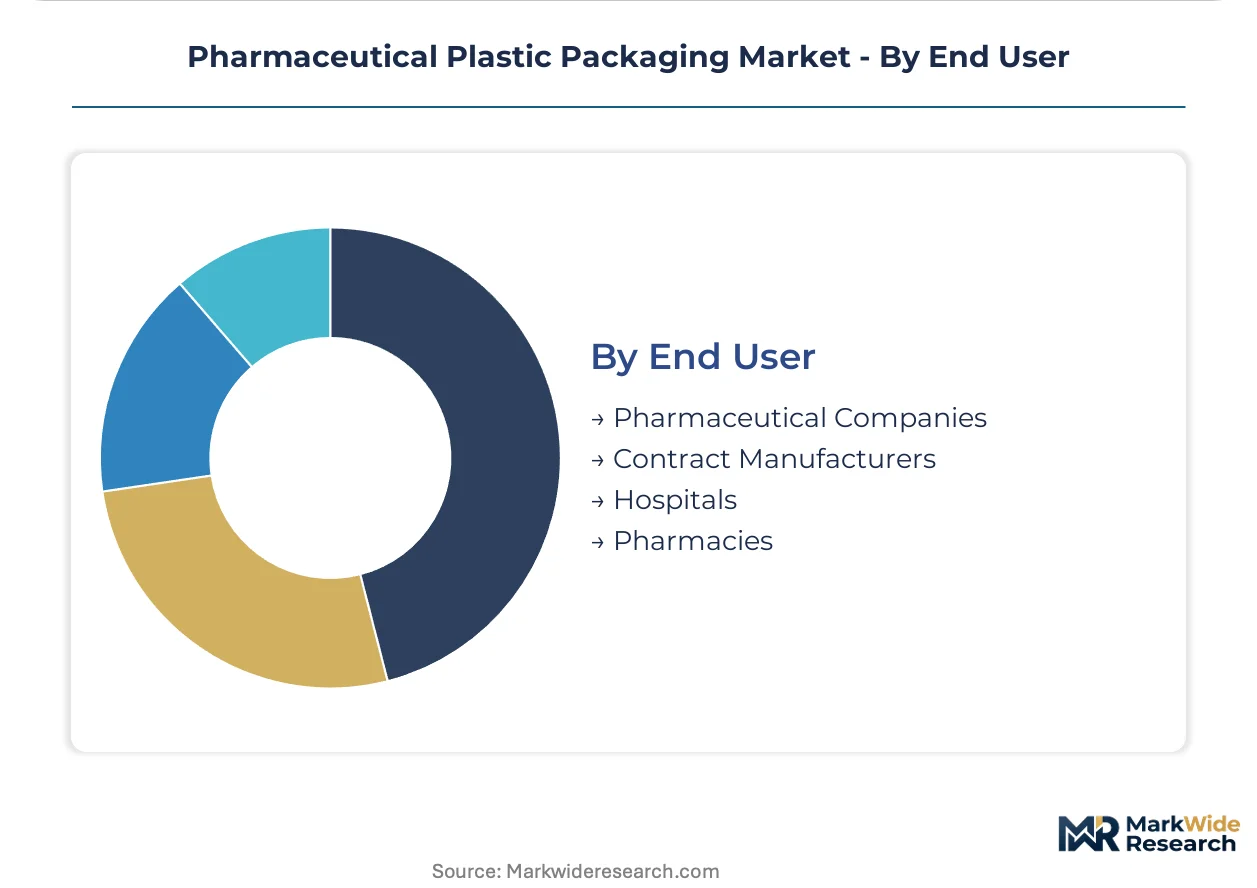
End User:
Customer type determines procurement centralization, with consolidated buying from large sponsors compressing supplier qualification timelines.
- Pharmaceutical Companies:Tier-one drug manufacturers now specify barrier performance thresholds directly rather than delegating material selection to converters. United States and German biologics sponsors drive standardization across global manufacturing networks.
- Contract Manufacturers:CDMO sterile fill-finish expansions in Germany, India, and the United States prioritize supply security over unit cost minimization, accelerating high-barrier polymer procurement cycles. Multi-layer extrusion capability concentrates qualification decisions.
- Hospitals:Pharmacy compounding and unit-dose repackaging demand drive container and closure specifications, with USP 797 aseptic handling requirements influencing primary packaging selection. Institutional procurement favors standardized stock-keeping units.
- Pharmacies:Retail dispensing focuses on compliance packaging and child-resistant closure compliance, with regional regulatory variations shaping local format preferences. Indian retail pharmacy expansion drives bottle and blister volume growth.
Procurement concentration sits with Pharmaceutical Companies; Contract Manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics fill-finish capacity expansions concentrate procurement power in Germany, India, and the United States, where sterile drug manufacturers prioritize supply security. These three markets anchor demand for high-barrier polymer systems and multi-layer extrusion capabilities.
United States
mRNA therapy manufacturing scale-up drives cyclic olefin polymer syringe procurement from specialty compounders. FDA serialization mandates under the Drug Supply Chain Security Act compress upgrade timelines for primary packaging lines. Boston and Research Triangle Park sterile fill-finish corridors concentrate demand for COP/COC cartridge systems.
Germany
Oncology monoclonal antibody packaging commands premium EVOH-core multi-layer specifications from domestic converters. EU MDR traceability requirements accelerate legacy blister format replacements across pharmaceutical operations. Baden-Württemberg and Bavaria host the densest clusters of blow-fill-seal equipment serving cytotoxic drug containment.
India
Contract manufacturing organization expansions in sterile fill-finish prioritize high-barrier polymer supply security over unit cost minimization. CDSCO alignment with ICH Q3D elemental impurity guidelines raises documentation barriers for uncertified resin imports. Maharashtra and Gujarat pharmaceutical corridors advantage domestic compounders with established analytical packages.
Switzerland
Specialty polymer syringe demand from biologics sponsors concentrates procurement decisions among qualified multi-layer extrusion suppliers. Swissmedic pharmaceutical packaging regulations enforce stringent extractables documentation for polymer primary containment systems. Basel and Zurich biotech clusters specify barrier performance thresholds directly rather than delegating material selection.
China
Domestic biologics manufacturing expansion drives qualified polymer packaging system procurement from certified compounders. NMPA pharmaceutical packaging regulations align with USP 661 extractables and leachables thresholds for imported drug applications. Yangtze River Delta pharmaceutical clusters upgrade blow-fill-seal lines to accommodate complex multi-layer wall constructions.
Pharmaceutical Plastic Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated buying from tier-one drug sponsors compressing supplier qualification timelines. The vendor base organizes around three strategic archetypes: multi-layer extrusion specialists serving biologics applications, high-throughput injection-blow molders dominating oral solid dose formats, and cyclic olefin polymer compounders capturing mRNA therapy contracts. Dominant competitive moves include backward integration into resin compounding capabilities and geographic co-location with sterile fill-finish expansions.
Within the specialty polymer tier, Gerresheimer AG and West Pharmaceutical Services, Inc. exemplify deep specialization in COP/COC syringe and cartridge systems for sensitive biologic formulations. Amcor plc anchors the multi-layer extrusion archetype through its North American and European footprint serving high-barrier biologics contracts. Berry Global Group, Inc. occupies a position at the scale-driven end of oral solid dose packaging with high-throughput injection-blow molding operations.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| AptarGroup, Inc. |
| West Pharmaceutical Services, Inc. |
| Berry Global Group, Inc. |
| Schott AG |
| Klöckner Pentaplast Group |
| Mondi Group |
| Essel Propack |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast ethylene and propylene spot indices cascade through polymer grade pricing tiers, compressing margins for converters lacking long-term resin offtake agreements while advantaging compounders with captive petrochemical supply.
Pricing Analysis
High-volume oral solid dose formats run on thin margins, while specialty multi-layer structures for biologics capture premium returns. Three-tier pricing structure across premium, standard, and economy levels separates EVOH-core barrier systems from commodity polyolefin bottles and PVC blister alternatives. Cost compression in standard-grade polyethylene stems from resin pricing volatility tied to Gulf Coast output fluctuations. Contract manufacturers serving sterile fill-finish corridors show least price sensitivity; retail pharmacy distributors in India exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with German and United States-based multi-layer extrusion equipment suppliers, where coextrusion die tuning expertise concentrates among aging workforces. Polymer resin supply draws from Saudi Arabia, South Korea, and United States Gulf Coast petrochemical complexes. Pharmaceutical-grade polypropylene and cyclic olefin polymer feedstock hinges on certified batch documentation under USP 661 protocols. Tariff exposure on imported barrier films threatens European converters. Distribution runs through qualified converter networks directly to sterile fill-finish sites, bypassing traditional distributor channels for high-barrier applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA serialization mandates and EU MDR traceability requirements force capital-intensive line upgrades, eliminating converters without balance sheet capacity for aggregation hardware deployment.
For Market Incumbents: To counter margin erosion from resin price volatility, secure backward integration into polymer compounding capabilities in India and Germany. Prioritize certification investment for USP 661.1 and 661.2 documentation to compress supplier qualification timelines for biologics contracts.
For New Entrants and Emerging Players: Launch via direct qualification with contract manufacturers in India's Maharashtra and Gujarat corridors, targeting domestic compounders with established ICH Q3D elemental impurity documentation. Focus initial penetration on halogen-free polypropylene respiratory device components where European phthalate restrictions open specification windows.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale multi-layer extrusion specialists in Germany with underutilized blow-fill-seal capacity and existing COP/COC polymer handling capabilities. Monitor CDSCO enforcement timelines for elemental impurity documentation as inflection signal for import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of pharmaceutical-grade polypropylene insulates margin from Gulf Coast price swings. |
| Multi-Layer Extrusion Capacity Expansion | EVOH-core barrier film output in Germany serves monoclonal antibody vial demand from Baden-Württemberg fill-finish sites. |
| Serialization Line Upgrade | FDA Drug Supply Chain Security Act compliance requires aggregation hardware across United States packaging suites. |
| CDSCO Certification Investment | ICH Q3D elemental impurity documentation raises entry barriers against uncertified resin imports into India. |
| Halogen-Free Material Transition | REACH Annex XVII phthalate restrictions redirect European respiratory device specifications toward polypropylene alternatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with sterile fill-finish operations managers, polymer compounder technical directors, pharmaceutical procurement leads, and CDSCO regulatory affairs specialists. Bottom-up modeling of converter capacity and resin consumption patterns was cross-validated against top-down pharmaceutical packaging expenditure estimates from FDA and EMA submission databases.
Reconciliation of production volume data, import-export statistics, and end-user procurement surveys shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, material grade, therapy area severity, and end-user procurement centralization. CAGRs were derived from fitted growth curves applied to qualified polymer demand trajectories, with specific inputs from mRNA manufacturing capacity announcements and biologics fill-finish expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for blow-fill-seal multi-layer coextrusion would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement timelines, resin supply stability, and biologics pipeline progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market