
 India Pharmaceutical Packaging Market | 2026-2036
India Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Pharmaceutical Packaging Market Outlook
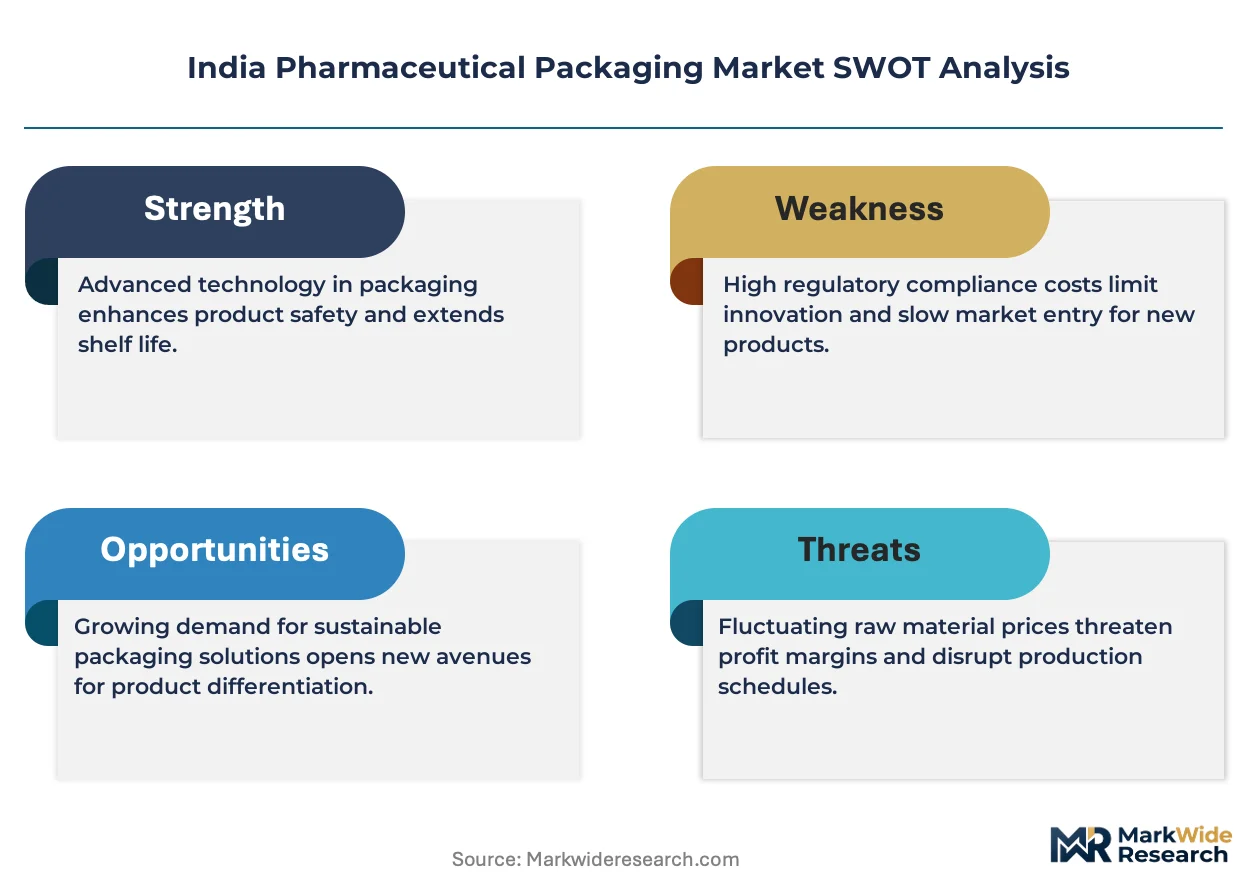
A capital-intensity divergence between integrated film producers and standalone converters is redrawing competitive boundaries in India's pharmaceutical packaging sector. ACG World leverages backward integration into aluminum foil and PVC films to sustain margin control across blister pack supply chains. UFlex Limited anchors its position through in-house production of specialized barrier films for moisture-sensitive drug formats. Parekhplast India Limited differentiates via dedicated cleanroom injection molding capacity serving domestic injectable demand.
Pharmaceutical packaging encompasses primary and secondary containment systems engineered to protect drug efficacy, ensure patient safety, and enable regulatory traceability through features such as child-resistant closures, tamper-evident seals, and oxygen transmission rates below 0.1 cc/m²/day. Blister packs dominate volume consumption due to their unit-dose precision and compliance advantages for India's chronic-disease prescription base. Plastic materials lead material demand given polyethylene terephthalate and polypropylene adaptability across oral solid and liquid formulations. Biologics represent the fastest-expanding product category, requiring cold-chain-compatible formats with validated thermal insulation performance.
CDSCO mandates barcoded serialization on export-bound drug packages, while BIS standards govern plastic container migration limits and glass hydrolytic resistance classifications. India's PLI scheme for active pharmaceutical ingredients indirectly stimulates packaging investment as domestic formulation output expands. Stakeholders must monitor evolving state-level e-pharmacy regulations and their implications for last-mile unit-dose packaging specifications.
Market Dynamics
CDSCO serialization mandates and state-level track-and-trace rules are compressing compliance timelines across India's pharmaceutical packaging value chain, forcing converters to reconfigure production lines for barcode integration and authentication features.
Growth Catalysts
- Domestic API expansion:India's PLI scheme for active pharmaceutical ingredients stimulates downstream packaging investment as formulation output scales.
- Chronic disease prevalence:Rising diabetes and cardiovascular patient bases drive unit-dose blister consumption for adherence programs.
- Maharashtra-Gujarat clustering:Dense formulation plant corridors in these states anchor concentrated procurement demand for primary packaging.
Market Restraints
- Aluminum foil import dependency:Domestic supply gaps force converters to absorb currency volatility on rolled thin-gauge inputs.
- Specialized barrier film concentration:Technical know-how for sub-0.1 cc/m²/day oxygen transmission rates sits with a narrow supplier base.
- BIS migration limit testing:Extended certification cycles for plastic container extractables delay new product commercialization.
Strategic Opportunities
- Cold-chain biologics formats:Insulin and vaccine distribution expansion creates demand for validated thermal insulation packaging.
- E-pharmacy unit-dose specs:Evolving state-level last-mile regulations open specifications for tamper-evident pouches and strip packs.
- Recyclable mono-material structures:PP and PET barrier innovations align with emerging extended producer responsibility frameworks.
Industry Challenges
- Serialization line retrofit costs:CDSCO track-and-trace compliance requires capital outlays for vision systems and aggregation software.
- Cleanroom molding technician scarcity:Injectable packaging growth outpaces trained workforce availability for aseptic filling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pharmaceutical Packaging Market |
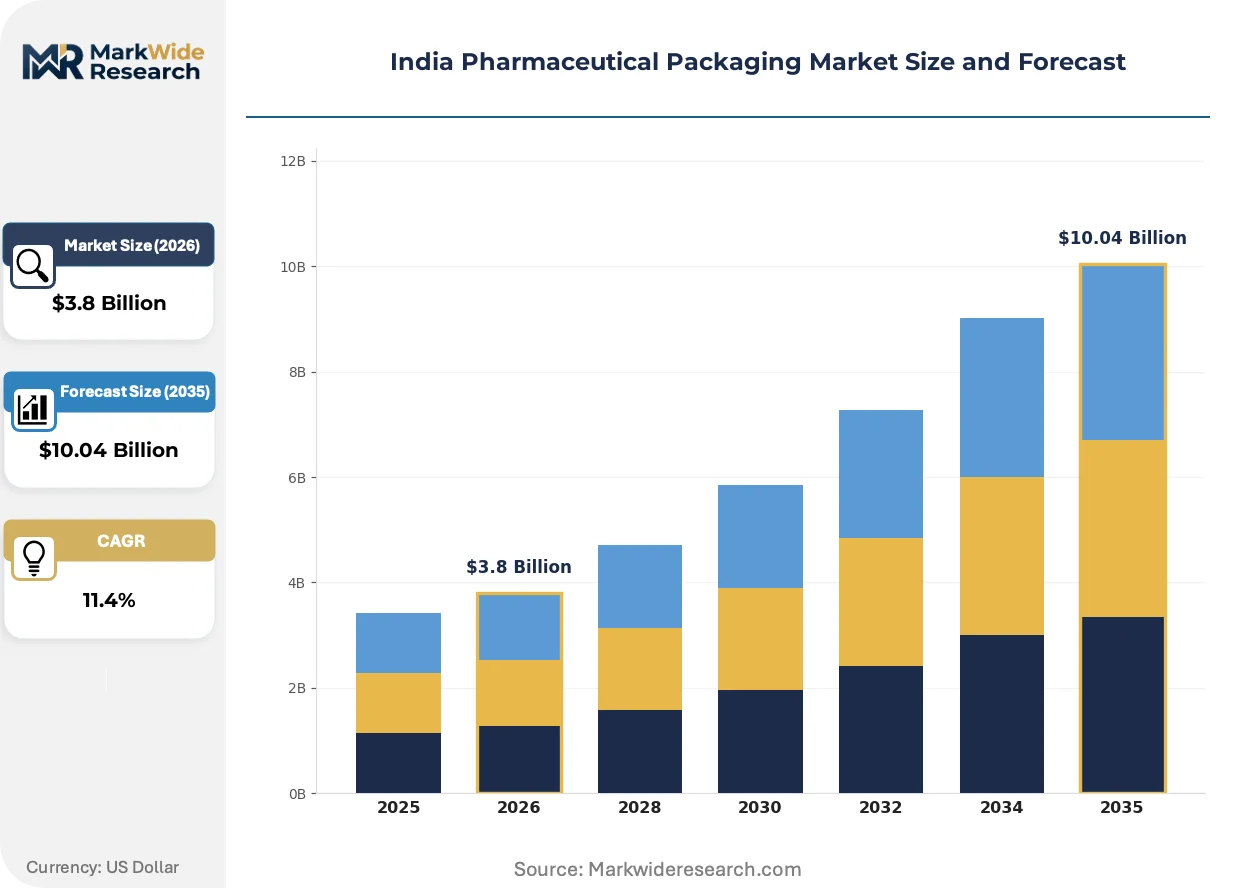
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Bottles, Cartons, Labels Material: Glass, Plastic, Aluminium, Paper End User: Hospitals, Clinics, Pharmacies, Research Labs Product Type: Prescription Drugs, Over-the-Counter, Nutraceuticals, Biologics |
| Companies Covered | EPL Limited, Nipro Medical India Pvt. Ltd., ACG World, PGP Glass, Parekhplast India Limited, Amcor plc, Huhtamaki India Ltd, UFlex Limited, AptarGroup Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pharmaceutical Packaging Market Strategic Shifts
Active barrier technologies and digital authentication layers are redefining material specifications across India's pharmaceutical packaging sector, compressing traditional supply relationships and opening new technical partnerships.
Multi-layer coextruded barrier films with embedded desiccant functionality are miniaturizing moisture protection into thinner gauge structures without compromising 0.05 cc/m²/day water vapor transmission performance. Generic drug manufacturers in Gujarat are adopting these formats at accelerated pace for hygroscopic API stability. The technology is miniaturizing packaging footprints while extending shelf life claims, enabling cost-optimized strip pack configurations for export markets.
CDSCO's barcoded serialization mandate for export-bound drug packages is forcing line-level integration of aggregation software with primary packaging equipment. Converters must now validate parent-child relationships between bottles and cases through three-tier coding hierarchies. Biologic exporters face the tightest compliance windows, with cold-chain label authentication adding thermal printer durability requirements.
Hospital and institutional procurement is consolidating toward direct converter relationships, bypassing traditional distributor networks for high-volume injectable and oncology formats. Maharashtra's tertiary care chains now specify lot-level traceability as a contract prerequisite, shifting negotiation leverage toward serialization-capable suppliers. This concentration is most visible in Mumbai-Pune corridor oncology demand, where single-source agreements cover annual blister volumes.
India Pharmaceutical Packaging Market Segmentation
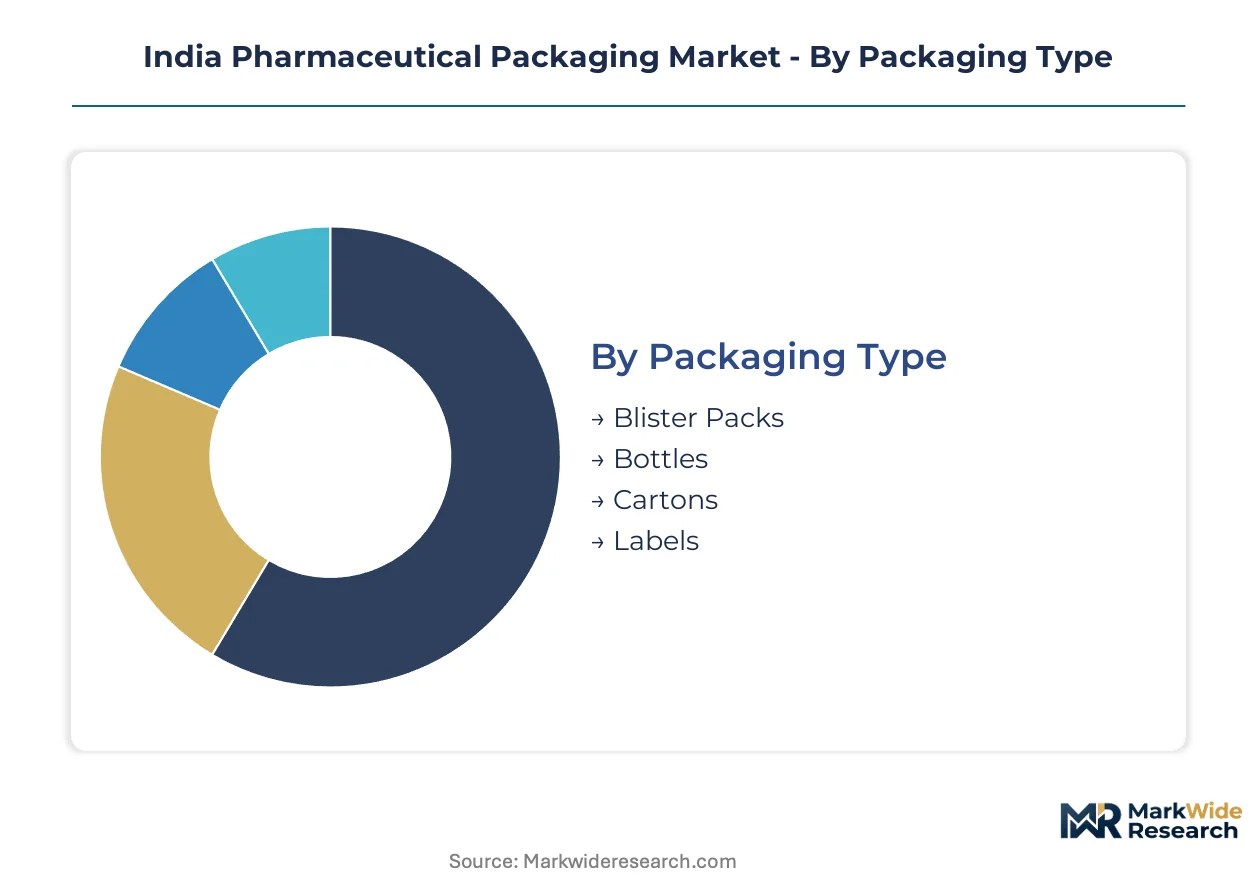
Segmentation in India's pharmaceutical packaging market reveals how domestic formulation output and export compliance requirements split demand across formats and materials. CDSCO mandates and state-level clustering create divergent procurement patterns that reshape converter specialization.
Packaging Type:
Domestic demand concentrates in unit-dose formats serving Maharashtra and Gujarat formulation corridors, while export-led procurement favors aggregation-ready bottles and cartons for CDSCO serialization compliance.
- Blister Packs:Aluminum-PVC or aluminum-aluminum cavity structures deliver unit-dose precision with child-resistant and senior-friendly opening options. Maharashtra's chronic disease prescription base drives volume procurement for diabetes and cardiovascular adherence programs, with Gujarat generic exporters adopting cost-optimized strip configurations for regulated markets.
- Bottles:HDPE and PET containers with induction seals and desiccant caps protect moisture-sensitive oral solids. Demand clusters around high-volume antibiotic and analgesic production in Himachal Pradesh and Telangana, where line speeds favor continuous capping systems over blister thermoforming cycles.
- Cartons:Folding carton structures with tamper-evident glue patterns and braille embossing for Indian labeling rules. Secondary packaging demand tracks injectable and biologic growth in Karnataka's biotech clusters.
- Labels:Pressure-sensitive and booklet formats carrying CDSCO-mandated barcodes, batch numbers, and storage conditions. Cold-chain biologics require thermal-transfer printable synthetics with validated adhesive performance.
Blister packs hold the largest share; momentum sits with bottles as high-volume generic output scales.
Material:
Cost tiers separate import-dependent specialty films from domestically extruded commodity resins, with margin pressure most acute in aluminum foil supply chains.
- Plastic:PET, HDPE, and PP dominate oral solid and liquid containment through blow-molding and injection-stretch processes. PP barrier innovations for recyclable mono-material structures align with emerging extended producer responsibility frameworks in Maharashtra and Tamil Nadu.
- Glass:Borosilicate and soda-lime formats for injectables, ampoules, and vials with hydrolytic resistance per BIS classification. Parenteral demand from Hyderabad's vaccine manufacturing base sustains Type I borosilicate procurement despite higher freight costs versus plastic alternatives.
- Aluminium:Cold-rolled thin-gauge foil for blister lidding and strip packs, with domestic supply gaps forcing converters to absorb currency volatility on imported inputs from European and Middle Eastern rolling mills.
- Paper:Folding cartonboard and patient information leaflets with serialization-ready print substrates. Secondary packaging demand concentrates in institutional procurement bypassing traditional distributor networks.
Plastic commands volume leadership; glass posts the steepest expansion trajectory on biologics growth.
End User:
Customer type determines packaging complexity tiers, with hospital procurement consolidating toward direct converter relationships and lot-level traceability prerequisites.
- Hospitals:Tertiary care chains in Mumbai-Pune corridor specify serialization-capable supply for oncology and high-value injectables, shifting negotiation leverage toward integrated converters with cleanroom molding capacity.
- Clinics:Outpatient facilities drive unit-dose blister consumption for chronic disease management programs, with procurement fragmented across regional distributors.
- Pharmacies:Retail and e-pharmacy channels generate demand for tamper-evident pouches and strip packs as state-level last-mile regulations evolve.
- Research Labs:Clinical trial materials require temperature-validated packaging with chain-of-custody documentation for investigational drug shipments.
Hospitals anchor premium pricing; e-pharmacy specifications represent the fastest-climbing demand category.
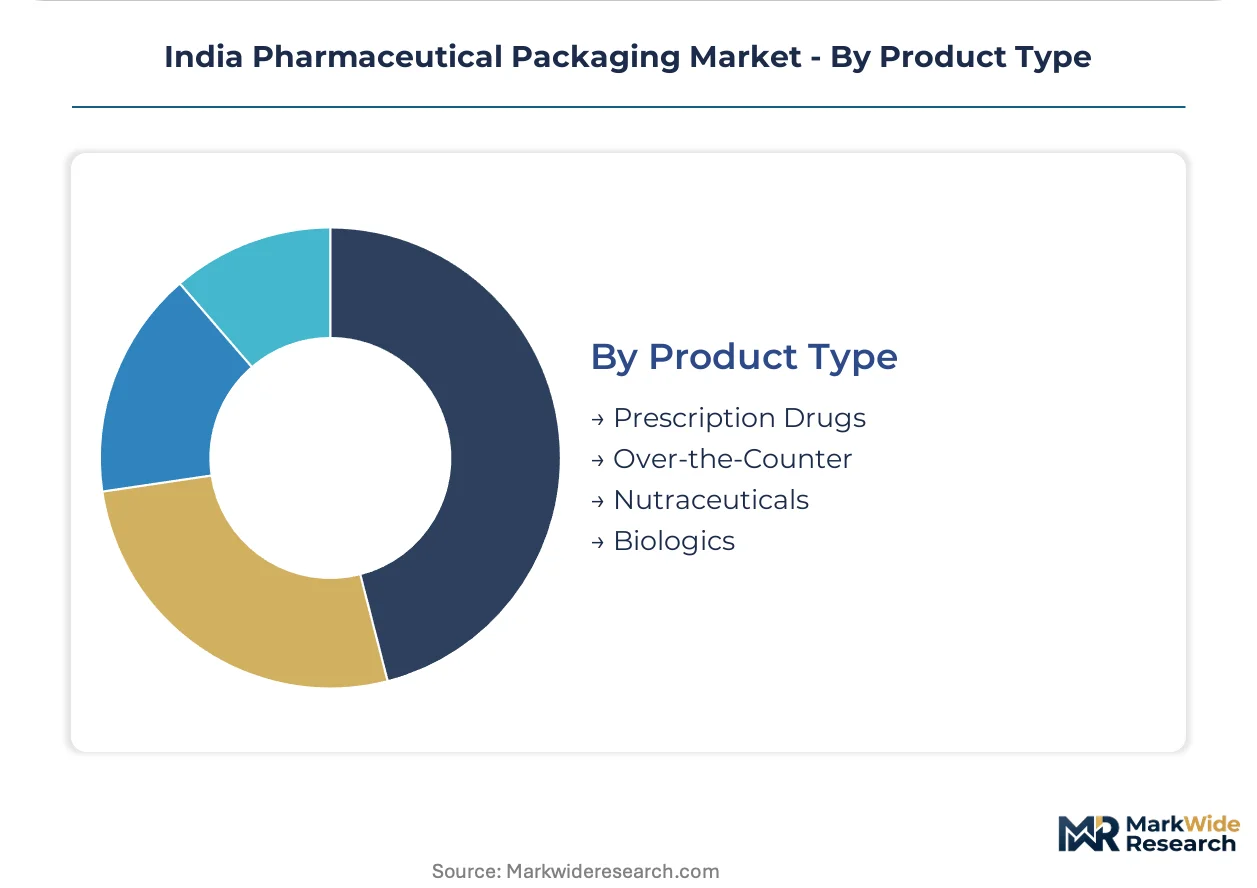
Product Type:
Maturity gradients separate established oral solid formats from emerging cold-chain requirements in temperature-sensitive biologics.
- Prescription Drugs:Chronic disease medications in blister and bottle formats dominate domestic consumption, with CDSCO serialization mandates compressing compliance timelines for export-bound shipments.
- Over-the-Counter:Analgesics, antacids, and cough-cold remedies in cost-optimized PET bottles and strip packs, with Gujarat and Himachal Pradesh formulation plants driving procurement scale.
- Nutraceuticals:Vitamins and dietary supplements requiring moisture barrier films and child-resistant closures, with demand fragmenting across direct-to-consumer and pharmacy channels.
- Biologics:Insulin, vaccines, and monoclonal antibodies demanding validated thermal insulation packaging with 2-8°C or frozen distribution profiles. Cold-chain label authentication adds thermal printer durability requirements for export compliance.
Prescription drugs maintain volume dominance; biologics gain share fastest on distribution infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns in India split sharply between export-oriented western states demanding serialization-ready formats and domestic prescription corridors favoring cost-optimized unit-dose blisters. CDSCO mandates and PLI-linked API expansion create divergent procurement intensities across sub-regional manufacturing clusters.
Maharashtra
Mumbai-Pune corridor anchors tertiary care procurement for oncology and high-value injectables. CDSCO serialization compliance forces hospital chains to specify lot-level traceability as a contract prerequisite. Dense formulation plant concentration in Nashik and Aurangabad drives blister pack demand for diabetes and cardiovascular adherence programs.
Gujarat
Ahmedabad-Vadodara belt dominates generic export output requiring aggregation-ready bottles and cartons. State-level track-and-trace rules compress compliance timelines for barcode integration. Cost-optimized strip pack configurations from Sanand and Ankleshwar clusters serve regulated European and North American markets.
Karnataka
Bengaluru biotech corridor generates cold-chain packaging demand for insulin and vaccine distribution. BIS migration limit testing governs plastic container certification for parenteral formats. Biologics manufacturing expansion in Mysuru and Mangaluru sustains Type I borosilicate glass procurement despite higher freight costs.
Telangana
Hyderabad vaccine manufacturing base drives validated thermal insulation packaging requirements. CDSCO mandates on export-bound shipments add thermal printer durability specifications for cold-chain label authentication. Bulk antibiotic and analgesic production favors continuous capping systems over blister thermoforming cycles.
Himachal Pradesh
Baddi-Barotiwala-Nalagarh belt concentrates high-volume oral solid output in HDPE and PET containers. PLI scheme stimulus for domestic APIs indirectly expands downstream packaging investment. Induction-sealed desiccant cap configurations protect moisture-sensitive formulations for northern Indian distribution.
India Pharmaceutical Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in India's pharmaceutical packaging sector. Backward integration into aluminum foil and barrier films separates margin-sustainable players from converters exposed to import volatility. Three archetypes dominate: film producers with captive resin supply, cleanroom molders serving injectable demand, and serialization-capable converters with vision system integration. Competitive moves concentrate on capacity expansion in Maharashtra-Gujarat corridors and technology licensing for cold-chain formats.
Among integrated material producers, ACG World and UFlex Limited exemplify upstream control strategies that buffer currency volatility on specialty inputs. Parekhplast India Limited occupies a position within the cleanroom molding specialist tier, serving domestic injectable requirements. These three entities represent distinct competitive vectors: backward integration into aluminum and PVC, in-house barrier film production, and dedicated aseptic capacity. Each archetype responds differently to CDSCO compliance pressures and PLI-linked formulation expansion.
| Leading Market Players |
|---|
| EPL Limited |
| Nipro Medical India Pvt. Ltd. |
| ACG World |
| PGP Glass |
| Parekhplast India Limited |
| Amcor plc |
| Huhtamaki India Ltd |
| UFlex Limited |
| AptarGroup Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for imported aluminum foil and specialized barrier films concentrate pricing power with European and Middle Eastern rolling mills, forcing Indian converters to absorb currency volatility while domestic formulation plants press for cost-optimized blister formats. This lead-time exposure shapes contract negotiations across Maharashtra and Gujarat procurement corridors, where long-term offtake agreements increasingly dominate high-volume relationships.
Pricing Analysis
Long-term offtake contracts with annual volume commitments anchor pricing for integrated film producers, while spot purchases govern secondary packaging inputs. Price differentiation rests on CDSCO serialization capability and cleanroom certification tier, with serialization-ready converters commanding premium positioning over commodity blister suppliers. Cost compression in standard blister formats intensifies as Gujarat generic exporters consolidate procurement. Hospital chains demonstrate lowest price sensitivity due to lot-level traceability mandates, while regional distributors serving outpatient clinics drive hardest bargain.
Supply Chain Analysis
Container availability constraints on Europe-India and Middle East-India trade lanes inflate inbound logistics costs for cold-rolled aluminum foil and specialized coextruded barrier films. Geographic supply concentrates in Germany, Austria, and UAE for thin-gauge foil inputs, while domestic PP and PET resin extrusion anchors commodity plastic containment. Raw material dependencies encompass aluminum rolling mill capacity, specialized desiccant-embedded films, and Type I borosilicate glass. Single-source vulnerability sits with sub-0.1 cc/m²/day oxygen transmission film know-how. Distribution runs through formulation plant clusters in Maharashtra and Gujarat before hospital and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's pharmaceutical packaging sector presents a service-attach opportunity where serialization compliance, cold-chain validation, and technical field support expand faster than base material supply. These recurring-revenue layers now determine contract renewal rates and account stickiness.
For Market Incumbents: Secure backward integration into aluminum foil and barrier film production to buffer currency volatility on imported inputs. Expand cleanroom molding capacity in Pune-Nashik corridor ahead of injectable demand acceleration. CDSCO serialization mandates threaten converters without vision system integration; prioritize aggregation software partnerships to defend hospital procurement relationships.
For New Entrants and Emerging Players: Cold-chain biologics technical service gaps offer entry points where incumbents under-serve vaccine and insulin manufacturers on thermal validation documentation. Target Karnataka and Telangana biotech clusters with validated packaging formats and on-site qualification support. Go-to-market through direct converter relationships with Bengaluru-Mysuru biologics manufacturers bypassing traditional distributor networks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because backward-integrated film producers with CDSCO-ready serialization infrastructure will absorb standalone converters exposed to import volatility. Acquisition target archetype: mid-cap converters with cleanroom capacity and Maharashtra-Gujarat geographic presence. Signal to watch: state-level e-pharmacy regulation finalization triggering last-mile unit-dose packaging specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil | Captive thin-gauge supply buffers currency exposure on European rolling mill imports. |
| Serialization Line Retrofit | CDSCO aggregation software integration secures hospital chain contract prerequisites. |
| Cold-Chain Validation Capability Buildout | Biologics distribution expansion in Karnataka demands 2-8°C thermal documentation. |
| Cleanroom Molding Capacity Expansion | Aseptic filling technician scarcity in Maharashtra creates captive workforce advantages. |
| Recyclable Mono-Material Structure Development | PP barrier innovations align with Maharashtra extended producer responsibility frameworks. |
Study Parameters
The analysis maps blister pack, bottle, carton, and label sub-sectors, each validated through procurement managers at formulation plants, regulatory affairs leads at CDSCO-registered exporters, and hospital supply chain directors across Maharashtra and Gujarat. Primary interviews with cleanroom molding technicians and barrier film R&D specialists combined with secondary validation from CDSCO export filings, BIS certification records, and PLI scheme beneficiary disclosures. Bottom-up demand modeling from formulation plant procurement data triangulated against top-down value chain estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass packaging type, material grade, end-user procurement channel, and product category regulatory cluster. CAGRs derived from annualized growth rate calculations applied to base-year estimates, with biologics cold-chain expansion and chronic disease prescription trends as key forecast inputs.
Forecasts assume regulatory continuity in CDSCO serialization mandates and state-level track-and-trace regimes; material policy shifts would require re-modeling. Aluminum import tariff adjustments, BIS migration limit testing cycle extensions, or e-pharmacy regulation accelerations represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market