
 Vials Market | 2026-2036
Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Vials Market Outlook
China is fragmenting its vial manufacturing base across multiple provincial hubs to reduce import dependence for pharmaceutical packaging. SCHOTT Pharma leverages its borosilicate glass expertise to anchor premium supply contracts with multinational drug makers. Gerresheimer AG sustains integrated production from tubing to finished vials across European and Asian plants. SGD Pharma competes through specialized molded glass capacity serving emerging market vaccine programs.
A vial is a small cylindrical container, typically manufactured from borosilicate glass Type I or pharmaceutical-grade polymers, designed to preserve sterility, chemical stability, and dosing accuracy for liquid or lyophilized drug products. Glass vials dominate therapeutic applications where inertness and barrier performance against oxygen and moisture prove critical, while plastic alternatives gain traction in diagnostics requiring breakage resistance and lower shipping costs. Pre-filled vials command premium positioning through reduced contamination risk and dosing precision, whereas multi-dose formats retain cost advantages in institutional settings with high patient throughput. Bulk vials occupy mature margin pools in compounding pharmacies and research laboratories where customization and small-batch flexibility outweigh unit economics.
The FDA enforces container closure integrity standards under cGMP guidelines, while EMA's Annex 1 revision mandates stricter particulate controls and barrier technology adoption for sterile medicinal products. ISO 15378 certification for primary packaging materials shapes supplier qualification and market access across regulated jurisdictions. Stakeholders must monitor evolving regulatory divergence between US and European sterilization validation requirements as dual-approval strategies become standard for global drug launches.
Market Dynamics
The vials market pivots on tightening sterile manufacturing standards that force material upgrades and barrier technology investments across primary packaging supply chains. EMA's Annex 1 revision and FDA cGMP updates create simultaneous compliance obligations that reshape supplier qualification and procurement patterns.
Growth Catalysts
- EMA Annex 1 Revision:Mandated barrier technology adoption for sterile medicinal products accelerates demand for pre-filled and closed-system vial formats across European fill-finish operations.
- Single-dose biologics expansion:Monoclonal antibody and cell therapy developers prioritize pre-filled glass vials to reduce contamination risk and enable point-of-care administration.
- India PLI scheme:Domestic pharmaceutical packaging incentives attract borosilicate glass tubing investments, reducing import dependence for vial manufacturing inputs.
Market Restraints
- Borosilicate glass supply concentration:Premium tubing production clusters in Germany and select Asian facilities, creating single-source vulnerability for Type I glass vial manufacturers.
- Aluminum and energy input volatility:Vial forming and printing operations face margin compression from fluctuating smelter-grade aluminum and natural gas pricing.
- Plastic vial oxygen permeability:Cyclic olefin polymer alternatives remain structurally excluded from oxygen-sensitive biologics despite breakage resistance advantages.
Strategic Opportunities
- China provincial hub fragmentation:Multiple regional manufacturing clusters emerge as pharmaceutical packaging self-sufficiency targets create distributed capacity expansion opportunities.
- ISO 15378 certification arbitrage:Suppliers achieving primary packaging material certification gain preferential access to dual US-EU approval drug launch programs.
- Lyophilization-ready vial convergence:Freeze-dry format compatibility with automated fill-finish lines opens specialized contracting with biologics CDMOs.
Industry Challenges
- Particulate control engineering talent:Sterile manufacturing barrier technology deployment outpaces trained cleanroom design and validation specialist availability.
- Dual-approval sterilization validation:Divergent US and European sterilization method acceptance criteria extend regulatory timelines for global vial format launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vials Market |
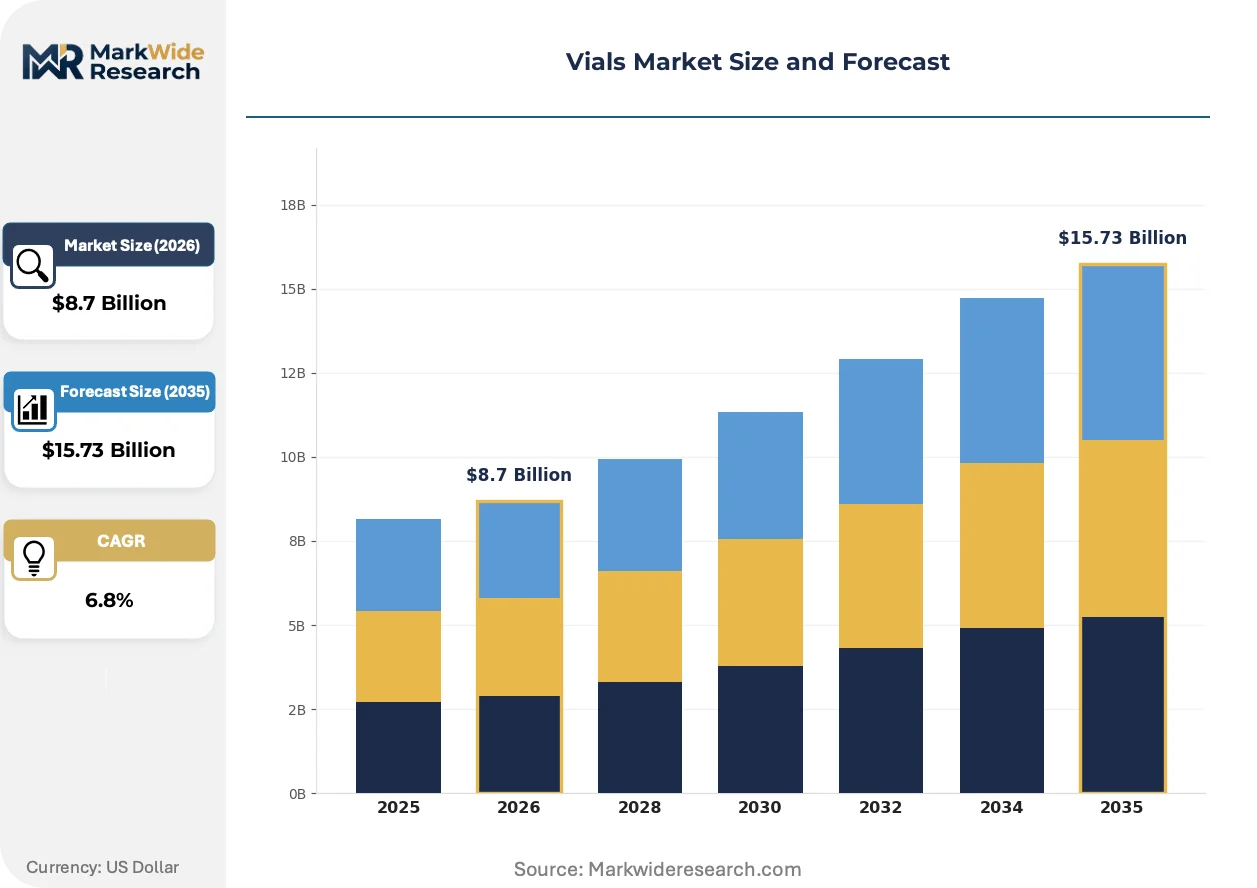
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Dose, Multi-Dose, Bulk Vials, Pre-Filled Material: Glass, Plastic, Polypropylene, Polyethylene End User: Hospitals, Pharmacies, Research Laboratories, Biotech Companies Application: Vaccines, Diagnostics, Therapeutics, Biopharmaceuticals |
| Companies Covered | Gerresheimer AG, SGD Pharma, SCHOTT Pharma, Stevanato Group, Nipro Corporation, Corning Incorporated, DWK Life Sciences, West Pharmaceutical Services, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vials Market Strategic Shifts
Barrier technology and material science advances are compressing traditional vial format hierarchies while regulatory synchronization efforts reshape competitive qualification requirements. Three developments merit specific attention.
Ready-to-use (RTU) sterile vial formats eliminate depyrogenation and sterilization steps at fill-finish sites. Biologics contract manufacturers and emerging therapy developers adopt RTU glass and polymer vials to compress batch turnaround and reduce cleanroom footprint. The technology is migrating from niche biologics applications toward mainstream small-molecule injectables as total cost of ownership models favor pre-sterilized alternatives.
EMA's Annex 1 revision mandates isolator and restricted access barrier systems for sterile medicinal product manufacturing. This regulatory pressure forces vial suppliers to demonstrate container closure integrity under stricter particulate and microbial control conditions. European fill-finish operations accelerate validation of pre-filled syringe and vial combinations that integrate primary container with delivery mechanism, compressing standalone vial demand in high-value therapeutic categories.
Hospital and clinic procurement consolidation shifts vial purchasing toward group purchasing organizations and integrated delivery networks. Large health systems in the United States negotiate multi-year supply agreements that bundle standard vial formats across therapeutic categories, displacing fragmented purchasing by individual pharmacy departments. This concentration pressures mid-tier vial suppliers to achieve GPO formulary inclusion or retreat to compounding pharmacy and research laboratory niche segments.
Vials Market Segmentation
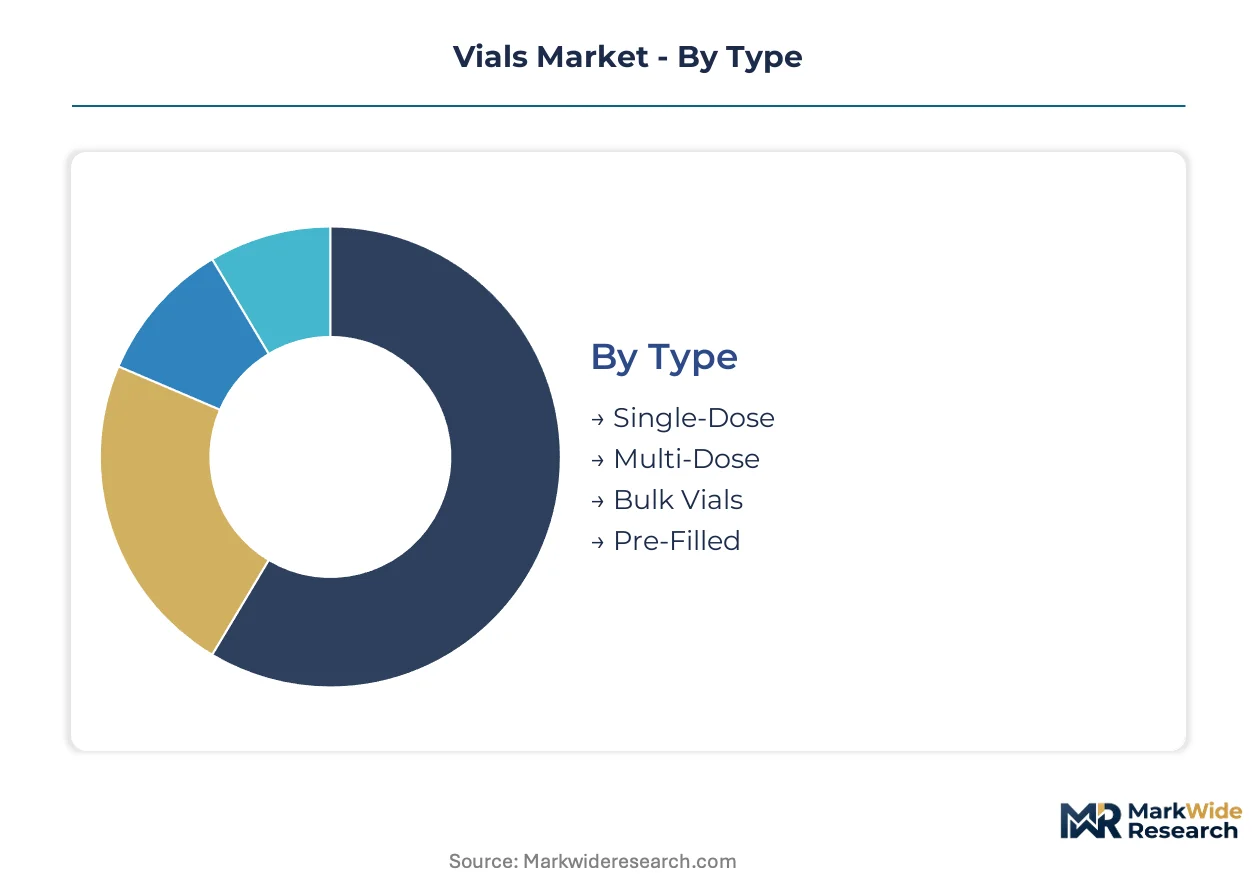
Vial format selection determines sterilization protocols, fill-finish line compatibility, and total cost of ownership across pharmaceutical packaging procurement. Segmentation reveals where premium positioning commands pricing power versus commoditized volume plays.
Type:
After-sales service intensity varies sharply by vial type, with pre-filled formats demanding technical support for fill-finish integration and multi-dose formats requiring minimal post-sale engagement.
- Single-Dose:Designed for one-time patient administration with fixed fill volumes and tamper-evident seals. Demand concentrates in oncology and autoimmune therapeutic categories where contamination risk elimination outweighs per-unit cost premiums.
- Pre-Filled:Integrate drug product with primary container at manufacturing source, eliminating compounding steps at point of care. Biotech companies in Germany and the United States prioritize these formats for monoclonal antibody launches requiring precise dosing accuracy.
- Multi-Dose:Accommodate repeated withdrawals through resealable septum designs, serving institutional settings with high patient throughput.
- Bulk Vials:Unsterilized containers for compounding pharmacies and research laboratories requiring customization flexibility.
By volume, multi-dose vials lead. By growth pace, pre-filled formats are gaining share fastest.
Material:
Cost tier stratification separates premium borosilicate glass from commodity polymer alternatives, with certification grade and barrier performance driving procurement decisions.
- Glass:Borosilicate Type I composition delivers inertness and oxygen barrier critical for biologic stability. FDA and EMA fill-finish operations in the United States and Germany specify glass for parenteral drug products where extractables control is mandatory.
- Plastic:Cyclic olefin polymers and engineered thermoplastics reduce breakage rates and shipping weight. Diagnostic applications in India favor plastic where cost sensitivity and distribution ruggedness outweigh barrier limitations.
- Polypropylene:Thermoplastic polymer with moderate chemical resistance and lower temperature tolerance than glass.
- Polyethylene:Flexible polymer option for non-sterile storage and transport applications.
Glass commands revenue share. Plastic alternatives show the steepest expansion trajectory in diagnostics.
End User:
Customer type determines order frequency, specification stringency, and contract structure across vial procurement channels.
- Biotech Companies:Development-stage and commercial biologics manufacturers specifying pre-sterilized, ready-to-use formats for clinical trial materials and commercial launches. CDMO partnerships in India and the United States drive concentrated demand for ISO 15378-certified supply.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidating procurement across therapeutic categories. United States health systems negotiate multi-year supply agreements bundling standard vial formats.
- Research Laboratories:Academic and institutional research requiring small-batch flexibility and custom specifications.
- Pharmacies:Compounding and retail pharmacy operations sourcing bulk and multi-dose formats.
Biotech companies lead by revenue contribution. Hospitals represent the fastest-growing procurement channel through GPO consolidation.
Application:
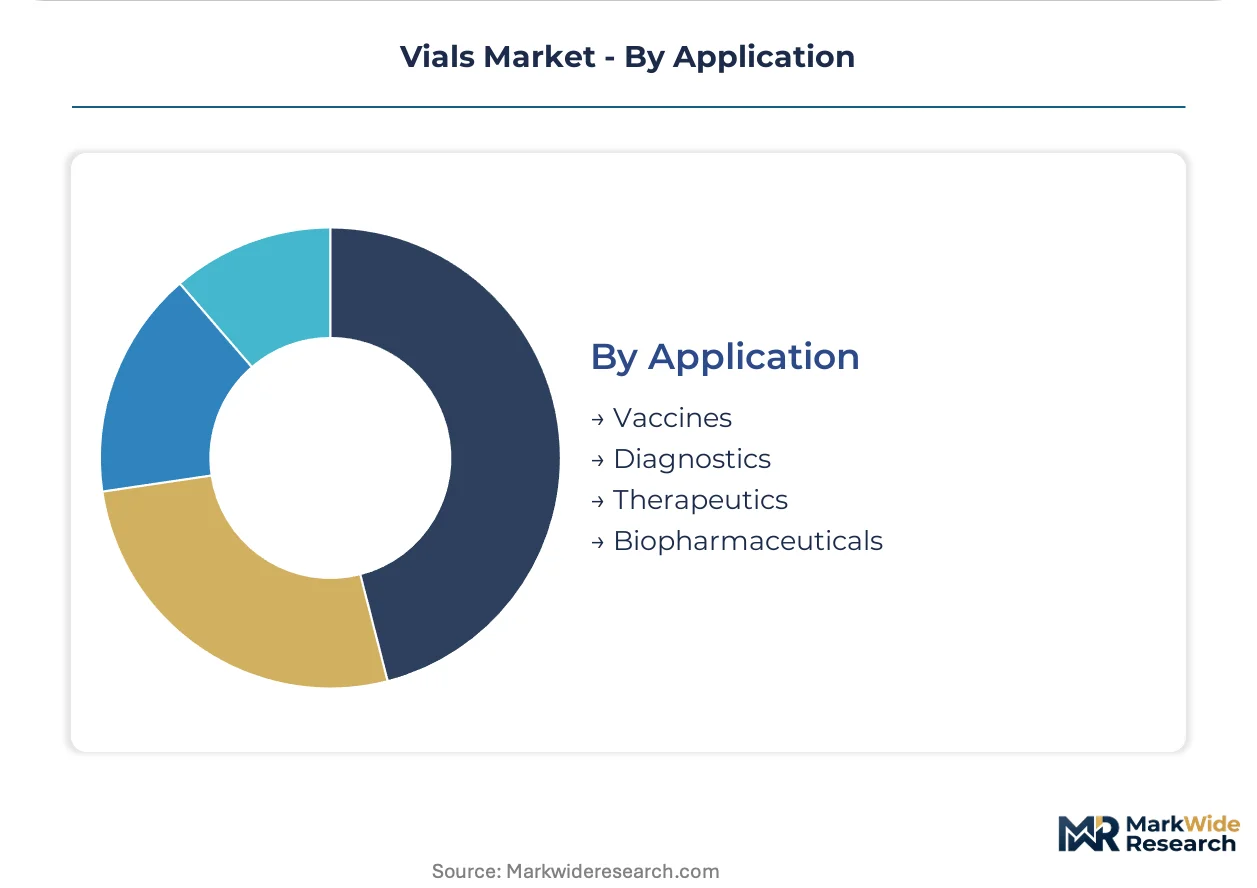
Maturity stage separates established vaccine and therapeutic segments from emerging biopharmaceutical applications with evolving format requirements.
- Biopharmaceuticals:Cell therapies, gene therapies, and monoclonal antibodies requiring specialized barrier technology and container closure integrity validation. EMA Annex 1 compliance in Germany and emerging fill-finish capacity in India concentrate demand for premium pre-filled formats.
- Vaccines:Large-volume programs with established cold chain and multi-dose format preferences. National immunization programs in India source molded glass vials through domestic manufacturing incentives.
- Therapeutics:Small-molecule and biologic drug products across chronic and acute indications.
- Diagnostics:Reagent storage and sample collection applications prioritizing breakage resistance.
Vaccines dominate by unit volume. Biopharmaceuticals are climbing the fastest on value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA container closure guidance and EMA Annex 1 revisions are synchronizing sterile manufacturing standards across major pharmaceutical markets. Fill-finish capacity expansion and regulatory stringency concentrate procurement power in specific national clusters where borosilicate glass supply and drug development pipelines align most closely.
United States
Biotech companies in Greater Boston and the San Francisco Bay Area drive pre-filled vial demand for monoclonal antibody launches. FDA cGMP updates mandate stricter container closure integrity validation for sterile injectables. Integrated delivery networks in the Midwest negotiate multi-year supply agreements bundling standard vial formats across therapeutic categories.
Germany
Specialty glass manufacturers anchor premium borosilicate tubing production serving multinational drug makers. EMA Annex 1 revision accelerates barrier technology adoption across fill-finish operations in Bavaria and Baden-Württemberg. The country's pharmaceutical packaging sector maintains integrated production from tubing to finished vials.
India
Domestic vaccine programs and CDMO partnerships concentrate demand in Maharashtra and Gujarat. The PLI scheme for pharmaceutical packaging attracts borosilicate glass tubing investments, reducing import dependence. National immunization programs source molded glass vials through manufacturing incentives targeting self-sufficiency.
China
Provincial hub fragmentation distributes vial manufacturing across multiple regional clusters to reduce import dependence. NMPA alignment with international standards shapes supplier qualification for domestic biopharmaceutical launches. Yangtze River Delta and Pearl River Delta facilities expand capacity for pre-filled and ready-to-use formats.
Japan
PMDA sterile product guidelines reinforce glass vial specifications for oxygen-sensitive biologics. Cell therapy developers in the Kanto region prioritize pre-filled formats with precise dosing accuracy. Domestic manufacturers maintain specialized capacity for high-barrier pharmaceutical packaging serving regional drug launches.
Vials Market Competitive Environment
Integrated tubing-to-vial manufacturers and specialized glass fabricators split the market between premium supply contracts and commoditized volume plays. The vendor base concentrates around three strategic archetypes: backward-integrated glass specialists with captive borosilicate supply, diversified packaging conglomerates spanning multiple primary container formats, and regional molded glass producers serving vaccine and diagnostic applications. Competitive moves center on ISO 15378 certification achievement for dual US-EU approval access and lyophilization-ready format development for biologics CDMO partnerships.
Among German-based integrated manufacturers, Gerresheimer AG and SCHOTT Pharma exemplify the backward-integrated archetype with in-house borosilicate tubing production. SGD Pharma occupies a position within the specialized molded glass tier, serving emerging market vaccine programs through differentiated capacity. These three anchors illustrate how geographic clustering around raw material access and regulatory proximity shapes competitive positioning.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SGD Pharma |
| SCHOTT Pharma |
| Stevanato Group |
| Nipro Corporation |
| Corning Incorporated |
| DWK Life Sciences |
| West Pharmaceutical Services |
| Amcor |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European borosilicate glass tubing facilities is compressing lead times and elevating pricing power for backward-integrated manufacturers serving FDA and EMA fill-finish operations. This utilization squeeze propagates through contract structures, forcing multi-year offtake commitments and certification-grade premiums that reshape procurement economics for vial converters and drug developers alike.
Pricing Analysis
German-manufactured Type I glass vials command 40-60% premiums over Indian and Chinese molded alternatives, with price differentiation anchored in ISO 15378 certification tier and barrier performance validation. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated pre-filled formats from multi-dose institutional supply and bulk unsterilized containers. Cost compression in standard-grade segments is intensifying because aluminum and natural gas input volatility erodes converter margins. Hospital group purchasing organizations exhibit highest price sensitivity, while biotech companies launching monoclonal antibodies demonstrate lowest sensitivity due to contamination risk elimination priorities.
Supply Chain Analysis
Export control regimes restricting advanced glass-forming equipment transfers to certain Asian markets are concentrating premium tubing production in Germany and Japan. Borosilicate glass vial supply draws from German tubing specialists, Indian molded glass converters, and Chinese provincial hub fabricators. Raw material dependencies center on high-purity silica sand, smelter-grade aluminum for vial forming, and pharmaceutical-grade elastomers for septum components. Single-source vulnerability in German tubing supply creates structural risk for multinational drug launches requiring dual-approval validation. Distribution runs through direct long-term contracts with biotech companies and group purchasing organization formularies for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vials market functions as a regulatory entrenchment story where ISO 15378 certification and EMA Annex 1 compliance create switching costs that lock in incumbent positions. This structural moat deepens as barrier technology investments and sterile manufacturing validation timelines extend supplier qualification cycles beyond typical procurement horizons.
For Market Incumbents: Build certification moats by accelerating ISO 15378 audit coverage across Asian manufacturing footprints before PLI scheme incentives mature domestic Indian competitors. Anchor long-term supply contracts with biotech CDMOs through lyophilization-ready format co-development, neutralizing threat from emerging Chinese provincial hub converters. Prioritize captive borosilicate tubing capacity expansion in Germany to maintain raw material leverage over standard-grade competitors. For New Entrants and Emerging Players: Mid-market diagnostic plastic vials in Southeast Asia represent the most penetrable entry point, with cyclic olefin polymer formats bypassing glass barrier limitations in reagent storage applications. Compounding pharmacy bulk vial segments in the United States offer second white-space target, where customization flexibility and small-batch agility outweigh scale economies. Go-to-market angle: position as ISO 15378-certified alternative to established suppliers for emerging biotech companies in India seeking dual-approval pathway support. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated tubing-to-vial manufacturers with captive borosilicate supply and EMA-validated barrier technology portfolios. Five-to-ten-year viability favors archetypes with demonstrated container closure integrity validation under Annex 1 revision standards. Acquisition target: mid-cap European converters with underutilized lyophilization-ready capacity and dormant ISO 15378 certifications. Signal to watch: CDMO consolidation announcements indicating preferred supplier list rationalization toward integrated packaging partners.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Acceleration | EMA and FDA dual-approval access unlocks multinational drug launch contracts. |
| Backward Integration into Tubing | Captive borosilicate supply insulates margin from German production concentration risk. |
| Lyophilization-Ready Format Development | Biologics CDMO partnerships command premium positioning in freeze-dry therapeutic segments. |
| India PLI Scheme Capacity Participation | Domestic pharmaceutical packaging incentives reduce import dependence for vial manufacturing inputs. |
| Barrier Technology Validation Investment | Annex 1 compliance mandates isolator-compatible container closure integrity for European fill-finish access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA cGMP guidance documents, EMA Annex 1 revision drafts, and pharmaceutical packaging trade data. Primary interviews engaged regulatory affairs leads at borosilicate glass manufacturers, procurement managers at biotech CDMOs, formulary directors at United States group purchasing organizations, and sterile manufacturing engineers at fill-finish operations. Secondary validation drew from ISO 15378 certification databases, CDSCO filing records, and customs import data for pharmaceutical glass tubing. Bottom-up vial volume estimates triangulated against top-down biopharmaceutical packaging expenditure benchmarks.
Forecast inputs span vial format type, material composition, end-user procurement channel, therapeutic application, and regional regulatory cluster across the analysis window. Segmentation modeling incorporates single-dose versus multi-dose preference shifts, glass versus plastic material substitution patterns, and biotech company versus hospital procurement consolidation trajectories. CAGRs derive from regression analysis against biologics pipeline expansion and sterile manufacturing capacity buildout indicators. Industry-specific inputs include EMA Annex 1 implementation timelines and India PLI scheme capacity commissioning schedules.
Stress conditions across borosilicate glass supply disruption, aluminum price volatility, and regulatory divergence between FDA sterilization validation and EMA barrier technology acceptance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fill-finish capacity expansion rates and biopharmaceutical launch cadence. Material shifts in EMA-FDA regulatory synchronization or German tubing supply consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Multi-Layer Blow Molded Containers Market
Containers
Global Styrene Compartment Boxes Market
Containers
Foldable Steel Containers Market
Containers
2 Piece Cans Market
Containers
Laboratory Sample Container Market
Containers
APAC Container Technology Market
Containers
Canning Jars Market
Containers
Stack and Nest Containers Market
Containers
PUR Containers Packaging Market
Containers
Spout Containers Market
Containers
Stackable Container Market
Containers
Collapsible Food Packaging Containers Market
Containers
Corrugated Open-Head Drums Market
Containers
Popcorn Containers Market
Containers
Grab and Go Containers Market
Containers
Conipack Pails Market