
 APAC Pharmaceutical Packaging Market | 2026-2036
APAC Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Pharmaceutical Packaging Market Outlook
India's Gujarat and Maharashtra pharmaceutical corridors is narrowing the supply-demand gap for export-grade blister and vial packaging. Amcor plc leverages its multi-layer film capacity to serve ASEAN generics exporters. Gerresheimer AG anchors high-value borosilicate glass supply for biologics fill-finish operations across Japan and South Korea. Schott AG specializes in polymer syringe and cartridge formats for mRNA vaccine cold-chain requirements.
APAC pharmaceutical packaging encompasses primary and secondary containment systems engineered to maintain drug stability, ensure patient safety, and comply with serialization mandates; specifications include moisture vapor transmission rates below 0.5 g/m²/day for tropical climates and child-resistant closure torque standards of 16-25 inch-pounds. Blister packs dominate volume due to their unit-dose compliance advantages and aluminum-barrier compatibility with India's humid monsoon distribution conditions. Glass vials capture premium margin pools in oncology and biologics segments where inert surface chemistry prevents protein aggregation. Plastic bottles sustain growth in over-the-counter cardiovascular and diabetes therapies across Southeast Asia's pharmacy retail expansion.
India's CDSCO mandates track-and-trace serialization for exported pharmaceuticals, forcing packagers to integrate aggregation-capable printing lines. China's NMPA enforces dual carbon compliance for packaging material recyclability, redirecting R&D spend toward mono-material polyethylene structures. Japan's PMDA maintains the region's most stringent particulate and extractables testing protocols for parenteral containers. Stakeholders must weigh India's cost-competitive contract manufacturing scale against Japan's premium qualification barriers when allocating regional capacity investments.
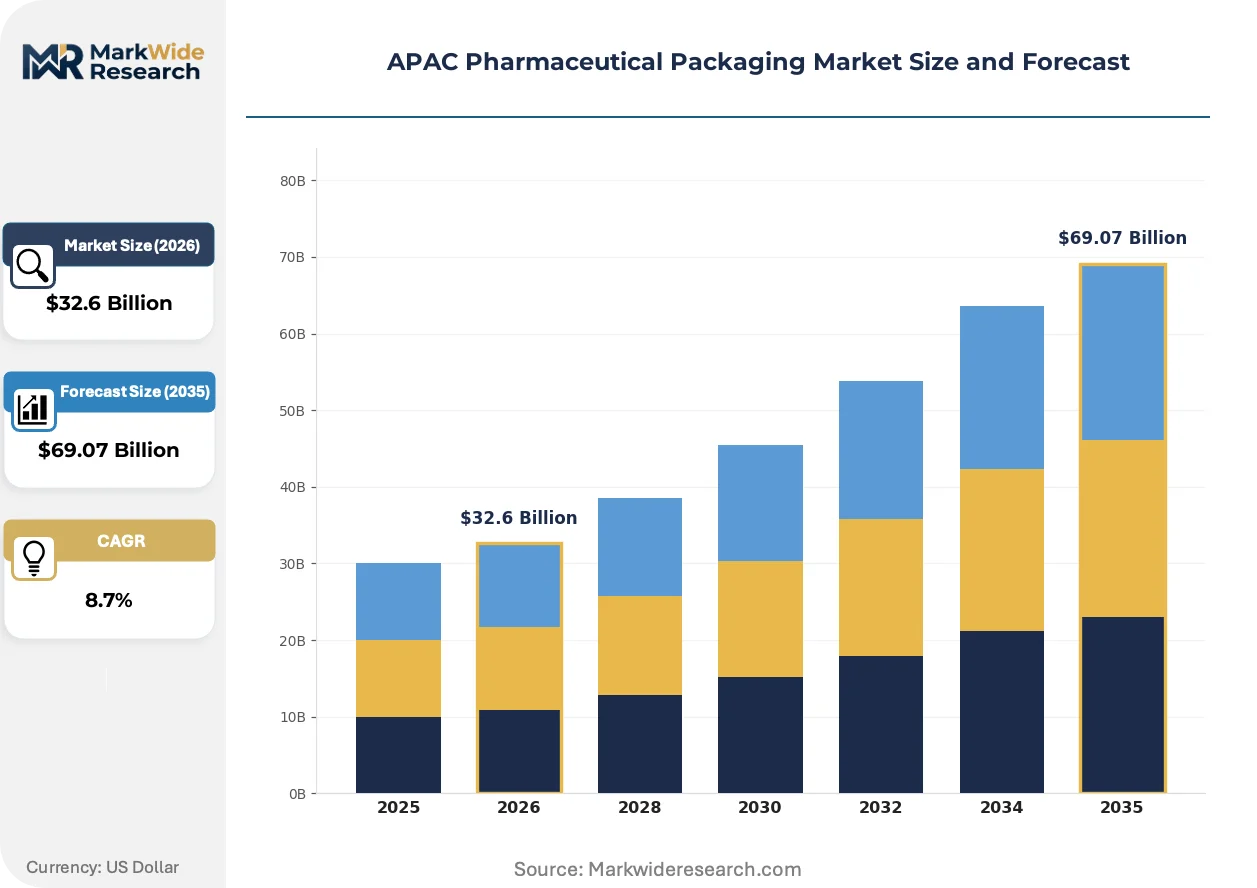
Market Dynamics
India's CDSCO serialization mandates and China's NMPA dual carbon compliance are forcing packaging converters to retool production lines simultaneously, compressing capital deployment timelines across the region's pharmaceutical manufacturing corridors.
Growth Catalysts
- CDSCO Track-and-Trace Mandate:India's export serialization requirements are pulling aggregation-capable blister and vial lines into the Maharashtra-Gujarat cluster, upgrading domestic packager technical capacity.
- mRNA Cold-Chain Expansion:Biologics fill-finish operations across Japan and South Korea are driving procurement of polymer syringe formats engineered for ultra-low temperature stability.
- ASEAN Pharmacy Retail Growth:Southeast Asia's cardiovascular and diabetes therapy distribution expansion is sustaining plastic bottle demand for over-the-counter compliance packaging.
Market Restraints
- Aluminum Barrier Supply Concentration:Tropical-grade blister foil capacity concentrates among limited South Korean and Japanese metallizers, exposing generics exporters to input volatility.
- Borosilicate Glass Technical Limitation:Premium vial chemistry requirements for oncology biologics restrict qualified supplier pools, elongating procurement lead times for fill-finish operators.
- NMPA Dual Carbon Friction:China's recyclability mandates are diverting R&D spend toward mono-material polyethylene structures before multi-layer film lines reach depreciation maturity.
Strategic Opportunities
- Vietnam Contract Manufacturing White Space:Underdeveloped local packaging converter capacity creates procurement gaps for export-oriented pharmaceutical manufacturers establishing fill-finish operations.
- Smart Packaging Convergence:Integration of printed electronics with primary containers enables real-time cold-chain monitoring for temperature-sensitive biologics distribution.
- PLI Scheme Tailwind:India's production-linked incentive framework for active pharmaceutical ingredients is pulling downstream packaging investment into integrated manufacturing zones.
Industry Challenges
- Serialization Engineering Skill Gap:Shortage of aggregation software specialists and vision-system technicians is delaying line qualification for CDSCO-compliant exporters.
- Legacy Equipment Integration Friction:Retrofitting existing blister and bottle lines with track-and-trace modules requires custom mechanical engineering, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Pharmaceutical Packaging Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Bottles, Vials, Ampoules Material: Glass, Plastic, Paper, Aluminum End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Pharmacies Therapy Area: Cardiovascular, Oncology, Neurology, Diabetes |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, AptarGroup, Inc, West Pharmaceutical Services, Inc, Nipro Corporation, CCL Industries Inc, Berry Global Group Inc, Parekhplast India Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Pharmaceutical Packaging Market Strategic Shifts
Multi-layer barrier films and connected packaging technologies are actively displacing conventional single-material structures, while regulatory pressure on recyclability accelerates format innovation cycles across primary and secondary containment systems.
Mono-material polyethylene structures are hybridizing with high-barrier coatings to maintain moisture vapor transmission performance below 0.5 g/m²/day while satisfying NMPA recyclability mandates. Generics exporters in India's humid distribution corridors are piloting these formats at accelerated qualification timelines. The technology is hybridizing cost-positioning for mid-tier blister applications previously served by aluminum-PVC laminates.
Japan's PMDA maintains the region's most stringent particulate and extractables testing protocols for parenteral containers, forcing borosilicate glass suppliers to upgrade surface chemistry certification documentation. Oncology and biologics segments face elongated qualification timelines as a result. Japanese fill-finish operators are responding by consolidating supplier relationships with pre-qualified European and domestic glass converters.
Buyer concentration among India's top ten contract drug manufacturers is compressing procurement cycles for export-grade primary packaging. Direct sourcing relationships are displacing traditional distributor intermediaries in the Maharashtra-Gujarat corridor. This pattern is most visible in high-volume blister and vial categories where technical specification alignment requires packager-manufacturer co-development.
APAC Pharmaceutical Packaging Market Segmentation
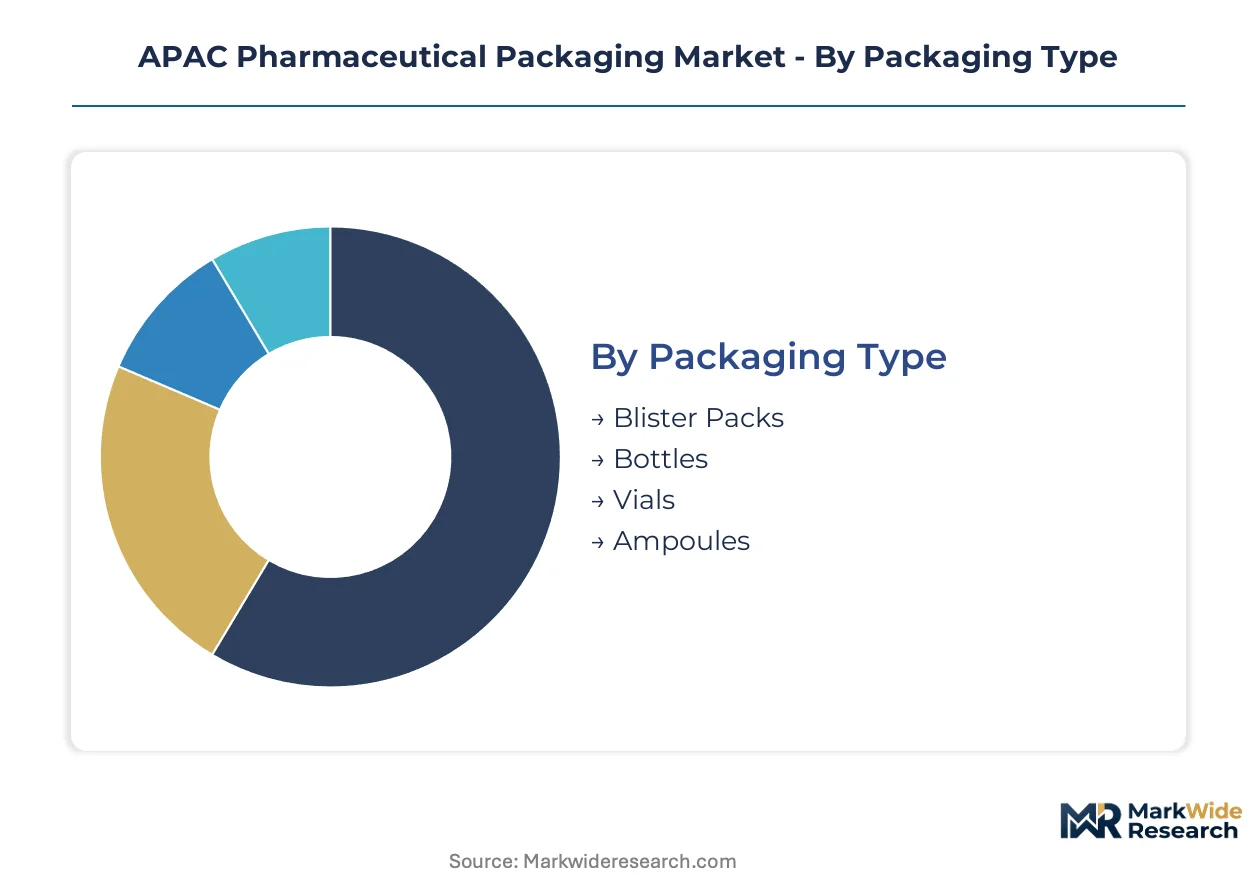
Packaging format selection in APAC pharmaceutical markets hinges on climate resilience, regulatory serialization compatibility, and cold-chain infrastructure maturity. Material and end-user segmentation reveals divergent investment cycles between tropical generics corridors and precision biologics manufacturing zones.
Packaging Type:
Cycle times vary dramatically: blister lines refresh every 3-5 years for serialization upgrades, while glass vial assets depreciate over 15 years with incremental coating improvements.
- Blister Packs:Aluminum-PVC laminates with moisture vapor transmission barriers below 0.5 g/m²/day dominate India's Maharashtra-Gujarat export corridors. CDSCO serialization mandates are forcing aggregation-capable printing retrofits across domestic converter capacity.
- Vials:Borosilicate glass with inert surface chemistry prevents protein aggregation in oncology and biologics fill-finish operations across Japan and South Korea. PMDA particulate testing protocols elongate supplier qualification timelines.
- Bottles:HDPE and PET containers serve Southeast Asia's over-the-counter cardiovascular and diabetes therapy expansion through pharmacy retail networks.
- Ampoules:Glass break-seal formats retain niche demand in emergency injectable and anesthetic applications across hospital procurement channels.
Blister packs dominate installed base. Vials are where expansion concentrates.
Material:
Cost tiers stratify sharply: commodity plastics serve volume generics, while technical glass and multi-layer films command 4-6x unit premiums in regulated biologics segments.
- Glass:Type I borosilicate vials and syringes anchor premium parenteral containment for mRNA cold-chain requirements across Japanese and South Korean fill-finish operations.
- Plastic:Mono-material polyethylene structures are displacing multi-layer films in China's NMPA-compliant recyclability push, with barrier coating R&D accelerating qualification timelines.
- Aluminum:Tropical-grade blister foil capacity concentrates among limited South Korean and Japanese metallizers, exposing Indian generics exporters to input price volatility.
- Paper:Secondary cartons and serialization labels integrate track-and-trace codes for CDSCO export compliance, with fiber-based formats gaining share in China's dual carbon packaging mandates.
Plastic captures volume share. Glass commands margin expansion.
End User:
Customer type determines specification intensity: contract manufacturers demand flexible format switching, while integrated pharmaceutical companies prioritize captive supply security.
- Pharmaceutical Companies:India's top ten contract drug manufacturers are compressing procurement cycles through direct packager relationships, displacing traditional distributor intermediaries in blister and vial categories.
- Contract Manufacturers:Fill-finish operators across Vietnam's emerging pharmaceutical zones face underdeveloped local converter capacity, creating white-space procurement gaps for imported primary containment.
- Hospitals:Institutional procurement of unit-dose blister and ampoule formats emphasizes tamper-evidence and child-resistant closure torque standards of 16-25 inch-pounds.
- Pharmacies:Southeast Asia's retail pharmacy expansion drives plastic bottle demand for over-the-counter cardiovascular and diabetes therapy compliance packaging.
Pharmaceutical companies anchor demand scale. Contract manufacturers are climbing the fastest.
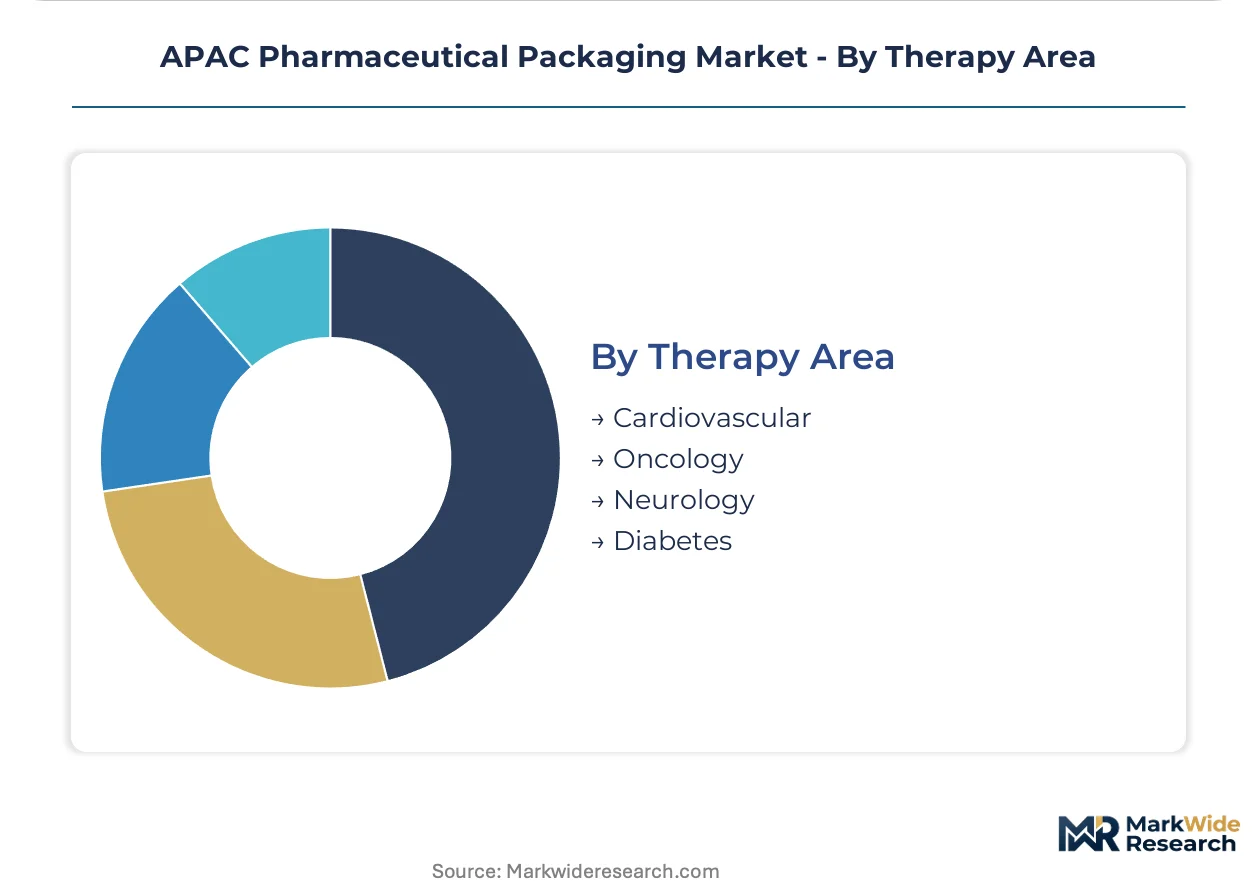
Therapy Area:
Application maturity diverges: cardiovascular and diabetes therapies leverage established plastic bottle infrastructure, while oncology and neurology biologics require unproven cold-chain polymer formats.
- Oncology:Premium vial chemistry requirements restrict qualified borosilicate glass supplier pools, with Japanese fill-finish operators consolidating pre-qualified European and domestic converter relationships.
- Diabetes:Pen injector cartridges and vials sustain dual-format demand across India's insulin manufacturing base and Southeast Asia's pharmacy retail channels.
- Cardiovascular:High-volume tablet and capsule blister packs serve India's generics export engine and domestic chronic therapy compliance programs.
- Neurology:CNS biologics and long-acting injectables drive polymer syringe procurement for ultra-low temperature stability requirements in Japanese and South Korean distribution networks.
Cardiovascular commands volume leadership. Oncology represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity across APAC clusters unevenly, with tropical-grade foil metallizers in South Korea and Japan supplying India's humid-distribution corridors while China's recyclability mandates redirect polymer R&D spend toward mono-material structures.
India
CDSCO serialization mandates for export-grade pharmaceuticals are forcing aggregation-capable printing retrofits across Maharashtra-Gujarat blister and vial lines. The country's PLI scheme for active pharmaceutical ingredients is pulling downstream packaging investment into integrated manufacturing zones near Ahmedabad and Mumbai.
China
NMPA dual carbon compliance requirements are diverting converter R&D toward mono-material polyethylene structures before multi-layer film assets reach depreciation maturity. Jiangsu-Zhejiang pharmaceutical corridors face compressed capital deployment timelines as packagers retool for recyclability standards simultaneously with track-and-trace integration.
Japan
PMDA particulate and extractables testing protocols for parenteral containers maintain the region's most stringent qualification barriers, elongating borosilicate glass supplier approval timelines. Fill-finish operators across Kanto and Kansai regions are consolidating pre-qualified domestic and European converter relationships to secure oncology biologics containment.
South Korea
MFDS regulatory alignment with international standards supports polymer syringe procurement for mRNA vaccine cold-chain distribution networks. Seoul-Incheon pharmaceutical manufacturing zones are scaling ultra-low temperature stability packaging formats alongside Japanese biologics fill-finish partners.
Vietnam
Underdeveloped local packaging converter capacity creates procurement white space for export-oriented pharmaceutical manufacturers establishing fill-finish operations. Ho Chi Minh City and Hanoi pharmaceutical zones rely on imported primary containment as domestic technical infrastructure lags regional compliance requirements.
APAC Pharmaceutical Packaging Market Competitive Environment
Multi-layer film specialists and borosilicate glass fabricators split the market between tropical generics corridors and precision biologics zones. The vendor base concentrates among Asia-Pacific headquartered converters with European technical partnerships, plus German and Swiss material science specialists maintaining premium qualification documentation. Three archetypes dominate: tropical-climate blister engineers, cold-chain polymer formulators, and high-barrier glass chemists. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as serialization mandates compress deployment timelines.
Among Asia-Pacific headquartered converters, Amcor plc and Nipro Corporation exemplify the scale-driven multi-material archetype, while Gerresheimer AG and Schott AG anchor the European-heritage premium containment tier. These four occupy positions spanning tropical-grade barrier films through ultra-low temperature polymer syringes, with each representing distinct technical qualification pathways for CDSCO, NMPA, and PMDA compliance requirements.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| AptarGroup, Inc |
| West Pharmaceutical Services, Inc |
| Nipro Corporation |
| CCL Industries Inc |
| Berry Global Group Inc |
| Parekhplast India Ltd |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo container freight corridors transmit aluminum foil and borosilicate glass cost volatility directly into Maharashtra-Gujarat packager procurement budgets, compressing margin buffers for CDSCO-compliant exporters while amplifying price differentiation between tropical-grade barrier films and cold-chain polymer formats.
Pricing Analysis
NMPA dual carbon compliance dictates the pricing tier structure across China's Jiangsu-Zhejiang pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified borosilicate glass from mono-material polyethylene recyclability-compliant films and commodity PVC blister substrates. Cost compression in standard-tier multi-layer films is intensifying because converters must retire assets before depreciation maturity. India's contract drug manufacturers exhibit highest price sensitivity due to direct sourcing consolidation, while Japanese fill-finish operators accept premium tiers for pre-qualified supplier security.
Supply Chain Analysis
Upstream feedstock flows for tropical-grade aluminum barrier foil concentrate in South Korean and Japanese metallizer capacity, with Type I borosilicate glass drawing from German and domestic Japanese fabricators. Raw material dependencies span aluminum ingot, pharmaceutical-grade polyethylene resin, and borosilicate silica sand. Single-source vulnerability concentrates in South Korean foil supply serving India's humid-distribution corridors. Distribution runs through direct packager-manufacturer relationships in Maharashtra-Gujarat, displacing traditional distributor intermediaries for high-volume blister and vial categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a platform-economics inflection where serialization aggregation software and connected cold-chain monitoring devices create interoperability lock-in between packager technical capacity and pharmaceutical manufacturer compliance systems.
For Market Incumbents: Harden aggregation-capable printing line deployments across Maharashtra-Gujarat before CDSCO enforcement deadlines compress qualification windows. Deepen backward integration into tropical-grade aluminum foil metallizing through South Korean joint ventures to secure input cost stability against spot market volatility. For New Entrants and Emerging Players: Vietnam's underdeveloped local converter capacity represents the most penetrable entry point for export-oriented pharmaceutical manufacturers establishing fill-finish operations. Smart packaging convergence integrating printed electronics with primary containers offers a differentiated go-to-market angle for temperature-sensitive biologics distribution. For Investors and Strategic Acquirers: Specialist serialization engineering firms with aggregation software capabilities and vision-system technician training platforms anchor acquisition priority. Long-term viability across the analysis window rests on regulatory compliance automation scale rather than commodity format manufacturing. Monitor CDSCO enforcement action intensity as inflection indicator for packager consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Aggregation-Capable Line Retrofit | CDSCO serialization mandates force capital deployment ahead of depreciation cycles in Maharashtra-Gujarat. |
| Mono-Material Polyethylene R&D | NMPA recyclability compliance redirects technical spend from multi-layer film assets in Jiangsu-Zhejiang. |
| Pre-Qualified Glass Supplier Consolidation | PMDA particulate testing protocols elongate approval timelines, favoring captive European-Japanese relationships. |
| Cold-Chain Polymer Syringe Scale-Up | MFDS-aligned mRNA distribution networks in Seoul-Incheon drive ultra-low temperature format procurement. |
| Smart Packaging Technology Licensing | Printed electronics integration enables real-time temperature monitoring for Japanese biologics distribution. |
Study Parameters
The analysis maps primary containment formats, secondary serialization systems, and cold-chain distribution technologies, each validated through regulatory affairs leads at CDSCO and NMPA, fill-finish operations directors across Japan and South Korea, and procurement managers at India's top ten contract drug manufacturers. Primary interview data triangulates against secondary sources including CDSCO export compliance filings, NMPA dual carbon implementation guidelines, PMDA pharmaceutical packaging guidance documents, and MFDS cold-chain distribution standards. Bottom-up packager capacity modeling and top-down pharmaceutical manufacturing output projections reconcile through iterative stakeholder feedback loops.
Assumptions held fixed include CDSCO serialization mandate enforcement timelines, NMPA recyclability percentage thresholds, and PMDA particulate testing protocol stringency, while aluminum foil input costs, polymer resin pricing, and freight corridor rates varied across sensitivity scenarios. Segmentation dimensions span packaging type, material chemistry, end-user archetype, and therapy area, with regional regulatory cluster as an additional modeling layer. CAGRs derive from packager capacity expansion announcements, pharmaceutical manufacturing investment pipelines, and therapy area growth trajectories across cardiovascular, diabetes, oncology, and neurology applications.
Practitioners should monitor CDSCO enforcement delay risks, NMPA dual carbon threshold adjustments, and PMDA testing protocol amendments for early signals of forecast revision. Cross-checking against pharmaceutical manufacturing capital expenditure disclosures and packager order backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market