
 Plastic Vials Market | 2026-2036
Plastic Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Vials Market Analytics
Asset-light leasing models for blow-fill-seal equipment is narrowing the capital barrier for mid-size entrants. Gerresheimer AG leverages captive resin compounding to sustain margin control across polypropylene vial lines. DWK Life Sciences anchors European laboratory demand through specialized borosilicate-alternative portfolios. Berry Global competes on thermoforming scale, extending its position in high-volume saline vial contracts with hospital networks.
Plastic vials are injection- or blow-molded containers typically manufactured from polypropylene, polyethylene, or cyclic olefin polymers, designed for sterile liquid storage, sample containment, or unit-dose dispensing with dimensional tolerances often held to ±0.1 mm. Screw cap vials dominate pharmaceutical distribution due to established capping-line compatibility and lower per-unit tooling costs, while dropper vials capture faster expansion in ophthalmic and pediatric segments where dosing precision commands premium positioning. PET vials occupy the fastest-growing material tier as barrier-enhanced grades displace glass in parenteral applications where breakage risk and weight drive conversion.
FDA enforces container closure integrity standards under 21 CFR 211.94, compelling migration toward validated leak-proof designs and tamper-evident feature integration. EMA's Annex 1 revision on sterile manufacturing and USP Chapter 661.1 plastic packaging system qualification collectively elevate testing burdens, favoring suppliers with in-house extractables-leachables laboratories. Stakeholders must monitor evolving pharmacopeial harmonization between FDA and EMA to anticipate which material certifications will become table stakes for multi-region tender participation.
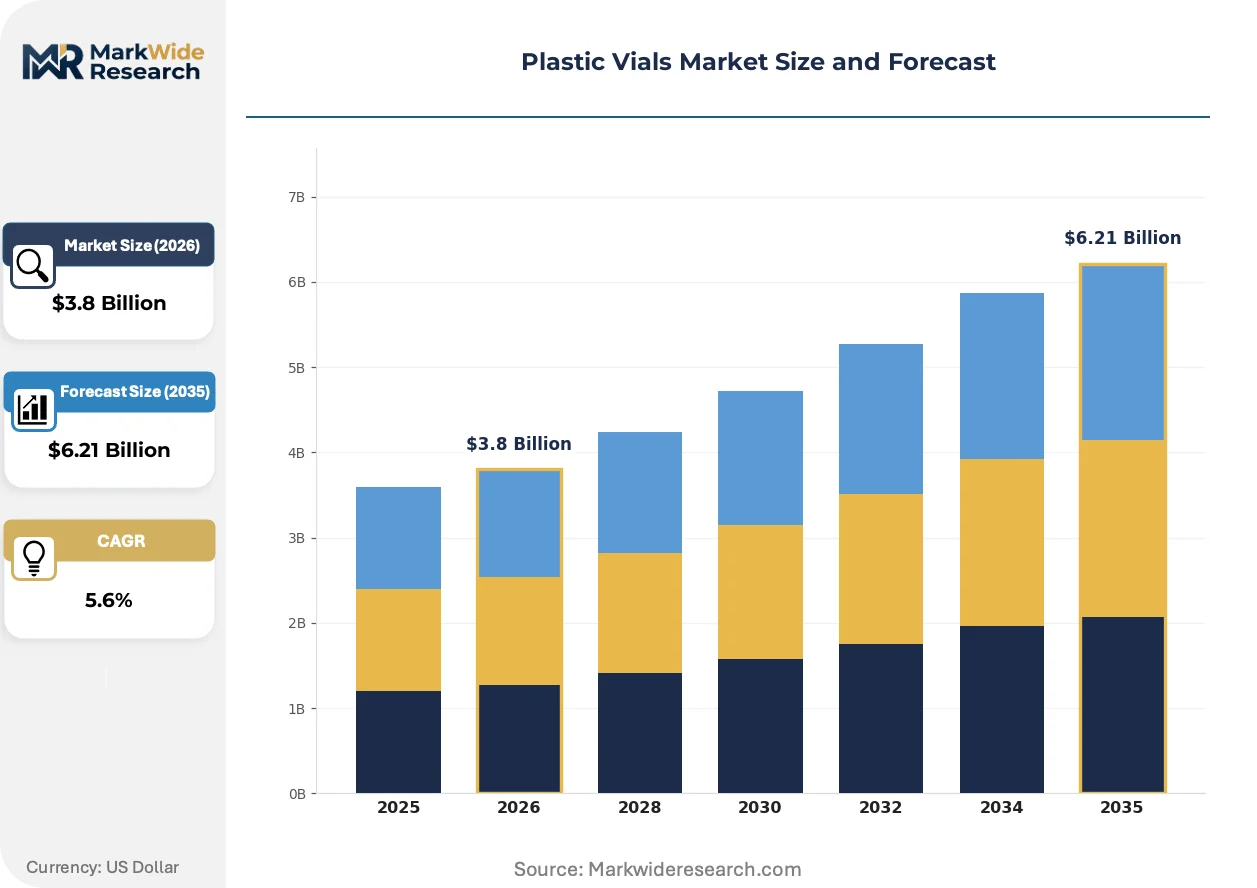
Market Dynamics
Biologics packaging migration from glass to plastic is compressing validation timelines while elevating material certification burdens, forcing suppliers to integrate extractables-leachables testing capabilities directly into production workflows.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revision:The updated guidance accelerates adoption of pre-sterilized single-use containers across European parenteral drug production, eliminating terminal sterilization steps.
- Ophthalmic unit-dose dispensing:Preservative-free eye care formulations drive demand for precision dropper vials with controlled droplet geometry.
- Cyclic olefin polymer barrier enhancement:Improved oxygen and moisture resistance enables plastic vial penetration into lyophilized biologic storage previously reserved for glass.
Market Restraints
- Propylene feedstock volatility:Polypropylene resin costs fluctuate with crude oil and naphtha pricing, compressing margins for converters without captive compounding.
- German production cluster concentration:Specialized pharmaceutical-grade vial manufacturing concentrates in the Rhine-Ruhr corridor, creating geographic supply risk.
- Glass-to-plastic regulatory friction:USP Chapter 661.1 plastic packaging qualification requirements impose lengthy extractables studies that delay product launches versus established glass dossiers.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's streamlined biosimilar approval pathways attract multinational fill-finish investments requiring regional plastic vial supply.
- Cell and gene therapy cold-chain packaging:Cryogenic-compatible polymer formulations address -80°C storage requirements for mRNA and CAR-T therapies.
- Direct-to-pharmacy distribution:Hospital network consolidation creates demand for serialized unit-of-use packaging that bypasses traditional wholesale repackaging.
Industry Challenges
- Extractables-leachables analytical capacity:Qualified chromatography and mass spectrometry expertise scarcity extends validation timelines for new polymer grades.
- Blow-fill-seal equipment qualification:FDA 21 CFR 211.72 automated manufacturing system validation demands specialized engineering resources that mid-size entrants struggle to secure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Vials Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Vials, Screw Cap Vials, Saline Vials, Sample Vials End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Hospitals Material: Polypropylene, Polyethylene, Polystyrene, PET Feature: Child-Resistant, Tamper-Evident, Leak-Proof, Reusable |
| Companies Covered | Gerresheimer AG, DWK Life Sciences, Amcor Plc, Berry Global Inc., AptarGroup, Inc., Nipro Corporation, Origin Pharma Packaging, SGD Pharma, West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Vials Market Evolving Landscape
Digital thread integration across quality management and production execution is compressing batch release cycles while enabling real-time container closure integrity verification throughout the supply chain.
Barrier-enhanced polyethylene terephthalate is virtualizing glass functionality in parenteral applications through advanced acetylene plasma coating and multilayer co-injection processes. Specialty pharmaceutical manufacturers in Switzerland and Singapore are qualifying these grades for protein-based injectables. The technology is virtualizing traditional glass breakage risk mitigation while enabling weight reduction in cold-chain logistics.
REACH polymer registration requirements are mandating comprehensive substance identity documentation for cyclic olefin copolymers used in European pharmaceutical packaging. Suppliers must now disclose full monomer composition and additive packages to ECHA, elevating formulation transparency burdens. Small-volume parenteral producers in Germany and France are consolidating supplier bases to reduce registration compliance fragmentation.
Hospital network procurement consolidation is compressing vendor qualification cycles while elevating total cost-of-ownership analytics over unit pricing. Integrated delivery networks in the United States now mandate five-year supply agreements with embedded volume flexibility clauses. This behavioral shift concentrates contract awards among converters with multi-site manufacturing redundancy and captive resin supply.
Plastic Vials Market Segmentation
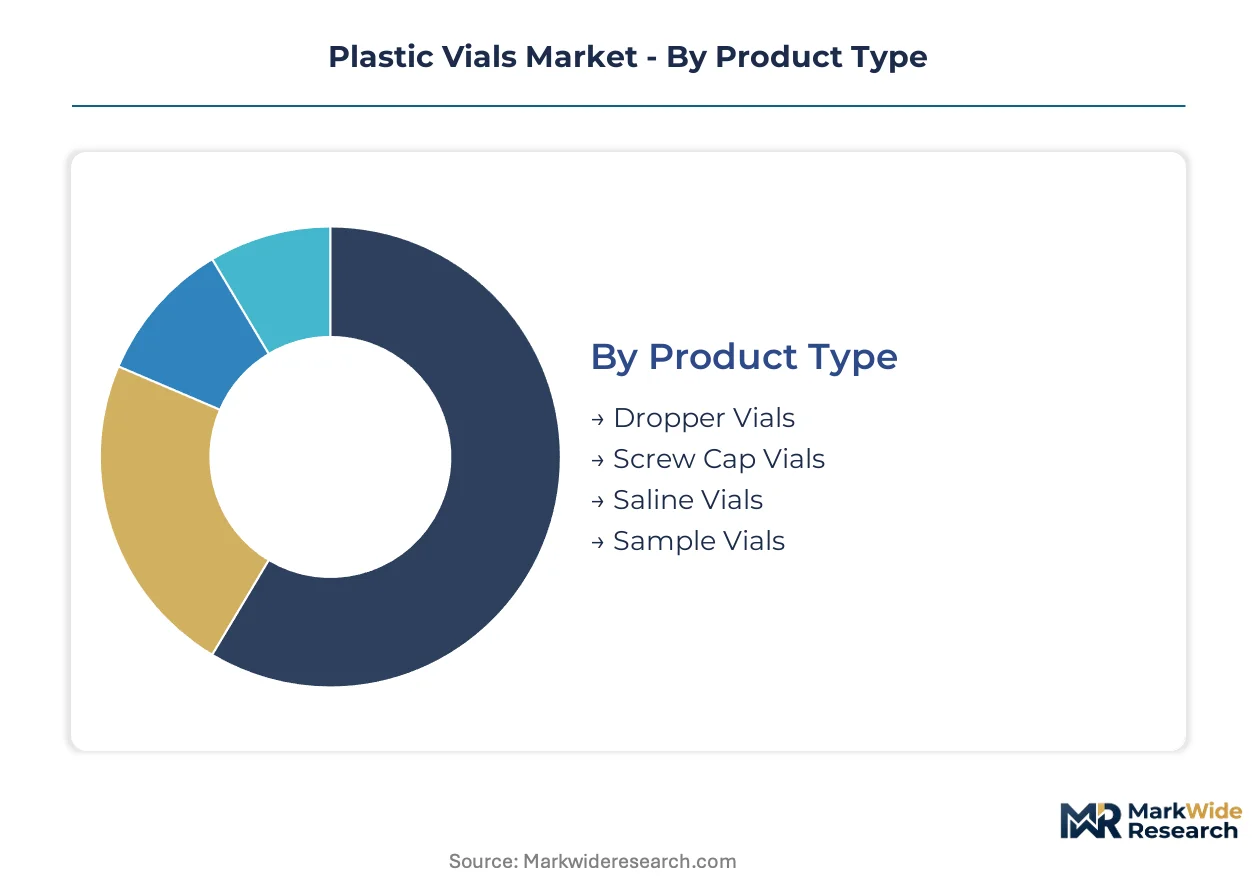
Segmentation in plastic vials reveals divergent technical requirements across pharmaceutical packaging workflows. Each dimension—product form, end-use environment, material specification, and safety feature—carries distinct regulatory validation burdens and aftermarket service intensity.
Product Type:
After-sales service intensity varies sharply across vial formats, with precision-dispensing designs demanding ongoing technical calibration support while commodity formats rely on volume replenishment contracts.
- Screw Cap Vials:Threaded closure systems manufactured from polypropylene or polyethylene with standardized neck finishes compatible with automated capping equipment. Pharmaceutical distribution networks in Germany and the United States concentrate procurement for oral solid dose packaging, driven by established capping-line infrastructure and lower per-unit tooling amortization.
- Dropper Vials:Integrated bulb-and-tip assemblies requiring controlled droplet geometry within ±10% volume variance for ophthalmic and pediatric applications. Swiss and Singaporean specialty pharmaceutical manufacturers are qualifying these formats for preservative-free formulations, where dosing precision commands premium positioning and dedicated field service support.
- Saline Vials:Sterile, single-use containers for irrigation and dilution solutions, typically blow-fill-seal manufactured.
- Sample Vials:Small-volume containers for diagnostic specimen collection and laboratory storage.
By volume, Screw Cap Vials leads. By growth pace, Dropper Vials is ahead.
End User:
Cost tier stratification separates capital-intensive biologics manufacturers from price-sensitive hospital procurement offices, with biotechnology firms occupying the premium service tier.
- Pharmaceutical Companies:Large-scale drug manufacturers requiring validated container closure integrity for commercial distribution. North American and European parenteral producers are migrating from glass to cyclic olefin polymer vials for protein-based injectables, compressing validation timelines while elevating extractables-leachables testing requirements.
- Biotechnology Firms:Cell and gene therapy developers with cryogenic storage requirements down to -80°C for mRNA and CAR-T products. CDSCO's streamlined biosimilar pathways in India are attracting fill-finish investments that demand regional plastic vial supply with cold-chain compatibility documentation.
- Research Laboratories:Academic and commercial R&D facilities with diverse small-batch requirements.
- Hospitals:Consolidated health systems pursuing direct-to-pharmacy distribution models that bypass wholesale repackaging.
Pharmaceutical Companies dominate current procurement volume. Biotechnology Firms exhibit the steepest expansion trajectory as advanced therapy pipelines mature.
Material:
Application-specific barrier requirements dictate material selection, with parenteral biologics demanding oxygen and moisture resistance that commodity polymers cannot deliver.
- PET:Barrier-enhanced polyethylene terephthalate grades with acetylene plasma coating or multilayer co-injection achieving glass-equivalent protection. Swiss specialty manufacturers are qualifying these for protein-based injectables, virtualizing breakage risk while reducing cold-chain logistics weight.
- Polypropylene:Workhorse polymer for oral solid dose and general liquid packaging with broad chemical compatibility. Rhine-Ruhr corridor converters leverage captive resin compounding to sustain margin control despite propylene feedstock volatility tied to crude oil and naphtha pricing.
- Polyethylene:Lower-cost option for non-critical applications with limited barrier requirements.
- Polystyrene:Transparent, rigid material for diagnostic and laboratory applications where clarity outweighs barrier performance.
PET is gaining share fastest in parenteral segments. Polypropylene retains the largest installed base across oral and topical applications.
Feature:
Regulatory mandates rather than customer preference now drive feature adoption, with FDA serialization and EU MDR compliance reshaping baseline specifications.
- Tamper-Evident:Mechanical or adhesive indicators of prior opening required for over-the-counter and hospital-distributed pharmaceuticals. EMA Annex 1 sterile manufacturing revisions are accelerating adoption of pre-sterilized single-use containers with integrated tamper-evident features across European parenteral production.
- Child-Resistant:Push-and-turn or squeeze-and-turn closures meeting ISO 8317 and 16 CFR 1700 protocols. Pediatric formulation specialists in Germany and France are consolidating supplier bases to reduce REACH polymer registration compliance fragmentation for cyclic olefin copolymers.
- Leak-Proof:Validated container closure integrity under 21 CFR 211.94 for sterile liquid storage.
- Reusable:Durable designs for laboratory and industrial process applications with cleaning validation protocols.
Tamper-Evident features lead in regulatory-driven retrofit volume. Child-Resistant designs are climbing the fastest as pediatric and geriatric safety protocols tighten across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pharmaceutical-grade plastic vials tilt toward production surplus in Germany and the United States against rising import dependency in India and Southeast Asian manufacturing hubs. This trade geometry concentrates advanced polymer conversion capacity in established regulatory jurisdictions while emerging fill-finish markets absorb unit volumes.
United States
FDA serialization mandates under the Drug Supply Chain Security Act drive contract packaging demand for tamper-evident unit-dose formats. 21 CFR 211.94 container closure integrity standards compel migration toward validated leak-proof designs. New Jersey and North Carolina host concentrated blow-fill-seal manufacturing corridors serving hospital network procurement consolidation.
Germany
Rhine-Ruhr corridor converters anchor European pharmaceutical-grade vial supply through captive resin compounding capabilities. EMA Annex 1 sterile manufacturing revisions accelerate adoption of pre-sterilized single-use containers eliminating terminal sterilization. Gerresheimer AG and DWK Life Sciences maintain specialized production clusters in the region.
India
CDSCO streamlined biosimilar approval pathways attract multinational fill-finish investments requiring regional plastic vial supply. BIS polymer certification standards for pharmaceutical packaging elevate material qualification burdens for imported resins. Maharashtra and Gujarat host emerging converter capacity serving biologics manufacturing expansion.
Switzerland
Swissmedic oversight of protein-based injectables drives qualification of barrier-enhanced PET grades displacing glass in parenteral applications. Basel and Zurich specialty pharmaceutical manufacturers command premium positioning for precision dropper vials in preservative-free formulations. REACH polymer registration requirements mandate comprehensive substance identity documentation for cyclic olefin copolymers.
Singapore
Biologics manufacturing investments by global pharmaceutical firms generate demand for cryogenic-compatible polymer formulations addressing cold-chain requirements. Singapore's national pharmaceutical regulator aligns with ICH guidelines for container closure integrity testing. Tuas Biomedical Park anchors regional fill-finish capacity requiring localized vial supply.
Plastic Vials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and precision molding. The vendor base stratifies across three tiers: multinational converters with captive compounding, regional specialists in sterile barrier technologies, and contract manufacturers serving hospital network procurement. Two dominant competitive moves are reshaping positioning: backward integration into polymer formulation to offset propylene feedstock volatility, and multi-site manufacturing redundancy to satisfy five-year supply agreements with embedded volume flexibility clauses.
Within the multinational converter tier, Gerresheimer AG and DWK Life Sciences exemplify European-based platform players with integrated quality systems. Berry Global Inc. occupies a position among North American scale-driven thermoforming specialists. These three entities represent divergent strategic archetypes: German precision manufacturing with regulatory dossier depth, laboratory-to-pharmaceutical portfolio breadth, and high-volume saline vial contracting with hospital networks respectively.
| Leading Market Players |
|---|
| Gerresheimer AG |
| DWK Life Sciences |
| Amcor Plc |
| Berry Global Inc. |
| AptarGroup, Inc. |
| Nipro Corporation |
| Origin Pharma Packaging |
| SGD Pharma |
| West Pharmaceutical Services, Inc. |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr corridor freight networks carry resin shipments from Rotterdam petrochemical hubs to German vial converters, with logistics cost differentials feeding directly into pricing power for captive-compounding specialists and downstream price stratification between pharmaceutical-grade and laboratory-tier buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on extractables-leachables certification depth and volume scale commitments. Price differentiation rests on FDA 21 CFR 211.94 compliance tier and geographic delivery cost to hospital network consolidation zones. Cost compression in standard-grade polypropylene vials is intensifying because propylene feedstock volatility squeezes converters without captive resin supply. Hospital procurement offices exhibit highest price sensitivity, while biotechnology firms developing cryogenic-compatible formulations demonstrate lowest sensitivity due to performance-critical material specifications.
Supply Chain Analysis
Propylene monomer and cyclic olefin polymer feedstocks draw from German, Belgian, and Dutch petrochemical complexes, with naphtha cracking capacity tethered to Brent crude pricing dynamics. Raw material dependencies center on polypropylene resin grades, high-purity cyclic olefin copolymers, and barrier-enhanced PET formulations. Single-source vulnerability concentrates in Rhine-Ruhr corridor specialized pharmaceutical-grade vial manufacturing. Distribution runs through direct-to-pharmacy channels serving consolidated hospital networks and regional fill-finish contractors supplying CDSCO-regulated Indian biologics facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic vials market functions as a regulatory-moat arena where EMA Annex 1 compliance and FDA container closure integrity dossiers create switching costs that entrench incumbent positions against commodity converter encroachment.
For Market Incumbents: Entrench through backward integration into polymer formulation to offset propylene feedstock volatility, and expand multi-site manufacturing redundancy across Germany, Switzerland, and Singapore to satisfy five-year supply agreements with embedded volume flexibility clauses. Threats from barrier-enhanced PET glass-displacement technologies demand accelerated extractables-leachables laboratory investment to maintain regulatory dossier depth.
For New Entrants and Emerging Players: Build out cryogenic-compatible polymer formulation capabilities targeting cell and gene therapy cold-chain packaging, the most penetrable segment as mRNA and CAR-T pipelines mature. CDSCO-streamlined Indian biosimilar approvals create regional white-space for converters with BIS polymer certification capabilities. Go-to-market leverage rests on partnering with multinational fill-finish investments seeking localized vial supply.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging conglomerates with underutilized pharmaceutical-grade cleanroom assets and dormant FDA master file registrations. Long-term viability centers on regulatory entrenchment durability rather than volume scale alone. Watch for EMA-FDA pharmacopeial harmonization announcements as inflection signals for multi-region tender participation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Investment | Gerresheimer-style margin control insulates against propylene feedstock volatility from Rotterdam naphtha markets. |
| Extractables-Leachables Laboratory Buildout | In-house analytical capacity compresses USP Chapter 661.1 validation timelines for cyclic olefin polymer grades. |
| Cryogenic Polymer Formulation Development | Cold-chain compatibility documentation unlocks cell and gene therapy packaging for mRNA and CAR-T therapies. |
| Multi-Site Manufacturing Redundancy | Geographic dispersion satisfies hospital network procurement consolidation demands for supply security. |
| Direct-to-Pharmacy Distribution Partnerships | Bypassing wholesale repackaging captures value from serialized unit-of-use packaging mandates under DSCSA. |
Research Methodology
Desk research of FDA 21 CFR filings, EMA Annex 1 guidance documents, and USP Chapter 661.1 pharmacopeial standards preceded structured interviews with pharmaceutical packaging procurement directors, biologics manufacturing executives, regulatory affairs specialists, and hospital supply chain managers. Secondary validation drew from customs trade data, SEC 10-K resin cost disclosures, and CDSCO biosimilar approval tracking. Bottom-up volume modeling across product type, material specification, end-user segment, and geographic regulatory cluster triangulated against top-down macro pharmaceutical production indicators.
Assumptions held fixed include EMA Annex 1 sterile manufacturing revision implementation timelines and FDA serialization mandate enforcement intensity, while propylene feedstock pricing and CDSCO approval pathway efficiency were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product form, material barrier tier, end-user compliance requirements, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-level volume trajectories, incorporating biologics pipeline maturation rates and glass-to-plastic conversion velocity in parenteral applications.
Practitioners should monitor REACH polymer registration requirement expansions and pharmacopeial harmonization negotiations for early signals of compliance burden shifts. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock pricing stability. Cross-checking against EIA petrochemical production data and IEA energy transition scenarios is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Global Plastic Bottle Recycling Market