
 Plastic Furniture Market | 2026-2036
Plastic Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Furniture Market Intelligence
Vietnamese resin compounders and molders is rebalancing regional supply chains as energy costs shift production economics. Keter Group leverages vertical integration across resin sourcing and retail distribution to sustain margin control. Nilkamal Limited anchors South Asian mass-market penetration through extensive dealer networks. Grosfillex SAS specializes in weather-resistant formulations for European hospitality channels.
Plastic furniture comprises molded or extruded polymer structures engineered for load-bearing and ergonomic functions, typically manufactured through injection molding, rotational molding, or blow-molding processes using thermoplastic resins rated for UV stability and impact resistance. Chairs and tables dominate volume production, while cabinets and shelves capture higher margin pools in commercial and residential storage applications. Polypropylene leads material consumption due to its fatigue resistance and recyclability, though polycarbonate gains traction in premium transparent designs where aesthetic differentiation commands pricing power.
EPA regulations on volatile organic compound emissions constrain coating and finishing operations for US-based manufacturers, while REACH compliance in Europe mandates disclosure of Substances of Very High Concern in polymer additives. India's BIS certification requirements for furniture safety create formal market access barriers that favor organized producers over unorganized competitors. Stakeholders must monitor evolving extended producer responsibility frameworks as jurisdictions shift disposal accountability upstream to manufacturers.
Market Dynamics
EU REACH Substances of Very High Concern disclosure mandates are forcing resin compounders to reformulate polymer additives, compressing margins for commodity-grade producers while creating compliance premiums for certified suppliers across European distribution channels.
Growth Catalysts
- Hospitality outdoor seating mandates:Restaurant chains and event organizers in warm-climate zones specify UV-stabilized polypropylene for terrace and patio installations, driving volume procurement of weather-resistant molded chairs and tables.
- REACH chemical safety compliance:European manufacturers investing in additive transparency and substitution documentation capture preferential placement in EU public procurement frameworks for institutional furniture.
- Rotational molding process refinement:Thickness control automation in rotational molding is reducing material waste rates and enabling complex hollow forms for premium storage furniture lines.
Market Restraints
- Crude oil derivative volatility:Polypropylene and polycarbonate resin prices track naphtha and propylene feedstock costs, exposing molders to margin compression during upstream petrochemical price spikes.
- Recycling infrastructure gaps:Mixed-polymer furniture waste streams lack dedicated collection and reprocessing capacity in most municipal systems, limiting closed-loop material claims and circular economy positioning.
- Wood and metal substitution:Solid wood outdoor furniture and powder-coated aluminum alternatives retain preference in premium residential segments where tactile warmth and perceived durability outweigh plastic cost advantages.
Strategic Opportunities
- Indian BIS certification pathways:Organized domestic producers leveraging Bureau of Indian Standards safety certification capture market share from unorganized competitors as formal retail channels expand in tier-2 and tier-3 cities.
- Extended producer responsibility frameworks:Jurisdictions shifting disposal accountability upstream to manufacturers create first-mover advantages for molders investing in take-back logistics and chemical recycling partnerships.
- 3D printing convergence with generative design:Fused deposition modeling of recycled polymer feedstock combined with topology optimization software enables mass-customized furniture components for contract interior projects.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for UV stabilizers, flame retardants, and impact modifiers concentrates among senior specialists at legacy resin suppliers, constraining rapid product development cycles at mid-size molders.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EPA VOC compliance for US coating operations, REACH SVHC documentation for EU markets, and BIS safety marks for India extends product launch schedules and freezes working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Furniture Market |
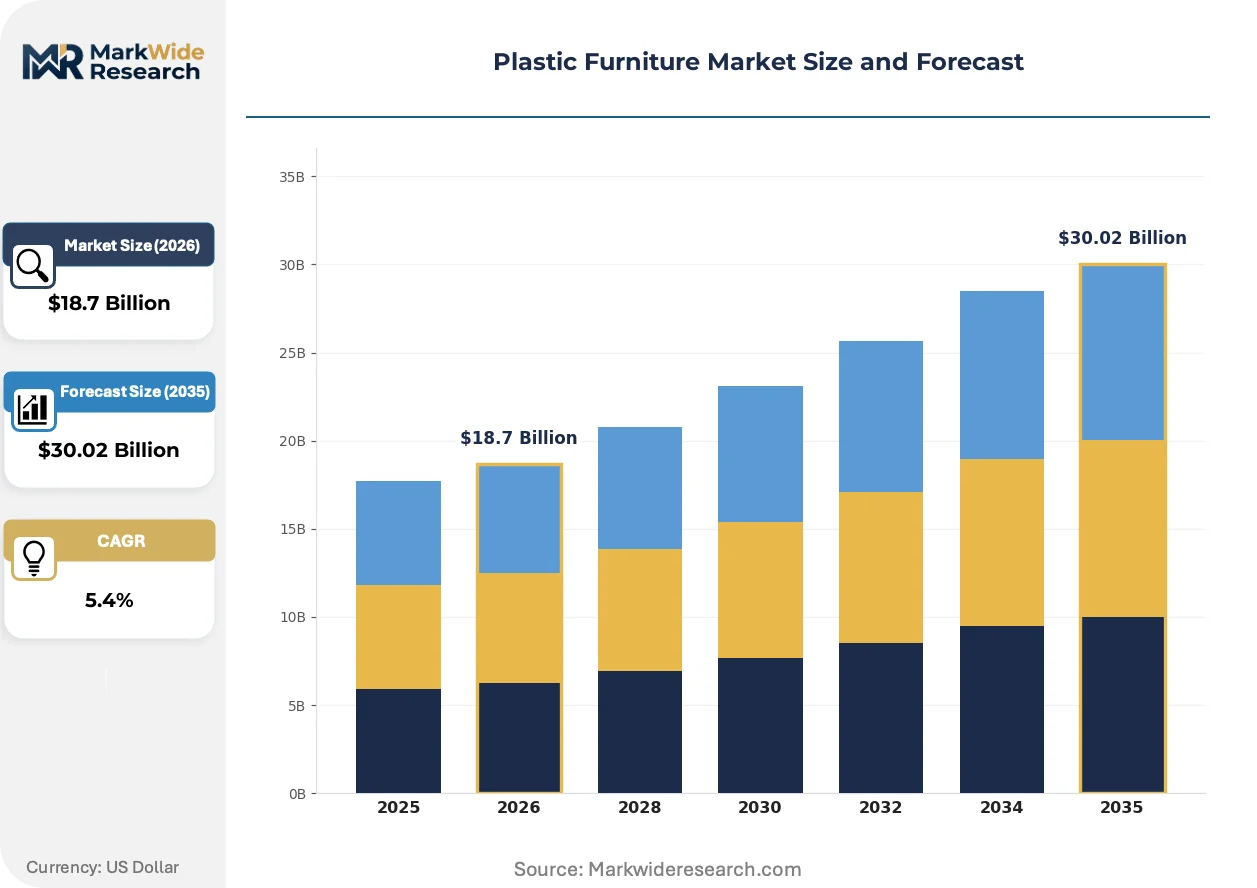
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Cabinets, Stools, Shelves Material Type: Polypropylene, Polycarbonate, Polyethylene, PVC, Polystyrene Application: Residential, Commercial Spaces, Educational Institutions, Hospitality, Outdoor Seating End User: Homeowners, Office Facilities, Schools, Restaurants, Event Organizers |
| Companies Covered | Ashley Furniture Industries Inc., Tramontina, Keter Group, ScanCom International A/S, Grosfillex SAS, Nilkamal Limited, Inter IKEA Systems B.V., Harwal Group, Supreme Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Furniture Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure requirements are converging to reshape competitive positioning around chemical transparency, process efficiency, and circular design protocols rather than pure unit economics.
Post-industrial recycled polypropylene flake is modularizing supply chain architecture for injection molders serving commercial seating markets. Food-grade rPP sourcing from post-consumer packaging waste streams is scaling through mechanical recycling investments in Germany and the Netherlands. Tier-1 contract furniture buyers now specify minimum recycled content thresholds in RFP documentation, compressing virgin resin premiums and rewarding backward-integrated compounders with captive reprocessing capacity.
EPA volatile organic compound emission limits on coating and finishing operations are constraining solvent-based decorative treatments for US-based manufacturers. Waterborne and powder coating alternatives require capital-intensive line conversions and extended cure cycle times. Outdoor furniture segments targeting the North American residential market are absorbing compliance costs through supplier consolidation toward vertically integrated finishers with in-house pollution control infrastructure.
Direct-to-hospitality procurement models are displacing traditional distributor intermediaries in European contract seating markets. Hotel chains and restaurant groups are consolidating specification authority at central procurement functions, demanding lot-traceable resin documentation and batch-level quality certificates previously handled by regional wholesalers. This concentration is most visible in Mediterranean resort markets where Spanish and Portuguese hospitality operators negotiate frame-plus-upholstery packages directly with molders in Valencia and Porto manufacturing clusters.
Plastic Furniture Market Segmentation
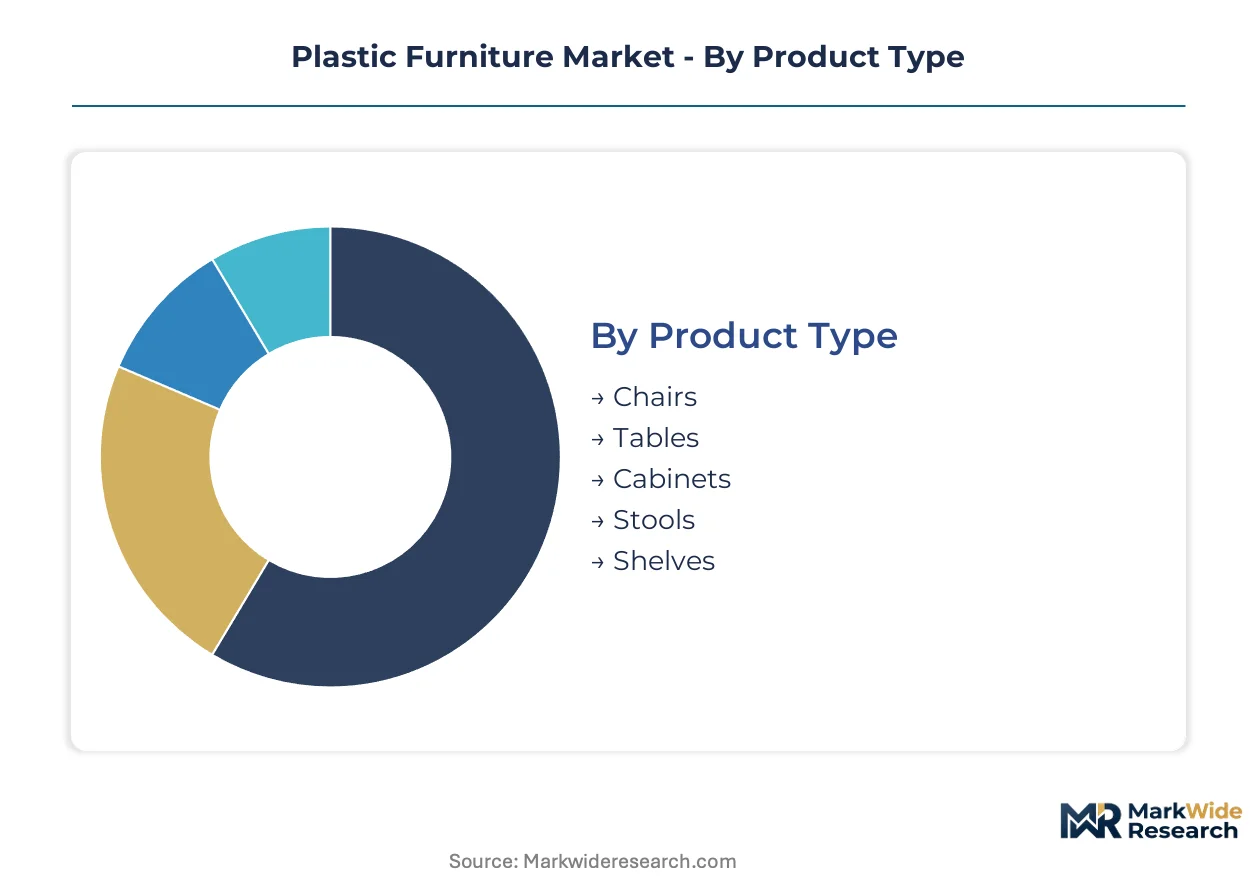
Segmentation in plastic furniture reveals divergent upgrade cycles across residential replacement purchases and commercial refresh mandates. Procurement patterns split between cost-driven mass-market turnover and specification-heavy contract installations requiring extended durability warranties.
Product Type:
Replacement frequency varies sharply across product categories, with outdoor seating facing accelerated refresh schedules due to UV degradation exposure.
- Chairs:Injection-molded polypropylene shells with metal or polymer legs constitute the highest-volume production category. Restaurant chains in warm-climate zones specify UV-stabilized terrace seating with 3-5 year replacement cycles, compressing procurement intervals versus residential dining chairs.
- Tables:Rotational-molded and blow-molded tabletops with integrated or detachable bases serve hospitality and residential markets. Event organizers in India drive demand for stackable banquet tables with standardized heights for mixed-brand compatibility.
- Cabinets:Polypropylene storage units with modular drawer systems target garage and utility room applications.
- Stools:Counter-height and bar-height seating for foodservice and residential kitchen islands.
- Shelves:Wall-mounted and freestanding storage systems for retail backroom and residential closet applications.
Volume placements concentrate in Chairs; the faster expansion belongs to Tables.
Material Type:
Cost tier stratification separates commodity resin formulations from premium transparent and high-impact grades.
- Polypropylene:Fatigue-resistant homopolymer and copolymer grades dominate injection-molded seating production due to recyclability and weld-line strength. REACH-compliant additive packages from German compounders command sourcing premiums for EU-bound exports.
- Polycarbonate:Optical-grade transparent formulations enable aesthetic differentiation in premium residential and hospitality segments. Bisphenol-A-free alternatives are gaining specification share in childcare and food-contact applications.
- Polyethylene:Rotational-molding grades for hollow outdoor furniture with lower stiffness requirements.
- PVC:Rigid and plasticized formulations for cost-sensitive utility furniture with limited outdoor exposure.
- Polystyrene:Crystal and high-impact grades for temporary event seating and low-cycle storage applications.
Polypropylene captures the dominant volume position; polycarbonate climbs the fastest on premium positioning.
Application:
Customer type differentiation splits between owner-occupied refresh decisions and institutional procurement with centralized specification authority.
- Residential:Patio, dining, and storage furniture purchased through retail channels with 7-10 year replacement cycles. Indian tier-2 and tier-3 city expansion is concentrating demand growth through organized retail penetration.
- Commercial Spaces:Office breakout areas and co-working lounges specifying contract-grade durability with 5-year warranty minimums.
- Educational Institutions:Stackable seating and activity tables for K-12 and higher education facilities.
- Hospitality:Hotel guest rooms, lobbies, and food-and-beverage outlets with brand-standard color matching requirements.
- Outdoor Seating:Terrace, poolside, and event venue installations with accelerated weathering exposure.
Residential maintains the volume anchor; hospitality shows the steepest expansion trajectory.
End User:
Procurement consolidation patterns separate fragmented homeowner decisions from centralized contract negotiations.
- Homeowners:Individual purchase decisions through e-commerce and big-box retail with price sensitivity and style-driven selection. Indian consumers increasingly favor BIS-certified products as safety awareness penetrates mass-market channels.
- Office Facilities:Corporate real estate and facilities management teams with sustainability scorecard requirements.
- Schools:District-level procurement with durability specifications and vandal-resistance priorities.
- Restaurants:Chain-level central procurement with direct molder relationships displacing distributor intermediaries.
- Event Organizers:Rental and purchase decisions for temporary seating with rapid deployment and retrieval requirements.
Homeowners drive absolute volume; restaurants are expanding most quickly through direct procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability along the US Gulf Coast anchors North American resin supply chains for injection molders serving hospitality and residential channels. European REACH compliance costs and Indian BIS certification expansion are redrawing competitive boundaries across manufacturing footprints.
United States
Restaurant chain procurement of UV-stabilized terrace seating drives demand through direct molder relationships in the Southeast. EPA volatile organic compound emission limits constrain solvent-based finishing operations for domestic manufacturers. Injection molding clusters in North Carolina and Texas concentrate production for hospitality and mass-market retail channels.
Germany
REACH Substances of Very High Concern disclosure mandates force resin compounders to reformulate polymer additives for EU-bound furniture exports. ECHA compliance documentation creates sourcing premiums for certified suppliers in public procurement frameworks. Mechanical recycling investments in the Rhine-Ruhr region scale food-grade recycled polypropylene flake for commercial seating applications.
India
Tier-2 and tier-3 city retail expansion concentrates demand growth for BIS-certified safety furniture as organized channels displace unorganized competitors. Bureau of Indian Standards certification requirements create formal market access barriers favoring domestic producers with testing infrastructure. Nilkamal Limited and Supreme Industries Limited anchor production networks in Maharashtra and Gujarat serving mass-market penetration.
Vietnam
Energy cost shifts are rebalancing regional supply chains as resin compounders and molders expand rotational molding capacity for export-oriented outdoor furniture. The country's national industrial standards regulator enforces furniture safety protocols that align with export market requirements. Manufacturing clusters near Ho Chi Minh City serve hospitality procurement consolidation across Mediterranean resort markets.
Spain
Hotel chains and restaurant groups in Mediterranean resort markets negotiate frame-plus-upholstery packages directly with molders, displacing traditional distributor intermediaries. EU Green Deal circular economy directives pressure manufacturers toward extended producer responsibility frameworks. Valencia manufacturing clusters specialize in weather-resistant formulations for European hospitality channels with lot-traceable resin documentation.
Plastic Furniture Market Key Industry Players
Global majors compete with regional champions across resin sourcing, certification documentation, and distribution reach. The vendor base spans vertically integrated resin compounders, specialized hospitality molders, and mass-market fabricators with extensive dealer networks. Three archetypes dominate: backward-integrated compounders with captive reprocessing capacity, hospitality specialists with direct procurement relationships, and organized domestic producers leveraging safety certification barriers. Competitive moves concentrate on strategic partnerships for chemical recycling feedstock and geographic expansion through tier-2 city dealer penetration.
Among the named players, Keter Group exemplifies vertical control across resin sourcing and retail distribution. Nilkamal Limited and Supreme Industries Limited occupy positions as organized domestic champions in South Asian mass-market channels. Grosfillex SAS represents the hospitality-specialist archetype with European weather-resistant formulation expertise.
| Leading Market Players |
|---|
| Ashley Furniture Industries Inc. |
| Tramontina |
| Keter Group |
| ScanCom International A/S |
| Grosfillex SAS |
| Nilkamal Limited |
| Inter IKEA Systems B.V. |
| Harwal Group |
| Supreme Industries Limited |
| Others |
Cost & Logistics Intelligence
Rotational molding automation is compressing per-unit labor costs while concentrating production among molders with capital access, simultaneously reshaping cost economics and supplier consolidation dynamics across European and Indian manufacturing clusters.
Pricing Analysis
Warranty bundling separates contract-grade hospitality seating with 5-year replacement guarantees from unbundled residential retail purchases. Pricing stratifies across premium polycarbonate transparent designs, REACH-certified polypropylene formulations, and commodity-grade recycled resin tiers. Price differentiation hinges on certification documentation depth and volume procurement scale. Cost compression in mass-market injection-molded chairs is intensifying because Indian organized retailers are absorbing BIS compliance overhead to displace unorganized competitors.
Supply Chain Analysis
Domestic-content mandates in India's public procurement frameworks are redirecting resin sourcing toward Maharashtra and Gujarat compounders with BIS-certified additive packages. Propylene feedstock draws from US Gulf Coast petrochemical complexes, German Rhine-Ruhr mechanical recycling facilities, and Vietnamese energy-cost-advantaged molders. Single-source vulnerability concentrates in UV stabilizer and flame retardant additive supply from legacy German compounders. Distribution runs through direct-to-hospitality procurement channels displacing traditional European distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH Substances of Very High Concern disclosure mandates erect barrier-to-entry moats favoring compounders with reformulation documentation infrastructure.
For Market Incumbents: Deploy captive reprocessing capacity investments to secure post-industrial recycled polypropylene flake supply ahead of tier-1 contract furniture RFP thresholds. Consolidate testing infrastructure for simultaneous EPA VOC, REACH SVHC, and BIS safety mark pursuit to compress multi-jurisdiction certification timelines. Wood and metal substitution in premium residential segments threatens margin pools; backward integration into resin compounding defends cost position against commodity-grade competitors. For New Entrants and Emerging Players: Capture tier-2 and tier-3 Indian city dealer network expansion as organized retail penetration accelerates BIS-certified safety furniture demand. White-space concentrates in chemical recycling partnerships for extended producer responsibility framework compliance across EU jurisdictions. Target direct procurement relationships with Mediterranean resort hotel chains seeking frame-plus-upholstery packages with lot-traceable resin documentation. For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated compounders with captive mechanical recycling capacity and hospitality-specialist molders with direct procurement relationships. Long-term viability favors suppliers with documented additive transparency and substitution pathways as REACH disclosure mandates expand. Watch for inflection in extended producer responsibility framework adoption rates across EU member states as signal for circular economy positioning value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene flake supply secures margin control against naphtha price volatility. |
| REACH Compliance Documentation Investment | ECHA-certified additive packages unlock EU public procurement preferential placement. |
| Chemical Recycling Partnership Formation | Extended producer responsibility frameworks shift disposal accountability upstream to manufacturers. |
| Tier-2 City Dealer Network Expansion | Nilkamal and Supreme Industries demonstrate BIS-certified mass-market penetration pathways. |
| Direct-to-Hospitality Procurement Model | Valencia and Porto manufacturing clusters displace distributor intermediaries in Mediterranean resort markets. |
Research Approach
Trade customs databases, Bureau of Indian Standards certification registries, and ECHA SVHC disclosure filings formed the secondary backbone, cross-referenced with primary interviews involving resin compounder technical directors, hospitality procurement managers, rotational molding plant engineers, and organized retail category buyers. Bottom-up production capacity modeling across Indian, Vietnamese, and Spanish manufacturing clusters combined with top-down demand estimation from restaurant chain refresh cycles and hotel construction pipelines.
Historical trendline analysis of polypropylene and polycarbonate resin price volatility against naphtha feedstock movements anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type, material grade tier, application, and end-user procurement consolidation pattern. CAGRs derived from weighted average of replacement cycle frequencies, regulatory compliance cost trajectories, and geographic demand concentration shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil derivative volatility, REACH additive reformulation timelines, and Indian organized retail penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Massive Wood Slabs Market
Furniture
Japan Home Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Upholstered Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
UAE Luxury Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Italy Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Metal Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
Furniture and Home Furnishing Store Market